
 Trace Minerals Chelated Feed Market | 2026-2036
Trace Minerals Chelated Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Trace Minerals Chelated Feed Market Analytics
Midwestern U.S. premix manufacturing is consolidating as larger compounders absorb regional blending operations to secure amino acid chelate supply chains. Cargill, Incorporated leverages its captive grain origination network to backward-integrate into trace mineral premix distribution. Zinpro Corporation sustains technology leadership through proprietary metal-amino acid complex patents that set absorption benchmarks. BASF SE anchors European supply with multi-site production of glycinate-based chelates serving regulated feed markets.
Trace minerals chelated feed refers to essential micronutrients—copper, zinc, iron, manganese—bound to organic ligands such as amino acids or hydroxy analogues at defined stability constants, typically manufactured through controlled pH precipitation or spray-drying to achieve protected bioavailability in the gastrointestinal tract of monogastric and ruminant animals. Zinc chelates dominate value pools due to their critical role in immune modulation and hoof integrity protocols across dairy herds, while copper chelates represent the fastest-expanding category as swine producers phase out high-dose inorganic copper to comply with environmental accumulation limits. Powder formulations retain volume leadership in bulk feed mill integration, though liquid chelate suspensions are gaining share in automated dosing systems for aquaculture and intensive poultry operations.
The U.S. Food and Drug Administration's Veterinary Feed Directive and the European Food Safety Authority's re-evaluation of copper and zinc maximum permitted levels are reshaping formulation standards and import compliance requirements for mineral premix suppliers. China's Ministry of Agriculture and Rural Affairs enforces GB standards on feed-grade trace minerals that restrict inorganic oxide forms in favor of organic complexes, creating divergent product registration pathways for multinational manufacturers. Stakeholders must monitor evolving maximum residue limits for heavy metals in animal-derived food products across major importing jurisdictions to align chelate purity specifications with downstream market access conditions.
Market Dynamics
The European Union's Feed Hygiene Regulation and escalating restrictions on inorganic mineral discharge are accelerating the shift toward organic trace mineral forms, consolidating formulation standards around glycinate and amino acid chelate complexes.
Growth Catalysts
- Environmental discharge limits:The EU's tightening restrictions on copper and zinc accumulation in soil and water are forcing livestock producers to replace inorganic sulfates and oxides with chelated alternatives that exhibit higher bioavailability and lower excretion rates.
- Dairy herd productivity protocols:Large-scale dairy operations across the United States and Brazil are integrating zinc methionine and copper lysine complexes into TMR formulations to reduce somatic cell counts and improve hoof integrity outcomes.
- Automated dosing infrastructure:Liquid chelate suspensions are capturing share in intensive poultry and aquaculture facilities where precision delivery systems enable real-time mineral adjustment based on growth-stage requirements.
Market Restraints
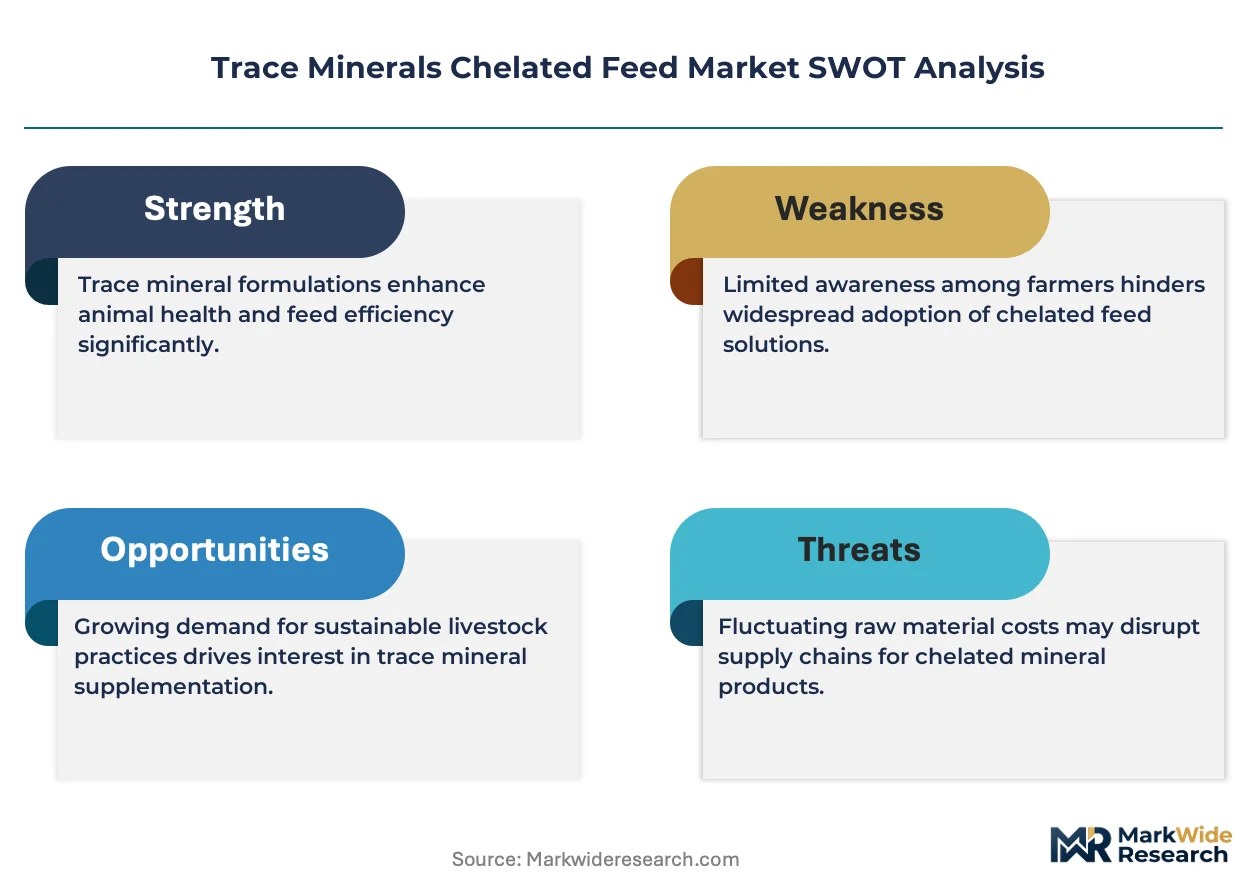
- Input cost volatility:Fluctuations in amino acid feedstock prices, particularly methionine and lysine derived from petrochemical and fermentation processes, compress margin predictability for chelate manufacturers.
- Supply concentration risk:Amino acid ligand production clusters heavily in China and select Southeast Asian facilities, exposing premix formulators to single-source dependency and freight cost spikes.
- Technical substitution pressure:Hydroxy trace minerals and inorganic nanoparticle formulations offer intermediate bioavailability at lower unit economics, threatening chelate penetration in price-sensitive swine and broiler segments.
Strategic Opportunities
- Brazilian integrated livestock expansion:Retrofitting of feed mills in Mato Grosso and Paraná with chelated mineral blending capacity creates first-mover positioning for premix suppliers establishing local technical service infrastructure.
- Regulatory tailwind from GB standards:China's Ministry of Agriculture and Rural Affairs enforcement of organic complex preferences over inorganic oxides opens differentiated product registration pathways for compliant manufacturers.
- Aquaculture mineral nutrition gap:Shrimp and salmonid producers in Norway and Chile are underserved by species-specific chelate formulations, presenting white space for methionine-chelated selenium and iodine complexes targeting immune resilience.
Industry Challenges
- Metal-ligand stability certification:Variability in chelation bond strength testing methodologies across ISO, AOAC, and feed association protocols creates compliance friction and customer skepticism regarding label claims.
- Legacy mill integration complexity:Retrofitting existing feed manufacturing lines designed for inorganic mineral handling with chelate-compatible mixing, storage, and conveying equipment demands capital allocation and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trace Minerals Chelated Feed Market |
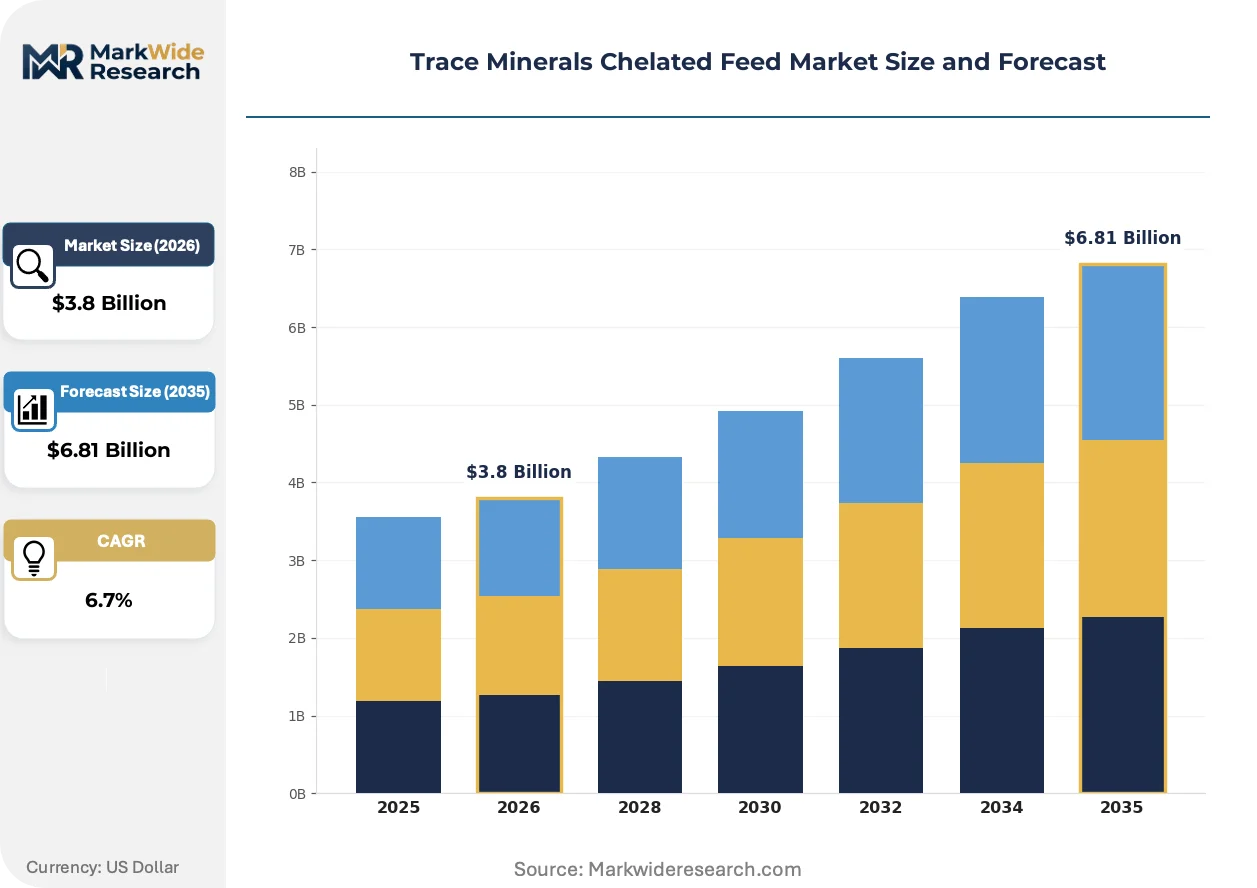
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Chelates, Zinc Chelates, Iron Chelates, Manganese Chelates End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Granules, Liquid, Pellets Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Phibro Animal Health Corporation, Cargill, Incorporated, Zinpro Corporation, BASF SE, DSM Nutritional Products, Alltech, Inc., Kemin Industries, Inc., Archer Daniels Midland Company, Novus International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trace Minerals Chelated Feed Market Evolving Landscape
Spray-dried metal-amino acid complex production is displacing traditional pH precipitation methods, enabling tighter stability constant control and superior gastrointestinal protection against antagonistic mineral interactions.
Hydroxy analogue chelation technology is rewriting bioavailability benchmarks in ruminant nutrition by delivering protected copper and zinc that bypass rumen microbial degradation and release in the abomasum. Dairy nutritionists in Wisconsin and the Netherlands are adopting these complexes at accelerating rates for transition cow and high-production herd protocols. The technology is compressing the performance gap between organic chelates and hydroxy minerals while commanding intermediate pricing positions.
EFSA's re-evaluation of maximum permitted copper and zinc levels in complete feeds is forcing reformulation across European compound feed operations. The regulatory consequence extends beyond label adjustment to require supply chain documentation of chelate source, purity, and heavy metal contamination thresholds. Swine and poultry premix suppliers serving German, Danish, and Dutch markets are responding by consolidating supplier audits and shifting toward glycinate-based complexes with established EU 1831/2003 additive registrations.
Buyer concentration among integrated protein producers is compressing procurement cycles and demanding outcome-based mineral nutrition guarantees rather than standard ingredient specifications. Large-scale beef feedlot operators in Texas and Kansas now contract directly with chelate manufacturers for custom premix formulations tied to feed conversion and carcass grade performance metrics. This behavioral shift is most visible in North American cattle feeding regions where packer integration has consolidated buying power among fewer decision-makers.
Trace Minerals Chelated Feed Market Segmentation
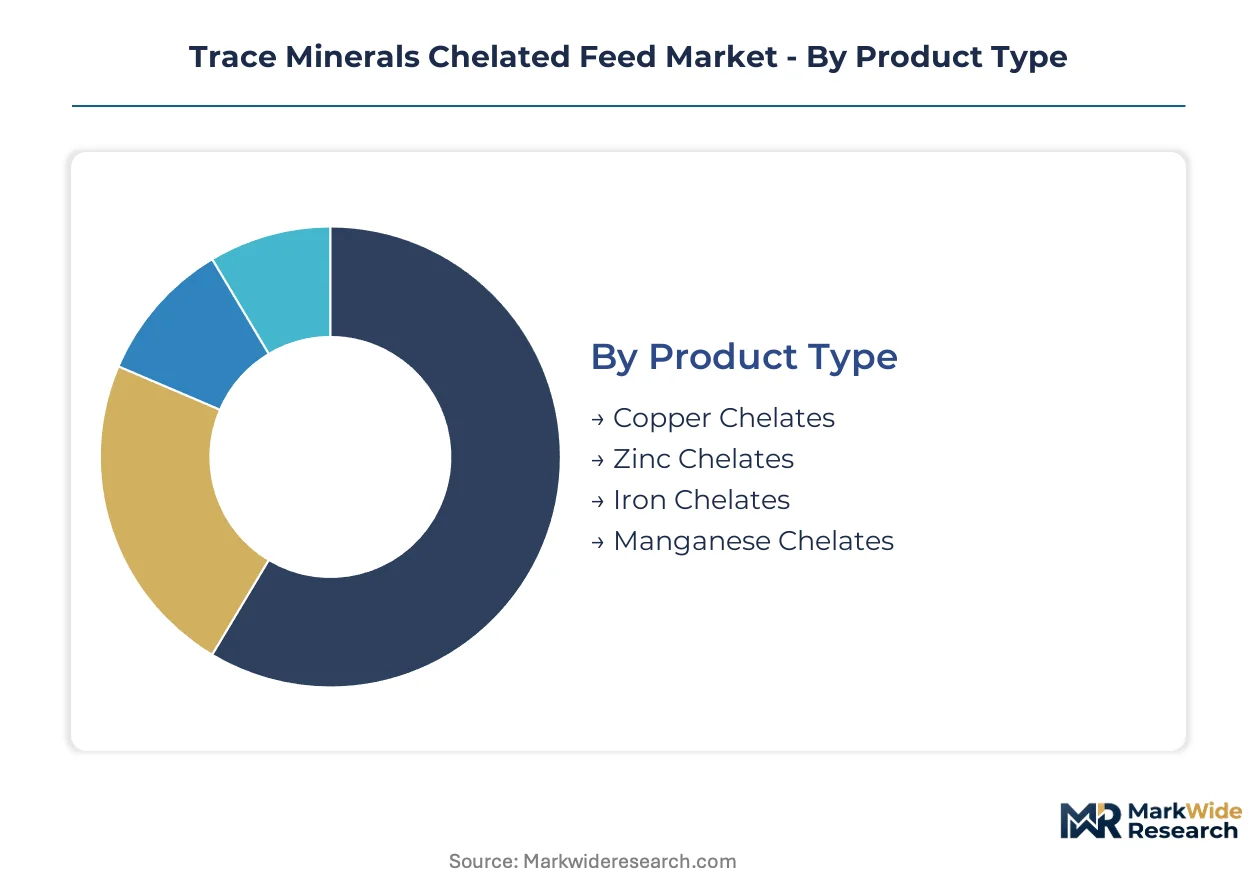
Segmentation in trace minerals chelated feed reveals how bioavailability requirements, species-specific metabolism, and feed manufacturing infrastructure shape procurement decisions across livestock value chains. Buyers prioritize mineral stability constants, handling characteristics, and regulatory compliance pathways when selecting chelated products.
Product Type:
Formulation selection hinges on species-specific absorption kinetics and environmental discharge regulations governing mineral excretion rates.
- Zinc Chelates:Metal-amino acid complexes with methionine or glycine ligands deliver protected bioavailability for immune modulation and epithelial integrity protocols. Dairy herds in Wisconsin and the Netherlands specify zinc methionine for hoof health programs and somatic cell count reduction. Zinc chelates dominate value pools due to volume concentration in ruminant and swine premix formulations.
- Copper Chelates:Lysine and glycinate complexes achieve rumen bypass protection or gastric absorption without antagonistic mineral interactions. Swine producers in Denmark and Germany are phasing out high-dose inorganic copper to comply with EFSA accumulation limits, redirecting demand toward chelated alternatives. Copper chelates are expanding most quickly as environmental discharge regulations tighten across EU member states and Chinese provinces.
- Iron Chelates:Ferrous bisglycinate complexes address bioavailability challenges in young animal nutrition and anemia prevention protocols.
- Manganese Chelates:Methionine-based complexes support bone development and reproductive performance in breeding stock operations.
Zinc chelates lead on scale; copper chelates lead on momentum.
End User:
Species metabolism determines ligand selection, dosing precision requirements, and premix integration complexity.
- Ruminants:Dairy and beef operations require rumen-protected chelates that bypass microbial degradation and release in the abomasum for intestinal absorption. Large-scale feedlots in Texas and integrated dairy processors in Brazil specify hydroxy analogue and amino acid complexes for transition cow and finishing protocols.
- Poultry:Broiler and layer operations prioritize uniform particle dispersion in mash and pelleted feeds for trace mineral adequacy across flock uniformity targets.
- Swine:Growing-finishing and sow units demand chelates with demonstrated bioavailability in gastric pH conditions without high-dose copper environmental liabilities.
- Aquaculture:Shrimp and salmonid producers in Norway and Chile require species-specific formulations addressing osmoregulation and immune resilience in saline and freshwater environments.
Ruminants anchor volume concentration; aquaculture presents the steepest expansion trajectory for species-specific formulation development.
Form:
Feed mill infrastructure and automated dosing capabilities dictate physical specification requirements.
- Powder:Spray-dried metal-amino acid complexes integrate into bulk premix handling systems at central feed mill operations. Powder formulations retain volume leadership due to compatibility with existing inorganic mineral conveying and storage equipment across Midwestern U.S. and Brazilian facilities.
- Liquid:Aqueous suspensions enable precision delivery through automated dosing systems in intensive poultry houses and recirculating aquaculture systems. Liquid chelates are gaining share fastest in facilities with real-time mineral adjustment based on growth-stage requirements.
- Granules:Agglomerated complexes reduce dust generation and improve flowability in mechanized batching operations.
- Pellets:Extruded mineral concentrates suit on-farm mixing and small-scale compound feed production.
Powder leads on installed base compatibility; liquid leads on precision nutrition adoption curves.
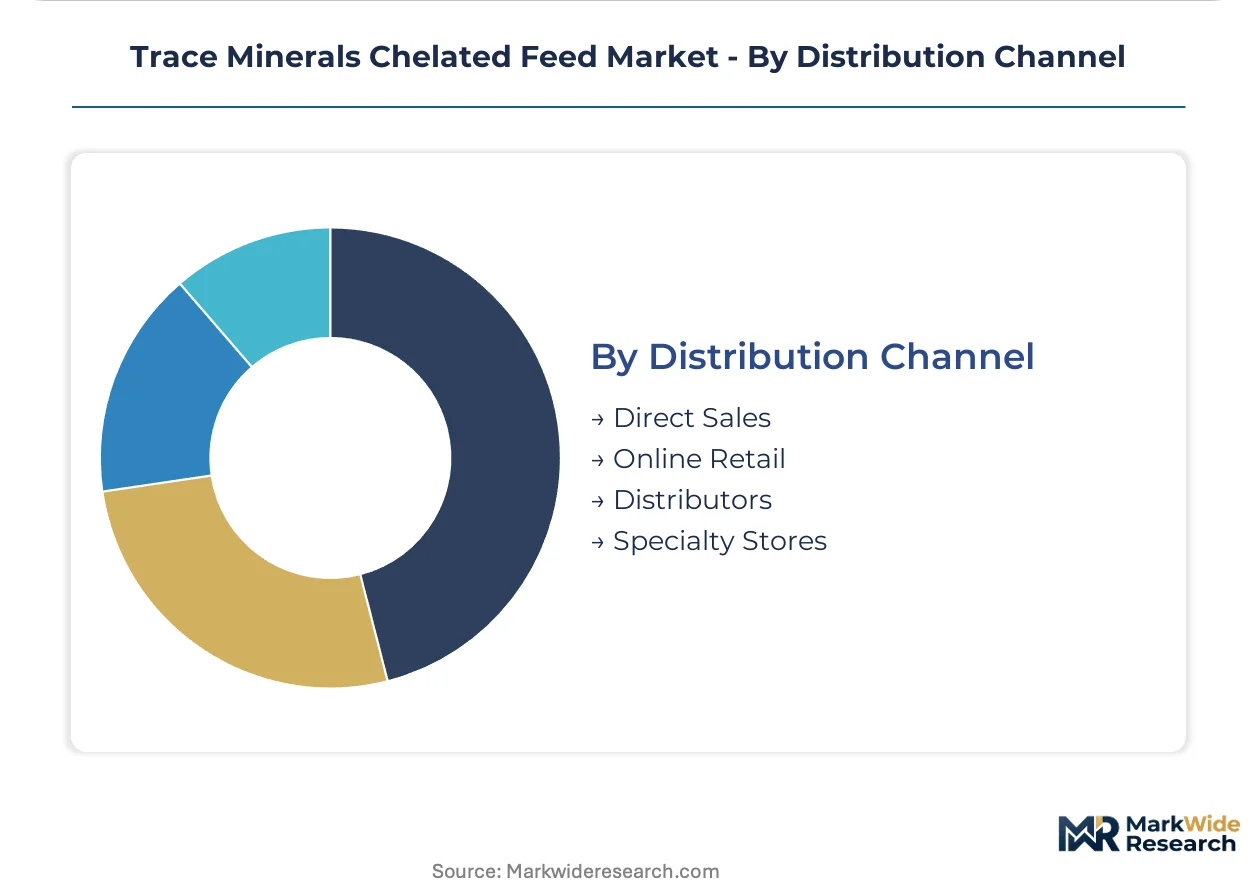
Distribution Channel:
Supply chain configuration reflects buyer scale, technical service requirements, and geographic concentration of livestock production.
- Direct Sales:Chelate manufacturers contract directly with integrated protein producers for custom premix formulations tied to performance guarantees. Large-scale beef feedlot operators in Kansas and Texas source through direct channels to secure amino acid chelate supply chains and technical nutrition support.
- Distributors:Regional feed ingredient distributors aggregate demand from mid-sized compounders and independent premix blenders. Distributor networks dominate in fragmented European markets with diverse national registration requirements.
- Online Retail:E-commerce platforms serve small-scale livestock producers and specialty animal operations with standardized mineral supplements.
- Specialty Stores:Farm supply cooperatives and veterinary clinics provide chelated products for hobby farms and performance horse segments.
Direct sales lead on contract value concentration; distributors lead on geographic coverage breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate chelate synthesis toward jurisdictions with streamlined feed additive registration pathways and lower environmental compliance costs. Brazil and China attract capital for integrated mineral premix facilities while European producers absorb EFSA-driven reformulation expenses.
United States
Large-scale beef feedlots in Texas and Kansas drive concentrated demand for rumen-protected copper and zinc complexes tied to feed conversion performance contracts. The FDA's Veterinary Feed Directive mandates veterinary oversight for medically important minerals, elevating documentation requirements for premix suppliers. Midwestern premix manufacturing clusters around Iowa and Illinois are consolidating through acquisition to secure amino acid chelate supply chains.
Brazil
Integrated livestock producers in Mato Grosso and Paraná are retrofitting feed mills with chelated mineral blending capacity to serve expanding dairy and beef export operations. ANVISA's alignment with Codex Alimentarius standards for feed-grade mineral purity creates registration pathways for glycinate-based complexes. São Paulo-based compounders are contracting directly with chelate manufacturers for custom transition cow formulations.
Germany
Swine and poultry premix operations in Lower Saxony and North Rhine-Westphalia are reformulating to comply with EFSA's reduced maximum permitted copper and zinc levels. The EU's Feed Hygiene Regulation enforces supply chain documentation of chelate source and heavy metal thresholds. Bavarian feed mills are shifting procurement toward glycinate complexes with established EU 1831/2003 additive registrations.
China
Commercial pig and poultry producers in Shandong and Guangdong provinces are transitioning from inorganic oxide mineral forms under Ministry of Agriculture and Rural Affairs GB standards enforcement. The regulatory preference for organic complexes over sulfates and oxides creates divergent product registration pathways for multinational manufacturers. Yangtze River Delta feed compounders are upgrading blending lines to handle methionine-chelated selenium for sow reproductive protocols.
Netherlands
High-intensity dairy operations in Friesland and Gelderland specify zinc methionine for hoof health programs and somatic cell count management. EFSA's re-evaluation of mineral maximums compounds with national phosphate reduction targets to accelerate chelate adoption. Wageningen-area nutrition research clusters are validating hydroxy analogue chelation technology for transition cow applications.
Trace Minerals Chelated Feed Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue species-specific formulation niches and automated dosing system integration. The supplier base stratifies between multinational chemical conglomerates with captive mineral supply chains and specialized animal nutrition houses focused on metal-amino acid complex patents. Three archetypes dominate: grain-origination backward-integrated compounders, technology-driven chelation specialists, and diversified nutrition multinationals. Competitive moves concentrate on regional premix manufacturing consolidation and direct-to-producer technical service contracts that displace distributor intermediaries.
Within the technology-specialist tier, Zinpro Corporation exemplifies patent-protected metal-amino acid complex positioning, while BASF SE anchors European supply security through multi-site glycinate production. Among grain-integrated conglomerates, Cargill, Incorporated leverages its captive origination network to control backward-integrated premix distribution channels. These three entities represent distinct competitive vectors: chelation science leadership, regional regulatory compliance infrastructure, and supply chain vertical control.
| Leading Market Players |
|---|
| Phibro Animal Health Corporation |
| Cargill, Incorporated |
| Zinpro Corporation |
| BASF SE |
| DSM Nutritional Products |
| Alltech, Inc. |
| Kemin Industries, Inc. |
| Archer Daniels Midland Company |
| Novus International, Inc. |
| Others |
Value Network & Pricing Analysis
Amino acid feedstock costs—methionine and lysine derived from petrochemical and fermentation processes—transmit directly through chelate manufacturing tiers, compressing margins at standard-formulation levels while glycinate-based premium complexes retain pricing power through EFSA-aligned certification.
Pricing Analysis
Distributor margin layering separates bulk compounders from integrated livestock producers, with direct-to-feedlot contracts commanding 15-20 point discounts for volume commitment. Three-tier pricing structure across glycinate-premium, amino acid-standard, and hydroxy-economy levels reflects bioavailability certification grade and heavy metal purity thresholds. Cost compression in standard chelates is intensifying because Chinese amino acid supply volatility feeds raw material unpredictability. Price-sensitive swine and broiler integrators in Brazil and Germany drive procurement toward hydroxy mineral substitutes, while dairy nutritionists in Wisconsin and the Netherlands absorb premium zinc methionine pricing for hoof health outcome guarantees.
Supply Chain Analysis
Workforce availability constraints in Shandong and Guangdong provinces limit expansion velocity for methionine ligand fermentation capacity, tethering global chelate output to Chinese coastal manufacturing zones. Amino acid ligand production clusters heavily in China and select Southeast Asian facilities, drawing from petrochemical feedstocks and corn-derived fermentation substrates. Single-source vulnerability concentrates in methionine supply, where three producers control 70 percent of global capacity. Distribution runs through regional feed ingredient distributors in fragmented European markets and direct technical service contracts with integrated protein producers in North American cattle feeding regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in glycinate-premium tier migration as EFSA copper and zinc maximums force reformulation toward certified organic complexes with documented supply chain provenance.
For Market Incumbents: Extend patent-protected metal-amino acid complex portfolios into species-specific aquaculture formulations targeting Norwegian salmonid and Chilean shrimp immune resilience protocols. Defend against hydroxy mineral substitution by embedding performance guarantees into direct contracts with Texas and Kansas feedlot operators. Backward integration into captive amino acid supply through offtake agreements with Shandong fermentation facilities secures ligand cost stability. For New Entrants and Emerging Players: The price-point gap between premium glycinate complexes and economy hydroxy minerals opens positioning for intermediate amino acid chelates with rumen-bypass validation. Target Brazilian Mato Grosso and Paraná retrofit feed mills with technical service infrastructure for transition cow mineral nutrition. Go-to-market leverage rests on automated liquid dosing system integration for intensive poultry houses seeking real-time mineral adjustment capability. For Investors and Strategic Acquirers: Roll-up economics work for regional premix blenders with established EU 1831/2003 additive registrations because regulatory compliance creates moats against unregistered import competition. Long-term viability frames around 5-10 year organic mineral transition curves in China and Brazil. Acquisition target archetype: mid-scale glycinate manufacturers with multi-site European production and existing EFSA documentation. Signal to watch: ANVISA alignment with Codex Alimentarius standards accelerating Brazilian registration pathway convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Supply | Captive methionine and lysine sourcing insulates margin from Chinese petrochemical volatility. |
| Species-Specific Aquaculture Formulation Development | Methionine-chelated selenium targeting Norwegian and Chilean immune resilience protocols opens white space. |
| EFSA-Aligned Glycinate Registration Investment | EU 1831/2003 additive status secures access to German, Danish, and Dutch reformulating compounders. |
| Automated Liquid Dosing System Partnership | Precision delivery integration captures share in intensive poultry and recirculating aquaculture facilities. |
| Brazilian Feed Mill Retrofit Technical Service | First-mover infrastructure in Mato Grosso and Paraná locks in integrated livestock producer contracts. |
Research Methodology
Multiple input streams—structured interviews with premix manufacturing executives, regulatory affairs specialists at chelate suppliers, dairy nutritionists in Wisconsin and the Netherlands, and feed procurement managers at Brazilian integrated livestock operations—were reconciled against customs data on amino acid ligand trade flows, EFSA additive registration databases, and SEC filings from publicly traded animal nutrition conglomerates. Bottom-up volume modeling across zinc, copper, iron, and manganese chelate categories was cross-validated with top-down expenditure estimates from compound feed production statistics.
Historical absorption curves for organic versus inorganic mineral forms were cross-referenced against panel input from ruminant and monogastric nutrition specialists to anchor bioavailability assumptions throughout the forecast period. Segmentation dimensions modeled include mineral type, species end-use, physical form, and distribution channel structure, with CAGRs derived from logistic diffusion curves fitted to regulatory transition timelines and feed mill retrofit adoption patterns. Industry-specific forecast inputs incorporated EFSA maximum permitted level re-evaluations and China's GB standards enforcement trajectory for organic complex preferences.
Caveats apply where EFSA copper and zinc maximum revisions, Chinese amino acid supply disruptions, or hydroxy mineral technology breakthroughs could materially shift the outlook. Forecasts reflect assumptions on regulatory implementation pace and species-specific formulation adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Cattle Nutrition Market