
 Animal Salt Licks Market | 2026-2036
Animal Salt Licks Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Salt Licks Market Insights
Buyer concentration among commercial livestock farmers is pivoting toward fewer, larger integrated operations that negotiate supply contracts at scale. Cargill leverages its global feed distribution network to bundle salt licks with broader mineral programs. K+S Aktiengesellschaft anchors European supply through its domestic salt mining assets. Ridley Corporation specializes in formulated livestock supplements across Australian grazing regions.
Animal salt licks are solid mineral blocks or loose formulations composed primarily of sodium chloride with trace elements including cobalt, iodine, zinc, and selenium, manufactured through compression molding or evaporative crystallization processes to provide essential electrolyte balance and micronutrient supplementation for ruminant and monogastric animals. Mineral blocks dominate commercial livestock channels due to their durability and controlled intake rates, while flavored licks compete for equine and exotic animal segments where palatability drives preference. Online retail extends fastest among pet owners and small-scale hobby farmers seeking specialized formulations unavailable through traditional farm supply stores.
The EU Green Deal and REACH frameworks restrict synthetic additive content in feed-grade minerals, while the USDA and FDA govern nutritional claims and manufacturing sanitation for products entering US interstate commerce. BIS standards in India and China's GB standards for feed additives create divergent compliance pathways that fragment cross-border formulation strategies. Stakeholders must monitor evolving residue limits and carbon accounting rules that will determine which material sources and distribution channels retain cost advantages.
Market Dynamics
Commercial livestock consolidation is compressing supplier margins as integrated operations demand volume-tiered contracts and traceable mineral sourcing. The EU Green Deal's carbon accounting rules now require feed-grade mineral suppliers to document supply chain emissions or face exclusion from European procurement channels.
Growth Catalysts
- EU Green Deal feed standards:Mandatory sustainability disclosure for mineral additives is forcing reformulation toward lower-carbon salt sources, creating upgrade cycles across European livestock operations.
- Brazilian cattle ranching expansion:Pasture intensification programs in Mato Grosso and Pará are driving systematic mineral supplementation adoption among commercial herds.
- Evaporative crystallization advances:Solar-powered brine processing is reducing energy inputs for block manufacturing, improving margins for producers with desert basin access.
Market Restraints
- Potassium chloride price volatility:Fertilizer market competition for KCl feedstock creates input cost instability that compresses formulated supplement margins.
- Chinese state salt monopoly concentration:Controlled access to domestic evaporite deposits limits independent formulation flexibility for Asia-Pacific distributors.
- Synthetic amino acid substitution:Precision-formulated liquid premixes are displacing traditional block formats in intensive poultry and swine systems.
Strategic Opportunities
- Indian dairy cooperative channel:18 million smallholder members of Amul and Nandini federations remain underpenetrated for branded mineral supplementation.
- Carbon credit monetization:Methane-reducing mineral formulations qualifying under Verra and Gold Standard protocols open premium pricing in climate-conscious supply chains.
- Veterinary telehealth integration:Remote herd health platforms are creating direct-to-producer mineral recommendation engines that bypass traditional feed dealer networks.
Industry Challenges
- ISO 22000 certification timelines:Feed safety management system audits require 12-18 month implementation cycles that delay market entry for new regional suppliers.
- Legacy ERP integration:Batch traceability requirements for EU export compliance force costly middleware development for established manufacturers with outdated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Salt Licks Market |
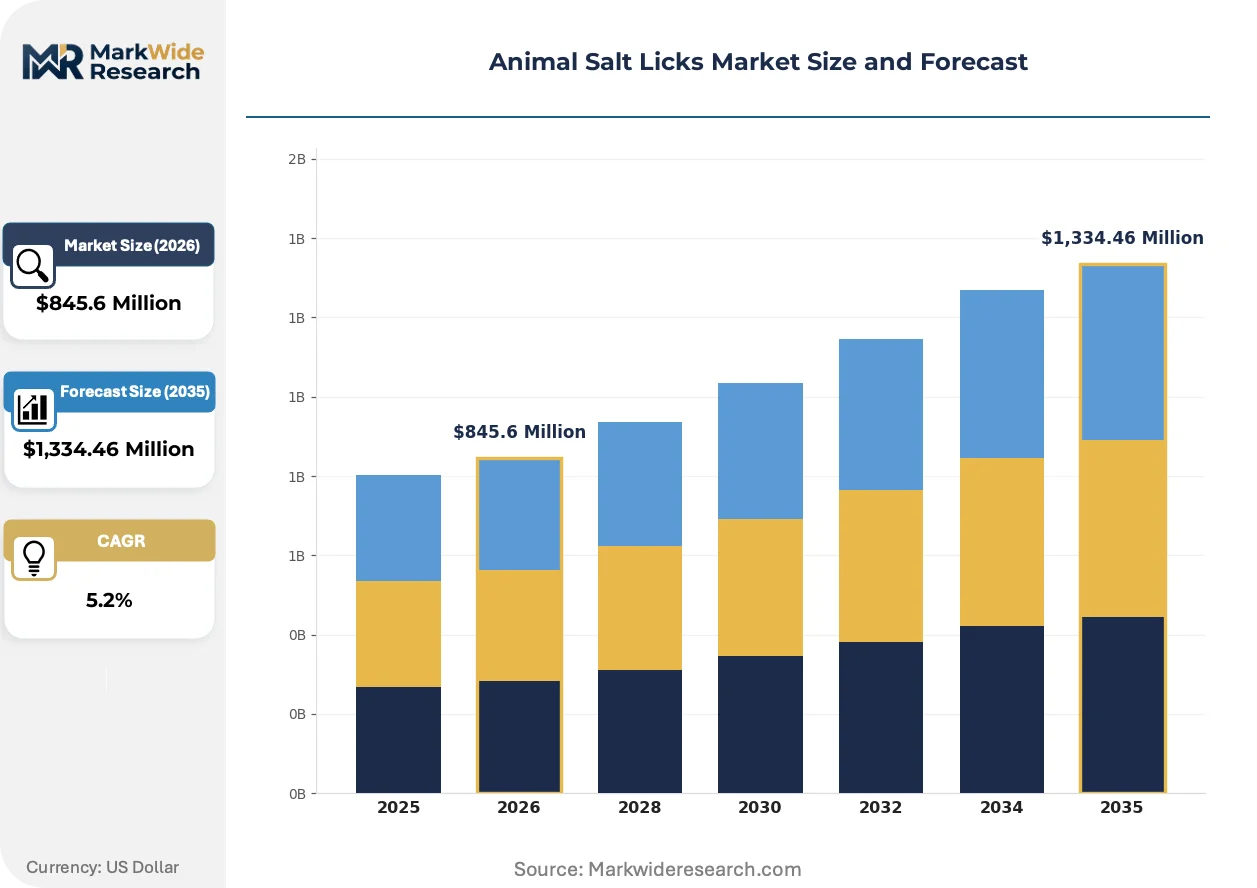
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,334.46 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Blocks, Loose Salt, Flavored Licks, Calcium Licks End User: Livestock Farmers, Zoos, Pet Owners, Veterinarians Material: Rock Salt, Sea Salt, Mineral Additives, Natural Ingredients Distribution Channel: Online Retail, Farm Supply Stores, Pet Shops, Direct Sales |
| Companies Covered | Cargill, K+S Aktiengesellschaft, Ridley Corporation, Morton Salt, Compass Minerals, Land O'Lakes, Himalayan Salt Company, Tata Chemicals Magadi, Nutribio Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Salt Licks Market Trends and Innovations
Formulation science is converging with digital livestock management platforms, compressing the traditional separation between mineral supplementation and real-time herd health monitoring. Three developments are actively restructuring competitive positioning.
Controlled-release polymer matrices are consolidating mineral delivery technology by embedding trace elements in biodegradable coatings that dissolve across 30-90 day cycles. Large-scale feedlot operators in Texas and Alberta are adopting these systems to reduce labor costs associated with frequent block replacement. The technology is consolidating supplier relationships as ranchers abandon multiple single-nutrient products for integrated slow-release platforms.
REACH authorization requirements for cobalt compounds are restricting traditional formulations across EU member states, forcing substitution with organic chelated alternatives. German and Dutch compound feed manufacturers are reformulating product lines to maintain market access, passing compliance costs through to livestock cooperatives. Small Polish and Romanian blenders lacking technical reformulation capacity are exiting the market or selling to larger integrated competitors.
Subscription-based mineral programs are displacing spot purchasing among North American cow-calf operations, with suppliers delivering calibrated monthly shipments tied to seasonal forage quality. Ranchers in Montana and Wyoming are locking in 12-month contracts that include forage testing and custom formulation adjustments. The model concentrates purchasing power with vertically integrated nutrition service providers and marginalizes traditional farm supply retailers.
Animal Salt Licks Market Segmentation
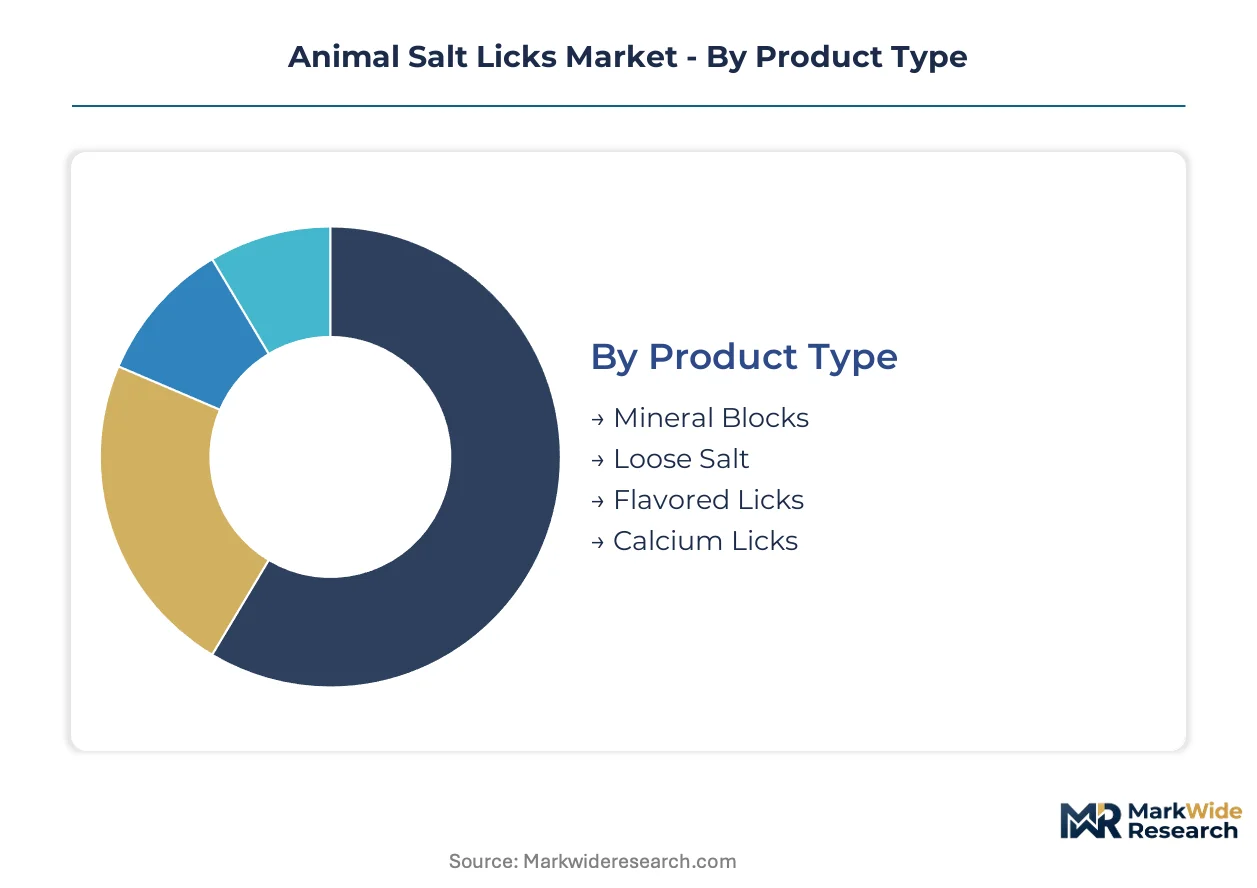
Segmentation in animal salt licks reveals divergent growth trajectories between industrial-scale livestock operations and specialized companion animal channels. Product durability, mineral bioavailability, and procurement convenience determine competitive positioning across each category.
Product Type:
Volume concentration sits with weather-resistant compressed formats, while palatability-enhanced variants command premium positioning in specialty channels.
- Mineral Blocks:Compressed sodium chloride matrices with embedded trace elements withstand environmental exposure across open pasture systems. Brazilian cattle ranching operations in Mato Grosso specify 50kg blocks for automated trough placement, driving systematic adoption among commercial herds.
- Loose Salt:Granular formulations enable precision dosing through mechanized feed mixing equipment. North American feedlot operators favor loose salt for integration with total mixed rations, though handling losses and moisture sensitivity constrain outdoor deployment.
- Flavored Licks:Molasses- or apple-infused blocks target equine and exotic animal keepers seeking voluntary intake control.
- Calcium Licks:Phosphorus-fortified variants address lactation-stage mineral deficits in high-producing dairy systems.
Today's leader: Mineral Blocks. Tomorrow's challenger: Flavored Licks.
End User:
Procurement scale separates contract-negotiating commercial operators from fragmented individual purchasers.
- Livestock Farmers:Integrated cattle, sheep, and goat operations purchase through volume-tiered supply agreements with mineral blenders. Australian grazing cooperatives coordinate collective procurement through Ridley Corporation distribution networks, consolidating regional demand.
- Zoos:Captive wildlife facilities require species-specific mineral formulations audited by veterinary nutritionists.
- Pet Owners:Equine enthusiasts and small-scale hobby farmers source specialized licks through digital channels.
- Veterinarians:Clinical mineral recommendations increasingly flow through telehealth platforms bypassing traditional feed dealers.
Procurement gravity centers on Livestock Farmers. Digital access is elevating Pet Owners fastest.
Material:
Source certification now determines EU market access under Green Deal carbon accounting protocols.
- Rock Salt:Underground evaporite deposits supply high-purity sodium chloride for compression molding. K+S Aktiengesellschaft mines domestic German deposits, anchoring European supply with documented supply chain emissions profiles.
- Sea Salt:Solar evaporation from coastal brine ponds offers lower-carbon credentials for sustainability-conscious procurement.
- Mineral Additives:Chelated cobalt, organic selenium, and zinc oxide concentrates enable precision trace element dosing.
- Natural Ingredients:Unrefined salt with retained marine minerals appeals to organic certification pathways.
Rock Salt dominates tonnage. Sea Salt is climbing the fastest on carbon credentials.
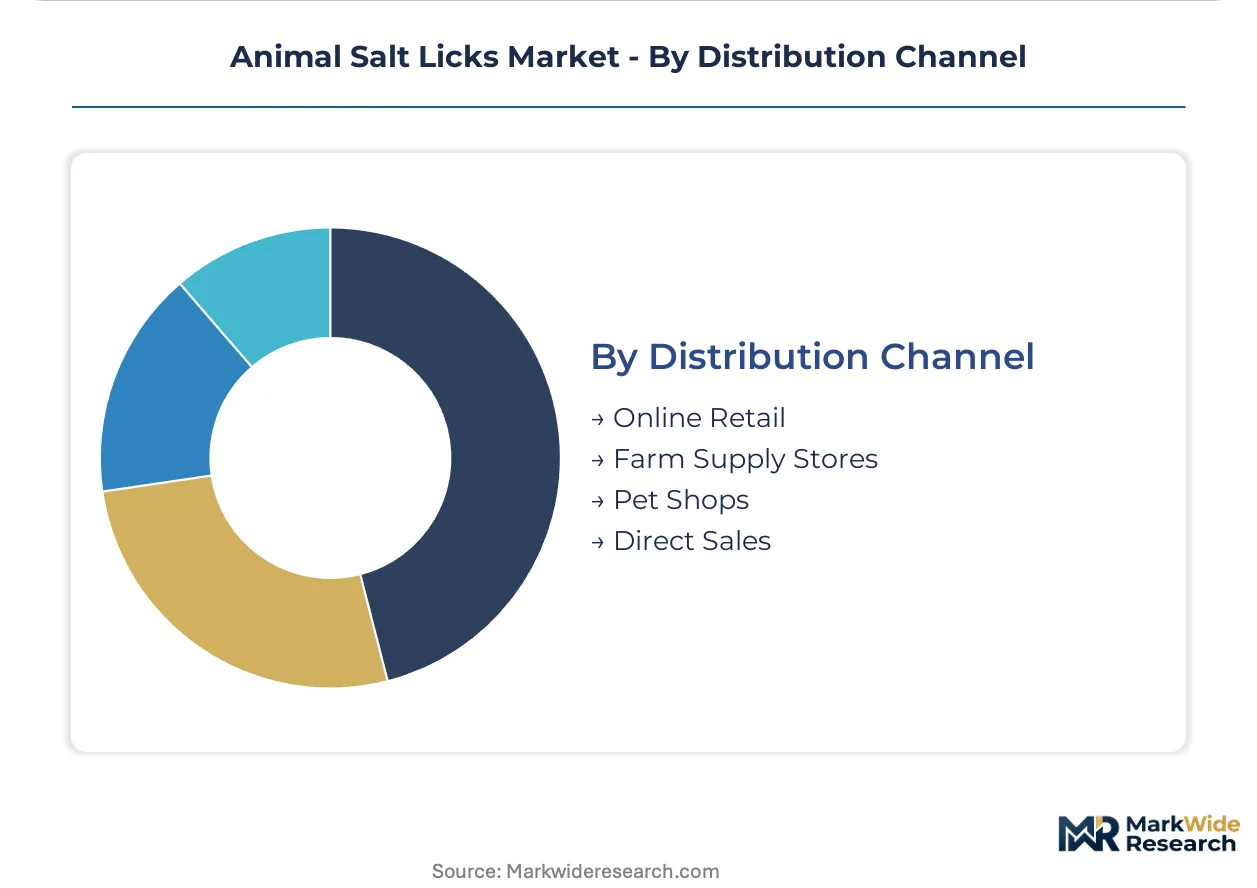
Distribution Channel:
Channel selection reflects buyer scale, formulation complexity, and delivery urgency requirements.
- Online Retail:E-commerce platforms aggregate specialized formulations for dispersed smallholders and pet owners. Amazon and Chewy capture equine supplement demand with subscription replenishment models unavailable through traditional farm supply stores.
- Farm Supply Stores:Regional cooperatives and independent dealers maintain bulk mineral block inventories for immediate pickup.
- Pet Shops:Specialty retailers stock flavored and decorative lick holders for companion animal segments.
- Direct Sales:Vertically integrated nutrition service providers lock in 12-month contracts with forage testing and custom calibration.
Farm Supply Stores anchor volume. Direct Sales is gaining share fastest through bundled nutrition services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cattle ranching expansion outpaces European mineral supplementation adoption, while India's dairy cooperatives present untapped scale that commercial suppliers are only beginning to penetrate.
United States
North American feedlot operators in Texas and Montana drive systematic mineral block adoption through volume-tiered contracts. The USDA and FDA govern nutritional claims and manufacturing sanitation for interstate commerce. Ranchers in Wyoming are locking in 12-month subscription contracts that bundle forage testing with calibrated mineral shipments.
Germany
REACH authorization requirements for cobalt compounds force reformulation toward organic chelated alternatives across compound feed manufacturing. The EU Green Deal mandates carbon accounting documentation for feed-grade mineral suppliers accessing procurement channels. K+S Aktiengesellschaft mines domestic evaporite deposits, anchoring European supply with traceable emissions profiles.
Brazil
Pasture intensification programs in Mato Grosso and Pará drive commercial herd mineral supplementation adoption at scale. ANVISA regulates feed additive safety standards for domestic manufacturing and import channels. Cattle ranching operations specify 50kg weather-resistant blocks for automated trough placement across open pasture systems.
India
18 million smallholder members of Amul and Nandini federations remain underpenetrated for branded mineral supplementation despite rising milk productivity demands. BIS standards for feed additives create compliance pathways that domestic blenders must navigate. Dairy cooperatives in Gujarat and Maharashtra coordinate collective procurement that concentrates regional demand for mineral suppliers.
Australia
Grazing cooperatives across Queensland and New South Wales coordinate mineral procurement through specialized distribution networks serving extensive beef and sheep operations. The TGA oversees veterinary product standards that influence mineral formulation claims. Ridley Corporation maintains formulated livestock supplement capabilities across Australian grazing regions.
Animal Salt Licks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply relationships. Commercial livestock consolidation compresses supplier margins as integrated operations demand volume-tiered contracts and traceable mineral sourcing. Three archetypes dominate: integrated agricultural conglomerates with captive feed distribution, specialized mineral blenders with regional formulation expertise, and salt mining operators with backward integration into feed-grade processing. Competitive moves center on strategic partnerships with dairy cooperatives and portfolio diversification into carbon-credentialed mineral lines.
Among diversified agricultural conglomerates, Cargill leverages global feed distribution infrastructure to bundle salt licks with broader mineral programs. K+S Aktiengesellschaft represents the mining-integrated archetype, anchoring European supply through domestic salt mining assets with documented emissions profiles. Ridley Corporation exemplifies the regional specialist model, occupying a formulation-focused position across Australian grazing regions.
| Leading Market Players |
|---|
| Cargill |
| K+S Aktiengesellschaft |
| Ridley Corporation |
| Morton Salt |
| Compass Minerals |
| Land O'Lakes |
| Himalayan Salt Company |
| Tata Chemicals Magadi |
| Nutribio Ltd |
| Others |
Pricing and Supply Chain Analysis
Specialized mineral formulation chemists concentrated in Germany and the Netherlands command wage premiums that widen pricing spreads between premium chelated formulations and standard oxide-based blocks. Labor-cost differentials between European technical specialists and Asian-Pacific production workers translate directly into tiered product positioning across export markets.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for weather-resistant compressed blocks serving commercial cattle operations. Pricing stratifies across premium, standard, and economy tiers based on certification grade under EU Green Deal carbon accounting protocols and volume-scale procurement commitments. Cost compression in standard-grade blocks is intensifying because Brazilian ranchers negotiate multi-year offtake agreements at scale. Smallholder dairy cooperatives in India exhibit highest price sensitivity, while North American feedlot operators prioritize traceability and controlled-release technology over unit cost.
Supply Chain Analysis
Skilled brine processing technicians remain scarce in Germany's evaporite mining regions, constraining expansion timelines for K+S Aktiengesellschaft's feed-grade salt output. Supply concentrates in Germany, Brazil, and Australia for rock salt extraction and block manufacturing. Formulated supplements draw from potassium chloride, chelated trace elements, and biodegradable polymer matrices. Single-source vulnerability sits with Chinese state-controlled evaporite access limiting Asia-Pacific distributor flexibility. Distribution runs through vertically integrated nutrition service providers locking in subscription contracts with forage testing and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal salt licks function as a stable compounder anchored by irreplaceable mineral supplementation requirements in commercial livestock systems. Livestock productivity mandates create steady upgrade cycles regardless of commodity price cycles.
For Market Incumbents: Anticipate displacement pressure from precision-formulated liquid premixes in intensive poultry and swine systems by accelerating controlled-release polymer matrix R&D. Defend position through backward integration into certified low-carbon sea salt sourcing that satisfies EU Green Deal procurement requirements. Lock in 12-month subscription contracts with forage testing services to marginalize traditional farm supply retailers.
For New Entrants and Emerging Players: EU Green Deal carbon accounting rules in Europe open a window for certified low-emission mineral blocks to capture premium positioning. Target Indian dairy cooperatives in Gujarat and Maharashtra with collective procurement models serving 18 million smallholder members currently underpenetrated for branded supplementation. Enter through veterinary telehealth platforms offering direct-to-producer mineral recommendation engines that bypass established feed dealer networks.
For Investors and Strategic Acquirers: Agricultural conglomerates with captive feed distribution infrastructure are the most active acquirer in this space, seeking mineral formulation capabilities to bundle with broader nutrition programs. Focus on regional specialists with established dairy cooperative relationships and ISO 22000 certification already in place. Watch for REACH authorization restrictions on cobalt compounds forcing technical reformulation exits among smaller Polish and Romanian blenders as acquisition inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Salt Sourcing | EU Green Deal compliance secures procurement access to European livestock cooperatives. |
| Controlled-Release Polymer Matrix Development | Texas and Alberta feedlots adopt 30-90 day dissolution cycles reducing labor replacement costs. |
| Veterinary Telehealth Platform Partnership | Montana and Wyoming ranchers receive direct mineral recommendations bypassing traditional dealers. |
| Indian Dairy Cooperative Channel Development | Amul and Nandini federation members remain underpenetrated for systematic supplementation programs. |
| Carbon Credit Certification Investment | Verra and Gold Standard protocols enable premium pricing in climate-conscious beef supply chains. |
Research Methodology
Coverage spans North America, Europe, South America, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Mineral formulation chemists, livestock procurement managers at integrated operations, dairy cooperative federation directors, and feed additive regulatory affairs specialists provided structured interviews. Secondary sources include USDA nutritional claim filings, EU REACH authorization databases, ANVISA feed safety registrations, and BIS standard documentation. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product format, end-user scale tier, material source certification, and distribution channel structure. CAGRs derive from logistic adoption curves fitted to mineral supplementation penetration rates in commercial versus smallholder systems. Forecast inputs incorporate pasture intensification program timelines in Mato Grosso and Pará, plus EU carbon accounting implementation schedules.
Revisions become necessary when EU Green Deal carbon border adjustments accelerate, Brazilian cattle herd liquidation cycles deepen, or Chinese state salt monopoly export quotas tighten. Forecasts reflect assumptions around regulatory stability, forage quality monitoring adoption, and veterinary telehealth platform scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Poultry Vitamin Market