
 Calf Milk Replacers Market | 2026-2036
Calf Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Calf Milk Replacers Market Analysis
European dairy ingredient processors is repositioning capacity toward specialized calf nutrition lines to capture premium returns from livestock producers. Cargill, Incorporated leverages its integrated grain-protein supply chain to sustain cost-advantaged replacer production across North American dairy corridors. Trouw Nutrition anchors its competitive stance through precision nutrition technology that differentiates its formulations for high-growth heifer programs. Volac International Ltd. specializes in whey-based calf milk replacers, occupying a defensible niche among UK and Irish dairy farm cooperatives.
Calf milk replacers are manufactured dairy-based or vegetable-protein formulations designed to replicate the nutritional profile of whole milk, typically containing 18-22% crude protein and 15-20% fat content delivered via spray-dried or agglomerated processes, and serve to nourish neonatal calves when maternal milk is unavailable or economically suboptimal. Milk powder formulations dominate volume due to extended shelf stability and ease of transport, while liquid formula commands margin premiums from large-scale dairy farms seeking labor efficiency in automated feeding systems. Granular and pelleted formats are gaining traction among livestock producers with mechanical feeding infrastructure, though these segments remain structurally smaller with concentrated demand in Northern European operations.
The European Food Safety Authority and national regulators under the EU Feed Hygiene Regulation enforce strict microbiological and contaminant thresholds that shape product formulation standards and market access conditions for imported replacers. The US Food and Drug Administration and state-level agriculture departments monitor antibiotic residue claims and medicated feed additives, constraining label positioning and influencing R&D allocation toward non-medicated nutritional solutions. Stakeholders must monitor evolving protein sourcing regulations and carbon footprint disclosure requirements that will increasingly determine supplier qualification and procurement criteria across major dairy-producing regions.
Market Dynamics
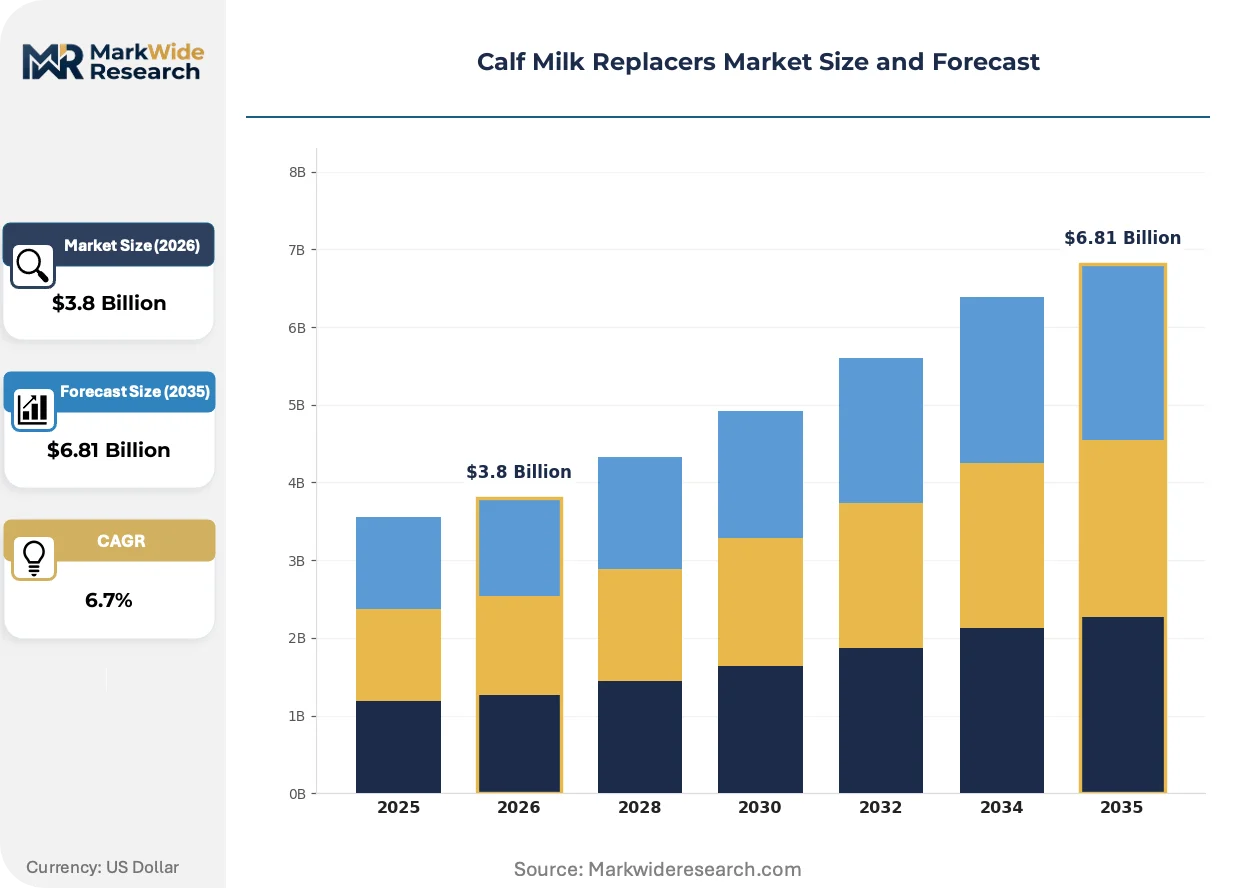
Precision-formulated calf nutrition is displacing conventional whole milk feeding as dairy operators confront antibiotic residue regulations and labor cost pressures. The EU Veterinary Medicines Regulation and parallel US FDA frameworks are compressing margins for medicated feed additives while opening premium positioning for clean-label whey and vegetable-protein formulations.
Growth Catalysts
- EU Veterinary Medicines Regulation:Antibiotic residue limits are forcing dairy farms toward non-medicated milk replacers with documented microbiological safety profiles.
- Automated calf feeding systems:Large-scale operations in the Netherlands and Wisconsin are standardizing liquid formula protocols to reduce labor hours per calf.
- Whey protein concentrate availability:European dairy ingredient processors are redirecting surplus whey streams into specialized calf nutrition lines.
Market Restraints
- Skim milk powder price volatility:Global dairy commodity swings directly compress replacer formulation margins, particularly for spray-dried milk powder products.
- Single-source dependency:Northern European whey processors dominate high-quality protein concentrate supply, creating geographic concentration risk.
- Technical substitution ceiling:Vegetable-protein formulations face digestibility limitations in calves under three weeks, constraining complete maternal milk replacement.
Strategic Opportunities
- Polish and Romanian dairy expansion:Underpenetrated Eastern European markets with growing herd sizes lack established replacer distribution networks.
- Carbon footprint disclosure mandates:The EU Green Deal is creating procurement preference for replacers with verified lifecycle emissions data.
- Blockchain-enabled provenance tracking:Converging digital traceability with feed safety certification is opening premium channel positioning.
Industry Challenges
- Precision nutrition specialist scarcity:Dairy farm advisory services lack personnel trained in automated feeding system calibration and calf growth monitoring.
- EFSA novel ingredient approval timelines:Microbiome-modulating additives face extended safety evaluation periods that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calf Milk Replacers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Liquid Formula, Granular, Pelleted End User: Dairy Farms, Livestock Producers, Research Institutions, Feed Manufacturers Composition: High Protein, Low Protein, High Fat, Essential Nutrients Packaging Type: Bags, Tubs, Pails, Bulk Containers |
| Companies Covered | Land O'Lakes, Inc., Cargill, Incorporated, Archer Daniels Midland Company, CHS Inc., Glanbia plc, Lactalis Group, Trouw Nutrition, Milk Specialties Global, Volac International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calf Milk Replacers Market Emerging Trajectories
Formulation science and feeding automation are converging to redefine calf rearing economics. Three developments are compressing traditional practices while opening premium positioning for technology-enabled nutrition providers.
Spray-dried whey protein concentrates with enhanced immunoglobulin retention are expanding into neonatal calf protocols previously reserved for whole colostrum. Dutch and Irish dairy cooperatives are adopting these formulations for heifer replacement programs. The technology is expanding into automated feeding systems that meter precise protein-to-fat ratios by calf age and weight.
REACH chemical registration requirements and the EU Feed Hygiene Regulation are tightening contaminant thresholds for imported dairy ingredients. European replacer manufacturers are reformulating with regionally sourced proteins to avoid border inspection delays. Medicated feed additive categories face particular scrutiny, accelerating R&D investment in botanical and organic acid alternatives.
Large-scale dairy operations are consolidating calf rearing into centralized facilities with mechanical feeding infrastructure. This procurement concentration is displacing small-batch milk powder purchases in favor of long-term supply contracts with volume-tiered pricing. The shift is most visible in California's Central Valley and the Netherlands' Gelderland province, where 500-plus cow operations now dominate replacer demand.
Calf Milk Replacers Market Segmentation
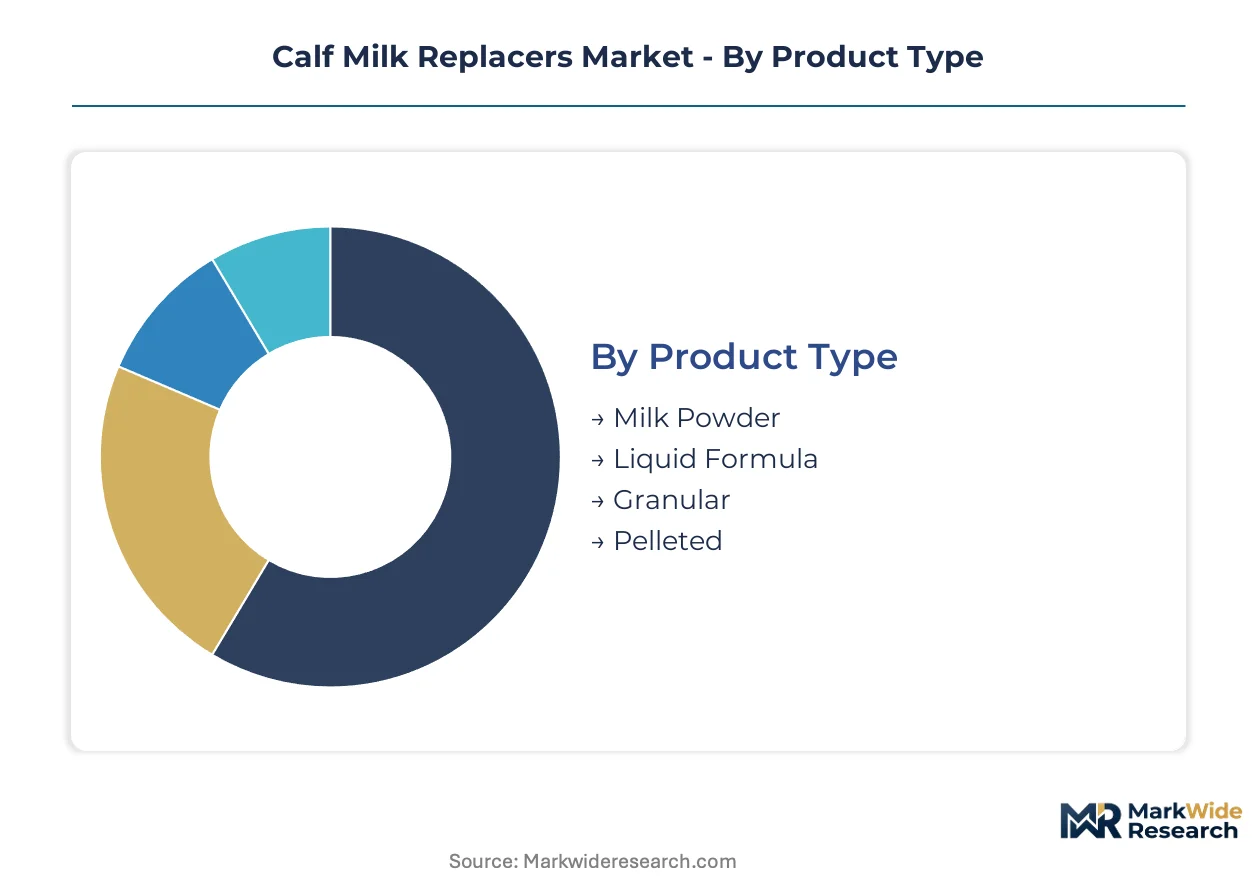
Calf milk replacer manufacturers configure product lines around feeding infrastructure, buyer scale, and nutritional protocols. Segment boundaries reflect operational constraints at dairy operations rather than abstract consumer preferences.
Product Type:
Dairy operators select formats based on labor availability, storage capacity, and whether automated feeding systems are deployed.
- Milk Powder:Spray-dried formulations with 18-22% crude protein and 15-20% fat content deliver extended shelf stability and economical transport. Dutch and Wisconsin dairy corridors concentrate procurement here for manual mixing operations.
- Liquid Formula:Pre-mixed solutions meter precise protein-to-fat ratios through automated calf feeding systems. Large-scale Gelderland province operations and California Central Valley dairies absorb volume premiums for labor efficiency.
- Granular:Agglomerated particles flow through mechanical feeding infrastructure with reduced dust generation. Northern European cooperatives with centralized calf facilities drive uptake.
- Pelleted:Compressed formulations suit mechanical dispensers but face digestibility constraints in neonates under three weeks. Limited to specialized heifer rearing programs with extended feeding windows.
Milk powder leads volumes today; liquid formula is gaining share fastest.
End User:
Procurement scale and technical sophistication separate buyers, with advisory requirements varying sharply across farm types.
- Dairy Farms:Owner-operated enterprises with 50-500 cow herds purchase through agricultural supply cooperatives. Polish and Romanian expansion zones lack established distribution networks, creating whitespace for direct manufacturer relationships.
- Livestock Producers:Beef cattle operations and mixed farming enterprises apply replacers to orphan calf protocols. Volume concentration in Irish and UK pasture-based systems sustains regional formulation specialization.
- Research Institutions:Veterinary colleges and agricultural experiment stations validate novel ingredient digestibility. EFSA novel ingredient approval timelines constrain procurement flexibility for microbiome-modulating trials.
- Feed Manufacturers:Compound feed blenders integrate replacer bases into complete calf starter rations. REACH chemical registration requirements shape supplier qualification criteria for European sourcing.
Dairy farms dominate current procurement; livestock producers are expanding most quickly.
Composition:
Protein and fat specifications align with calf age, growth targets, and regulatory constraints on medicated additives.
- High Protein:Formulations exceeding 22% crude protein accelerate frame development in heifer replacement programs. EU Veterinary Medicines Regulation compliance pressures redirect R&D toward non-medicated high-protein alternatives.
- Low Protein:Economical 18% protein variants suit bull calf finishing where genetic potential is secondary to cost control. Commodity dairy ingredient swings compress margins here.
- High Fat:20% fat content replicates energy density of whole milk for cold-stress periods and early neonatal protocols. Whey protein concentrate availability from European dairy processors enables regional supply security.
- Essential Nutrients:Vitamin-mineral premixes and organic acid blends address specific deficiency risks without antibiotic residues. Botanical additive categories face extended EFSA safety evaluation periods.
High protein leads current formulation volumes; essential nutrients are climbing the fastest.
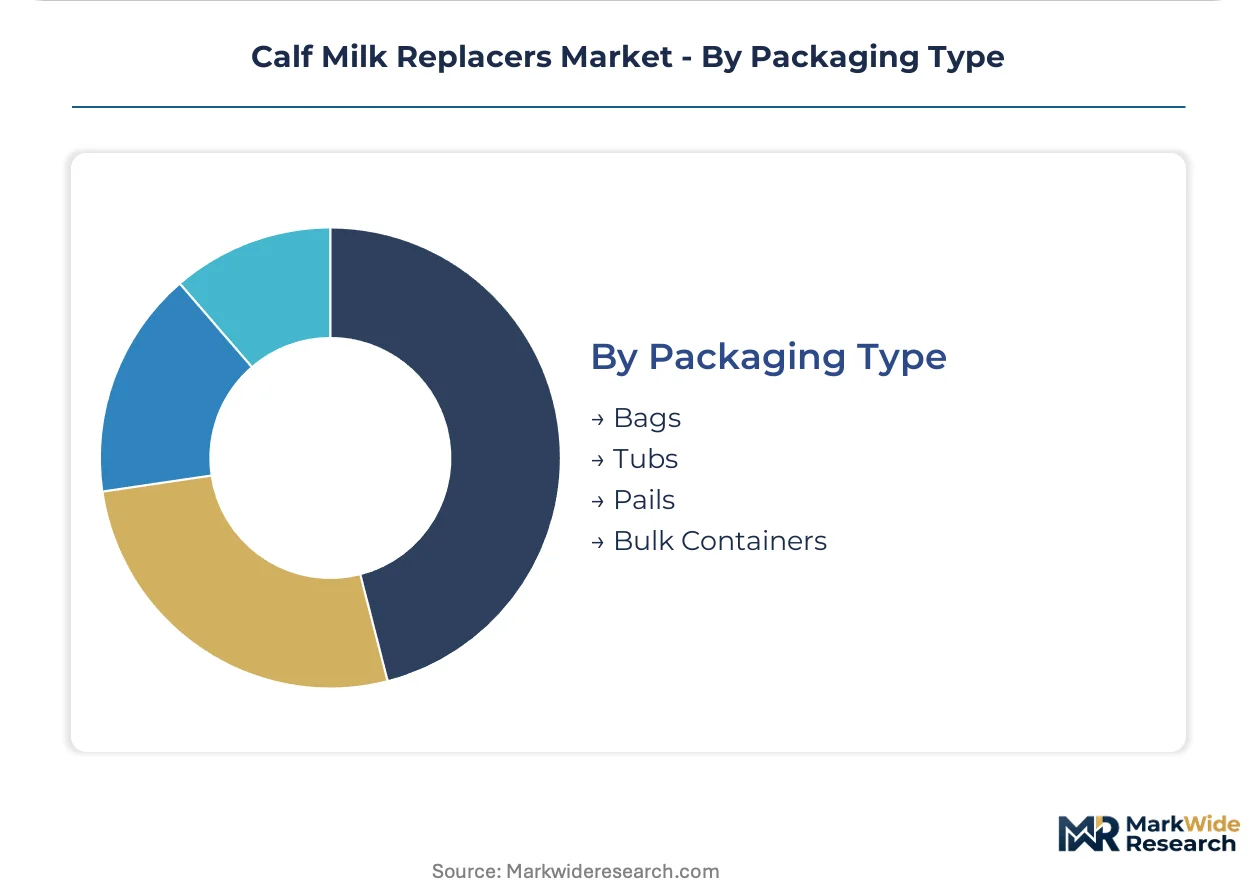
Packaging Type:
Unit sizing reflects buyer scale, storage hygiene standards, and mechanical handling infrastructure.
- Bags:Multi-wall paper or woven polypropylene sacks in 25-50kg units serve mid-scale operations with manual handling. EU Feed Hygiene Regulation microbiological thresholds enforce sealed-liner specifications for cross-border trade.
- Tubs:Rigid plastic containers with resealable lids protect hygroscopic powders in humid climates. Southeast Asian dairy expansion zones favor this format despite freight cost premiums.
- Pails:Smaller 10-20kg units target research institutions and specialty heifer programs requiring batch traceability. Blockchain-enabled provenance tracking is converging with this packaging tier.
- Bulk Containers:Tote bins and silo deliveries supply automated feeding systems at 500-plus cow operations. Long-term supply contracts with volume-tiered pricing displace spot purchasing in this segment.
Bags sustain the largest volume position; bulk containers are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting calf milk replacer manufacturing toward jurisdictions with streamlined feed safety protocols. The EU Feed Hygiene Regulation imposes stringent microbiological thresholds that elevate compliance costs for non-European suppliers. This divergence is concentrating production capacity within the European dairy belt while creating entry barriers for external competitors.
United States
Wisconsin and California dairy corridors drive concentrated demand for automated feeding-compatible liquid formulas. The FDA monitors antibiotic residue claims under medicated feed additive frameworks, constraining label positioning for imported products. Large-scale operations in California's Central Valley now procure through long-term supply contracts with volume-tiered pricing structures.
Netherlands
Intensive dairy operations in Gelderland province anchor European premium uptake for specialized milk powder formulations. The EU Veterinary Medicines Regulation enforces strict antibiotic residue limits that accelerate clean-label whey protein adoption. Dutch cooperatives are standardizing precision-formulated protocols across centralized calf-rearing facilities with mechanical feeding infrastructure.
Germany
Bavarian and North Rhine-Westphalian dairy clusters sustain demand for high-protein heifer replacement formulations. REACH chemical registration requirements shape supplier qualification criteria for European-sourced protein concentrates. Regional ingredient processors are redirecting surplus whey streams toward specialized calf nutrition lines to capture premium returns.
Ireland
Pasture-based beef and dairy systems in Munster and Leinster sustain regional formulation specialization for orphan calf protocols. EFSA novel ingredient approval timelines constrain procurement flexibility for microbiome-modulating trials. Irish dairy farm cooperatives maintain defensible procurement relationships with whey-based replacer specialists.
Poland
Underpenetrated dairy expansion zones in Greater Poland and Masovia lack established replacer distribution networks. The EU Green Deal is creating procurement preference for formulations with verified lifecycle emissions data. Growing herd sizes among 50-500 cow operations present whitespace for direct manufacturer relationships bypassing agricultural supply cooperatives.
Calf Milk Replacers Market Vendor Landscape
North American agribusiness conglomerates anchor one tier; European dairy-specialist processors hold differentiated positions through whey protein concentrate expertise. The vendor base stratifies across integrated grain-protein supply chains, precision nutrition technology providers, and regional whey processors. Three archetypes dominate: diversified agricultural conglomerates with captive ingredient sourcing, specialized calf nutrition formulators with automated feeding system integration, and cooperative-aligned dairy processors with surplus whey stream utilization. Competitive dynamics center on backward integration into protein concentrate supply and geographic expansion into underpenetrated Eastern European markets.
Within the diversified agribusiness tier, Cargill, Incorporated exemplifies integrated grain-protein supply chain leverage across North American dairy corridors. Trouw Nutrition occupies a position among precision nutrition technology providers targeting high-growth heifer programs with automated feeding calibration. Volac International Ltd. represents the cooperative-aligned archetype, anchoring whey-based formulation expertise within UK and Irish dairy farm networks. These three entities illustrate how competitive positioning depends on upstream control over critical protein inputs and downstream relationships with procurement-concentrated large-scale operations.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| CHS Inc. |
| Glanbia plc |
| Lactalis Group |
| Trouw Nutrition |
| Milk Specialties Global |
| Volac International Ltd. |
| Others |
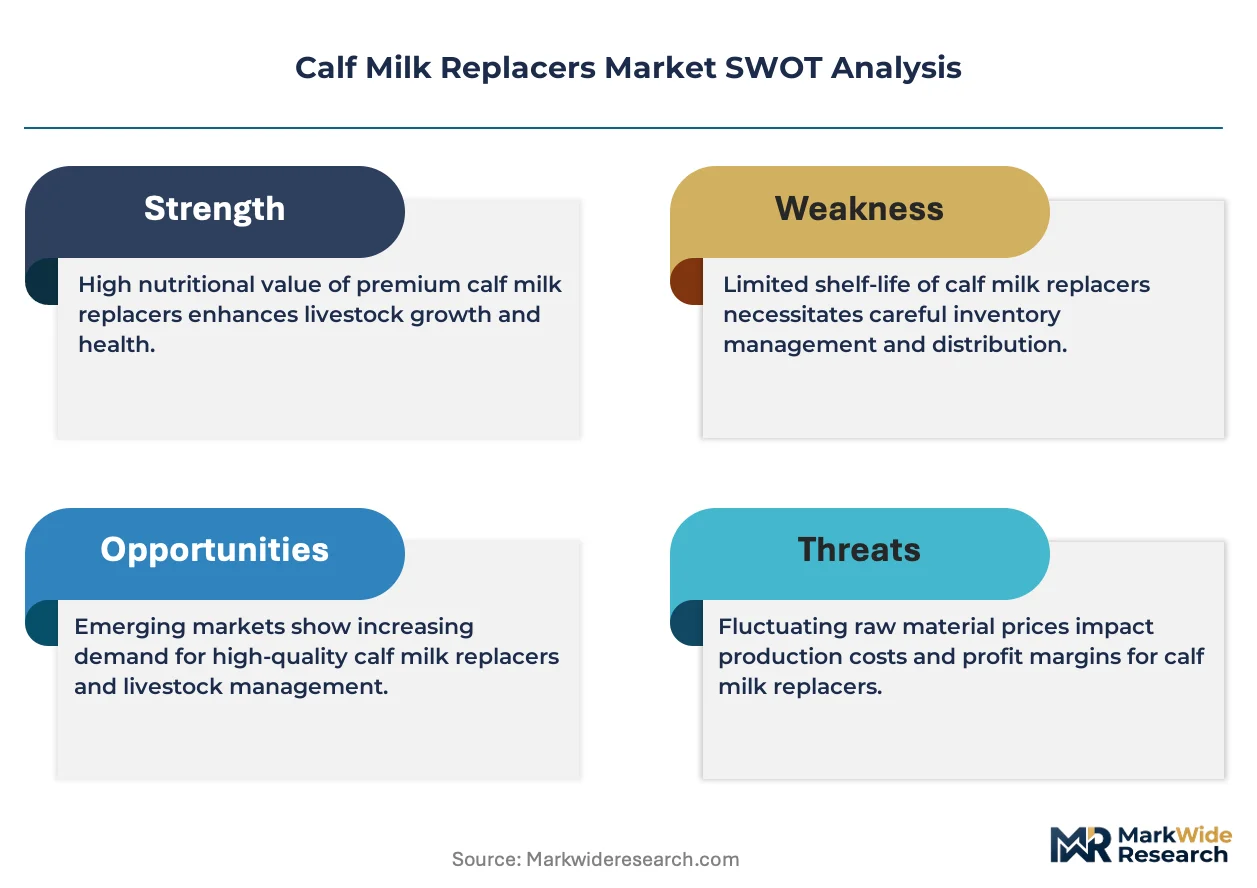
Supply Flow & Price Mechanics
Whey protein concentrate costs cascade through three distinct pricing tiers before reaching dairy farm buyers, with Northern European processor concentration enabling premium capture at the ingredient stage while automated feeding system compatibility commands margin premiums downstream. Skim milk powder commodity swings transmit volatility directly to spray-dried milk powder formulations, compressing margins for manufacturers without captive dairy ingredient sourcing or long-term offtake agreements with whey processors.
Pricing Analysis
Distributor margins of 15-25% separate bulk container deliveries to 500-plus cow operations from bagged-unit sales through agricultural supply cooperatives. Three-tier pricing structure across premium, standard, and economy levels reflects protein concentration, immunoglobulin retention certification, and automated feeding system compatibility. Pricing pressure stems from global dairy commodity volatility, particularly skim milk powder price swings that squeeze formulation margins. Mid-scale dairy farms with 50-500 cow herds exhibit highest price sensitivity, while Gelderland province operations with centralized calf facilities absorb premiums for labor-efficient liquid formulas.
Supply Chain Analysis
Direct-to-feed-manufacturer channels handle compound feed blender demand, while agricultural supply cooperatives distribute to owner-operated dairy farms across Polish and Romanian expansion zones. Geographic supply concentrates in the Netherlands, Ireland, and Germany, where dairy ingredient processors redirect surplus whey streams into specialized calf nutrition lines. Raw material dependencies center on whey protein concentrates, skim milk powder, and vegetable protein isolates. Single-source vulnerability from Northern European whey processor dominance creates concentration risk for high-quality protein concentrate supply. Distribution runs through long-term supply contracts with volume-tiered pricing at large-scale operations, displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Veterinary Medicines Regulation functions as a regulatory compounder, accelerating demand displacement from medicated feed additives toward clean-label whey and vegetable-protein formulations with documented microbiological safety profiles.
For Market Incumbents: To counter margin compression from skim milk powder price volatility, backward integration into whey protein concentrate supply secures cost-advantaged formulation inputs. Capacity addition in Poland and Romania captures whitespace from underpenetrated dairy expansion zones lacking established distribution networks. Certification investment in carbon footprint disclosure aligns procurement preference under the EU Green Deal. For New Entrants and Emerging Players: Begin with direct manufacturer relationships in Polish and Romanian 50-500 cow operations, bypassing agricultural supply cooperatives that dominate incumbent distribution. Blockchain-enabled provenance tracking opens premium channel positioning among research institutions and specialty heifer programs requiring batch traceability. Target livestock producer segments in Irish and UK pasture-based systems with orphan calf protocol specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA novel ingredient approval timelines constrain R&D productivity and extend product launch cycles. Long-term viability favors cooperative-aligned dairy processors with surplus whey stream utilization and automated feeding system integration capabilities. Watch for inflection signals in carbon footprint disclosure mandate enforcement intensity across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Processing | Captures premium returns from captive protein concentrate supply for high-growth heifer formulations. |
| Automated Feeding System Partnership | Secures long-term offtake contracts with Gelderland province and California Central Valley dairies. |
| Carbon Footprint Certification Program | Aligns with EU Green Deal procurement preferences for verified lifecycle emissions data. |
| Eastern European Distribution Buildout | Addresses whitespace in Polish and Romanian markets with growing herd sizes. |
| Botanical Additive R&D Investment | Accelerates EFSA-compliant alternatives to medicated feed additives facing regulatory compression. |
Methodological Framework
Coverage spans North America, Western Europe, and Eastern Europe, with primary inputs from each region combined with secondary validation. Interviews incorporated dairy farm operators, calf nutrition formulators, agricultural supply cooperative procurement managers, and veterinary college researchers. Secondary sources included EU Feed Hygiene Regulation compliance databases, FDA medicated feed additive filings, customs and trade data on dairy ingredient flows, and dairy cooperative annual disclosures. Bottom-up farm-level demand estimates triangulated against top-down processor capacity assessments.
Granularity-level modeling addressed product type, end user scale, protein-fat composition, and packaging format across national dairy production clusters. CAGRs derived from segment-level volume trajectories and value-per-unit trends throughout the forecast period. Industry-specific forecast inputs incorporated whey protein concentrate availability from European dairy processors and automated feeding system penetration rates in the Netherlands and Wisconsin.
Several conditions sit outside the modeled scope, including extreme dairy commodity price dislocations, trade policy disruptions affecting whey concentrate flows, and accelerated novel ingredient approval pathways. Forecasts reflect assumptions about regulatory enforcement continuity and protein sourcing stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market