
 Poultry Vitamin Market | 2026-2036
Poultry Vitamin Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Vitamin Market Analysis
Contract grower networks is unwinding purchasing autonomy from independent backyard operations across Southeast Asia and Latin America. DSM-Firmenich anchors its position through captive biotechnology assets for vitamin B12 fermentation. Cargill leverages its grain origination infrastructure to bundle vitamin premixes with base feed contracts. BASF competes on chemical synthesis scale for fat-soluble vitamins A and E.
Poultry vitamins comprise water-soluble and fat-soluble organic compounds formulated into premixes at inclusion rates typically ranging from grams to kilograms per ton of finished feed, manufactured through chemical synthesis or microbial fermentation to prevent deficiency disorders and support metabolic performance in meat and egg-producing birds. Vitamin E leads value contribution among fat-soluble categories due to its antioxidant role in stress mitigation and shelf-life extension of poultry products. Powder form dominates volume throughput in feed mill applications, while liquid vitamin concentrates gain traction in automated drinking water systems for pullet rearing and layer flocks.
The European Food Safety Authority evaluates additive efficacy and safety under Regulation 1831/2003, while China's Ministry of Agriculture and Rural Affairs enforces feed-grade vitamin quality standards through its GB certification system. Brazil's Ministry of Agriculture requires ANVISA-aligned import registrations for novel vitamin formulations. Stakeholders must track evolving maximum permitted levels for synthetic vitamins in organic poultry systems across multiple jurisdictions.
Market Dynamics
Contract grower networks across Southeast Asia and Latin America are dismantling purchasing autonomy from independent backyard operations, centralizing vitamin procurement decisions under processor-controlled protocols and standardizing inclusion rates across millions of birds.
Growth Catalysts
- EU Feed Additives Regulation:Mandatory efficacy documentation under Regulation 1831/2003 creates competitive moats for established premix formulators with existing registration portfolios.
- Brazil's integrated poultry belt:Vertical coordination between processors and contract growers standardizes vitamin protocols across millions of birds, locking in recurring premix volumes.
- Microbial fermentation:Biotechnology advances in vitamin B12 production reduce dependency on petrochemical feedstocks and improve yield consistency.
Market Restraints
- Petrochemical input volatility:Fat-soluble vitamins A and E rely on chemical synthesis pathways exposed to crude oil derivative price swings.
- Registration concentration:Brazil's ANVISA-aligned import requirements concentrate novel formulation approvals among established multinationals with dedicated regulatory affairs teams.
- Natural extract substitution:Plant-derived vitamin E from tocopherol-rich oils competes with synthetic forms in premium organic poultry systems.
Strategic Opportunities
- Drinking water automation:Liquid vitamin concentrates for automated dosing systems in pullet rearing operations bypass traditional feed mill channels.
- Organic certification tailwinds:Evolving maximum permitted levels for synthetic vitamins in organic systems create demand for fermentation-derived alternatives.
- Vietnam contract grower expansion:Processor-led vertical integration in the Mekong Delta standardizes vitamin protocols across previously fragmented backyard operations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in stability engineering for heat-sensitive vitamins during pelleting remains concentrated among legacy premix houses.
- Dual certification timelines:Parallel organic and conventional approval pathways extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Vitamin Market |
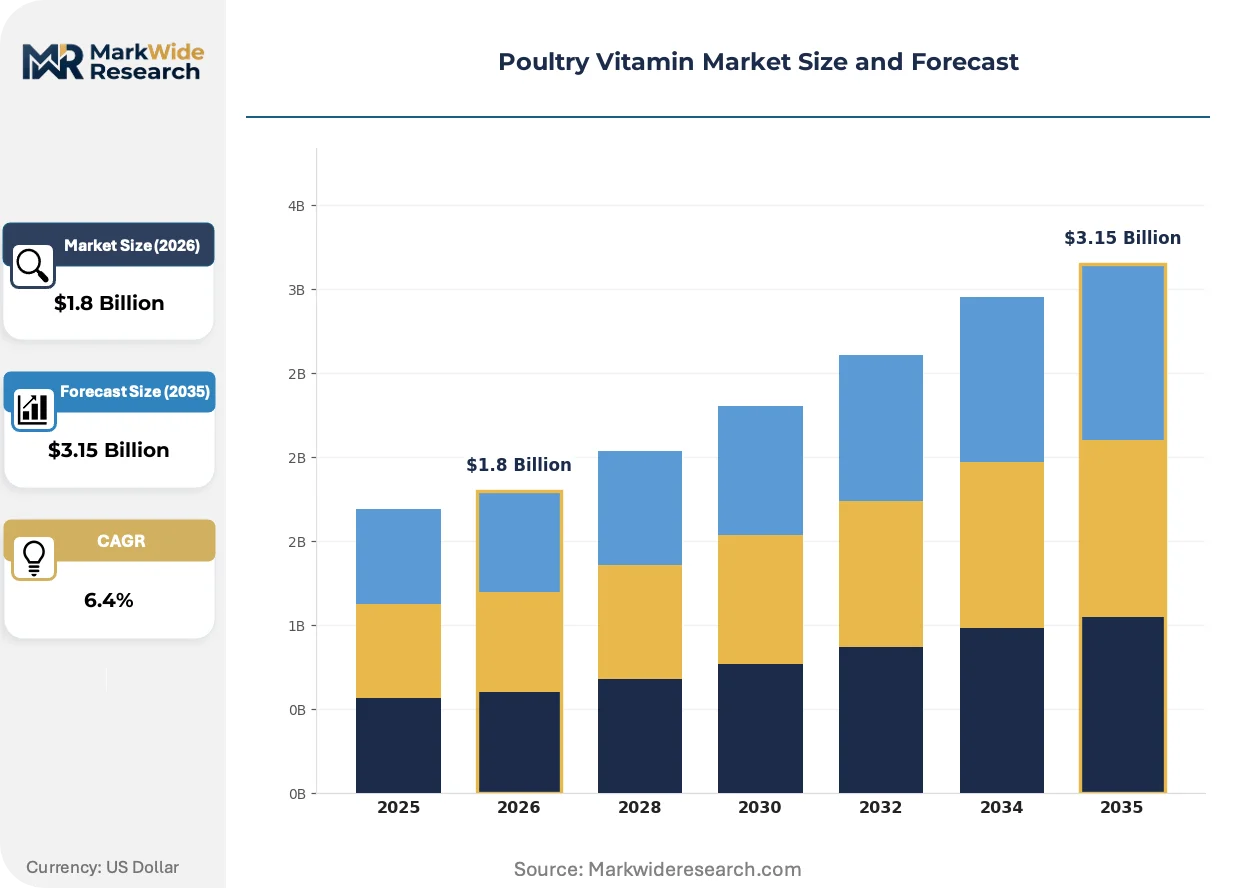
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vitamin Type: Vitamin A, Vitamin D, Vitamin E, Vitamin K Form: Powder, Liquid, Granule, Tablet End User: Poultry Farms, Feed Producers, Veterinary Clinics, Researchers Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | ADM, Adisseo, DSM-Firmenich, Evonik Industries, Cargill, BASF, Nutreco, Zagro, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Vitamin Market Emerging Trajectories
Precision livestock technologies and alternative production methods are fragmenting traditional premix value chains, creating parallel supply channels that bypass conventional feed mill intermediaries.
Encapsulation technology for heat-sensitive vitamins is fragmenting the premix manufacturing landscape. Layer and broiler operations with in-house pelleting capacity now source unprotected vitamin bases and apply protective coatings post-processing. This bypass of traditional premix houses compresses margins for toll manufacturers while enabling customized stability profiles matched to specific thermal processing regimes.
EFSA's expanding safety re-evaluations under the EU Feed Additives Regulation are compressing approved inclusion ranges for synthetic vitamins. The industrial consequence forces reformulation toward microbial fermentation alternatives and natural-source derivatives. Layer operations targeting export markets face the steepest compliance costs, accelerating partnerships with biotechnology suppliers possessing captive fermentation assets.
Procurement centralization under processor-controlled contract networks is displacing independent feed dealer channels. Smallholder operations in Indonesia and Colombia now receive premixes bundled under grower agreements rather than purchasing through agricultural supply cooperatives. This channel compression concentrates pricing power with integrated processors and locks out independent premix distributors from the fastest-expanding production bases.
Poultry Vitamin Market Segmentation
Poultry vitamin procurement channels diverge sharply between integrated operations and fragmented backyard systems. Segment boundaries determine whether products flow through feed mill intermediaries, processor-controlled distribution, or direct-to-farm digital platforms.
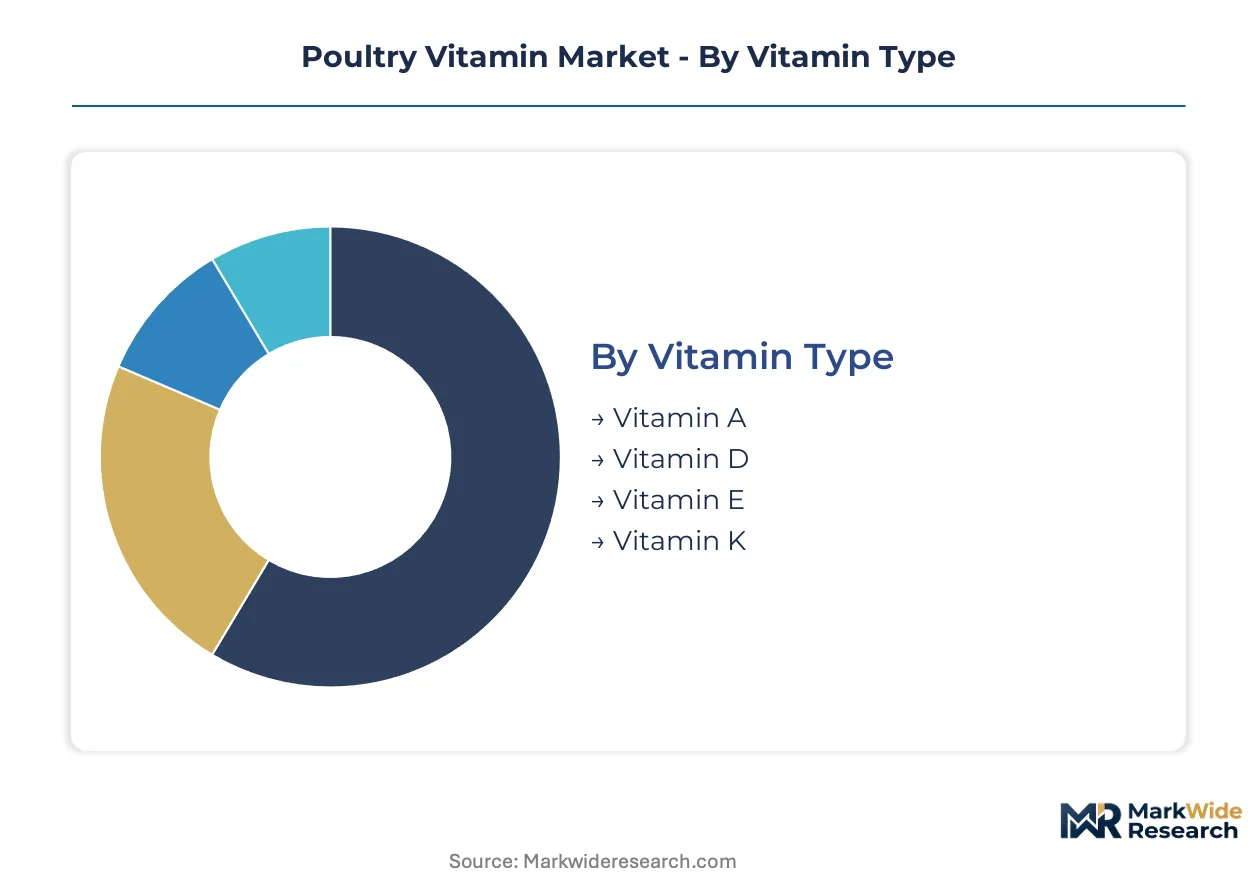
Vitamin Type:
Fat-soluble vitamins dominate premix value contribution through distinct synthesis pathways and stability profiles, while water-soluble categories concentrate in fermentation-derived supply chains.
- Vitamin A:Chemically synthesized retinol esters require petrochemical feedstocks and exhibit heat sensitivity during pelleting. Brazilian integrated processors standardize inclusion rates across contract grower networks to optimize feed conversion ratios in broiler operations.
- Vitamin E:Synthetic tocopherol acetate and natural-source tocopherols compete in antioxidant applications for stress mitigation and meat shelf-life extension. Layer operations targeting EU export markets face EFSA-driven reformulation toward fermentation alternatives as synthetic inclusion ranges compress.
- Vitamin D:Cholecalciferol from lanolin-derived precursors supports calcium metabolism and bone integrity in high-density housing systems.
- Vitamin K:Menadione derivatives remain essential for coagulation function in coccidiosis-stressed flocks.
By volume, Vitamin E leads. By growth pace, Vitamin A alternatives are climbing the fastest.
Form:
Physical presentation determines equipment compatibility across feed mill, drinking water, and direct-supplementation delivery systems.
- Powder:Free-flowing premix concentrates integrate into mash and pelleted feeds through standard batching equipment. Southeast Asian feed producers prefer powder forms for compatibility with existing mill infrastructure and lower transport costs per unit activity.
- Liquid:Concentrated suspensions enable automated dosing in drinking water systems for pullet rearing and layer flocks. Vietnamese contract grower networks are adopting liquid concentrates to bypass traditional feed mill channels and enable real-time inclusion adjustments.
- Granule:Agglomerated forms reduce dust exposure during handling and improve flowability in humid climates.
- Tablet:Compressed units serve veterinary clinic dispensing and research trial protocols requiring precise individual dosing.
Powder commands the largest volume share. Liquid forms are gaining share fastest through drinking water automation.
End User:
Customer scale and technical sophistication determine whether procurement flows through distributor networks or direct manufacturer relationships.
- Poultry Farms:Independent operations purchase through agricultural supply cooperatives or bundled grower agreements. Indonesia's smallholder sector is transitioning from dealer channels to processor-controlled premix supply under vertical coordination schemes.
- Feed Producers:Integrated compounders with in-house pelleting capacity source unprotected vitamin bases and apply proprietary encapsulation coatings post-processing.
- Veterinary Clinics:Clinical dispensing of therapeutic vitamin formulations targets deficiency correction in backyard flocks.
- Researchers:Academic and commercial trial operations require analytical-grade vitamin standards with documented purity certificates.
Feed producers dominate volume throughput. Poultry farms under contract grower expansion are expanding most quickly.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Manufacturer-to-processor relationships lock in recurring premix volumes through multi-year supply agreements. Brazil's integrated poultry belt concentrates procurement decisions under processor-controlled protocols, eliminating independent dealer margins.
- Wholesalers:Regional distributors serve mid-scale independent feed mills and cooperative purchasing groups across fragmented production bases.
- Specialty Stores:Agricultural supply retailers retain relevance in Colombia and other Latin American markets with dispersed smallholder populations.
- Online Retail:Digital platforms emerge for specialty vitamin formulations and organic-certified alternatives targeting niche segment demand.
Direct sales anchor volume. Online retail channels show the steepest expansion trajectory among emerging procurement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos Port complex underwrites Brazil's dominance in poultry vitamin logistics, handling soybean meal exports that anchor premix formulation supply chains across South America's integrated poultry belt.
Brazil
Contract grower networks in São Paulo and Paraná standardize vitamin protocols across millions of birds under processor-controlled procurement. ANVISA-aligned import registrations concentrate novel formulation approvals among established multinationals with dedicated regulatory affairs teams. The southern integrated poultry belt locks in recurring premix volumes through multi-year supply agreements between grain origination infrastructure and compound feed operations.
United States
Midwest feed mill consolidation drives centralized vitamin procurement decisions across Iowa and Arkansas broiler operations. USDA's Food Safety and Inspection Service coordinates with FDA on feed additive oversight, while EPA regulations shape chemical synthesis pathways for fat-soluble vitamins. The Delmarva Peninsula cluster maintains specialized premix formulation capacity serving Atlantic seaboard layer operations targeting export markets.
China
Shandong Peninsula feed producers expand microbial fermentation capacity for vitamin B12 to reduce petrochemical dependency. The Ministry of Agriculture and Rural Affairs enforces GB certification standards for feed-grade vitamin quality through provincial inspection regimes. Yangtze River Delta integrators are adopting automated drinking water systems for pullet rearing, creating demand for liquid vitamin concentrates outside traditional feed mill channels.
Germany
EFSA's expanding safety re-evaluations under Regulation 1831/2003 compress approved inclusion ranges for synthetic vitamins in layer operations targeting EU export markets. Lower Saxony's compound feed sector leads reformulation toward fermentation-derived alternatives as synthetic tocopherol ranges contract. Bavarian biotechnology suppliers possess captive fermentation assets serving organic certification tailwinds across European premium poultry systems.
Vietnam
Mekong Delta processor-led vertical integration standardizes vitamin protocols across previously fragmented backyard operations. The country's national agricultural regulator enforces feed additive quality standards aligned with ASEAN harmonization initiatives. Ho Chi Minh City logistics hubs distribute liquid vitamin concentrates for automated dosing systems bypassing traditional feed mill infrastructure.
Poultry Vitamin Market Vendor Landscape
Listed leaders compete with private specialists across registration portfolios and fermentation asset ownership. The vendor base clusters around three strategic archetypes: integrated nutrition houses with grain origination infrastructure, biotechnology specialists with captive fermentation capacity, and chemical synthesis scale operators for fat-soluble categories. Market structure rewards backward integration into vitamin manufacturing and multi-jurisdiction regulatory expertise. Consolidation pressures concentrate among toll premix manufacturers as encapsulation technology enables layer and broiler operations to source unprotected vitamin bases directly.
Within the biotechnology tier, DSM-Firmenich and Evonik Industries exemplify archetypes built on microbial fermentation assets for water-soluble categories. BASF occupies a position representing chemical synthesis scale for fat-soluble vitamins A and E. These three anchors illustrate how competitive positioning fragments between petrochemical-dependent synthesis pathways and fermentation-derived alternatives reshaping supply security calculations.
| Leading Market Players |
|---|
| ADM |
| Adisseo |
| DSM-Firmenich |
| Evonik Industries |
| Cargill |
| BASF |
| Nutreco |
| Zagro |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Natural-source tocopherol substitution for synthetic Vitamin E is redrawing supply geography toward Malaysian and Indonesian palm oil processing clusters while compressing price premiums for fermentation-derived alternatives. This input shift simultaneously elevates working capital requirements for processors managing tocopherol-rich oil inventories and intensifies margin pressure on petrochemical-dependent synthesis pathways.
Pricing Analysis
Volume-discount tiering separates contract grower networks purchasing multi-ton premix volumes from independent backyard operations buying through agricultural supply cooperatives. Price differentiation hinges on certification grade—organic-compliant formulations command substantial premiums over conventional synthetic grades—and vertical integration depth, with grain-origination bundling reducing per-unit vitamin costs. Cost compression in standard synthetic grades is intensifying because Brazilian and Vietnamese processor consolidation eliminates independent dealer margins. Contract grower networks exhibit lowest price sensitivity due to bundled supply agreements, while Indonesian smallholders remain most exposed to spot market volatility.
Supply Chain Analysis
Strategic stockpiling of petrochemical feedstocks for fat-soluble vitamin synthesis contrasts with just-in-time fermentation substrate management for water-soluble categories. Supply concentrates in China for microbial fermentation capacity, Germany for chemical synthesis scale, and Brazil for integrated premix formulation. Raw material dependencies encompass crude oil derivatives for retinol esters, corn-derived dextrose for fermentation substrates, and palm fatty acid distillate for natural tocopherol extraction. Single-source vulnerability in Vitamin B12 fermentation strains poses structural risk. Distribution runs through processor-controlled direct sales channels in vertically integrated poultry belts, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poultry vitamin market sits in a cyclical recovery phase driven by restocking intensity across Southeast Asian contract grower networks following disease-induced destocking periods.
For Market Incumbents: Compound registration portfolio depth under EFSA and ANVISA frameworks to create competitive moats against biotechnology specialists encroaching on synthetic vitamin share. Prioritize captive fermentation asset acquisition in Germany and China to secure supply independence from petrochemical price volatility. Defend margin position by locking multi-year supply agreements with Brazil's integrated processors before novel formulation entrants secure regulatory approvals. For New Entrants and Emerging Players: EU organic certification fast-track offers the most penetrable entry vector as EFSA-driven synthetic inclusion range compression forces reformulation demand. Target Vietnam's Mekong Delta contract grower expansion with liquid vitamin concentrate formulations bypassing established feed mill channels. Pursue direct-to-farm digital platforms for specialty organic-certified alternatives where processor-controlled distribution remains underdeveloped. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotechnology specialists with captive fermentation assets over petrochemical-dependent synthesis operators. Long-term viability across the projection horizon rests on backward integration into vitamin manufacturing and multi-jurisdiction regulatory expertise. Acquisition target archetype: mid-scale fermentation houses with existing EFSA registration portfolios. Signal to watch: ANVISA approval velocity for novel microbial-derived formulations as inflection indicator for synthetic substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive Vitamin B12 production reduces petrochemical dependency and improves yield consistency. |
| EU Organic Certification Pathway | EFSA-driven synthetic inclusion compression creates premium positioning for fermentation-derived alternatives. |
| Direct-to-Farm Digital Platform Launch | Bypasses processor-controlled channels in Vietnam and Indonesia's fragmented backyard sectors. |
| Multi-Jurisdiction Registration Portfolio | ANVISA-aligned approvals in Brazil and GB certification in China lock out late entrants. |
| Liquid Concentrate Formulation Development | Automated drinking water systems in pullet rearing operations bypass traditional feed mill intermediaries. |
Methodological Framework
Cross-validation between primary interviews with feed mill procurement directors, poultry processor nutritionists, regulatory affairs specialists at premix formulators, and veterinary clinic dispensing managers anchors the qualitative findings. Secondary validation draws from EFSA additive re-evaluation databases, ANVISA import registration filings, Chinese Ministry of Agriculture GB certification records, and Brazilian customs trade data. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across poultry production economics.
Sensitivity analysis around petrochemical feedstock price trajectories and fermentation yield assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions encompass vitamin type, physical form, end-user scale, and distribution channel structure, with additional granularity on organic versus conventional certification tiers. CAGRs derive from elasticity-adjusted demand projections incorporating broiler feed conversion optimization targets and layer flock mortality reduction protocols.
Underlying assumptions cover sustained contract grower network expansion, stable regulatory maximum permitted levels, and continued petrochemical price volatility, with deviation risk concentrated in EFSA safety re-evaluation outcomes and ANVISA approval timelines for novel formulations. Revision becomes warranted when synthetic vitamin inclusion range compression accelerates beyond modeled thresholds or fermentation yield breakthroughs disrupt cost parity calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Animal Probiotics Market