
 Europe Organic Aquaculture Market | 2026-2036
Europe Organic Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Aquaculture Market Intelligence
Market Dynamics
Specialty supermarkets and premium foodservice operators is reorganizing procurement priorities toward traceable organic seafood. Aqualande leverages its French production base to supply major retail banners across Western Europe. Glenarm Organic Salmon Limited anchors the United Kingdom's premium salmon segment through controlled estuary operations. Biofisch GmbH specializes in German-certified organic trout, competing on feed transparency and local processing scale.
Product and Segment Structure
Europe organic aquaculture comprises finfish, shellfish, and aquatic plant cultivation under certified organic protocols prohibiting synthetic inputs, genetically modified feeds, and high-density stocking rates, with production cycles typically spanning 18 to 36 months depending on species. Fish dominates current output volumes, while seaweed cultivation represents the fastest-expanding category as coastal nations invest in integrated multi-trophic systems. EU Organic certification commands the widest retail acceptance, though Naturland and Demeter standards capture premium positioning in German-speaking markets where buyers pay explicit premiums for stricter welfare and environmental criteria.
Regulatory Environment
The EU Organic Regulation 2018/848, enforced by national competent authorities in each member state, mandates full traceability from hatchery to retail shelf and restricts conventional feed conversion ratios. EFSA evaluates additive safety for organic aquafeeds, while national regulators such as France's DGAL and Germany's BLE conduct farm inspections and certification audits. Stakeholders must monitor the ongoing revision of organic aquaculture-specific guidelines within the EU Green Deal framework, as stricter nutrient discharge limits and habitat protection rules will reshape site licensing and production economics.
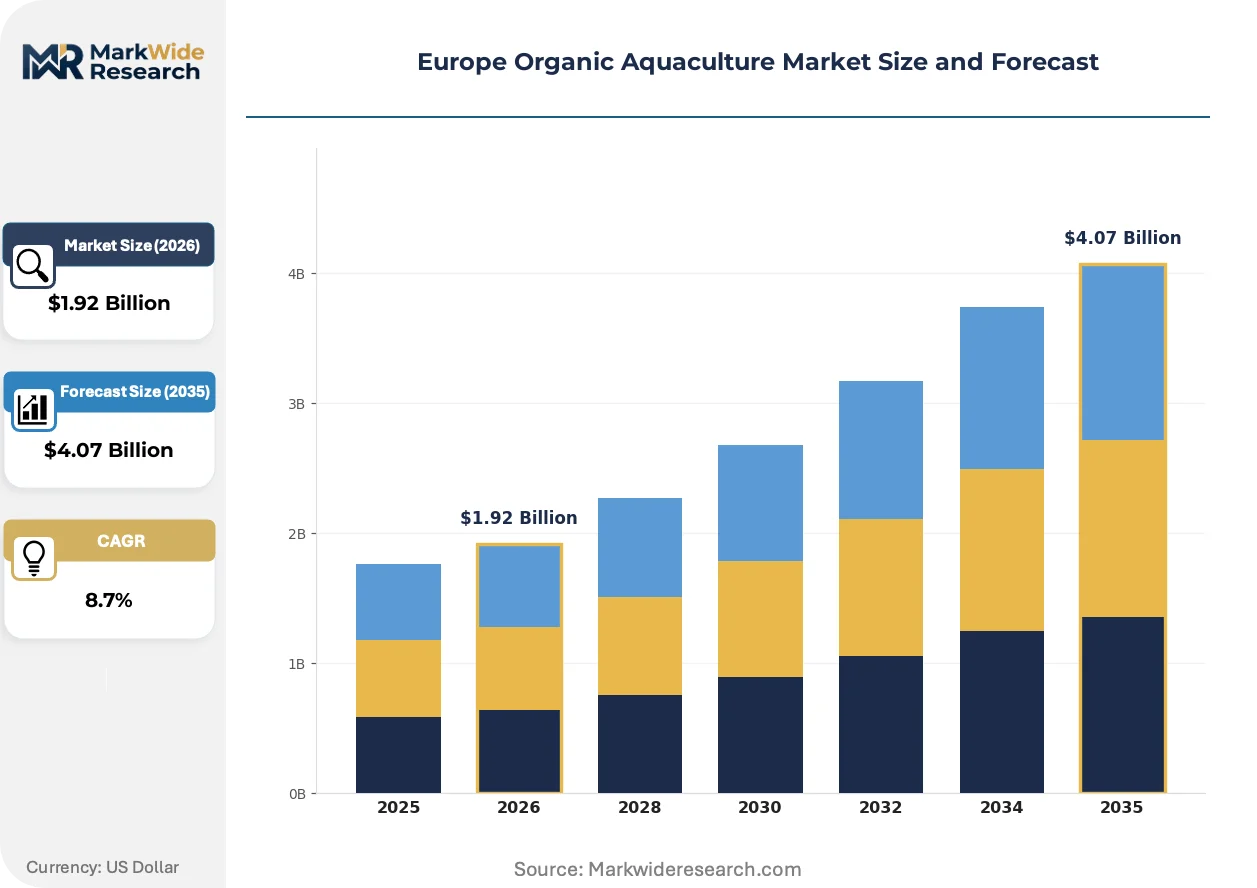
Market Dynamics
EU Organic Regulation 2018/848 is compressing conventional feed sourcing options across European aquaculture, forcing producers to rebuild supply chains around traceable marine and agricultural inputs with full batch documentation from hatchery to retail.
Growth Catalysts
- EU Green Deal nutrient discharge limits:Coastal nations are accelerating site licensing for integrated multi-trophic systems that combine finfish with seaweed cultivation, creating certified organic output with lower environmental monitoring costs.
- German retail procurement:Premium supermarket banners in Bavaria and Baden-Württemberg now mandate Naturland or Demeter certification for shelf placement, pulling volume toward stricter welfare standards.
- Recirculating aquaculture systems:Closed-loop water treatment technology enables inland organic trout production in regions previously dependent on coastal flow-through sites.
Market Restraints
- Marine ingredient cost volatility:Fishmeal and fish oil prices fluctuate with Peruvian and Chilean anchovy quotas, squeezing organic feed margins where synthetic alternatives are prohibited.
- Norwegian smolt supply concentration:Three controlled-environment hatcheries dominate certified organic salmon egg and juvenile supply, creating bottleneck risk for expansion outside existing contract relationships.
- Extended production cycles:Lower stocking density requirements under EU Organic certification stretch grow-out periods to 24-36 months, locking working capital and reducing annual harvest turns.
Strategic Opportunities
- Eastern European retail penetration:Polish and Romanian premium foodservice channels show nascent demand for certified organic seafood with limited domestic supply, creating import substitution potential for French and German producers.
- Seaweed biostimulant convergence:Extracts from organically farmed kelp and dulse are displacing synthetic fertilizers in adjacent agricultural markets, opening dual-revenue stream models for coastal operators.
- EU Carbon Border Adjustment Mechanism:Upcoming embodied carbon tracking on imported seafood creates competitive shelter for European organic producers with documented lower feed-chain emissions.
Industry Challenges
- Veterinary pharmacopeia limitations:Restricted treatment options under organic protocols extend mortality recovery timelines, demanding specialized aquatic health staff scarce in continental Europe.
- Multi-standard audit fatigue:Simultaneous EU Organic, Naturland, and retailer-specific certification requirements create overlapping inspection schedules and documentation burdens for mid-scale farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Aquaculture Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $4.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Seaweed, Mollusks Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Restaurants, Supermarkets, Direct Consumers, Foodservice Certification: EU Organic, USDA Organic, Naturland, Demeter |
| Companies Covered | Aqualande, Blackshell Farm Ltd, Biofisch GmbH, Cromaris D.D, Cultimer France Producteurs Associes, Glenarm Organic Salmon Limited, Kaerhede Dambrug ApS, Kush Shellfish, Mowi ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Aquaculture Market Strategic Shifts & Innovations
Automation and alternative feed chemistry are compressing the cost gap between organic and conventional aquaculture, while regulatory pressure on marine ingredient traceability is rewriting procurement relationships across the value chain.
Single-cell protein derived from methane-oxidizing bacteria is displacing fishmeal in organic-certified feed formulations. Norwegian and Danish feed mills are trialing these inputs at commercial scale. The technology is displacing traditional marine ingredient dependence for producers seeking EU Organic compliance without South Atlantic supply exposure.
EFSA's expanded additive safety evaluations under the EU Organic Regulation are tightening the approved substance list for organic aquafeeds. French operators face reformulation deadlines for mineral premixes previously grandfathered under older standards. Smolt producers in Brittany and Scotland are accelerating trials of algae-based pigment alternatives to meet stricter carotenoid sourcing rules.
Direct contracting between French organic salmon farms and Parisian restaurant groups is shortening the traditional wholesale auction channel. Specified volume commitments with fixed seasonal pricing replace spot market purchases for high-end establishments. This pattern concentrates most visibly in Île-de-France and Rhône-Alpes, where chef-owned groups prioritize provenance documentation for menu storytelling.
Europe Organic Aquaculture Market Segmentation
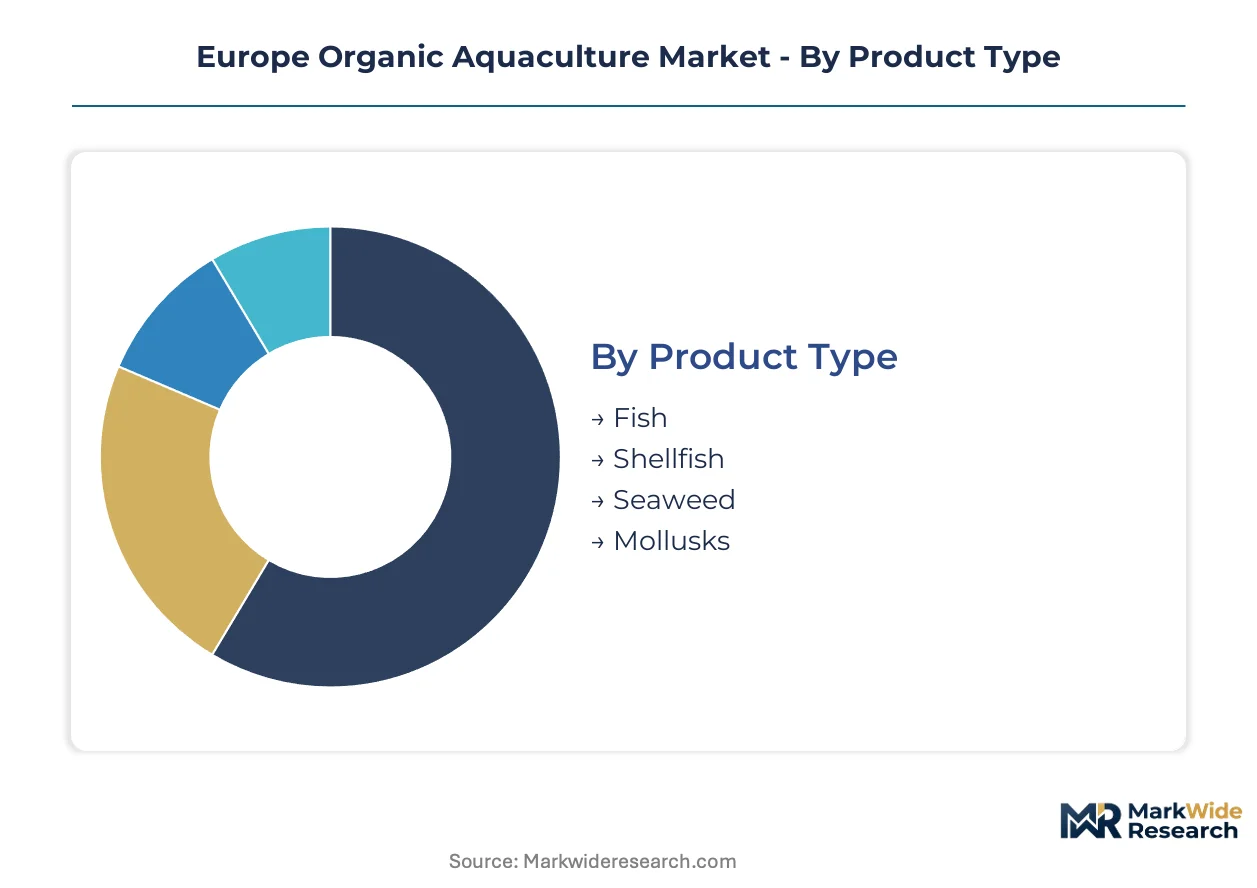
Organic aquaculture segmentation in Europe reflects divergent certification burdens and channel economics. Producers optimize species mix and distribution pathways based on regional regulatory enforcement intensity and retail procurement specifications.
Product Type:
EU Organic Regulation 2018/848 imposes distinct feed traceability and stocking density rules across species categories, reshaping production economics and harvest cycle planning.
- Fish:Salmon and trout dominate certified output under controlled-environment protocols with 24-36 month grow-out cycles. French and Norwegian farms supply premium retail banners across Germany and the United Kingdom, constrained by Norwegian smolt supply concentration and extended capital lock-up periods.
- Shellfish:Mussels and oysters cultivated in coastal integrated multi-trophic systems face lower feed input costs but stricter habitat protection licensing under EU Green Deal frameworks. Brittany and Scottish loch operations serve Parisian and London restaurant groups seeking provenance documentation.
- Seaweed:Kelp and dulse extraction for biostimulant markets is climbing the fastest as coastal nations invest in nutrient discharge-compliant production models.
- Mollusks:Clam and scallop operations remain fragmented across Mediterranean and Atlantic sites with limited certified organic scale.
Established volume favors Fish; emerging adoption favors Seaweed.
Distribution Channel:
Channel selection determines margin capture and certification audit frequency, with direct and digital pathways reducing intermediary documentation burdens.
- Retail:German premium supermarket banners in Bavaria and Baden-Württemberg mandate Naturland or Demeter certification for shelf placement, concentrating procurement toward traceable supply chains with full batch documentation.
- Wholesale:Traditional auction channels in Boulogne and Peterhead face displacement as French farms contract directly with restaurant groups for specified volume commitments with fixed seasonal pricing.
- E-commerce:Direct-to-consumer platforms enable smaller Brittany and Scottish producers to bypass consolidated wholesale margins.
- Direct Sales:Chef-owned groups in Île-de-France and Rhône-Alpes prioritize contracted farm relationships for menu storytelling and provenance verification.
Margin compression hits Wholesale; margin expansion concentrates in Direct Sales.
End User:
End-user procurement specifications split between provenance-demanding foodservice operators and price-sensitive retail consumers, with certification tier determining addressable market.
- Restaurants:Parisian and London chef-owned groups drive demand for EU Organic and stricter Naturland-certified species, accepting premium pricing for documented hatchery-to-table traceability.
- Supermarkets:French and German premium retail chains expand organic seafood shelf space while imposing additive disclosure and welfare audit requirements.
- Direct Consumers:Subscription box models and farmers' market channels serve urban clusters in Copenhagen, Amsterdam, and Vienna with limited certified supply.
- Foodservice:Institutional catering contracts in Nordic countries specify EU Organic compliance for public procurement tenders.
Procurement sophistication concentrates in Restaurants; volume scale concentrates in Supermarkets.
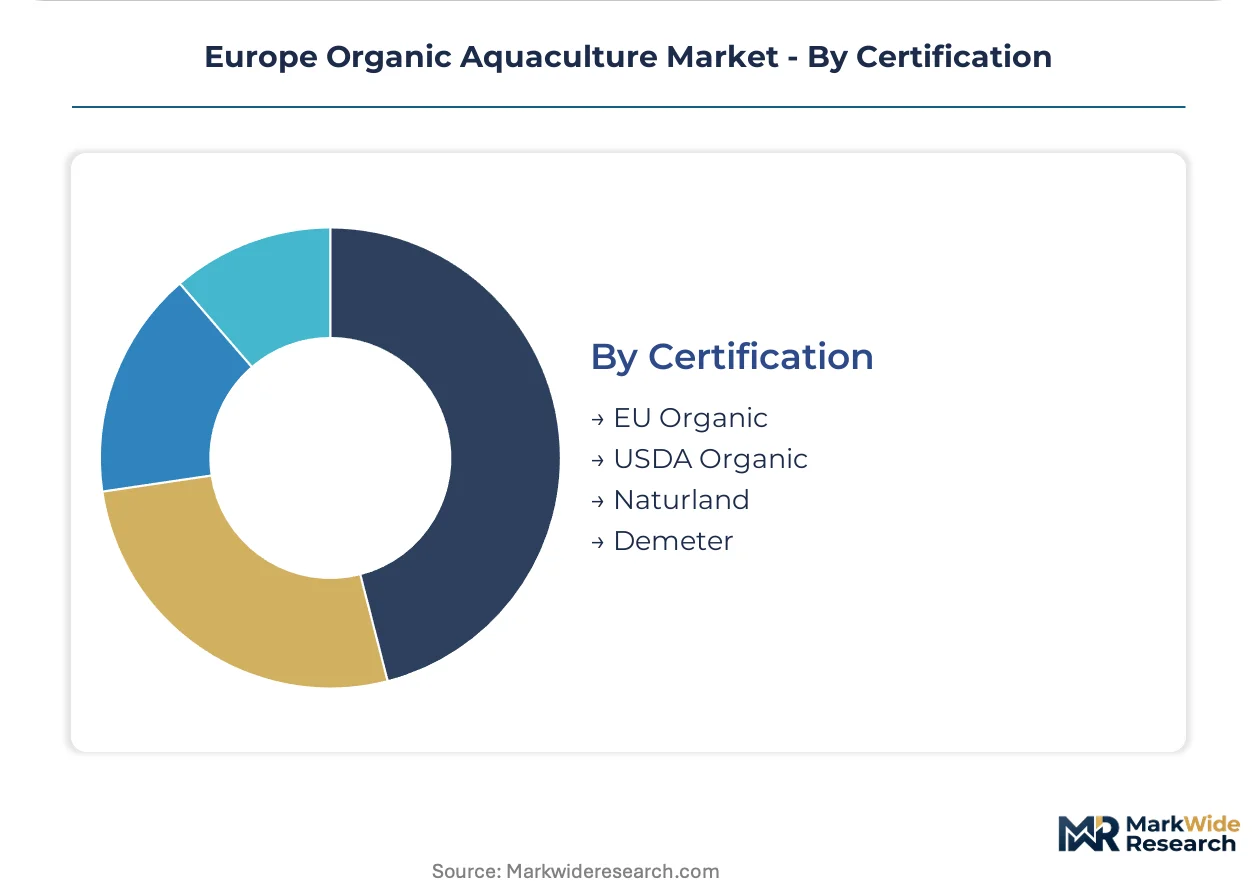
Certification:
Certification tier selection shapes feed sourcing options, veterinary treatment protocols, and achievable price premiums across member state enforcement environments.
- EU Organic:The baseline standard commands widest retail acceptance across France, Germany, and the United Kingdom, mandating full traceability and prohibiting synthetic inputs and genetically modified feeds.
- Naturland:German-speaking markets pay explicit premiums for this stricter welfare and environmental standard, requiring additional habitat protection and extended stocking density protocols.
- Demeter:Biodynamic certification captures niche premium positioning in Austrian and Swiss retail with mandatory soil association and lunar cycle requirements.
- USDA Organic:Export-oriented Irish and Scottish salmon farms maintain this parallel certification for North American market access.
Regulatory alignment favors EU Organic; premium positioning favors Naturland.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian organic salmon farms supply premium retail banners across Germany and France through established cold-chain corridors, while French producers export directly to London and Paris restaurant clusters under fixed-volume contracts.
Norway
Three controlled-environment hatcheries dominate certified organic smolt supply, constraining expansion outside existing contract relationships. The Norwegian Food Safety Authority enforces strict traceability protocols aligned with EU Organic Regulation 2018/848. Coastal fjord operations in Nordland and Trøndelag concentrate grow-out capacity for German supermarket procurement.
France
Parisian chef-owned groups in Île-de-France drive contracted farm relationships for menu storytelling and provenance documentation. France's DGAL conducts farm inspections and certification audits under delegated EU authority. Brittany operations serve both domestic retail and cross-channel export to London foodservice channels.
Germany
Premium supermarket banners in Bavaria and Baden-Württemberg mandate Naturland or Demeter certification for organic seafood shelf placement. Germany's BLE coordinates national enforcement of EU Organic standards with additional state-level welfare inspections. Baden-Württemberg trout farms leverage recirculating aquaculture systems for inland production.
United Kingdom
Scottish loch operations supply London restaurant groups seeking EU Organic and parallel Naturland-certified species. The Food Standards Agency implements retained EU organic regulations with post-Brexit certification equivalence arrangements. Glenarm Organic Salmon Limited anchors Northern Ireland's premium salmon segment through controlled estuary operations.
Denmark
Nordic institutional catering contracts specify EU Organic compliance for public procurement tenders. The Danish Veterinary and Food Administration enforces additive safety evaluations for organic aquafeeds. Kattegat Strait mussel farms integrate with finfish operations in emerging multi-trophic systems.
Europe Organic Aquaculture Market Key Industry Players
Listed leaders compete with private specialists across certification tier and channel access. The vendor base fragments across family-owned coastal farms, integrated salmon majors, and feed-specialist cooperatives. Three archetypes dominate: integrated multi-species operators controlling hatchery-to-retail chains, regional trout specialists competing on local processing scale, and seaweed-focused ventures capturing biostimulant dual-revenue streams. Capacity expansion and direct restaurant contracting represent the dominant competitive moves.
Within the integrated salmon tier, Mowi ASA and Glenarm Organic Salmon Limited exemplify divergent scale strategies, while Aqualande occupies a position bridging French production base with Western European retail distribution. Biofisch GmbH sits within the regional specialist archetype, competing on German-certified feed transparency. These three entities represent the spectrum from multinational listed structure to private domestic focus.
| Leading Market Players |
|---|
| Aqualande |
| Blackshell Farm Ltd |
| Biofisch GmbH |
| Cromaris D.D |
| Cultimer France Producteurs Associes |
| Glenarm Organic Salmon Limited |
| Kaerhede Dambrug ApS |
| Kush Shellfish |
| Mowi ASA |
| Others |
Cost & Logistics Intelligence
EU Organic Regulation 2018/848 gates both supply qualification and price differentiation simultaneously, mandating full traceability from hatchery to retail shelf while prohibiting synthetic inputs that would otherwise compress feed costs. This regulatory architecture forces producers to absorb premium marine ingredient expenses that conventional operations avoid, creating three distinct price tiers tied to certification burden rather than species alone.
Pricing Analysis
Current-generation EU Organic certification commands premium positioning against prior-generation conventional aquaculture and next-generation integrated multi-trophic systems still scaling proof-of-concept. Three-tier pricing structure across premium, standard, and economy levels separates Naturland-certified salmon from baseline EU Organic trout and uncertified conventional imports. Pricing pressure stems from Peruvian anchovy quota volatility squeezing organic feed margins. Supermarket procurement teams in Germany exhibit highest price sensitivity, while Parisian chef-owned groups accept documented provenance premiums.
Supply Chain Analysis
Container availability constraints on South Atlantic fishmeal trade lanes elevate inbound logistics costs for European feed mills dependent on Chilean and Peruvian marine ingredient inputs. Supply concentrates in Norway, France, and Germany, with Norwegian hatcheries controlling certified organic smolt supply. Raw material dependencies center on fishmeal, fish oil, and single-cell protein alternatives. Single-source vulnerability runs through Norwegian controlled-environment hatcheries. Distribution runs through premium retail banners and direct restaurant contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aquatic health expertise represents the critical capability gap constraining organic aquaculture expansion, as restricted veterinary pharmacopeias under organic protocols demand staff scarce across continental Europe.
For Market Incumbents: Fortify smolt supply security through captive hatchery investments or long-term offtake contracts with Norwegian controlled-environment facilities, insulating against bottleneck risk from three-dominant-supplier concentration. Deepen backward integration into single-cell protein feed inputs to reduce South Atlantic marine ingredient exposure. For New Entrants and Emerging Players: Anchor in Eastern European foodservice white space, specifically Polish and Romanian premium channels with nascent organic seafood demand and limited domestic certified supply. Seaweed biostimulant dual-revenue models offer lower capital intensity entry points than finfish operations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recirculating aquaculture system deployments as inland organic trout production scales. Target acquisition candidates include regional trout specialists with established Naturland certification and coastal integrated multi-trophic operators capturing biostimulant revenue streams. Monitor EU Green Deal nutrient discharge limit implementation timelines as inflection signal for site licensing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Capacity Expansion | Reduces Norwegian smolt supply bottleneck constraining French and Scottish grow-out operations. |
| Single-Cell Protein Feed Integration | Displaces volatile South Atlantic fishmeal dependence for EU Organic compliance. |
| Direct Restaurant Contracting | Captures margin expansion bypassing traditional wholesale auction channels in Boulogne. |
| Seaweed Biostimulant Diversification | Opens dual-revenue streams from kelp extracts displacing synthetic agricultural fertilizers. |
| Naturland Certification Investment | Unlocks Bavarian and Baden-Württemberg premium retail shelf placement mandates. |
Research Approach
Desk research of EU regulatory filings, EFSA additive safety evaluations, and national competent authority inspection protocols preceded structured interviews with organic aquaculture farm managers, feed mill procurement directors, premium supermarket category buyers, and Parisian restaurant group executive chefs. Secondary validation drew from EU Organic Regulation implementation guidance, DGAL and BLE enforcement reports, and trade flow documentation. Bottom-up production volume estimates triangulated against top-down retail channel value assessments.
Variance decomposition across species categories, certification tiers, and distribution channels shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included product type, certification standard, and end-user procurement sophistication. CAGRs derived from production capacity build-out timelines and retail shelf space expansion trajectories. Forecast inputs incorporated smolt supply constraints and EU Green Deal licensing velocity assumptions.
Material uncertainties — Peruvian anchovy quota fluctuations, EU organic aquaculture guideline revisions, and veterinary pharmacopeia amendments — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and marine ingredient price stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
North America Shrimp Feed Market