
 Animal Nutrition Market | 2026-2036
Animal Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Nutrition Market Analysis
Aquaculture is recalibrating procurement priorities across the Animal Nutrition Market as marine and inland farming operations scale output. Cargill leverages its aquafeed formulation capabilities to secure long-term supply contracts in coastal production zones. BASF SE anchors its position through precision fermentation technologies for amino acid production. DSM differentiates via its algae-based omega-3 platforms that reduce fishmeal dependency in salmon diets.
Animal nutrition encompasses the formulation and delivery of dietary inputs—proteins, lipids, vitamins, minerals, and functional additives—engineered to optimize growth rates, reproductive performance, and disease resistance in production animals and companion species. These formulations typically achieve target metabolizable energy densities between 2,800 and 3,200 kcal per kilogram for poultry and swine rations, with particle size distribution controlled below 1.5 millimeters for broiler starter feeds to maximize nutrient absorption. Feed additives command concentrated margin pools as enzyme and probiotic categories attract premium pricing from livestock integrators seeking feed conversion ratio improvements. Premix volumes are expanding fastest in aquaculture as shrimp and salmon producers adopt species-specific micronutrient protocols. Nutritional supplements for companion animals occupy a stable, high-margin tier as pet owners prioritize veterinary-recommended therapeutic diets.
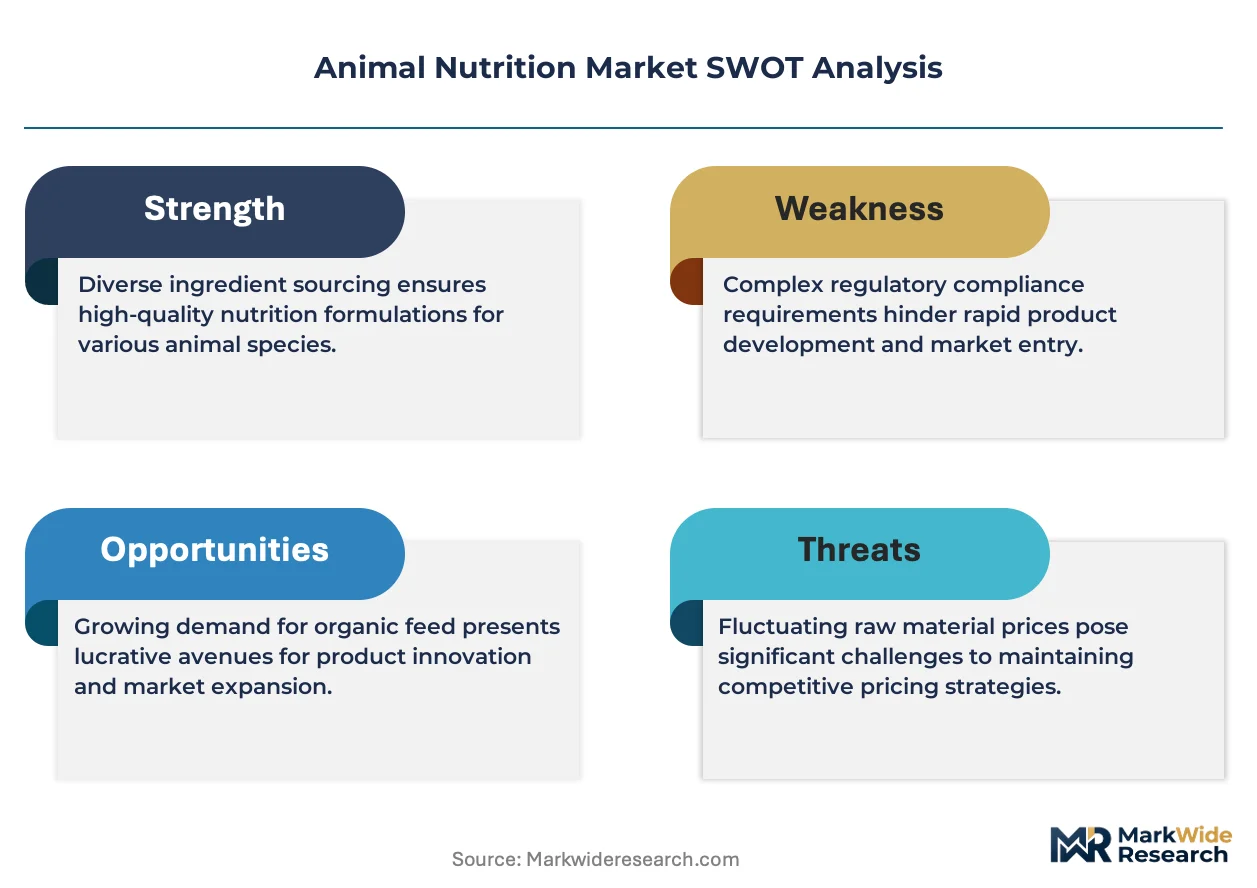
The FDA regulates feed additive safety through the Food Additive Petition process, while the EU Green Deal and REACH framework restrict antibiotic growth promoters and certain chemical residues in imported feedstuffs. USDA organic certification requirements shape ingredient sourcing for premium livestock and pet food channels, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving mycotoxin thresholds and alternative protein approval pathways as regulatory divergence between North American and European jurisdictions accelerates formulation complexity.
Market Dynamics
The EU F-Gas Regulation is compressing manufacturing margins while forcing feed producers toward low-emission processing equipment and alternative refrigerant systems. This structural pressure cascades through ingredient costs and facility capex requirements.
Growth Catalysts
- Precision fermentation:Microbial production platforms for amino acids and specialty proteins reduce land-use intensity and supply volatility for livestock integrators.
- China's protein security mandate:Domestic capacity expansion in swine and poultry operations drives concentrated demand for compound feeds and micronutrient premixes.
- Aquaculture intensification:Shrimp and salmon producers in Southeast Asian coastal zones adopt species-specific additive protocols to optimize feed conversion ratios.
Market Restraints
- Soybean meal price volatility:Brazilian and Argentinian harvest variability transmits directly into poultry and swine ration cost structures.
- Antibiotic growth promoter bans:EFSA restrictions and FDA Veterinary Feed Directive compliance add formulation complexity and extend product development timelines.
- Fishmeal supply concentration:Peruvian anchovy quota fluctuations and Chilean reduction plant capacity constraints limit marine protein availability for aquafeed.
Strategic Opportunities
- Insect protein commercialization:Black soldier fly and mealworm farming operations in the Netherlands and France scale toward regulatory approval for poultry and aquaculture inclusion.
- Carbon credit monetization:Methane-reducing feed additives qualify for compliance and voluntary carbon markets under EU ETS and California LCFS frameworks.
- Companion animal therapeutics:Veterinary-recommended prescription diets for renal, diabetic, and gastrointestinal conditions command sustained premium pricing from pet owners.
Industry Challenges
- Formulation talent scarcity:Shortage of nutritionists with species-specific expertise in aquaculture and exotic companion animal diets constrains R&D throughput.
- Legacy ERP integration:Feed mills struggle to connect batch control systems with cloud-based formulation optimization platforms.
- Mycotoxin surveillance gaps:Climate-induced aflatoxin and deoxynivalenol outbreaks exceed testing infrastructure in sub-tropical grain sourcing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Nutrition Market |
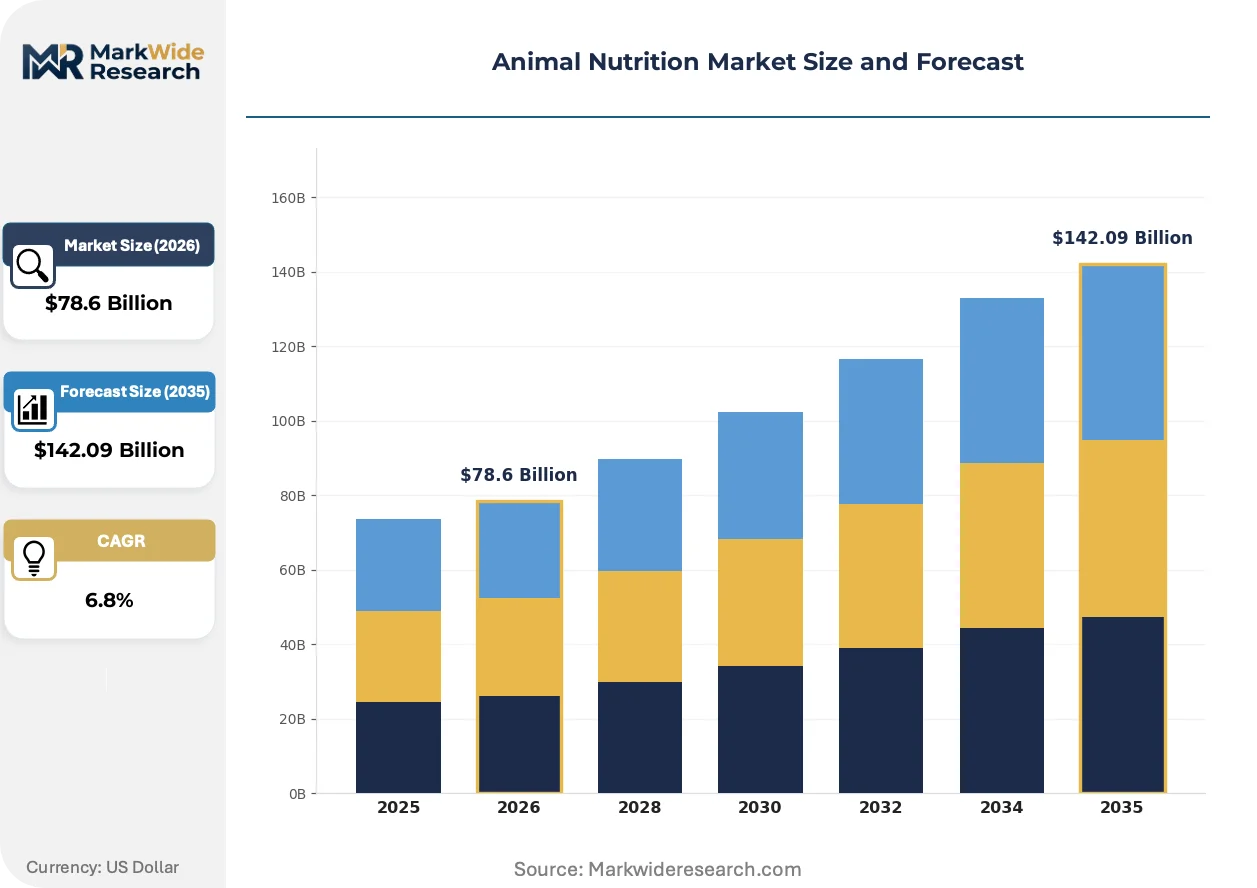
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Additives, Premix, Nutritional Supplements, Veterinary Diets End User: Livestock, Poultry, Aquaculture, Pet Owners Form: Granules, Powders, Liquids, Pellets Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Cargill, Archer Daniels Midland Company, BASF SE, DSM, Nutreco, Alltech, Evonik Industries, Adisseo, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Nutrition Market Emerging Trajectories
Biotechnology platforms and emission compliance frameworks are recalibrating how feed value chains capture margin. Three developments dominate current investment priorities.
Single-cell protein derived from methanotrophic bacteria is overtaking fishmeal in salmon grower diets. Norwegian and Chilean producers are integrating these ingredients at commercial scale. The technology is compressing marine ingredient dependency while stabilizing input cost curves for integrated aquaculture operations.
REACH authorization requirements for feed additive substances are extending safety dossier timelines. European compound feed manufacturers face reformulation mandates as legacy preservatives and processing aids lose approved status. The regulation is accelerating substitution toward enzymatic and microbial alternatives with established toxicological profiles.
Direct contracting between livestock integrators and specialty additive suppliers is displacing distributor-mediated procurement. Large poultry and swine producers in the US Midwest and Brazil's southern states negotiate volume commitments for phytase and probiotic blends. This channel compression squeezes regional feed distributor margins while capturing cost savings for scaled end-users.
Animal Nutrition Market Segmentation
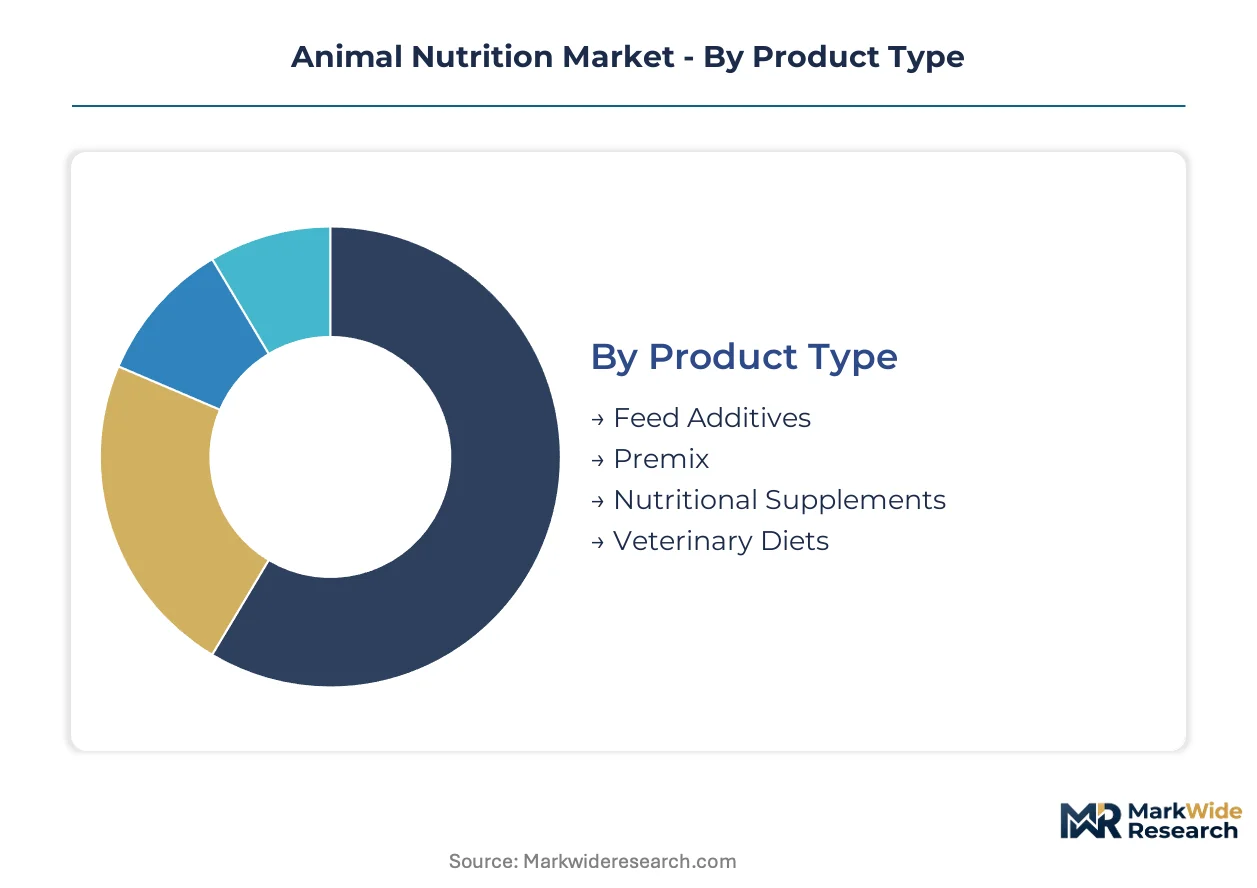
Animal nutrition procurement patterns diverge sharply across species requirements, manufacturing formats, and channel economics. Understanding these fault lines clarifies where formulation investments concentrate and which customer segments command premium pricing power.
Product Type:
Buyers in this category separate by technical sophistication and margin tolerance—livestock integrators prioritize feed conversion efficiency while pet owners seek therapeutic outcomes.
- Feed Additives:Enzyme, probiotic, and acidifier formulations engineered for digestibility enhancement and pathogen suppression. Poultry operations in Brazil's southern states negotiate multi-year phytase supply agreements to lock in feed conversion ratio gains. Livestock integrators absorb price premiums for additives delivering measurable performance deltas.
- Premix:Concentrated vitamin-mineral blends requiring precision blending infrastructure at compound feed mills. Aquaculture producers in Vietnam and Indonesia adopt species-specific micronutrient protocols for shrimp and tilapia as domestic output scales. Premix volumes track closely with intensification rates in coastal farming zones.
- Nutritional Supplements:Targeted nutrient delivery for deficiency correction in grazing and confined systems.
- Veterinary Diets:Prescription-formulated rations for clinical conditions requiring veterinary authorization.
Feed Additives leads volumes today; Premix is gaining share fastest.
End User:
Volume concentration varies dramatically by species—poultry and swine dominate tonnage while aquaculture and companion animals drive margin expansion.
- Livestock:Cattle and swine operations consuming bulk compound feeds and metabolic enhancers. China's protein security mandate accelerates domestic swine herd rebuilding, concentrating demand for lysine and energy-dense rations in Sichuan and Henan provinces. Dairy operations in the Netherlands deploy precision feeding systems to optimize milk yield per cow.
- Poultry:Broiler and layer operations with exacting amino acid specifications and rapid turnover economics. US Midwest integrators enforce strict metabolizable energy densities between 2,800 and 3,200 kcal per kilogram in grower rations. Contract farming structures concentrate purchasing power among a handful of regional processors.
- Aquaculture:Marine and inland farming operations adopting specialized additives for species-specific nutritional requirements.
- Pet Owners:Companion animal households prioritizing veterinary-recommended therapeutic and preventive nutrition.
Poultry leads volumes today; Aquaculture is climbing the fastest.
Form:
Manufacturing format selection hinges on species feeding behavior, storage infrastructure, and nutrient stability requirements across climate zones.
- Granules:Free-flowing particulate feeds with controlled dissolution rates for ruminant and swine applications. Brazilian feed mills favor granule formats for bulk handling efficiency in humid tropical storage conditions. Particle size distribution below 1.5 millimeters optimizes nutrient absorption in broiler starter phases.
- Powders:Fine-milled ingredients for premix incorporation and liquid feed suspensions. Aquaculture operations in Norway integrate powdered single-cell proteins into salmon grower diets as fishmeal substitution accelerates. Dust control systems add capital intensity at manufacturing facilities.
- Liquids:Pumpable nutrient suspensions for automated dosing and medicated drinking water applications.
- Pellets:Compressed feed forms reducing waste and improving intake consistency in intensive systems.
Pellets leads volumes today; Granules is expanding most quickly.
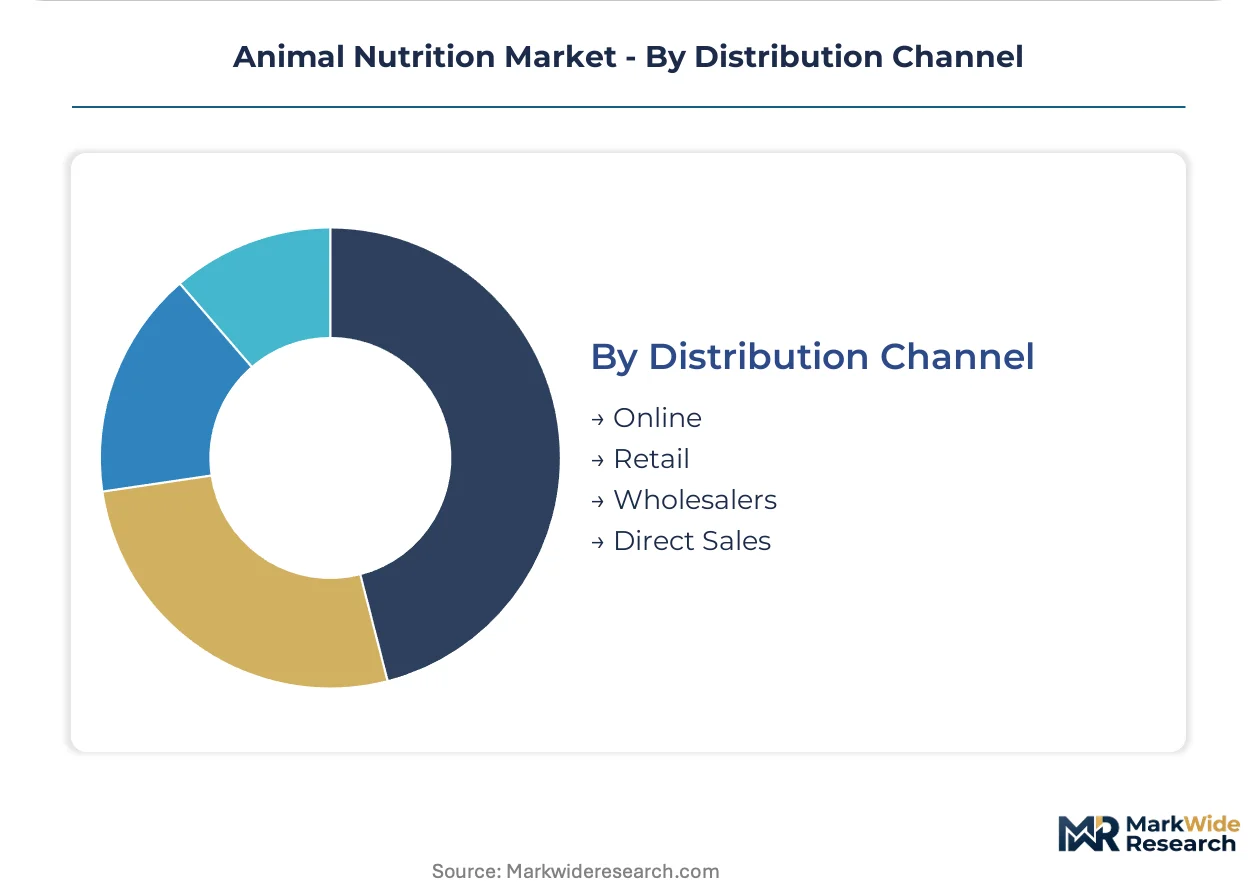
Distribution Channel:
Channel selection reflects customer scale, geographic density, and the technical service intensity required for species-specific formulation support.
- Direct Sales:Volume commitments negotiated between livestock integrators and specialty additive suppliers bypassing distributor margins. Cargill's aquafeed division secures long-term supply contracts directly with Chilean salmon producers. This channel compression captures cost savings for scaled end-users while squeezing regional distributor economics.
- Wholesalers:Regional distributors aggregating fragmented demand from mid-sized livestock operations and independent feed mills. India's compound feed sector relies on wholesaler networks to reach poultry farmers in Andhra Pradesh and Karnataka. Credit terms and technical advisory services differentiate competitive positioning.
- Retail:Point-of-sale availability for companion animal nutrition and small-scale livestock producers.
- Online:E-commerce platforms capturing convenience-oriented pet owner demand and specialty ingredient procurement.
Wholesalers leads volumes today; Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping feed additive manufacturing as producers relocate to jurisdictions with lower emission compliance costs. The EU F-Gas Regulation and Green Deal frameworks impose steep capex burdens on European facilities. Production capacity is migrating toward regions with streamlined environmental permitting and subsidized energy inputs.
China
Domestic protein security mandates are accelerating swine herd reconstruction in Sichuan and Henan provinces. SAMR's feed safety standards are tightening additive registration requirements for imported enzymes. Shandong Peninsula feed mills are scaling lysine and threonine output to displace reliance on offshore amino acid suppliers.
United States
Midwest poultry integrators are consolidating procurement through direct additive contracts bypassing distributor networks. FDA Veterinary Feed Directive compliance is extending product development timelines for antibiotic alternatives. Iowa and Arkansas processing clusters are deploying precision fermentation platforms for feed-grade amino acids.
Brazil
Southern state swine and poultry operations are absorbing price premiums for phytase and probiotic formulations to improve feed conversion ratios. ANVISA's residue monitoring protocols are shaping import requirements for vitamin premixes. Santa Catarina feed mills are expanding granule production capacity for humid tropical storage conditions.
Norway
Salmon producers are integrating single-cell proteins at commercial scale to reduce fishmeal dependency in grower diets. The country's national pharmaceutical regulator enforces strict maximum residue limits for aquaculture medicated feeds. Bergen-area formulation facilities are scaling algae-based omega-3 platforms.
Netherlands
Dairy operations in North Brabant are deploying precision feeding systems to optimize milk yield per cow. REACH authorization requirements are forcing reformulation of legacy preservatives toward enzymatic alternatives. Eindhoven-region insect protein farms are advancing black soldier fly larvae approval for poultry inclusion.
Animal Nutrition Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation and precision processing facilities multiply across coastal production zones. The market structure concentrates around diversified chemical conglomerates with captive biotechnology platforms and specialized nutrition houses with species-specific formulation expertise. Two strategic archetypes prevail: integrated agribusiness operators with backward control over grain origination, and additive specialists monetizing R&D through patent-protected enzyme and probiotic portfolios. M&A activity and geographic licensing agreements represent the primary competitive vectors as players seek regulatory approvals in high-growth protein production regions.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company exemplify operators with grain origination leverage and compound feed manufacturing scale. BASF SE occupies a position among diversified chemical conglomerates applying industrial biotechnology to amino acid production. These three entities represent distinct competitive postures: trading and origination dominance, fermentation technology leadership, and precision nutrition specialization.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| BASF SE |
| DSM |
| Nutreco |
| Alltech |
| Evonik Industries |
| Adisseo |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Precision fermentation platforms for amino acid production are compressing manufacturing economics while redrawing supplier concentration maps across feed additive value chains. This biotechnology transition simultaneously erodes legacy chemical synthesis margins and concentrates production capacity among capital-intensive fermentation operators in China and the Netherlands.
Pricing Analysis
Distributor margins face compression as direct contracting between livestock integrators and specialty additive suppliers accelerates in the US Midwest and Brazil's southern states. Three-tier pricing structure across premium, standard, and economy levels stratifies by feed conversion ratio performance guarantees and species-specific formulation complexity. Pricing pressure stems from soybean meal volatility transmitting through poultry and swine ration costs. Small-scale aquaculture operations in Southeast Asia exhibit highest price sensitivity; salmon integrators in Norway absorb premiums for algae-based omega-3 platforms.
Supply Chain Analysis
SAMR's tightening feed additive registration requirements and China's protein security mandates are reshaping sourcing patterns toward domestic lysine and threonine producers in Shandong Province. Supply concentration rests on Brazilian soybean processing, Peruvian anchovy reduction, and Chinese amino acid fermentation. Raw material dependencies include fishmeal, soybean meal, and corn-derived starch feedstocks. Single-source vulnerability runs through Peruvian anchovy quota fluctuations. Distribution runs through wholesaler networks in India and direct sales channels for scaled integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal nutrition offers margin expansion through precision fermentation cost curves and therapeutic diet premiumization in companion animals. Feed conversion efficiency gains justify pricing power for performance-proven additives.
For Market Incumbents: Deploy precision fermentation capacity additions in coastal Chinese production zones to capture domestic protein security demand. Consolidate formulation talent pools in aquaculture nutrition to counter specialist poaching from biotechnology entrants. Anchor backward integration into single-cell protein platforms to reduce fishmeal dependency exposure.
For New Entrants and Emerging Players: Begin with insect protein regulatory approval pathways in the Netherlands and France for poultry and aquaculture inclusion. Target companion animal therapeutic diets for renal and diabetic conditions where veterinary authorization creates prescription barriers. Pursue carbon credit qualification for methane-reducing feed additives under EU ETS frameworks.
For Investors and Strategic Acquirers: Roll-up economics work for regional premix specialists because formulation talent scarcity and species-specific expertise create local moats. Five-to-ten-year viability hinges on biotechnology platform adoption rates. Monitor black soldier fly regulatory approval timelines as inflection signal for alternative protein substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | DSM and BASF SE deploy microbial platforms to displace chemical synthesis in amino acid production. |
| Direct Contracting Expansion | Cargill bypasses distributor networks to secure long-term supply agreements with Chilean salmon producers. |
| Insect Protein Regulatory Approval | Netherlands-based black soldier fly farms advance EU authorization for poultry feed inclusion. |
| Carbon Credit Monetization | Methane-reducing additives qualify for compliance markets under EU ETS and California LCFS frameworks. |
| Algae-Based Omega-3 Platforms | Norwegian producers reduce fishmeal dependency in salmon grower diets through DSM's marine biotechnology. |
Methodological Framework
Multiple input streams — executive interviews with compound feed mill operators, procurement leads at livestock integrators, regulatory affairs specialists at additive manufacturers, and distribution channel partners — were reconciled against secondary validation from SAMR registration databases, FDA Veterinary Feed Directive filings, EU REACH authorization records, and customs trade data. Bottom-up volume estimates derived from species-specific feed conversion ratios and production intensity metrics were cross-referenced against top-down market sizing from industry association statistics.
Historical growth trajectories were cross-referenced against panel input from nutrition science directors and aquaculture operations managers to establish projection parameters across the analysis window. Segmentation modeling incorporated product type, species end-use, manufacturing format, and distribution channel dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs included precision fermentation capacity buildout schedules and fishmeal substitution elasticity estimates.
Several conditions sit outside the modeled scope, including abrupt climate shocks to grain harvests, trade policy reversals affecting soybean tariff structures, and breakthroughs in lab-grown meat commercialization that could structurally reduce livestock feed demand. Forecasts reflect documented assumptions about regulatory timeline stability and biotechnology cost curve trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market