
 Essential Oils in Animal Nutrition Market | 2026-2036
Essential Oils in Animal Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oils in Animal Nutrition Market Foresight
Multi-source phytogenic procurement is decoupling from traditional single-supplier antibiotic-replacement programs across major feed compounders. Cargill Incorporated leverages integrated crop-to-compound supply chains to secure consistent terpenoid feedstock for its animal nutrition division. Kemin Industries anchors its position through captive extraction infrastructure in key botanical sourcing regions. Delacon Biotechnik GmbH specializes in species-specific essential oil blends validated through peer-reviewed trials, differentiating its portfolio from commodity phytogenics.
Essential oils in animal nutrition comprise volatile aromatic compounds—primarily terpenoids, phenolics, and aldehydes—extracted through steam distillation or cold pressing, then formulated as feed additives to modulate gut microbiota, enhance nutrient digestibility, and reduce oxidative stress in livestock. Liquid formulations dominate current volumes due to ease of incorporation into existing feed mill infrastructure, while micro-encapsulated powders command premium positioning for heat-stable applications in pelleting operations. Poultry applications lead absolute consumption as integrators phase out ionophores, though aquaculture represents the fastest-growing addressable segment as shrimp and salmon producers adopt phytogenic disease management protocols.
EFSA's feed additive evaluation framework and the EU Green Deal's sustainable protein targets constrain novel essential oil entrants to rigorous safety dossiers, while FDA's Generally Recognized as Safe pathway shapes US market access timelines for new botanical actives. China's Ministry of Agriculture and Rural Affairs maintains a positive-list approach to feed additives, requiring domestic registration that favors local-foreign joint ventures. Stakeholders must monitor evolving residue-testing protocols and antimicrobial-resistance surveillance thresholds as these determine which phytogenic chemistries achieve sustained commercial traction versus regulatory delisting.
Market Dynamics
Micro-encapsulation technologies are compressing formulation margins while expanding heat-stable applications, forcing compounders to choose between licensing precision-blending patents or accepting commodity positioning in pelleted feed markets.
Growth Catalysts
- EU Green Deal protein targets:EFSA's streamlined feed additive pathways for phytogenic alternatives accelerate market entry timelines for botanical actives meeting residue thresholds.
- Brazilian poultry integrators:Antibiotic-free certification requirements from export buyers are mandating essential oil inclusion in grower-finisher rations.
- Steam distillation yield improvements:Advanced solvent recovery systems in Indonesian clove and cinnamon processing are lowering terpenoid extraction costs.
Market Restraints
- Botanical supply concentration:Indonesian and Madagascan vanilla-orchid regions control 70% of global eugenol feedstock, creating price volatility during monsoon disruptions.
- EFSA safety dossier costs:Novel essential oil actives require 18-24 month toxicological studies that exhaust mid-tier compounder R&D budgets.
- Synthetic antioxidant substitution:BHT and ethoxyquin retain cost advantages in bulk swine operations where heat stability requirements are minimal.
Strategic Opportunities
- Vietnamese aquaculture expansion:Shrimp producers in Mekong Delta provinces are piloting phytogenic disease management protocols for early mortality syndrome prevention.
- China's positive-list registration:Joint venture structures with domestic feed additive license holders bypass 12-18 month foreign registration queues.
- Precision livestock farming convergence:Sensor-enabled dosing systems enable real-time essential oil adjustment based on gut microbiome biomarkers.
Industry Challenges
- Phytochemist talent scarcity:Compound formulation teams lack expertise in terpenoid stability modeling under extrusion temperatures.
- Multi-jurisdiction residue testing:Divergent MRL protocols between EU, China, and Saudi Arabia force parallel validation studies.
- Legacy feed mill retrofit costs:Liquid dosing infrastructure upgrades for micro-encapsulated powder handling strain integrator capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oils in Animal Nutrition Market |
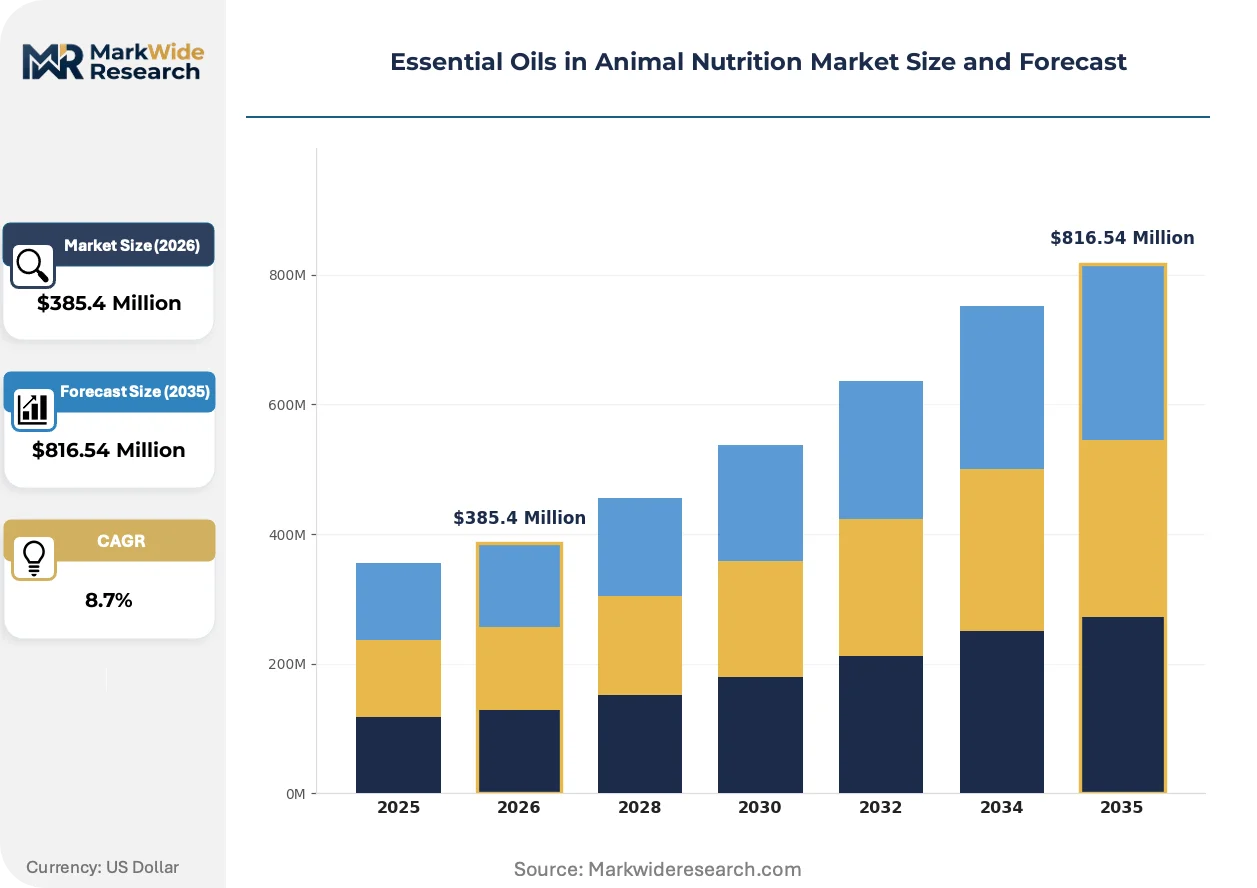
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Granule Application: Ruminants, Poultry, Swine, Aquaculture End User: Farmers, Feed Manufacturers, Pet Owners, Veterinary Clinics Delivery Mode: Dosing Pump, Spray, Feed Additive, Liquid Formulation |
| Companies Covered | Cargill Incorporated, Kemin Industries, Archer Daniels Midland Company, Koninklijke DSM N.V., BASF SE, Evonik Industries, Nutreco N.V., Delacon Biotechnik GmbH, BIOMIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oils in Animal Nutrition Market Shifts & Advancements
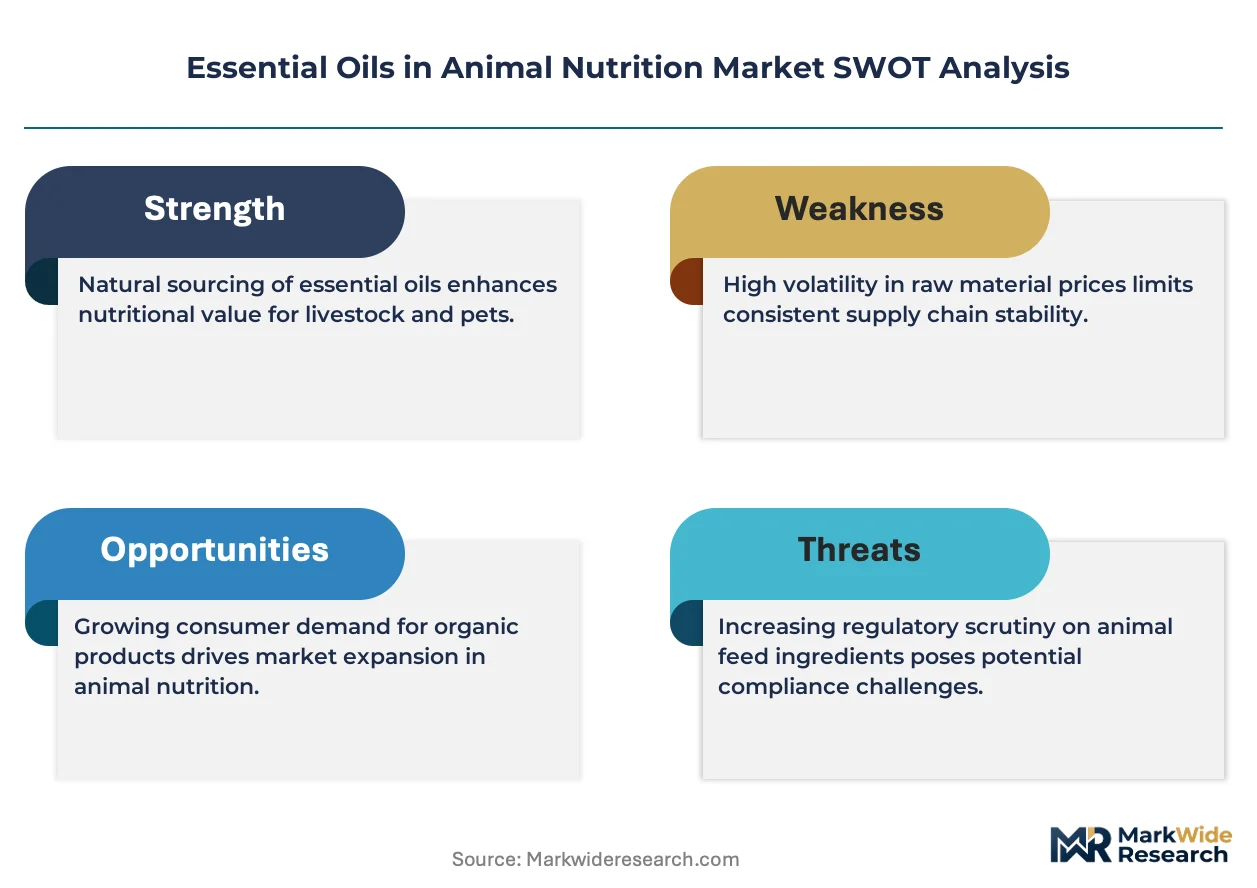
Formulation science is pivoting from single-actives to synergistic terpenoid-phenolic blends, while regulatory data requirements and precision-feeding hardware reshape competitive boundaries.
Co-extrusion micro-encapsulation is converging with precision-feeding hardware to enable species-specific essential oil release profiles. Salmon farmers in Norway are adopting these systems to synchronize phytogenic delivery with feeding cycles. The technology is converging with gut-health monitoring platforms, compressing the gap between formulation innovation and measurable performance outcomes.
EFSA's 2023 feed additive guidance on botanicals tightens heavy metal and pesticide residue thresholds for novel entrants. Compounders must now submit full supply chain traceability documentation from cultivation to extraction. German and Dutch integrators are responding by consolidating procurement through vertically controlled terpenoid suppliers.
Buyers are consolidating phytogenic procurement under long-term offtake agreements with extraction specialists. Southeast Asian poultry integrators are displacing spot-market botanical purchases with three-year terpenoid supply contracts. This pattern is most visible in Thailand, where CP Group and Betagro have locked Indonesian clove and oregano oil volumes through 2027.
Essential Oils in Animal Nutrition Market Segmentation
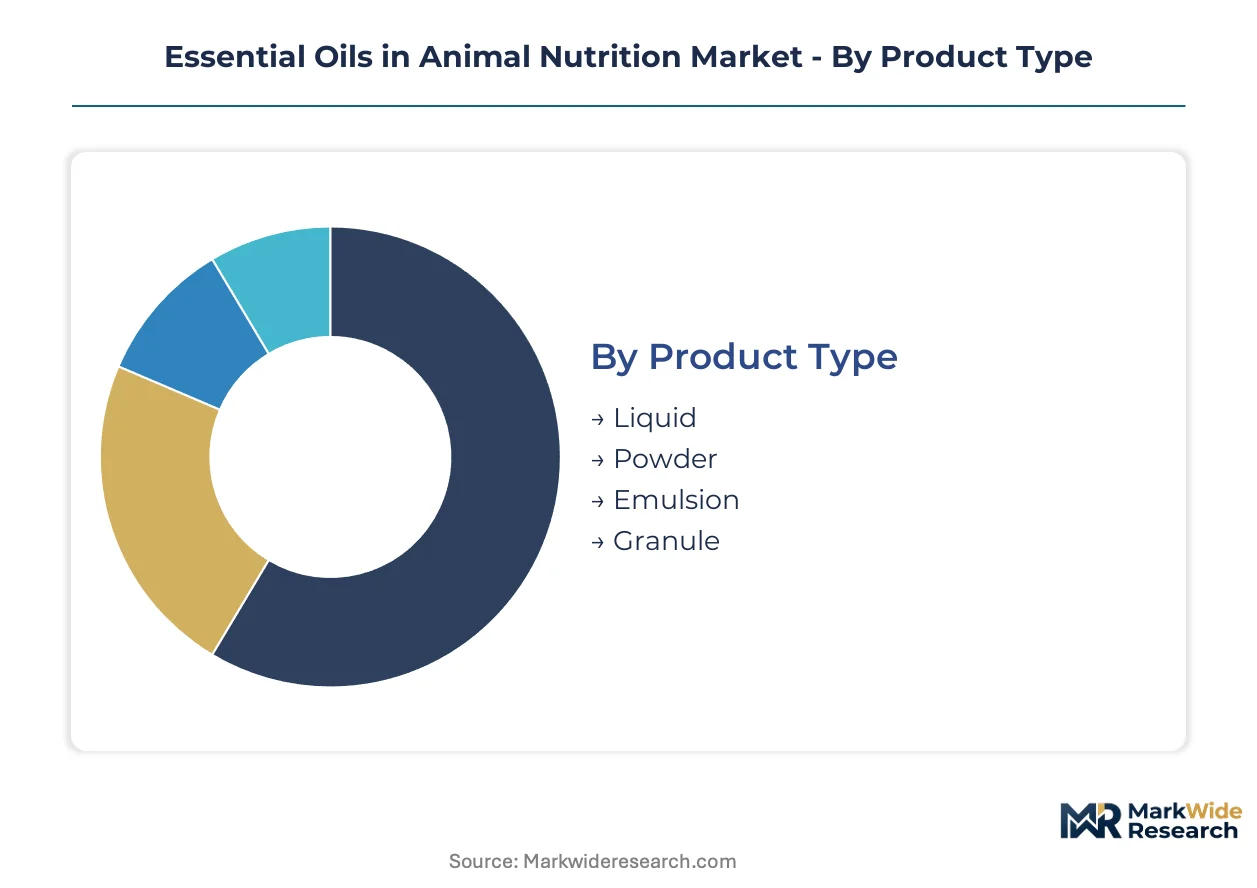
Essential oil formulation strategies diverge sharply across product types, applications, and delivery infrastructure. Each segmentation axis reveals distinct margin structures and regulatory compliance burdens that determine competitive positioning.
Product Type:
Customization intensity spans from commodity liquids to precision-engineered granules with embedded release profiles.
- Liquid:Unformulated terpenoid concentrates dissolved in carrier oils enable direct incorporation into existing feed mill liquid dosing lines. Brazilian poultry integrators favor this format for antibiotic-free grower-finisher programs where rapid microbiome modulation is required.
- Powder:Spray-dried essential oils on inert carriers offer intermediate heat stability for mash feed applications. Chinese feed compounders prefer powder formats for swine nursery diets where pelleting temperatures remain moderate.
- Emulsion:Oil-in-water dispersions improve terpenoid bioavailability in ruminant applications.
- Granule:Extruded matrices with controlled-release coatings command premium positioning in pelleted aquaculture feeds.
Leading the category by volume: Liquid. Growing fastest: Granule.
Application:
Species-specific physiology dictates formulation complexity and regulatory pathway selection.
- Poultry:Broiler and layer operations drive absolute consumption as integrators phase out ionophores and seek phytogenic alternatives to coccidiostats. EFSA's streamlined botanical pathways accelerate novel essential oil actives into EU poultry feed programs.
- Aquaculture:Shrimp and salmon producers adopt phytogenic disease management protocols for early mortality syndrome and sea lice prevention. Norwegian salmon farmers pilot sensor-synchronized essential oil delivery systems.
- Swine:Nursery and grower-finisher applications concentrate in China and Germany where antibiotic growth promoter bans are most stringent.
- Ruminants:Dairy and beef cattle applications remain underpenetrated due to rumen degradation challenges.
Dominant by volume: Poultry. Steepest expansion trajectory: Aquaculture.
End User:
Procurement scale and technical capability separate formulation buyers from direct applicators.
- Feed Manufacturers:Compounders integrate essential oils into complete feeds and premixes, requiring batch-to-batch consistency and full supply chain traceability documentation for EFSA compliance.
- Farmers:Direct application concentrates in Southeast Asian poultry operations where on-farm mixing of liquid essential oils into drinking water bypasses feed mill infrastructure constraints.
- Veterinary Clinics:Therapeutic applications for gut health management in companion and production animals.
- Pet Owners:Niche demand for natural feed supplements in premium companion animal nutrition.
Highest volume concentration: Feed Manufacturers. Fastest growth: Farmers.
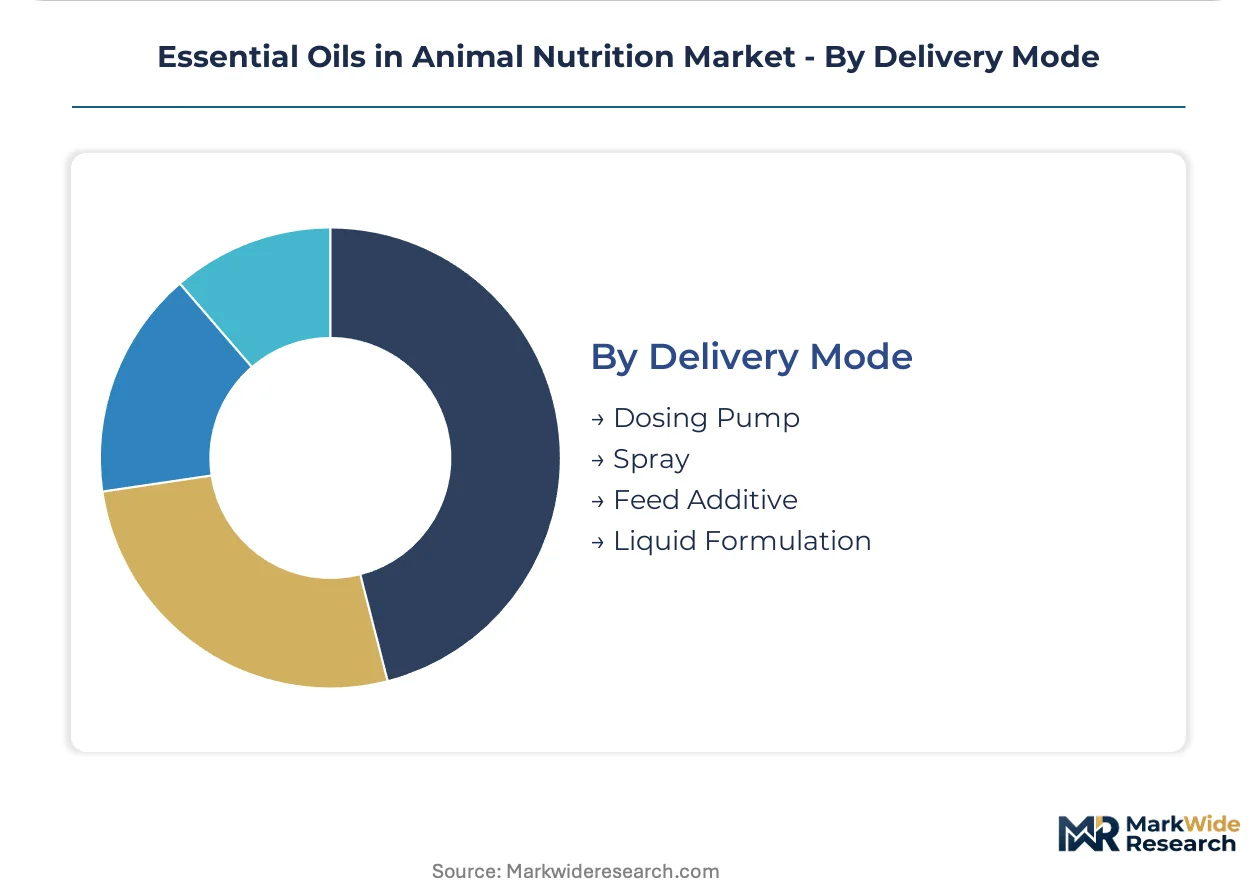
Delivery Mode:
Equipment retrofit requirements and labor intensity shape adoption patterns across farm and mill settings.
- Feed Additive:Premix incorporation enables precise dosing control and uniform distribution. German and Dutch integrators consolidate procurement through vertically controlled terpenoid suppliers to meet EFSA's tightened heavy metal and pesticide residue thresholds.
- Dosing Pump:Automated liquid delivery systems synchronize essential oil administration with feeding cycles in precision livestock farming deployments.
- Liquid Formulation:Direct-to-feed or drinking water application suits small-scale operations without premix infrastructure.
- Spray:Surface application onto finished feed for heat-sensitive actives that cannot survive pelleting.
Primary volume driver: Feed Additive. Fastest uptake: Dosing Pump.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian clove and Madagascan vanilla-orchid regions anchor terpenoid feedstock supply for essential oil processors serving animal nutrition compounders worldwide.
China
Poultry and swine integrators in Shandong and Henan provinces drive phytogenic demand as antibiotic growth promoter bans tighten. The Ministry of Agriculture and Rural Affairs maintains a positive-list approach to feed additives, requiring domestic registration that favors local-foreign joint ventures. Yangtze River Delta feed compounders are consolidating procurement through three-year terpenoid supply contracts with Indonesian extraction specialists.
Brazil
Export-oriented poultry producers in Paraná and Santa Catarina mandate essential oil inclusion for antibiotic-free certification compliance. ANVISA aligns feed additive protocols with EU residue standards to maintain market access for processed chicken exports. São Paulo-based integrators are retrofitting liquid dosing infrastructure to handle micro-encapsulated powder formulations for pelleted grower-finisher rations.
Germany
Layer and broiler operations in Lower Saxony lead EU phytogenic adoption as EFSA streamlines botanical feed additive pathways. The EU Green Deal's sustainable protein targets accelerate novel essential oil actives meeting tightened heavy metal and pesticide residue thresholds. Dutch-German border region compounders are consolidating procurement through vertically controlled terpenoid suppliers to satisfy traceability documentation requirements.
United States
Midwest swine operations and Southeast poultry integrators pilot precision-feeding hardware synchronized with essential oil delivery systems. FDA's Generally Recognized as Safe pathway shapes market access timelines for new botanical actives in feed applications. Iowa and North Carolina feed manufacturers are licensing co-extrusion micro-encapsulation patents to expand heat-stable applications in pelleted diets.
Vietnam
Mekong Delta shrimp producers pilot phytogenic disease management protocols for early mortality syndrome prevention in aquaculture operations. The country's national agricultural regulator evaluates feed additive registrations against ASEAN harmonized standards. Ho Chi Minh City-based aquafeed compounders are displacing spot-market botanical purchases with structured offtake agreements covering clove and oregano oil volumes.
Essential Oils in Animal Nutrition Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as compounders secure terpenoid feedstock against botanical supply volatility. The vendor base clusters around three strategic archetypes: integrated agribusiness conglomerates with captive crop-to-compound supply chains, specialty extraction houses with captive infrastructure in key sourcing regions, and species-specific formulation specialists validated through peer-reviewed trials. Competitive intensity centers on micro-encapsulation technology licensing and precision-blending patent acquisition.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify upstream control over terpenoid feedstock through crop origination networks. Kemin Industries occupies a position among specialty extraction houses with infrastructure anchored in botanical sourcing regions. Delacon Biotechnik GmbH represents the species-specific formulation archetype, differentiated from commodity phytogenics through targeted essential oil blends.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kemin Industries |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| BASF SE |
| Evonik Industries |
| Nutreco N.V. |
| Delacon Biotechnik GmbH |
| BIOMIN |
| Others |
Supply & Pricing Matrix
Captive extraction infrastructure in Indonesian clove and Madagascan vanilla-orchid regions anchors both supply security and premium pricing power for terpenoid feedstock processors serving animal nutrition compounders. EFSA's tightened residue thresholds and traceability mandates reward vertically controlled suppliers with pricing premiums over spot-market botanical sourcing.
Pricing Analysis
Service bundling separates micro-encapsulation technology licensing from unbundled commodity terpenoid concentrate sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in liquid formulations is intensifying because Brazilian poultry integrators are consolidating procurement under long-term offtake agreements. Small-scale Southeast Asian farmers exhibit highest price sensitivity, while German-Dutch compounders demonstrate lowest sensitivity due to EFSA compliance premiums.
Supply Chain Analysis
Dual-sourcing qualification requirements from German and Dutch integrators mandate Indonesian and Madagascan terpenoid suppliers alongside Brazilian oregano oil processors. Feedstock draws from clove bud, cinnamon bark, and oregano leaf botanicals. Single-source vulnerability concentrates in monsoon-dependent Indonesian harvests. Distribution runs through vertically controlled extraction houses to compounders, then to feed manufacturers or direct-to-farm dosing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-encapsulation precision-blending technology is displacing legacy liquid formulation infrastructure across poultry and aquaculture feed operations. This transition compresses margins for compounders lacking patented heat-stable delivery systems.
For Market Incumbents: To counter synthetic antioxidant substitution in bulk swine operations, deepen captive extraction infrastructure in Indonesian sourcing regions and accelerate EFSA-compliant traceability certification investments for premium tier positioning. For New Entrants and Emerging Players: Capture Vietnamese aquaculture expansion by piloting phytogenic disease management protocols for shrimp early mortality syndrome prevention, leveraging joint venture structures with domestic feed additive license holders to bypass foreign registration queues. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty extraction house acquisitions by integrated agribusiness conglomerates seeking upstream terpenoid control. Long-term viability favors targets with patented micro-encapsulation portfolios and EFSA-validated dossiers. Monitor EFSA residue threshold revisions as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-encapsulation Patent Licensing | Enables heat-stable essential oil applications in pelleted aquaculture feeds for Norwegian salmon farmers. |
| Captive Extraction Infrastructure Buildout | Secures consistent terpenoid feedstock supply from Indonesian clove and Madagascan vanilla-orchid regions. |
| EFSA-compliant Traceability Certification | Satisfies tightened heavy metal and pesticide residue thresholds for EU poultry feed additive market access. |
| Joint Venture with Domestic License Holders | Bypasses China's 12-18 month foreign feed additive registration queues through local partnership structures. |
| Precision-feeding Hardware Integration | Synchronizes sensor-enabled essential oil dosing with gut microbiome biomarkers in livestock operations. |
Research Methodology
Document review covered EFSA feed additive guidance documents, ANVISA regulatory protocols, and Chinese Ministry of Agriculture registration databases, complemented by interviews with feed compounder procurement directors, extraction house operations managers, poultry integrator nutritionists, and aquaculture disease management specialists. Secondary validation drew from customs trade data, SEC 10-K filings of listed agribusiness conglomerates, and botanical supply chain reports. Bottom-up demand modeling triangulated against top-down market sizing.
Output projections span volume and value across the analysis window through segmented modeling of formulation type, species application, delivery infrastructure, and geographic regulatory cluster. CAGRs derived from historical penetration rates and policy-driven adoption curves. Industry-specific inputs incorporated EFSA authorization timelines, Brazilian antibiotic-free certification mandates, and Indonesian clove harvest volatility indices.
The model holds under stable regulatory authorization pathways and consistent monsoon patterns; deviation in EFSA residue threshold tightening or Indonesian supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Broiler Premix Market