
 Pet Premixes Market | 2026-2036
Pet Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Premixes Market Analytics
Buyer concentration among large pet food manufacturers is rebalancing as mid-size specialty brands and direct-to-consumer startups fragment procurement channels. Cargill leverages its integrated supply chain to secure bulk micronutrient sourcing contracts across North American feed operations. DSM Nutritional Products sustains R&D intensity in amino acid and vitamin premix formulations for companion animal diets. Alltech differentiates through yeast-based bioactive premix platforms that target gut health in dogs and cats.
Pet premixes constitute concentrated blends of vitamins, minerals, amino acids, and functional additives dosed at 0.5-3.0% inclusion rates into finished pet foods to ensure nutritional completeness. Manufacturers produce these blends through sequential dilution systems that guarantee homogeneous distribution of micro-ingredients at parts-per-million precision. Dry Mixes occupy the dominant volume position due to extended shelf stability and lower logistics costs in bulk feed operations. Nutritional Supplements represent the fastest-expanding category as pet owners seek condition-specific formulations for joint, cognitive, and dermatological health. Distribution through Online Retail channels is capturing margin pools previously held by wholesale intermediaries.
The FDA Center for Veterinary Medicine enforces Current Good Manufacturing Practice requirements for animal food that mandate hazard analysis and preventive controls across premix facilities. The EU Feed Hygiene Regulation and EFSA guidelines on feed additives constrain which functional ingredients gain market access in European formulations. The USDA and state-level feed control officials conduct routine inspections that shape compliance costs for domestic premix producers. Stakeholders must monitor evolving regulatory thresholds for novel ingredients such as postbiotics and hemp-derived compounds.
Market Dynamics
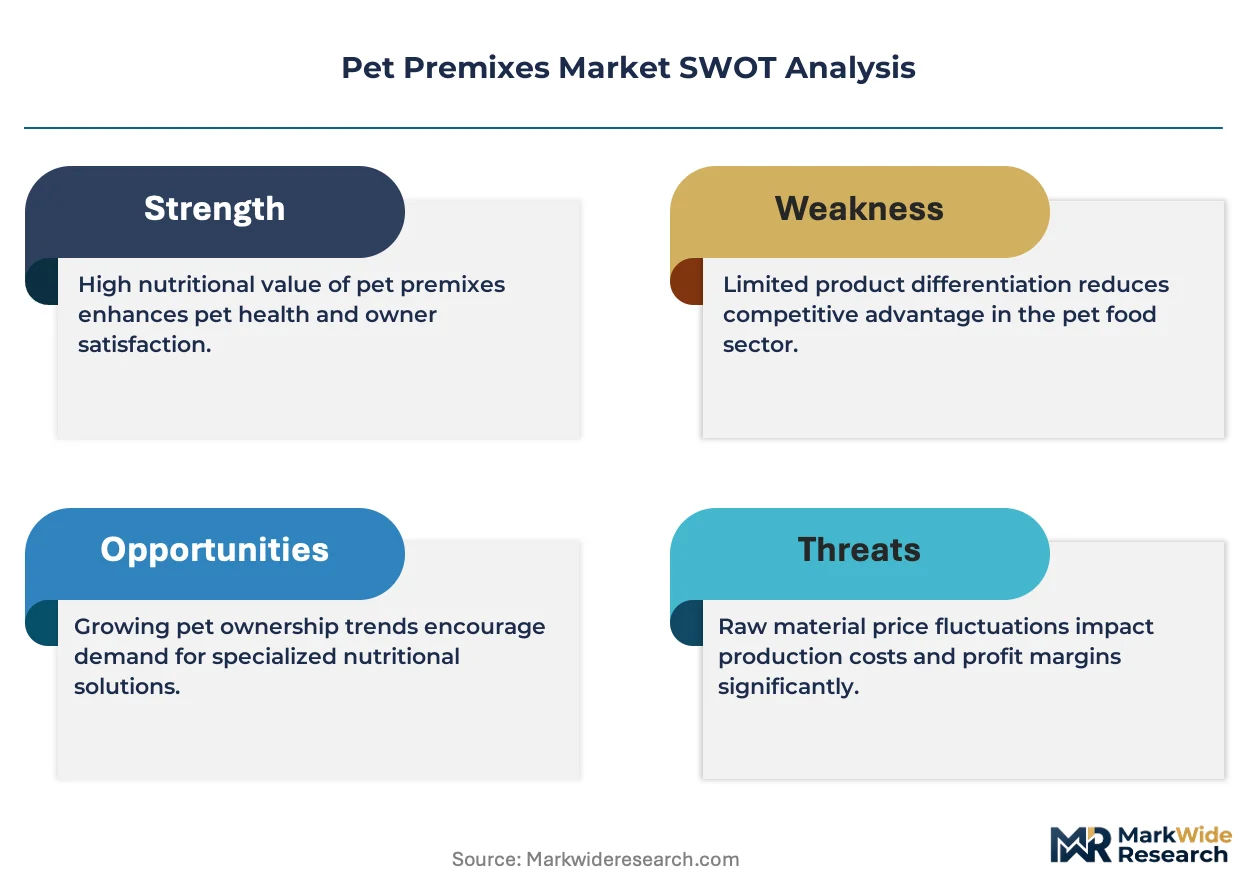
Precision dosing automation is compressing premix formulation tolerances from percent-level to parts-per-million specifications, forcing capital upgrades across mid-tier blending facilities and redrawing competitive tiers based on metrology capability.
Growth Catalysts
- Humanization of Pet Nutrition:Pet owners in the United States now apply human dietary frameworks to companion animal formulations, accelerating demand for condition-specific micronutrient premixes targeting joint mobility and cognitive function.
- EU Feed Hygiene Regulation:Mandatory hazard analysis and preventive control requirements are professionalizing premix manufacturing standards, creating compliance-driven demand for certified premix suppliers across European feed operations.
- Direct-to-Consumer Channel Expansion:Specialty pet food startups are bypassing traditional wholesale intermediaries, fragmenting procurement volumes and creating dedicated premix sourcing relationships with flexible minimum order quantities.
Market Restraints
- Vitamin Price Volatility:Feed-grade vitamin A and E derivatives fluctuate with crude oil and agricultural feedstock cycles, compressing blending margins during input cost spikes.
- Supply Concentration in China:Bulk amino acid and vitamin precursor manufacturing clusters in Shandong and Jiangsu provinces, creating geographic risk exposure for premix formulators dependent on single-source API inputs.
- Regulatory Friction from Novel Ingredients:FDA Center for Veterinary Medicine review timelines for postbiotic and hemp-derived cannabinoid premix additives extend 18-36 months, delaying product commercialization.
Strategic Opportunities
- Senior Pet Formulation White Space:Geriatric dog and cat populations in Japan and Western Europe remain underpenetrated by age-adjusted micronutrient premixes targeting sarcopenia and renal function.
- Regulatory Tailwind from USDA Organic:Certified organic pet food growth is mandating synthetic vitamin exclusions, creating demand for natural-source premix alternatives and fermentation-derived nutrient platforms.
- Technology Convergence:Near-infrared spectroscopy and blockchain traceability are unifying real-time quality verification with ingredient provenance documentation, enabling premium pricing for transparent supply chains.
Industry Challenges
- Metrology Talent Scarcity:Premix facilities require analytical chemists capable of validating homogeneity coefficients below 10% relative standard deviation, a skill set concentrated in pharmaceutical rather than feed industry labor pools.
- Legacy System Integration:Sequential dilution blending equipment from 1990s installations lacks data architecture compatibility with modern manufacturing execution systems, forcing costly parallel infrastructure during digital transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Premixes Market |
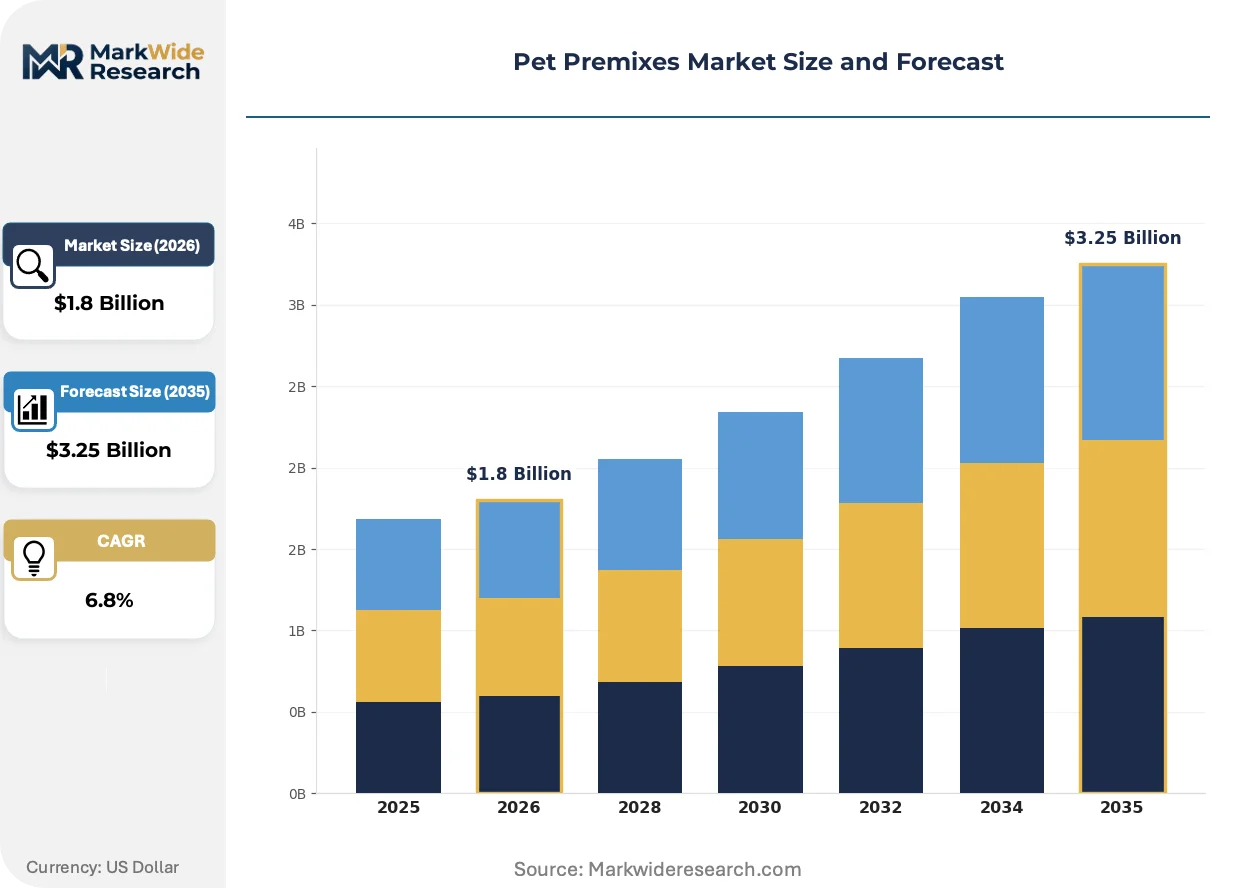
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Mixes, Wet Mixes, Nutritional Supplements, Fortified Foods End User: Dog Owners, Cat Owners, Livestock Farmers, Pet Shops Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Weight Management, Nutritional Support, Meal Replacement, Dietary Requirements |
| Companies Covered | Cargill, Archer Daniels Midland Company, DSM Nutritional Products, Evonik Industries, Wisium, Zinpro, Alltech, Trouw Nutrition, MIAVIT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Premixes Market Evolving Landscape
Formulation science and verification technology are converging to enable mass-customization of micronutrient premixes at production-scale economics previously reserved for pharmaceutical applications.
Micro-encapsulation technology is unifying lipid-soluble vitamin stability with controlled-release kinetics in high-temperature extrusion environments. Premium dry pet food manufacturers in the United States and Germany are adopting spray-congealed vitamin matrices at accelerated procurement cycles. This unification is compressing the performance gap between standard and premium premix tiers, forcing commodity suppliers toward technical service differentiation.
EFSA guidelines on feed additive re-evaluation are mandating expanded toxicological datasets for legacy vitamin and mineral compounds. European premix formulators face reformulation costs to maintain market access as safety thresholds tighten for copper and zinc inclusion rates. Condition-specific premix categories targeting dermatological health are most affected, with suppliers accelerating natural-source mineral substitution programs.
Subscription-based premix procurement is displacing spot-market purchasing among mid-size specialty pet food brands. Direct sourcing relationships with premix houses are replacing distributor intermediaries in North American and Western European supply chains. This pattern is most visible in the United States, where venture-backed pet food startups prioritize supply chain transparency over procurement cost minimization.
Pet Premixes Market Segmentation
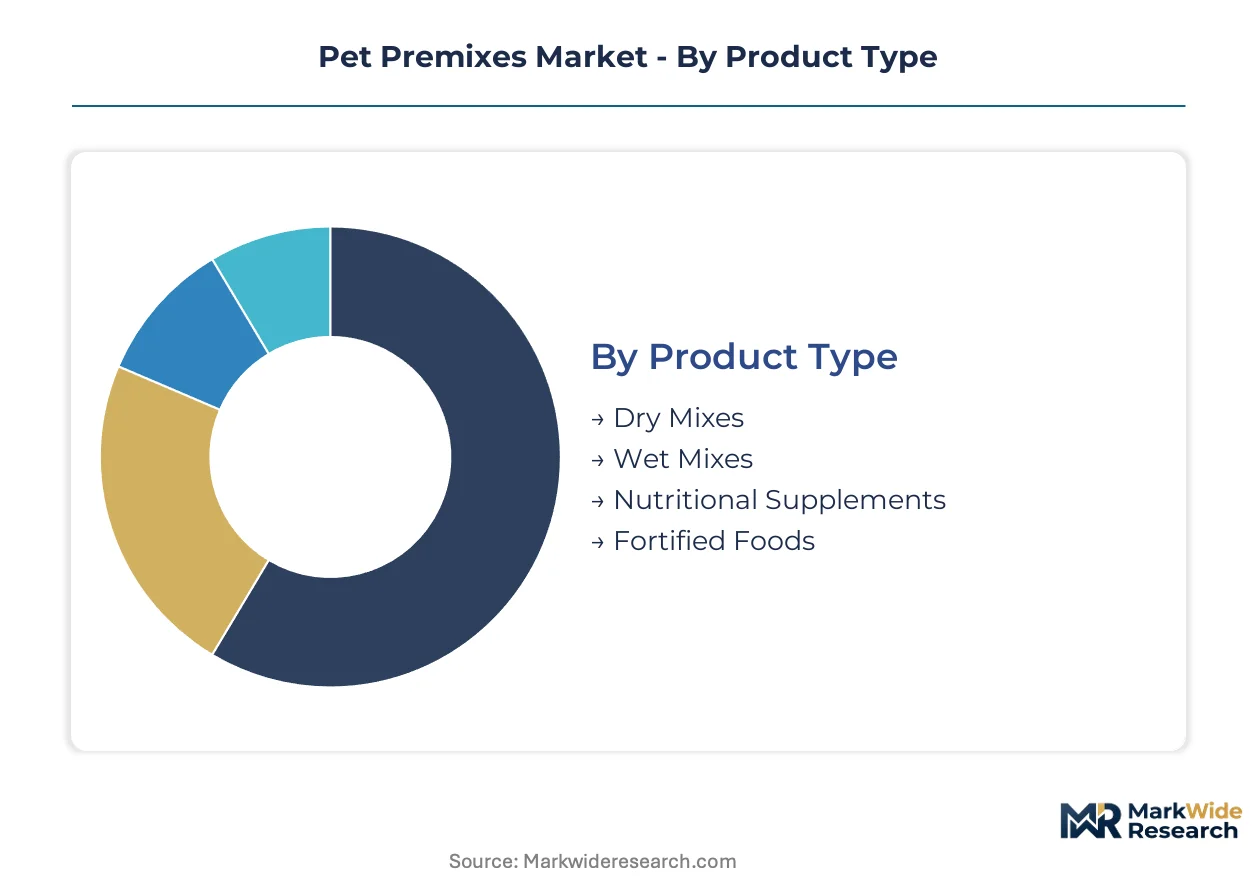
Pet premix manufacturers configure production lines around distinct formulation chemistries and channel economics. Segment boundaries determine capital allocation for blending equipment, shelf-life engineering, and regulatory compliance documentation.
Product Type:
Upgrade cycles in blending automation are segmenting competitive tiers by precision capability and batch traceability.
- Dry Mixes:Powdered vitamin-mineral matrices achieve 18-24 month stability through moisture-barrier packaging and anti-caking agents. Demand concentrates in high-volume extrusion facilities across the United States, where bulk procurement contracts favor logistics efficiency over formulation flexibility.
- Nutritional Supplements:Condition-specific micronutrient concentrates target joint, cognitive, and dermatological health endpoints with inclusion rates below 1.5%. Specialty pet food startups in Germany and Japan are accelerating procurement of these precision-dosed formats as humanization trends reshape owner expectations.
- Wet Mixes:Liquid suspensions of lipid-soluble vitamins require refrigerated supply chains and shorter rotation cycles.
- Fortified Foods:Complete diet formats with embedded premix layers bypass separate supplementation steps for convenience-oriented owners.
Dry Mixes sits at the top of the volume ranking, with Nutritional Supplements climbing the fastest.
End User:
Customer procurement sophistication spans from commodity spot purchasing to collaborative formulation development.
- Dog Owners:Premium dry food manufacturers serving this segment demand condition-specific premix matrices targeting mobility and digestive health. Large breed formulations in the United States specify enhanced chondroitin and glucosamine loading rates.
- Cat Owners:Obligate carnivore physiology drives taurine and arachidonic acid premix specifications. Japanese and UK specialty brands are tightening amino acid assay tolerances for renal support diets.
- Livestock Farmers:Companion animal premixes represent a sideline procurement category with less stringent traceability requirements.
- Pet Shops:Private-label sourcing relationships prioritize minimum order flexibility and rapid formulation iteration.
Dog Owners commands the largest addressable base, though Cat Owners is gaining share fastest in premium tier expansion.
Distribution Channel:
Channel selection determines margin retention and minimum viable batch economics for premix houses.
- Online Retail:Direct-to-consumer pet food brands bypass wholesale markups through platform-integrated supply chains. Venture-backed startups in the United States prioritize transparent premix provenance over cost minimization.
- Specialty Stores:Independent retailers stock condition-specific SKUs with higher per-unit premix loading and technical service support.
- Supermarkets:Mass-market dry food procurement emphasizes volume scale and standardized vitamin premix specifications.
- Wholesale:Distributor intermediaries consolidate fragmented demand from regional feed operations.
Online Retail is displacing traditional intermediaries most rapidly, while Wholesale retains bulk volume leadership.
Application:
Clinical outcome claims are tightening regulatory scrutiny and reformulation frequency across functional positioning tiers.
- Weight Management:Calorie-dilute premixes maintain micronutrient density at reduced energy density. Veterinary therapeutic diets in the United States specify L-carnitine and fiber matrix additives.
- Nutritional Support:Recovery and convalescence formulations concentrate B-vitamin and antioxidant loading for metabolic support.
- Meal Replacement:Complete nutrition premixes for therapeutic feeding tubes and liquid diets require pharmaceutical-grade homogeneity validation.
- Dietary Requirements:Hypoallergenic and limited-ingredient formats constrain premix sourcing to single-protein or hydrolyzed nutrient carriers.
Nutritional Support anchors clinical channel revenue, with Weight Management expanding most quickly through veterinary endorsement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in premix procurement sophistication, with German manufacturers emphasizing EFSA compliance documentation while US buyers prioritize supply chain transparency for direct-to-consumer brands.
United States
Premium pet nutrition spending outpaces conventional feed markets as venture-backed startups demand flexible minimum order quantities. FDA Center for Veterinary Medicine enforces Current Good Manufacturing Practice requirements that mandate hazard analysis across premix facilities. Kansas and Iowa host major blending operations where precision dosing automation is compressing formulation tolerances.
Germany
Specialty pet food manufacturers in Bavaria and Baden-Württemberg scale premix procurement for condition-specific formulations targeting joint mobility. EU Feed Hygiene Regulation and EFSA guidelines on feed additives constrain functional ingredient market access. The Stuttgart industrial corridor concentrates yeast-based bioactive premix development for gut health applications.
China
Domestic pet food brands accelerate micronutrient premix adoption as dog and cat ownership expands in tier-one cities. SAMR and GB standards govern feed additive safety assessments for imported premix formulations. Shandong and Jiangsu provinces cluster bulk amino acid and vitamin precursor manufacturing, creating geographic risk exposure for formulators.
Japan
Geriatric dog and cat populations drive underpenetrated demand for age-adjusted micronutrient premixes targeting sarcopenia. METI and MAFF guidelines shape feed safety protocols for novel ingredients including postbiotics. The Kanto region around Tokyo anchors premium pet food manufacturing where taurine assay tolerances tighten for renal support diets.
United Kingdom
Independent specialty retailers stock condition-specific SKUs with higher per-unit premix loading and technical service support. FSA and Defra regulations align with EU Feed Hygiene standards post-Brexit transition periods. The Midlands and Northern England concentrate mid-size blending facilities serving private-label sourcing relationships.
Pet Premixes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered competitive strata. Large integrated agribusinesses leverage bulk micronutrient sourcing contracts and captive supply chains to defend position in high-volume extrusion channels. Mid-tier formulators differentiate through technical service partnerships and rapid formulation iteration for specialty brands. Emerging competitive moves center on precision dosing automation upgrades and direct sourcing relationship cultivation with venture-backed pet food startups.
Within the diversified agribusiness tier, Cargill and Archer Daniels Midland Company represent integrated supply chain archetypes with feed operations spanning multiple continents. DSM Nutritional Products and Evonik Industries occupy positions among chemical and nutritional science specialists, exemplifying R&D-intensive formulation capabilities. Alltech anchors the biotechnology-driven segment, representing yeast-based bioactive platforms that target functional health endpoints. These three archetypes—integrated agribusiness, nutritional science specialists, and biotechnology platforms—capture distinct margin pools across commodity and premium premix tiers.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| DSM Nutritional Products |
| Evonik Industries |
| Wisium |
| Zinpro |
| Alltech |
| Trouw Nutrition |
| MIAVIT |
| Others |
Value Network & Pricing Analysis
Micro-encapsulation technology adoption across North American extrusion facilities is compressing cost differentials between standard and premium premix tiers while concentrating procurement leverage among automated blending houses. FDA Current Good Manufacturing Practice mandates and EU Feed Hygiene Regulation compliance investments are simultaneously elevating fixed cost thresholds and rewarding scale economies in micronutrient sourcing.
Pricing Analysis
Capacity additions in Kansas and Iowa are reshaping price floors for high-volume dry mix procurement as precision dosing automation diffuses across mid-tier facilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with organic-certified natural-source premixes commanding sustained premiums. Price differentiation stems from metrology capability gaps and after-sales technical service bundling. Pricing pressure intensifies in commodity vitamin-mineral matrices as Chinese feed-grade precursor exports expand. Mass-market extrusion channels exhibit highest price sensitivity, while venture-backed direct-to-consumer brands prioritize transparent provenance over cost minimization.
Supply Chain Analysis
Analytical chemist scarcity in Shandong and Jiangsu provinces is constraining quality validation throughput at bulk amino acid precursor facilities. Geographic supply concentration centers on China for vitamin precursors and fermentation-derived nutrients, the United States for precision blending automation, and Germany for yeast-based bioactive platforms. Raw material dependencies encompass feed-grade vitamin A and E derivatives, taurine and arachidonic acid concentrates, and micro-encapsulation lipid matrices. Single-source vulnerability in Shandong's vitamin precursor cluster exposes formulators to geographic concentration risk. Distribution runs through direct sourcing relationships with specialty pet food startups displacing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Feed Hygiene Regulation re-evaluations and FDA preventive control mandates continuously elevate compliance-driven demand for certified premix suppliers.
For Market Incumbents: Cement position through backward integration into fermentation-derived nutrient platforms and captive supply of micro-encapsulation matrices. Incumbents must defend against venture-backed startups fragmenting procurement volumes by embedding technical service partnerships with direct-to-consumer brands. Capacity addition in automated precision dosing equipment represents the priority defensive lever against metrology-capable mid-tier challengers. For New Entrants and Emerging Players: Near-infrared spectroscopy integration with blockchain traceability offers a technology-first wedge into premium tier transparency demands. New entrants should target Japan's underpenetrated geriatric pet formulation segment and USDA Organic-certified natural-source premix white space. A go-to-market angle anchored in subscription-based procurement relationships with mid-size specialty brands bypasses entrenched distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier formulators with automated blending capabilities but underdeveloped direct sourcing channels. Long-term viability over the next decade hinges on regulatory compliance infrastructure and R&D intensity in condition-specific formulations. The signal to watch is FDA review timeline compression for postbiotic and hemp-derived additive categories as inflection indicator for novel ingredient platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Dosing Automation Upgrade | Kansas and Iowa facilities compress formulation tolerances to parts-per-million specifications. |
| Backward Integration into Fermentation Platforms | Natural-source vitamin alternatives bypass synthetic exclusion mandates in USDA Organic certification. |
| Direct Sourcing Relationship Cultivation | Venture-backed US startups prioritize transparent premix provenance over distributor intermediaries. |
| Subscription-Based Procurement Launch | Mid-size specialty brands displace spot-market purchasing with flexible minimum order quantities. |
| Blockchain Traceability Implementation | Near-infrared spectroscopy unification enables premium pricing for documented ingredient provenance. |
Research Methodology
Bottom-up pet food manufacturer procurement modeling reconciled against top-down micronutrient premix production tracking forms the analytical core of this study. Primary interviews with premix formulation scientists, regulatory affairs specialists at FDA Center for Veterinary Medicine, procurement directors at specialty pet food brands, and blending facility operations managers combined with secondary validation from EU Feed Hygiene Regulation compliance databases, EFSA feed additive re-evaluation submissions, USDA state feed control inspection records, and customs trade data on vitamin precursor imports.
Historical trendline analysis of premix inclusion rate evolution and automation adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled encompass product type chemistry, end-user species specificity, distribution channel structure, and application clinical positioning. CAGRs derived from weighted average of bottom-up demand aggregation and top-down supply capacity expansion trajectories, with specific inputs including precision dosing equipment installation rates and novel ingredient regulatory approval velocity.
The model holds under stable regulatory enforcement intensity and continued venture capital deployment into direct-to-consumer pet nutrition; deviation in FDA review timeline extension or Chinese precursor export restriction would shift forecast trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market