
 Poultry and Eggs Market | 2026-2036
Poultry and Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry and Eggs Market Insights
Foodservice is pivoting toward antibiotic-free and plant-fed poultry offerings as institutional buyers rewrite procurement specifications. Tyson Foods anchors North American supply through integrated breeding-to-processing operations across multiple states. Perdue Farms differentiates via organic and no-antibiotics-ever product lines that command shelf space in premium retail channels. Cal-Maine Foods dominates shell egg distribution through scale advantages in feed milling and layer house automation.
Poultry and eggs encompass avian species raised for meat and ovum production, with broilers reaching processing weight in approximately six to eight weeks and layer hens producing 250-300 eggs annually under commercial conditions. Broilers generate the highest volume throughput in product type terms, while layers capture disproportionate margin in branded and specialty egg segments. Foodservice channels are expanding fastest in distribution channel terms as quick-service chains and cloud kitchens standardize poultry-centric menus, though supermarkets retain the largest absolute value share through private-label and promotional bundling strategies.
The USDA enforces pathogen reduction and Hazard Analysis Critical Control Point standards that dictate slaughter facility design and microbiological testing protocols, while the FDA oversees egg safety rules requiring refrigeration and Salmonella prevention measures across layer operations. State-level cage-free mandates in California, Massachusetts, and Colorado are forcing capital redeployment toward aviary and enriched colony systems. Stakeholders must monitor how feed cost volatility and evolving welfare standards reshape the economics of scale versus regional sourcing flexibility.
Market Dynamics
EU cage-free mandates and parallel state-level requirements in the US are forcing integrators to redeploy capital toward aviary systems, restructuring the economics of layer housing and processing plant location decisions.
Growth Catalysts
- Foodservice menu expansion:Quick-service chains and cloud kitchens are standardizing poultry-centric offerings, pulling volume through dedicated supply contracts with integrated processors.
- EU welfare directives:The European Commission's cage-free transition timeline is accelerating capital flows toward enriched colony and free-range infrastructure investments.
- Export capacity buildout:Brazilian integrators are scaling processing plants to serve Middle Eastern and Asian buyers, redirecting trade flows from traditional Atlantic routes.
Market Restraints
- Feed input volatility:Corn and soybean meal price swings compress margin predictability for contract growers and independent producers alike.
- Slaughter capacity concentration:US broiler processing remains geographically concentrated in the Southeast, creating regional supply vulnerabilities during weather disruptions.
- Plant-based substitution:Cultivated and fermented protein alternatives are capturing shelf space in European retail, pressuring conventional poultry volume in premium channels.
Strategic Opportunities
- Underpenetrated Middle East markets:Saudi Arabia and UAE import dependency creates openings for Brazilian and US exporters with halal certification capabilities.
- Precision fermentation feed additives:Enzyme and probiotic supplementation is converging with automated climate control to reduce FCR and mortality rates.
- Direct-to-foodservice distribution:Bypassing traditional wholesale layers through dedicated cold-chain logistics is capturing margin previously absorbed by intermediaries.
Industry Challenges
- Veterinarian and technician shortages:Commercial layer and broiler operations face hiring gaps for flock health management and automated system maintenance.
- Aviary system retrofit complexity:Converting conventional cage facilities requires phased downtime that disrupts egg supply continuity and strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry and Eggs Market |
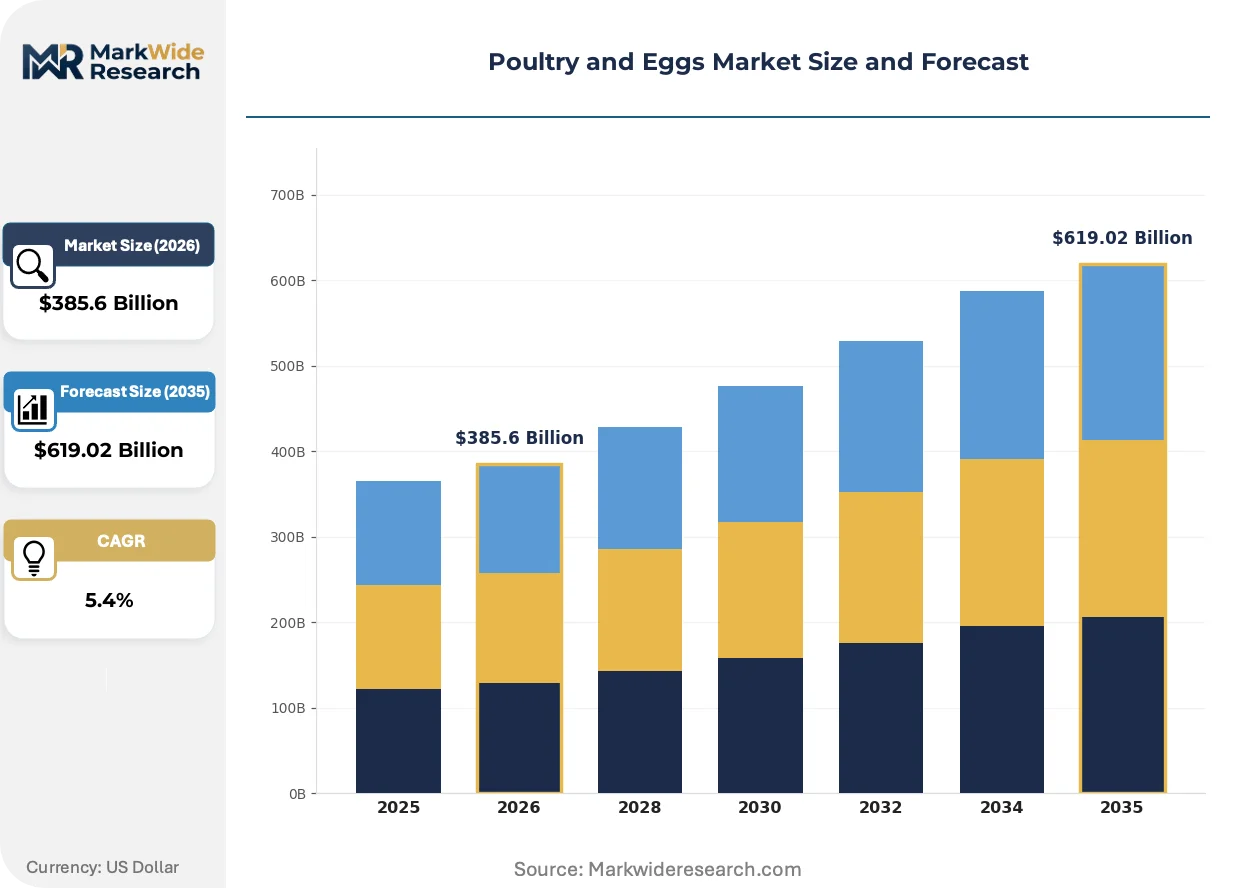
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $619.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Layers, Turkeys, Ducks End Use: Food Processing, Retail, Foodservice, Households Distribution Channel: Supermarkets, Wholesale, Direct Sales, Online Packaging Type: Plastic Wrap, Vacuum Pack, Cartons, Tray Packs |
| Companies Covered | Sysco Corporation, Tyson Foods, Perdue Farms, Pilgrim's Pride, Cal-Maine Foods, Sanderson Farms, Koch Foods, Mountaire Farms, Hubbard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry and Eggs Market Trends and Innovations
Automation and data analytics are penetrating breeding, feeding, and processing stages simultaneously, compressing cycle times and enabling mass customization of product specifications.
Computer vision-based grading and robotic deboning systems are rewriting throughput benchmarks in slaughter facilities. Tyson Foods and JBS are deploying these technologies at scale in US plants, reducing labor dependency while standardizing cut consistency. The structural consequence is a compression of unit economics that smaller processors struggle to match without equivalent capital deployment.
The EU's Farm to Fork Strategy under its Green Deal is mandating 25% reduction in antimicrobial use and accelerating welfare audit requirements. Layer operations across Germany, France, and the Netherlands are consolidating to amortize compliance costs. Specialty egg segments bearing organic and free-range labels are absorbing disproportionate investment as retailers preempt enforcement timelines.
Institutional procurement specifications are pivoting toward no-antibiotics-ever and slow-growth broiler commitments. Sodexo and Compass Group are rewriting supplier scorecards to favor integrated operators with verified welfare audit trails. This specification tightening is most visible in North American and Western European contract foodservice, where price premiums for compliant supply are stabilizing despite input cost pressures.
Poultry and Eggs Market Segmentation
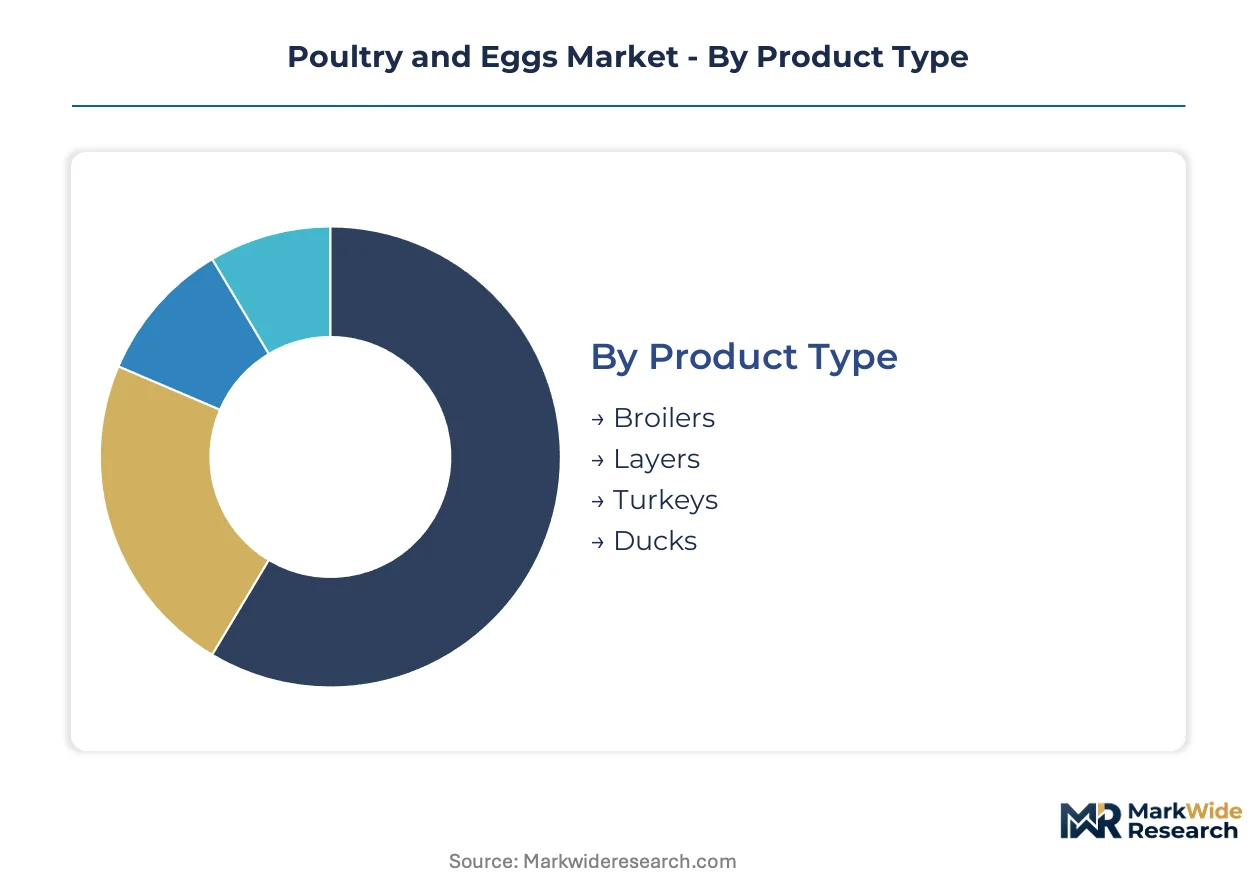
Poultry and eggs segmentation reveals how capital deployment, regulatory compliance, and channel economics fragment across distinct production systems. Each category carries specific margin structures and capital intensity profiles that reshape competitive positioning.
Product Type:
Supply concentration in breeding genetics and hatchery infrastructure shapes competitive dynamics across avian species, with integrators optimizing feed conversion ratios and processing yields to defend margin positions.
- Broilers:Meat-type chickens reaching processing weight in six to eight weeks through optimized genetics and automated feeding systems. Demand concentrates in quick-service chains across the United States and Brazil, where Tyson Foods and JBS secure dedicated supply contracts through integrated operations.
- Layers:Egg-producing hens yielding 250-300 eggs annually under commercial housing conditions. Investment is concentrating in cage-free and aviary systems across Germany, France, and the Netherlands as EFSA welfare directives and EU Green Deal timelines force capital redeployment.
- Turkeys:Seasonal demand peaks in North American retail channels, with Butterball and Cargill dominating processing capacity through geographically concentrated operations in the US Southeast.
- Ducks:Niche production serving Asian culinary traditions and European fine dining, with France and China maintaining distinct breeding stock and processing infrastructure.
Broilers absorb the bulk of installed capacity; layers are expanding most quickly through welfare-driven infrastructure conversion.
End Use:
Customer procurement specifications are rewriting supplier qualification requirements, with institutional buyers demanding verified audit trails that favor integrated operators over fragmented grower networks.
- Food Processing:Further-processed products including nuggets, patties, and ready-to-cook formats requiring standardized raw material specifications. Tyson Foods and Perdue Farms supply this channel through dedicated further-processing facilities in Arkansas and Georgia.
- Retail:Branded and private-label offerings competing on shelf placement and promotional bundling. Cal-Maine Foods dominates shell egg distribution through scale advantages in feed milling and automated layer house operations.
- Foodservice:Quick-service chains and contract caterers standardizing poultry-centric menus. Sodexo and Compass Group are rewriting supplier scorecards to favor no-antibiotics-ever and slow-growth commitments.
- Households:Direct consumption of whole birds and shell eggs through traditional retail and emerging subscription channels.
Food Processing commands the largest absolute volume; Foodservice is climbing the fastest as cloud kitchens and delivery platforms proliferate.
Distribution Channel:
Cold-chain infrastructure investment and last-mile logistics capabilities determine which channels can deliver shelf-stable quality without margin erosion from spoilage or temperature excursions.
- Supermarkets:Private-label and promotional bundling strategies retaining the largest value share through established cold-chain infrastructure and consumer traffic patterns.
- Wholesale:Intermediary layers absorbing margin that direct distribution models are increasingly bypassing through dedicated logistics investments.
- Direct Sales:Farm-to-table and regional processor models capturing premium pricing through shortened supply chains and freshness positioning.
- Online:Subscription and on-demand delivery platforms requiring specialized packaging and temperature-controlled fulfillment networks.
Supermarkets retain dominant share; Online is gaining share fastest through platform consolidation and delivery infrastructure buildout.
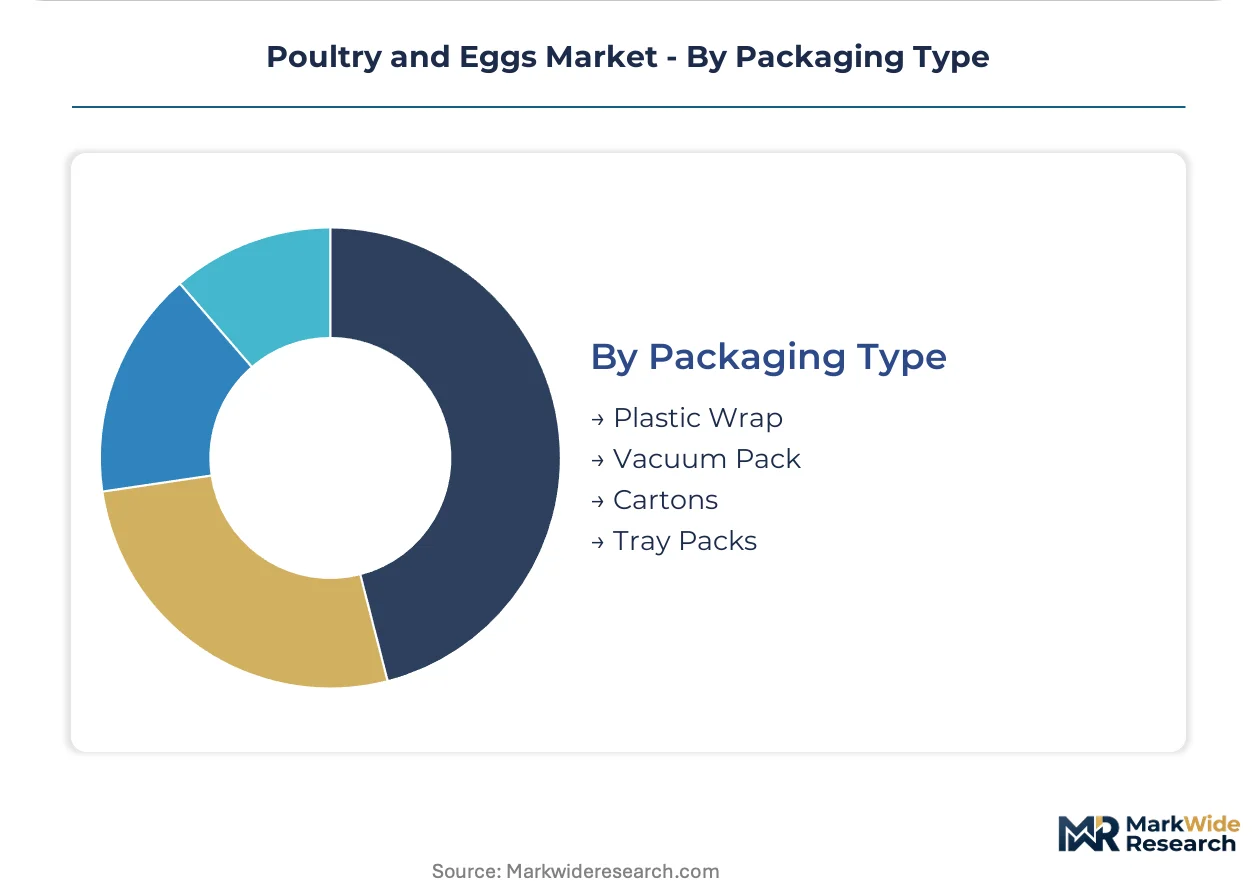
Packaging Type:
Shelf-life extension and retail presentation requirements drive material selection, with sustainability mandates from EU regulators and major retailers forcing transitions away from conventional plastics.
- Plastic Wrap:Conventional overwrap for tray-packed poultry, facing displacement from fiber-based alternatives under EU packaging waste directives.
- Vacuum Pack:Modified atmosphere packaging extending shelf life for case-ready retail programs and export shipments requiring extended distribution cycles.
- Cartons:Molded pulp and recycled fiber formats dominating shell egg distribution, with Cal-Maine Foods and Rose Acre Farms investing in automated carton forming equipment.
- Tray Packs:Multi-piece presentation formats for value-added poultry products, requiring precise portion control and label compliance for retail scanning.
Cartons absorb the bulk of egg-specific packaging volume; Vacuum Pack is expanding most quickly through case-ready meat programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports more poultry than any nation, yet domestic consumption lags production scale. The United States runs the opposite imbalance—massive internal demand absorbs most output. China and India balance both, with regional production clusters serving dense urban corridors.
United States
Quick-service chains and contract foodservice operators pull volume through dedicated supply agreements with integrated processors. USDA enforces pathogen reduction and HACCP standards that dictate slaughter facility design across Arkansas, Georgia, and Alabama. The Delmarva Peninsula concentrates layer operations where Cal-Maine Foods and Rose Acre Farms maintain automated facilities serving East Coast metropolitan markets.
Brazil
Export-oriented integrators scale processing capacity to serve halal-certified demand from Saudi Arabia and UAE buyers. ANVISA oversees sanitary protocols while the Ministry of Agriculture promotes trade access through bilateral agreements. The South-Central region around São Paulo and Paraná anchors breeding stock and hatchery infrastructure for Middle Eastern and Asian shipment routes.
China
Urbanization and dietary protein diversification drive broiler consumption in Yangtze River Delta and Pearl River Delta megacities. NMPA and SAMR enforce veterinary drug residue limits and food safety licensing. Shandong Province clusters industrial-scale layer houses serving Beijing-Tianjin-Hebei demand, with automated climate control systems reducing mortality in high-density operations.
Germany
Retail procurement specifications favor free-range and organic eggs as EFSA welfare directives force aviary system conversion. The EU Green Deal Farm to Fork Strategy mandates antimicrobial reduction targets. Lower Saxony and North Rhine-Westphalia consolidate layer operations to amortize compliance costs, with Dutch-German border regions sharing processing infrastructure.
India
Quick-service chain expansion and institutional catering standardize broiler demand in Maharashtra and Karnataka. FSSAI enforces food safety standards while state agricultural departments promote contract farming models. Telangana and Andhra Pradesh concentrate commercial layer houses with automated feeding systems serving Hyderabad and Chennai metropolitan markets.
Poultry and Eggs Market Competitive Landscape
Top-tier vendors anchor integrated breeding-to-processing operations, while mid-scale specialists concentrate on organic and welfare-certified segments. The structure rewards scale economies in feed milling and automated housing, yet leaves openings for regional players with direct foodservice relationships. Three archetypes dominate: multinational integrators with geographic diversification, national champions with state-level processing density, and premium specialists with certified product lines. Competitive moves center on backward integration into genetics and feed, plus direct-to-foodservice distribution bypassing wholesale layers.
Among US-based integrators, Tyson Foods and Perdue Farms occupy distinct positioning archetypes—Tyson exemplifies scale-driven vertical control, while Perdue represents premium-tier differentiation through no-antibiotics-ever commitments. Cal-Maine Foods anchors the layer segment with automation-heavy operations that exemplify capital-intensity defense. These three names illustrate how market structure separates volume leaders from margin defenders.
| Leading Market Players |
|---|
| Sysco Corporation |
| Tyson Foods |
| Perdue Farms |
| Pilgrim's Pride |
| Cal-Maine Foods |
| Sanderson Farms |
| Koch Foods |
| Mountaire Farms |
| Hubbard |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap processors in the US Southeast and Brazil's South-Central region anchor supply discipline through generational control of breeding stock and feed milling assets, translating operational continuity into pricing power during input volatility cycles.
Pricing Analysis
Cost-down pressure on conventional broiler tiers accelerates because Brazilian export integrators are absorbing freight and halal-certification overhead to capture Middle Eastern contract volumes. Pricing stratifies across premium no-antibiotics-ever, standard commodity, and economy private-label tiers, with certification grade and vertical integration status as primary differentiation drivers. Margin tightening in the standard tier reflects corn and soybean meal price swings that compress contract grower returns. Quick-service chains demonstrate highest price sensitivity through annual rebidding protocols, while European retail buyers absorb premiums for welfare-certified supply with limited volume elasticity.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale institutional demand through dedicated cold-chain logistics that bypass traditional wholesale layers. Geographic supply concentration centers on Brazil, the United States, and China, with the South-Central Brazilian cluster serving export routes to Saudi Arabia and UAE. Raw material dependencies rest on corn and soybean meal for feed formulation, plus veterinary pharmaceuticals for flock health management. Single-source vulnerability in breeding genetics creates structural risk, as proprietary broiler lines from Cobb-Vantress and Aviagen underpin global production. Distribution runs through integrated processor networks with captive hatchery-to-slaughter control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU cage-free mandates and parallel US state-level requirements are erecting capital barriers that favor incumbent integrators with balance-sheet capacity to fund aviary retrofits, effectively moating compliant players against undercapitalized challengers.
For Market Incumbents: Cement supply security through backward integration into feed milling and genetics operations, insulating margin structures from input volatility. Expand processing footprint in underpenetrated halal-certified export corridors to capture Brazilian trade flow redirection. Plant-based protein substitution in European retail channels represents the primary demand-side threat requiring defensive positioning through welfare-audit trail investments. For New Entrants and Emerging Players: Launch via direct-to-foodservice distribution models that bypass incumbent wholesale relationships through specialized cold-chain partnerships. Target Middle Eastern import dependency as the most penetrable geography, where Saudi Arabia and UAE procurement specifications favor halal-certified supply with limited established supplier density. Differentiate through precision fermentation feed additives that reduce feed conversion ratios and mortality rates. For Investors and Strategic Acquirers: ANVISA and USDA enforcement actions against sanitary violations at Brazilian and US Southeast processing facilities are the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Long-term viability favors integrators with demonstrated cage-free transition execution and verified welfare audit infrastructure. Monitor state-level mandate expansion beyond California, Massachusetts, and Colorado as the signal for accelerated capital deployment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Aviary System Retrofit | California and EU mandates force capital redeployment toward cage-free infrastructure to maintain market access. |
| Halal Certification Buildout | Brazilian integrators capture Saudi and UAE demand through ANVISA-compliant slaughter protocols and dedicated export capacity. |
| Precision Fermentation Feed Additives | Enzyme and probiotic supplementation reduces FCR and mortality rates in Tyson Foods and JBS deployment pilots. |
| Direct-to-Foodservice Cold Chain | Bypassing wholesale layers captures margin previously absorbed by intermediaries in Sodexo and Compass Group contracts. |
| Backward Integration into Genetics | Captive breeding stock control insulates supply continuity against proprietary line concentration risk at Cobb-Vantress. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with USDA slaughter facility reports, ANVISA sanitary inspection disclosures, and EU Commission welfare directive documentation providing foundational volume and trade flow benchmarks. Primary interviews with integrated processor operations executives, contract grower cooperative managers, veterinary flock health specialists, and foodservice procurement directors at institutional catering groups validated assumptions on capacity utilization and specification evolution. Bottom-up triangulation across state-level production data and top-down reconciliation with national consumption estimates ensured cross-verified outputs.
Granularity-level modeling disaggregated volume and value across product type (broilers, layers, turkeys, ducks), end-use application (food processing, retail, foodservice, households), and distribution channel (supermarkets, wholesale, direct sales, online) throughout the forecast period. CAGRs were derived from trend extrapolation of historical production capacity expansion rates, regulatory compliance cost trajectories, and feed input price correlation models. Industry-specific forecast inputs incorporated layer house automation adoption curves and cloud kitchen proliferation indices as demand-side drivers.
The model assumes a particular technology adoption path for automated climate control and computer vision grading systems; alternative pathways for robotic deboning deployment would alter the outlook for labor cost compression and processing throughput benchmarks. Forecasts reflect assumptions on cage-free transition timelines, veterinary drug residue enforcement intensity, and feed grain price volatility regimes. Periodic stress-testing of base assumptions is recommended given avian disease outbreak probabilities and trade policy disruption risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market