
 Animal Feed and Feed Additives Market | 2026-2036
Animal Feed and Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed and Feed Additives Market Analysis
Livestock procurement is consolidating among integrated meatpackers and large-scale dairy cooperatives across North America and Western Europe. Cargill leverages its grain origination networks to secure cost-advantaged feed formulations for contracted growers. BASF differentiates through precision nutrition platforms that optimize amino acid dosing in swine and poultry rations. Nutreco anchors aquaculture feed growth through its Skretting division, which dominates salmonid diets in Norway and Chile.
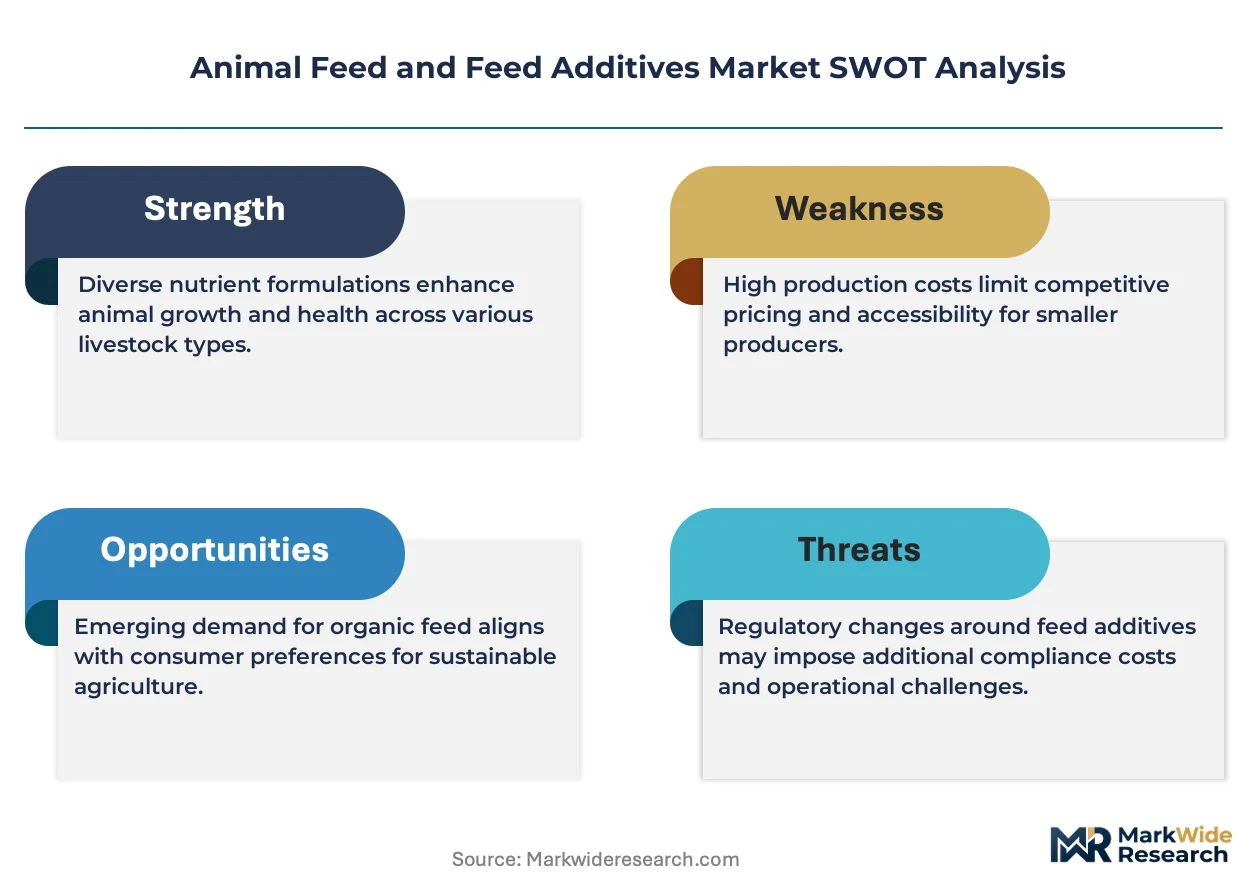
Animal feed and feed additives comprise formulated mixtures of cereals, protein meals, vitamins, minerals, and functional additives manufactured through grinding, pelleting, and extrusion processes to deliver specified metabolizable energy and digestible amino acid profiles for targeted livestock performance. The product type dimension shows complete feed occupying the dominant value share as integrators outsource formulation complexity, while specialty feed registers the fastest structural expansion driven by precision livestock farming adoption. Ingredients-based analysis reveals additives and nutritional supplements capturing disproportionate margin pools due to formulation IP and regulatory certification barriers.
The EU Green Deal's Farm to Fork strategy, enforced through EFSA residue limits and REACH chemical safety protocols, is tightening antibiotic growth promoter bans and mycotoxin thresholds across European supply chains. The US FDA's Veterinary Feed Directive and USDA organic certification standards shape product access and label premiums in North American markets. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning across export-oriented feed operations.
Market Dynamics
Consolidation among livestock integrators is compressing procurement channels and forcing feed suppliers to absorb margin pressure through captive formulation contracts and backward integration into grain origination.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Antibiotic growth promoter bans are accelerating demand for functional additives and precision nutrition platforms across European supply chains.
- Poultry belt concentration:Santa Catarina and Paraná in Brazil are driving volume pull for compound feeds as integrators expand slaughter capacity.
- Precision livestock farming:Sensor-based feeding systems are creating real-time demand for specialty feed segments that optimize amino acid dosing.
Market Restraints
- Grain price volatility:Corn and soybean meal input costs swing with Black Sea supply disruptions and US planting conditions, squeezing formulation margins.
- Regulatory fragmentation:Divergent residue limits between EFSA, FDA Veterinary Feed Directive, and REACH chemical safety protocols multiply compliance costs for export-oriented operations.
- Protein meal substitution:Insect meal and single-cell proteins remain cost-prohibitive at scale, limiting near-term displacement of soy and fishmeal.
Strategic Opportunities
- Aquaculture feed penetration:Salmonid and shrimp farming in Vietnam and Indonesia present underdeveloped demand for high-performance extruded diets.
- Carbon accounting integration:EU CSRD disclosure requirements are creating premium positioning for feed suppliers with verified Scope 3 emission reductions.
- Direct-to-farm digital channels:E-procurement platforms are bypassing traditional distributor networks in North American dairy cooperatives.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionists with metabolizable energy modeling expertise command premium compensation and limit R&D throughput.
- Certification timeline compression:Organic and non-GMO feed certifications require 24-36 month transition periods that strain working capital.
- Legacy mill retrofit costs:Pelleting and extrusion equipment upgrades for precision additive dosing demand seven-figure capital commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed and Feed Additives Market |
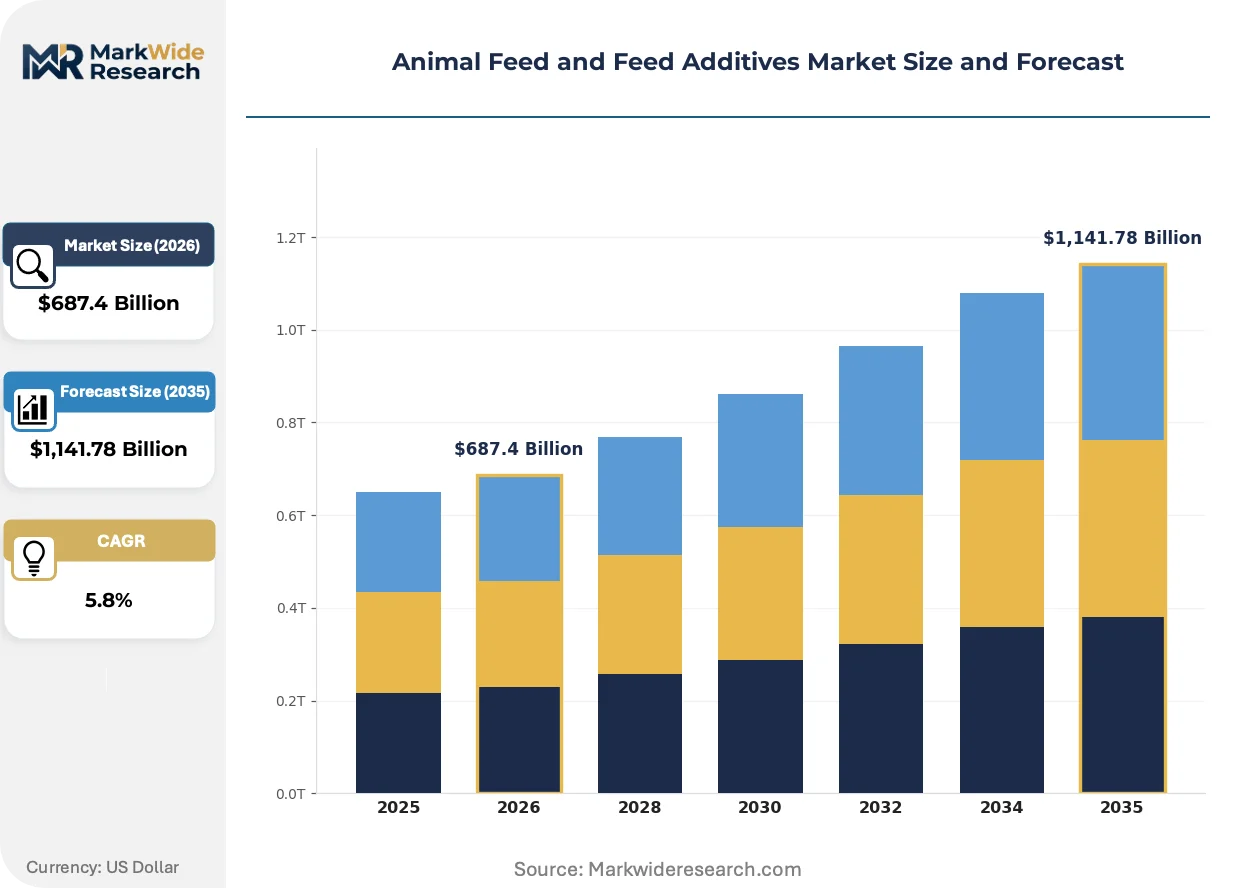
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,141.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Medicated Feed, Feed Supplements, Specialty Feed Ingredients: Cereals, Protein Meals, Additives, Nutritional Supplements Animal Type: Poultry, Ruminants, Swine, Aquaculture Form: Pellets, Mash, Liquid, Crumble |
| Companies Covered | Cargill, BASF, DSM, ADM, Evonik Industries, Nutreco, Kemin Industries, Adisseo, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed and Feed Additives Market Emerging Trajectories
Digital feeding systems and novel protein sources are restructuring how livestock integrators specify, procure, and verify feed performance across contract grower networks.
Enzyme-based digestibility enhancers are overtaking traditional acidifiers in swine and poultry rations. Large-scale integrators in Denmark and the Netherlands are adopting phytase and carbohydrase cocktails at commercial scale. This technology is overtaking mineral phosphate supplementation by reducing feed conversion ratios and manure phosphorus output.
REACH chemical safety protocols are tightening mycotoxin binder approval pathways across European compound feed manufacturing. EFSA residue limits now require expanded toxicity dossiers for clay-based and yeast-derived detoxifiers. Specialty additive suppliers are responding by consolidating formulation IP and pursuing dual registrations in multiple jurisdictions.
Contract growers are consolidating feed procurement decisions under integrator-controlled nutrition programs. Traditional independent feed dealers in Iowa and Minnesota are losing volume to captive supply agreements with meatpackers. This concentration is most visible in US broiler operations where Tyson and Pilgrim's Pride specify rations directly.
Animal Feed and Feed Additives Market Segmentation
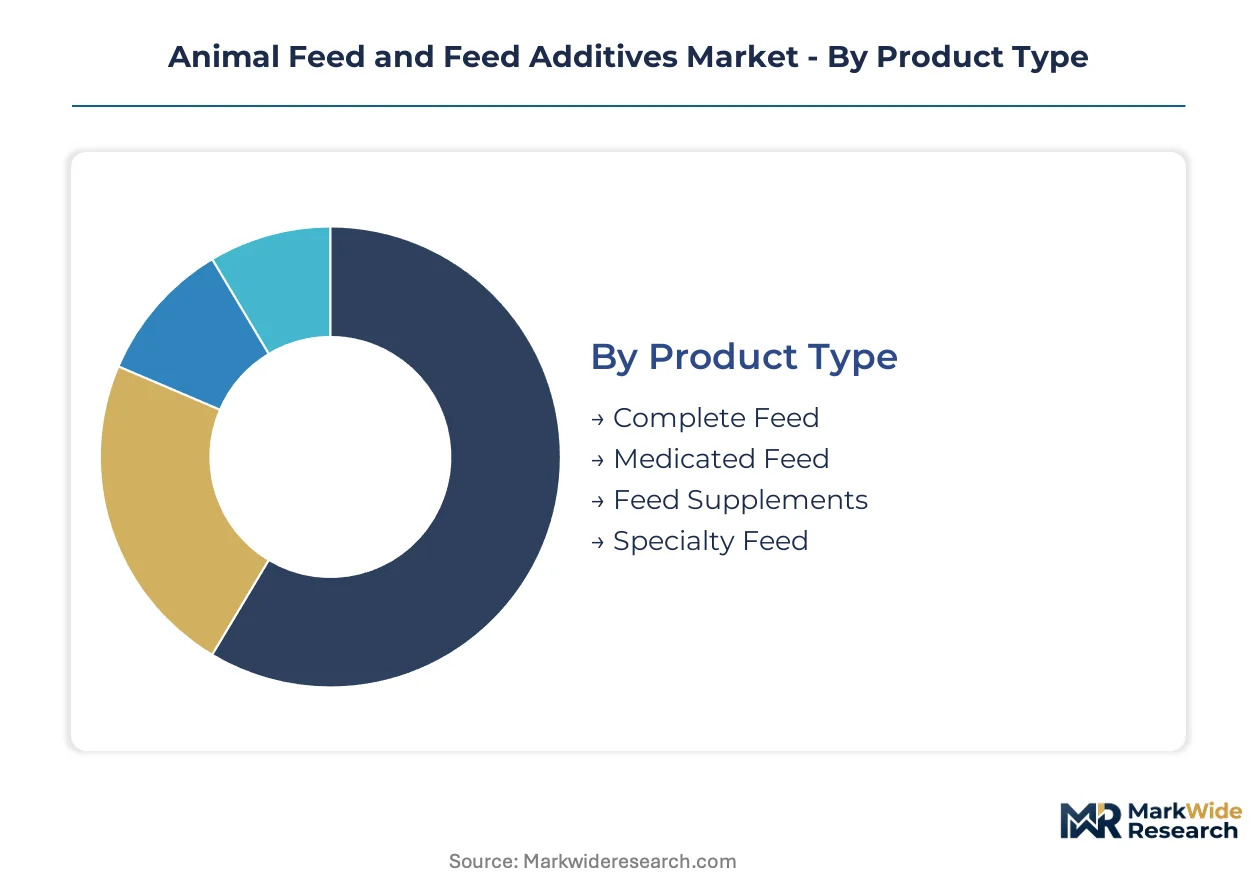
Feed segmentation determines procurement economics for livestock integrators. Product complexity, ingredient premiums, and delivery form dictate working capital requirements and formulation margins across contract grower networks.
Product Type:
Volume concentrates in mass-market formulations while premium capture shifts toward precision-dosed specialty products.
- Complete Feed:Fully formulated rations combining cereals, protein meals, and micronutrients into single-source procurement solutions. Integrators in Brazil's Santa Catarina poultry belt outsource entire nutrition programs to secure cost-advantaged supply contracts. Demand concentrates among large-scale broiler operations seeking procurement simplification.
- Specialty Feed:Precision-formulated diets targeting specific metabolic windows or production phases with enhanced amino acid profiles. Sensor-based feeding systems in Dutch and Danish operations create real-time demand for phase-specific formulations. This segment captures disproportionate margin pools through formulation IP.
- Medicated Feed:Veterinary prescription formulations incorporating coccidiostats or growth-promoting additives under FDA Veterinary Feed Directive compliance protocols.
- Feed Supplements:Concentrated nutrient packs designed for on-farm blending with base rations to customize metabolizable energy profiles.
Today's leader: Complete Feed. Tomorrow's challenger: Specialty Feed.
Ingredients:
Raw material sourcing strategy separates commodity traders from formulation specialists.
- Additives:Functional micro-ingredients including enzymes, acidifiers, and mycotoxin binders manufactured through fermentation and chemical synthesis. EFSA residue limits and REACH chemical safety protocols create regulatory certification barriers that protect margin pools. Yeast-derived and clay-based detoxifiers require expanded toxicity dossiers for European approval.
- Protein Meals:Soybean meal, rapeseed meal, and fishmeal providing digestible amino acid foundations for growth-phase optimization. Black Sea supply disruptions and US planting conditions drive input cost volatility that squeezes formulation margins.
- Cereals:Corn, wheat, and barley delivering metabolizable energy density through grinding and pelleting processes.
- Nutritional Supplements:Vitamin and mineral premixes manufactured to precise inclusion specifications for species-specific requirements.
Additives command the steepest expansion trajectory as antibiotic growth promoter bans accelerate functional alternative demand.
Animal Type:
Species-specific digestive physiology dictates formulation complexity and regulatory compliance burden.
- Poultry:High-density broiler and layer rations optimized for rapid feed conversion ratios through precision amino acid dosing. Santa Catarina and Paraná integrators drive volume pull as slaughter capacity expands across Brazil's poultry belt.
- Aquaculture:Extruded floating and sinking diets for salmonid and shrimp species requiring precise lipid and protein profiles. Norway and Chile anchor demand for high-performance Skretting formulations, while Vietnam and Indonesia present underdeveloped penetration opportunities.
- Ruminants:Forage-based and total mixed rations formulated for dairy cooperatives and beef feedlot operations across North American markets.
- Swine:Phase-feeding programs targeting nursery, grower, and finisher stages with optimized digestible lysine and phosphorus matrices.
Poultry dominates procurement volumes. Aquaculture claims the fastest share gains.
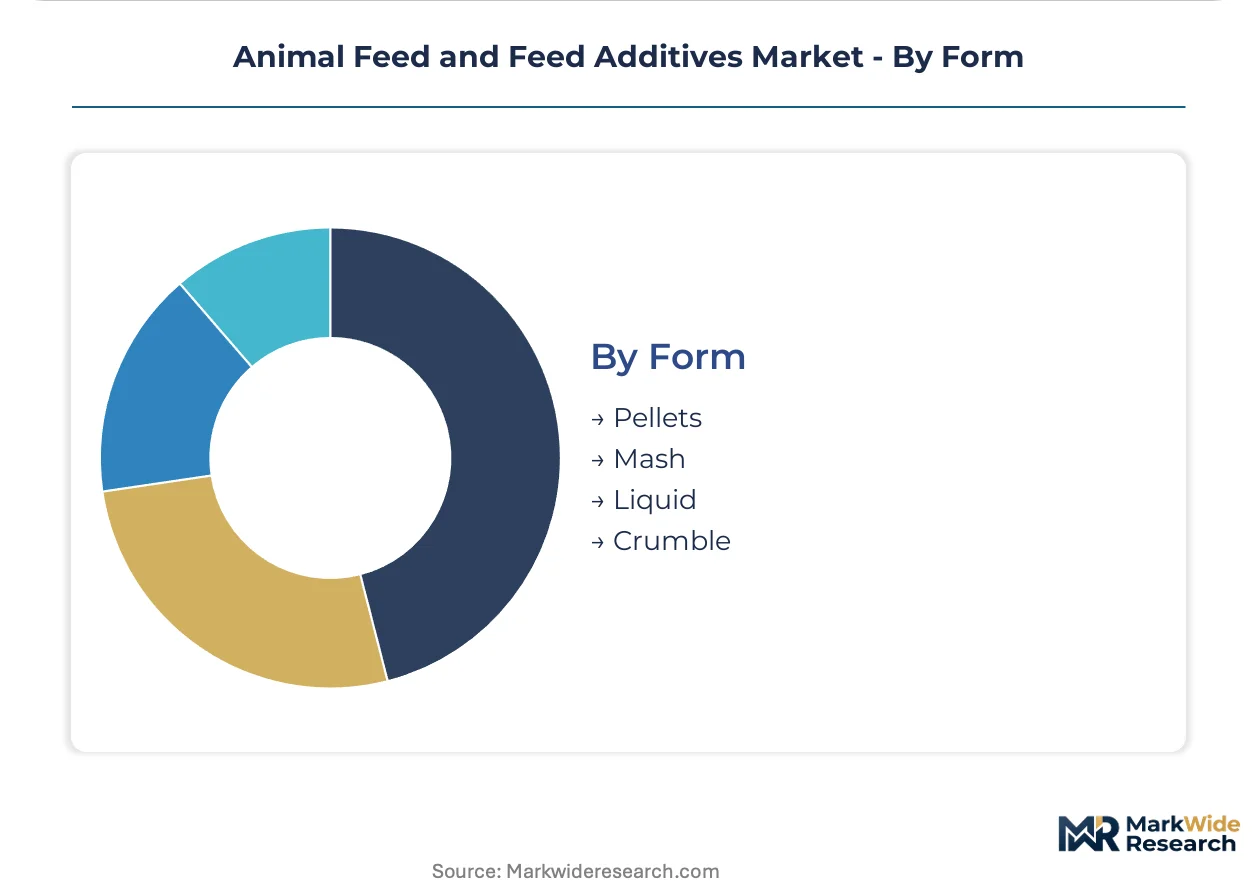
Form:
Physical processing determines storage logistics, feed conversion efficiency, and equipment capital requirements.
- Pellets:Compressed cylindrical forms manufactured through conditioning and pelleting processes that improve feed conversion ratios and reduce waste. Large-scale integrators specify pelleted rations to minimize segregation during transport and optimize intake uniformity.
- Mash:Ground and mixed dry feeds retaining ingredient particle integrity for species requiring texture variation or on-farm customization.
- Liquid:Suspended or dissolved nutrient solutions delivered through automated pipeline systems for high-volume dairy and swine operations.
- Crumble:Broken pellet fragments sized for starter-phase poultry and young animals with limited intake capacity.
Pellets anchor integrator procurement specifications. Crumble gains traction in precision starter-phase programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Santa Catarina poultry belt generates denser compound feed demand than Germany's Lower Saxony dairy corridor, yet both regions face tightening residue protocols that reshape supplier qualification requirements.
United States
Integrated meatpackers in Iowa and Minnesota consolidate procurement through captive nutrition programs that displace independent feed dealers. FDA Veterinary Feed Directive compliance shapes prescription access for medicated formulations. Tyson and Pilgrim's Pride specify pelleted rations directly across the US broiler belt.
Brazil
Slaughter capacity expansion in Paraná and Santa Catarina accelerates volume pull for cost-advantaged soy-based formulations. ANVISA monitors antibiotic residue thresholds under Mercosur harmonization pressure. Integrators around Chapecó outsource entire nutrition programs to secure supply contracts.
Germany
Precision livestock farming adoption in Lower Saxony creates demand for phase-specific amino acid dosing platforms. EFSA residue limits and REACH chemical safety protocols tighten mycotoxin binder approval pathways. BASF leverages Ludwigshafen formulation expertise to serve Dutch and Danish integrator networks.
China
Swine restocking after ASF outbreaks concentrates demand in Sichuan and Henan provinces. SAMR enforces GB standards for feed additive safety and antibiotic growth promoter restrictions. Yangtze River Delta integrators adopt sensor-based feeding systems for real-time ration adjustment.
Norway
Salmonid farming in Trøndelag and Vestland drives premium demand for high-performance extruded diets. EFSA and national regulators coordinate on fishmeal substitution thresholds for sustainable aquaculture certification. Skretting anchors formulation supply across Norwegian fjord systems.
Animal Feed and Feed Additives Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier base. Grain origination networks and fermentation-based additive manufacturing create distinct capability moats. Three archetypes dominate: integrated agribusinesses with captive supply chains, precision nutrition platforms with formulation IP, and regional compounders with logistics density. Consolidation proceeds through backward integration into grain origination and strategic partnerships for novel protein sourcing.
Among diversified agribusinesses, Cargill and ADM represent scale-driven procurement consolidation. BASF and DSM exemplify the precision nutrition archetype through amino acid and enzyme platform positioning. Nutreco anchors aquaculture specialization through its Skretting division structure.
| Leading Market Players |
|---|
| Cargill |
| BASF |
| DSM |
| ADM |
| Evonik Industries |
| Nutreco |
| Kemin Industries |
| Adisseo |
| Alltech |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's Farm to Fork strategy gates qualified supply and premium-tier pricing access by mandating antibiotic-free certification and residue documentation across European compound feed procurement channels.
Pricing Analysis
Capacity additions in Brazil's Santa Catarina poultry belt are reshaping price floors for soy-based formulations. Contract-based long-term offtake dominates integrator procurement, with price differentiation separating organic-certified rations from conventional formulations. Pricing pressure stems from Black Sea grain volatility squeezing formulation margins. Independent feed dealers in Iowa show highest price sensitivity; Norwegian salmonid integrators exhibit lowest sensitivity due to performance-linked premium positioning.
Supply Chain Analysis
Corn and soybean meal supply rests on US, Brazil, and Argentina origination networks. Fermentation-derived enzymes, clay-based mycotoxin binders, and fishmeal constitute critical input dependencies. Single-source vulnerability concentrates in Black Sea wheat corridors disrupted by export instability. Distribution runs through integrator-controlled nutrition programs that displace traditional dealer networks across North American broiler operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU Green Deal's antibiotic growth promoter bans create structural demand for functional additive substitutes.
For Market Incumbents: Acquire fermentation-based additive manufacturing assets to secure formulation IP moats against single-cell protein entrants. BASF and DSM have anchored precision nutrition platforms through amino acid synthesis capabilities. Cargill's grain origination networks defend against backward integration moves by Tyson and Pilgrim's Pride. Certification investment in REACH-compliant mycotoxin binders protects European margin pools. For New Entrants and Emerging Players: Sensor-based dosing algorithms offer technology-first wedge into Dutch and Danish precision livestock farming installations. Vietnam and Indonesia aquaculture feed present the most penetrable white-space with underdeveloped extruded diet supply. Direct-to-farm digital procurement channels bypass legacy distributor networks in North American dairy cooperatives. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with logistics density because integrator consolidation compresses procurement channels toward captive suppliers. Five-to-ten year viability hinges on carbon accounting integration for EU CSRD disclosure premiums. Watch for salmonid farming expansion in Vietnam as inflection indicator for aquaculture feed platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill leverages Brazilian soy networks to secure cost-advantaged feed formulations for contracted growers. |
| Precision Nutrition Platform Development | BASF's Ludwigshafen amino acid dosing expertise serves Dutch and Danish integrator networks. |
| Aquaculture Feed Capacity Expansion | Skretting anchors Norwegian fjord systems while targeting underdeveloped Vietnam and Indonesia demand. |
| Carbon Accounting Certification Program | EU CSRD disclosure requirements create premium positioning for verified Scope 3 emission reductions. |
| Direct-to-Farm Digital Channel Launch | E-procurement platforms bypass traditional distributor networks in Iowa and Minnesota dairy cooperatives. |
Methodological Framework
Bottom-up livestock integrator modeling reconciled against top-down additive manufacturing tracking forms the analytical core. Primary interviews with veterinary nutritionists, procurement leads at meatpackers, plant managers at compound feed mills, and regulatory affairs specialists at EFSA and FDA combine with secondary validation from customs/trade data, SEC 10-K filings, and ANVISA residue monitoring reports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of feed conversion ratios and amino acid inclusion rates informs projection frameworks across the modeling period. Segmentation dimensions include product type complexity, ingredient premium tiers, species-specific digestive physiology, and physical processing form. CAGRs derive from integrating integrator capacity expansion schedules with regulatory compliance cost trajectories. Black Sea grain supply volatility and precision livestock farming adoption curves constitute key forecast inputs.
The model holds under stable regulatory enforcement trajectories; deviation in EFSA mycotoxin threshold revisions or FDA Veterinary Feed Directive scope expansions would shift additive demand profiles. Forecasts reflect documented assumptions about integrator consolidation pace and novel protein cost curves. A small set of named triggers warrants ongoing watch: ASF recurrence in China, REACH chemical safety protocol amendments, and carbon border adjustment mechanism implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Eggs Market