
 Non-Protein Nitrogen in Feed Market | 2026-2036
Non-Protein Nitrogen in Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Protein Nitrogen in Feed Market Analysis
Dairy cattle nutrition is shifting toward higher NPN inclusion rates as milk producers face margin pressure from conventional protein costs. Yara International ASA leverages its integrated ammonia supply chain to dominate bulk urea deliveries across Nordic dairy cooperatives. Cargill Incorporated anchors its position through controlled-release biuret formulations that reduce rumen ammonia spikes. Nutrien Ltd competes by extending its retail agronomy network into direct-to-farmer feed-grade nitrogen distribution.
Non-protein nitrogen in feed encompasses synthetic nitrogenous compounds, principally urea and ammonium nitrate, that rumen microbes convert to microbial protein without supplying true protein substrates; typical urea inclusion rates range from 0.5% to 1.0% of total dry matter to avoid ammonia toxicity. Urea formulations occupy the largest volume share due to decades of proven efficacy and lowest cost per unit nitrogen, though biuret variants command premium positioning in automated feeding systems where dust control and slower ammonia release improve handler safety and intake consistency. Among applications, beef cattle finishing operations represent the fastest-growing demand pool as pasture-to-feedlot transitions accelerate in tropical regions with limited oilseed processing infrastructure.
The United States Environmental Protection Agency enforces Clean Water Act discharge permits that limit nitrogen runoff from concentrated animal feeding operations, while the Food and Drug Administration's Center for Veterinary Medicine monitors feed additive safety thresholds. Brazil's Ministry of Agriculture livestock department and India's Bureau of Indian Standards both maintain maximum allowable NPN concentrations in compounded feeds, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving ammonia emissions caps and precision-feeding technology maturation to determine whether to invest in slow-release formulations or bulk commodity positioning.
Market Dynamics
Feed-grade urea supply chains are compressing as integrated ammonia producers capture margin pools previously held by independent blenders, while precision-feeding hardware adoption forces reformulation of slow-release nitrogen compounds.
Growth Catalysts
- EU F-Gas Regulation:Ammonia emissions caps on livestock operations in the Netherlands and Denmark are accelerating demand for controlled-release biuret formulations that reduce rumen ammonia spikes.
- Automated feeding systems:Large-scale dairy cooperatives in Wisconsin and Minnesota are retrofitting bunkers with sensor-driven delivery mechanisms that require dust-free, free-flowing nitrogen sources.
- Pasture-to-feedlot transitions:Brazilian beef finishing operations in Mato Grosso are expanding NPN supplementation as local oilseed crushing capacity lags behind herd growth.
Market Restraints
- Natural gas price volatility:Urea synthesis depends on ammonia feedstock whose production costs swing with European and Asian natural gas benchmarks, compressing blender margins during price spikes.
- Handler safety thresholds:OSHA permissible exposure limits for ammonia vapors during feed mixing constrain inclusion rates and require capital-intensive ventilation systems at smaller operations.
- True protein substitution:Distillers dried grains from ethanol plants compete directly with NPN in Midwest cattle rations when corn processing margins favor fuel over feed.
Strategic Opportunities
- India's compound feed deficit:Bureau of Indian Standards regulations cap NPN inclusion, yet organized dairy sector expansion in Gujarat and Punjab creates demand for compliant slow-release formulations.
- Carbon credit monetization:EU Green Deal farm-to-fork targets reward methane-reduction practices, positioning precision NPN dosing as a verifiable emissions mitigation pathway.
- Blockchain-enabled traceability:Feed cooperatives in Denmark are piloting distributed ledger systems that verify nitrogen source origin for export certification to Middle Eastern dairy importers.
Industry Challenges
- Rumen microbiology expertise:Formulation chemists who understand microbial protein synthesis rates remain scarce relative to demand for customized NPN blends across tropical beef systems.
- Retrofit capex burdens:Existing feed mills require pneumatic handling upgrades to manage hygroscopic urea without caking, straining capital allocation at mid-sized operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Protein Nitrogen in Feed Market |
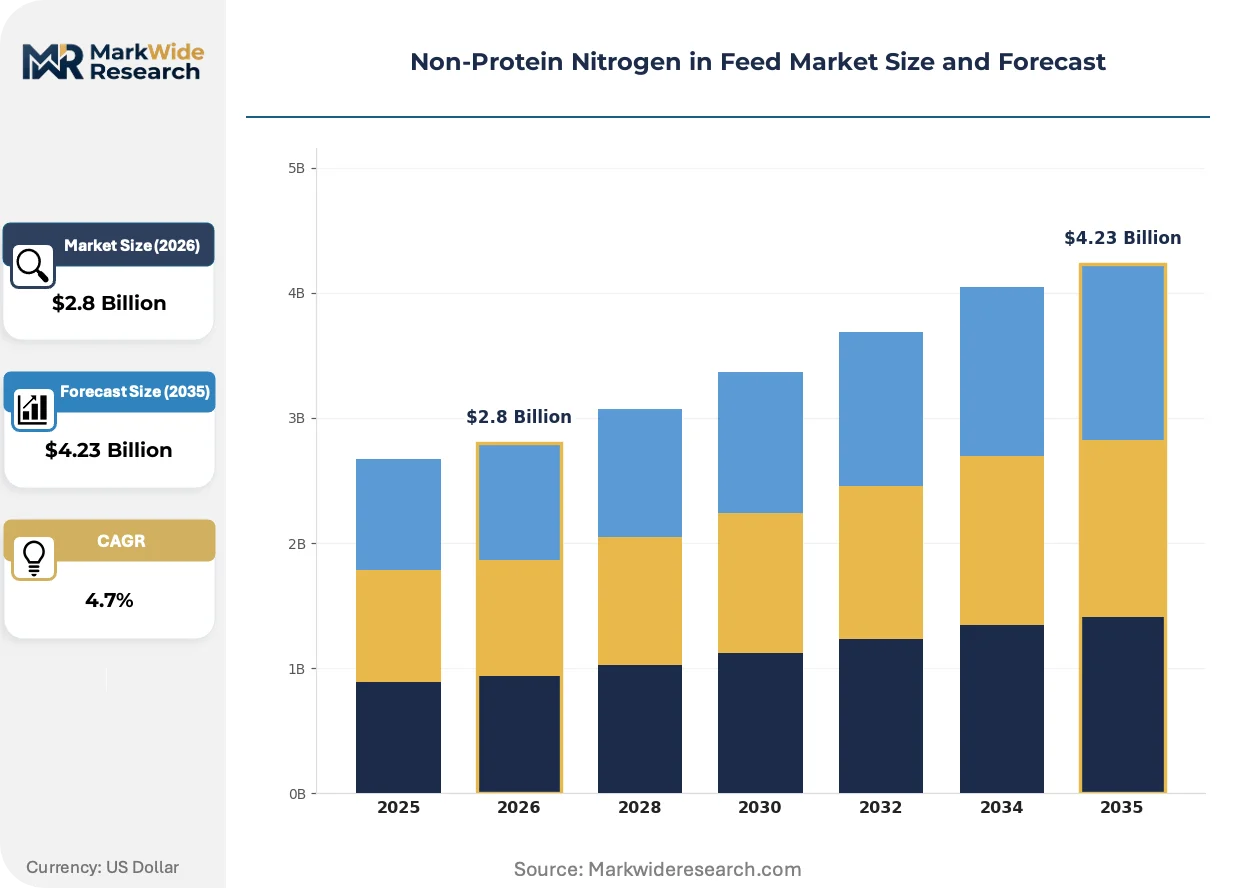
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Calcium Ammonium Nitrate, Biuret Application: Dairy Cattle, Beef Cattle, Poultry, Swine Form: Granular, Powdered, Liquid, Tablet End User: Farmers, Feed Manufacturers, Livestock Producers, Agricultural Cooperatives |
| Companies Covered | Yara International ASA, Alltech Inc, Archer Daniels Midland Company, ADM Animal Nutrition, Cargill Incorporated, Kemin Industries Inc, Nutrien Ltd, Incitec Pivot Ltd, CF Industries Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Protein Nitrogen in Feed Market Emerging Trajectories
Digital feeding technologies and emissions monitoring protocols are converging to redefine how nitrogen compounds are dosed, tracked, and verified across livestock supply chains.
Coated urea granules with polymer membranes are consolidating market share among automated feeding operations by synchronizing ammonia release with rumen microbial activity peaks. Dairy cooperatives in the Netherlands and Denmark have adopted these formulations at scale since F-Gas Regulation enforcement tightened. The technology is consolidating supplier margins toward integrated ammonia producers who control both base chemical and encapsulation chemistry.
REACH registration requirements for feed additive intermediates are extending compliance timelines for novel nitrogen compounds entering the European market. Formulators must submit extended toxicity dossiers that delay commercialization by 18-24 months relative to other regions. Specialty chemical suppliers are responding by prioritizing biuret variants with existing safety profiles over experimental slow-release chemistries.
Direct-to-farm nitrogen procurement through agronomy retail networks is displacing traditional feed dealer channels in North American corn belt states. Nutrien Ltd and similar suppliers now bundle feed-grade urea with crop nutrient programs, capturing cattle producer relationships previously held by independent feed mills. This channel compression is most visible in Iowa and Illinois, where integrated crop-livestock operations favor single-supplier logistics.
Non-Protein Nitrogen in Feed Market Segmentation
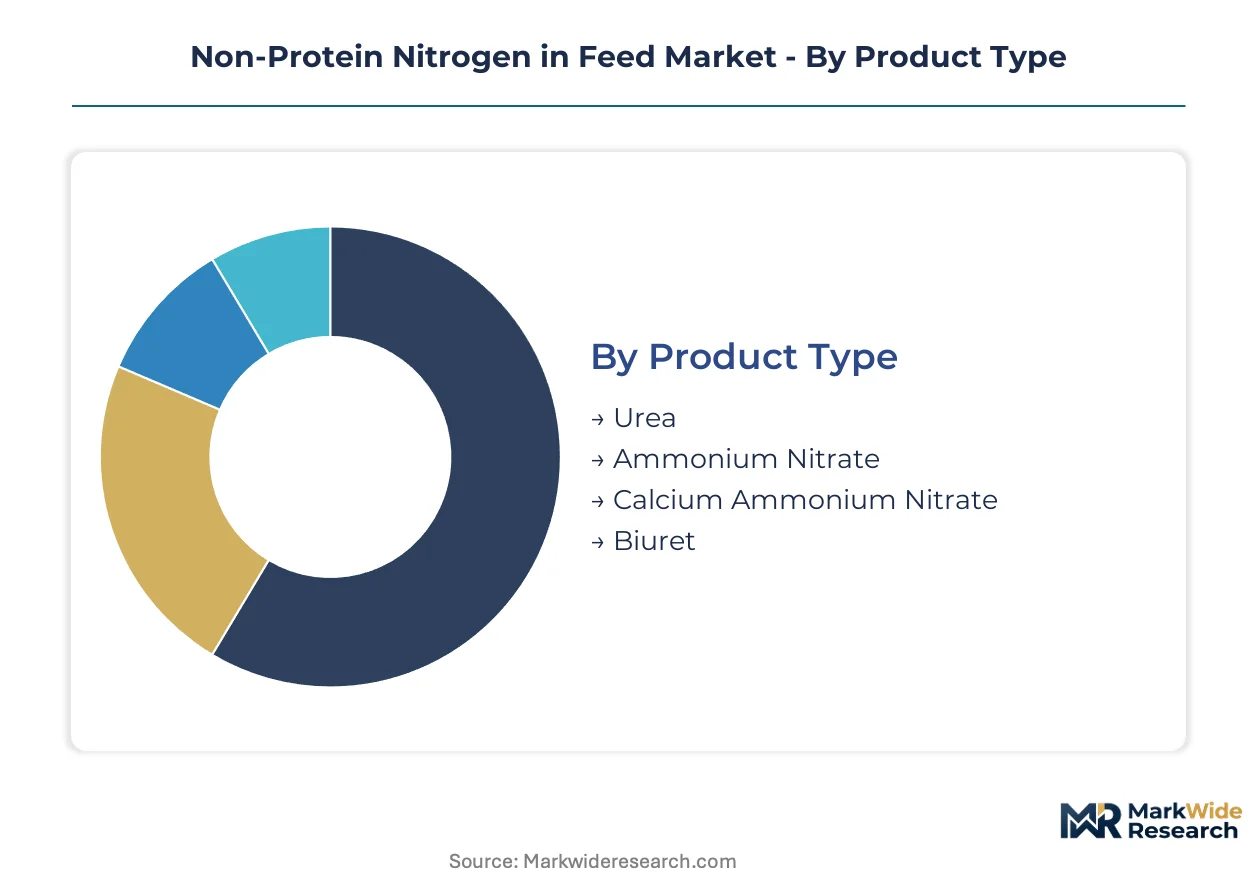
Non-protein nitrogen in feed markets segment across four dimensions that determine formulation chemistry, delivery economics, and regulatory compliance. Buyers differentiate by protein cost pressure, animal physiology, handling infrastructure, and procurement scale.
Product Type:
Cost per unit nitrogen and rumen safety profile separate buyers across synthetic nitrogen sources.
- Urea:Synthetic crystalline compound containing 46% nitrogen by weight; rumen microbes hydrolyze it to ammonia for microbial protein synthesis. Demand concentrates in Brazilian Mato Grosso feedlots where oilseed crushing deficits force cost-driven protein substitution. Inclusion rates stay below 1% dry matter to prevent toxicity.
- Biuret:Condensation dimer of urea with slower ammonia release kinetics and reduced handler exposure risk. Automated dairy operations in Wisconsin and Minnesota specify dust-free biuret for sensor-driven feeding systems where precision dosing limits rumen ammonia spikes.
- Ammonium Nitrate:Dual-purpose nitrogen source with oxidizing properties requiring specialized storage protocols; finds limited feed use amid handler safety constraints.
- Calcium Ammonium Nitrate:Limestone-ammonium nitrate blend with lower nitrogen concentration and improved handling stability; niche positioning in regions with humid storage conditions.
Urea leads volumes today; biuret is gaining share fastest.
Application:
Ruminant versus monogastric physiology dictates nitrogen metabolism efficiency and regulatory scrutiny intensity.
- Beef Cattle:Finishing operations in Brazil's Cerrado biome drive bulk urea consumption as pasture-to-feedlot transitions accelerate. Tropical regions lack oilseed processing infrastructure, forcing reliance on synthetic nitrogen for protein supplementation.
- Dairy Cattle:High-producing herds in Denmark and the Netherlands face EU F-Gas Regulation ammonia emissions caps. Controlled-release formulations reduce environmental discharge while maintaining milk yield targets.
- Poultry:Monogastric birds utilize non-protein nitrogen poorly; minimal inclusion rates apply only during specific growth phases with microbial additive support.
- Swine:Similar metabolic constraints to poultry limit NPN to experimental rations; true protein sources dominate commercial formulations.
Beef cattle applications anchor current demand; dairy operations show steepest expansion trajectory.
Form:
Handling infrastructure investment and climate exposure determine physical specification preferences.
- Granular:Free-flowing spherical particles resist caking in humid conditions; pneumatic conveying systems at commercial feed mills specify this grade for automated batching.
- Powdered:Fine crystalline form enables rapid dissolution in liquid feed supplements; dust generation requires enclosed mixing systems and respiratory protection.
- Liquid:Aqueous urea solutions eliminate inhalation exposure and enable direct injection into total mixed rations; tank storage and metering equipment demands capital investment.
- Tablet:Compressed slow-release units for precision-fed individual animals; limited scale due to manufacturing cost premium.
Granular forms dominate commodity volume; liquid formulations climb fastest in automated operations.
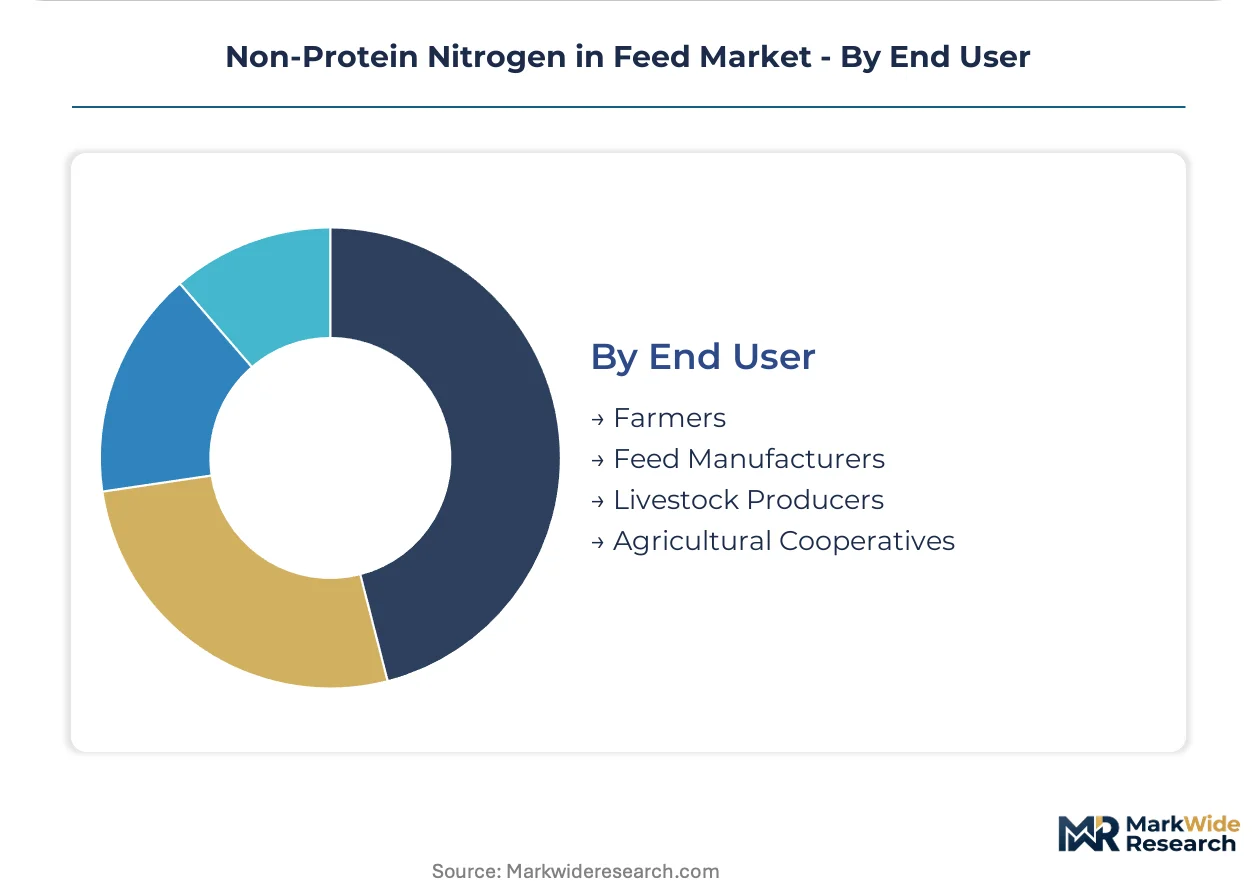
End User:
Procurement scale and technical capability separate buyers across the value chain.
- Feed Manufacturers:Compound feed mills with in-house nutritionists formulate customized NPN blends; FDA Center for Veterinary Medicine compliance documentation requirements favor established operations.
- Agricultural Cooperatives:Member-owned buying groups in Iowa and Illinois leverage crop nutrient supplier relationships for bundled feed-grade nitrogen procurement.
- Livestock Producers:Integrated crop-livestock operations with on-farm mixing capacity purchase bulk urea directly; OSHA ammonia vapor exposure limits constrain small-scale handling.
- Farmers:Fragmented smallholders rely on dealer channels with limited technical support; price sensitivity drives commodity urea purchases.
Feed manufacturers command premium formulation margins; agricultural cooperatives expand procurement share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling production capacity toward jurisdictions with lower ammonia-handling compliance costs while demand concentrates where protein substitution economics prove most compelling.
United States
Dairy cooperatives in Wisconsin and Minnesota retrofit automated feeding systems that demand dust-free biuret formulations. The EPA enforces Clean Water Act discharge permits limiting nitrogen runoff from concentrated animal feeding operations. Bulk urea procurement concentrates in Iowa and Illinois where integrated crop-livestock operations favor single-supplier logistics.
Brazil
Beef finishing operations in Mato Grosso and Goiás states drive bulk urea consumption as pasture-to-feedlot transitions accelerate. ANVISA maintains maximum allowable NPN concentrations in compounded feeds, creating compliance burdens for multinational suppliers. Large-scale feedlots in the Cerrado biome rely on synthetic nitrogen amid local oilseed crushing deficits.
India
Organized dairy sector expansion in Gujarat and Punjab creates demand for compliant slow-release formulations. The Bureau of Indian Standards caps NPN inclusion rates, forcing reformulation for formal market channels. Compound feed deficit conditions persist despite regulatory constraints on synthetic nitrogen use.
Denmark
High-producing dairy herds face EU F-Gas Regulation ammonia emissions caps that accelerate controlled-release biuret adoption. The EU Green Deal farm-to-fork targets reward methane-reduction practices through precision NPN dosing. Dairy cooperatives pilot blockchain-enabled traceability systems verifying nitrogen source origin for Middle Eastern export certification.
Netherlands
Livestock operations confront tightening ammonia emissions standards under EU F-Gas Regulation enforcement. Coated urea granules with polymer membranes consolidate market share by synchronizing ammonia release with rumen microbial activity peaks. Precision-feeding hardware adoption forces reformulation of slow-release nitrogen compounds across commercial dairy operations.
Non-Protein Nitrogen in Feed Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated ammonia producers capture margin pools previously held by independent blenders. The vendor base stratifies between bulk commodity suppliers and specialty formulation houses with encapsulation chemistry capabilities. Three archetypes define positioning: integrated ammonia producers controlling base chemical supply, agronomy retailers extending into feed-grade distribution, and controlled-release specialists with polymer membrane technology. M&A activity and backward integration into ammonia feedstock represent the dominant competitive vectors reshaping supply chain economics.
Within the integrated producer tier, Yara International ASA anchors Nordic dairy cooperative supply relationships through captive ammonia infrastructure. Cargill Incorporated and Nutrien Ltd exemplify divergent channel strategies—Cargill leverages controlled-release biuret formulations for automated feeding systems while Nutrien extends retail agronomy networks into direct-to-farmer feed-grade nitrogen distribution. These three entities collectively represent the scale-driven, specialty-formulation, and channel-compression archetypes competing for procurement relationships across North American and European dairy operations.
| Leading Market Players |
|---|
| Yara International ASA |
| Alltech Inc |
| Archer Daniels Midland Company |
| ADM Animal Nutrition |
| Cargill Incorporated |
| Kemin Industries Inc |
| Nutrien Ltd |
| Incitec Pivot Ltd |
| CF Industries Holdings Inc |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation ammonia emissions caps in Denmark and the Netherlands are forcing dairy cooperatives toward controlled-release biuret formulations, compelling integrated ammonia producers to absorb encapsulation chemistry costs while compressing independent blender margins.
Pricing Analysis
Distributor markups on feed-grade urea compress as agronomy retailers bundle nitrogen procurement with crop nutrient programs. Three-tier pricing structure across premium, standard, and economy levels separates coated biuret formulations from granular urea and commodity-grade ammonium nitrate. Price differentiation stems from certification grade and volume scale, with automated dairy operations in Wisconsin and Minnesota showing least price sensitivity. Cost compression in bulk urea intensifies because natural gas feedstock volatility transfers directly to blender margins.
Supply Chain Analysis
Brazil's ANVISA domestic-content mandates for compounded feeds are reshaping sourcing toward local blending capacity even as ammonia feedstock concentrates in Trinidad, Qatar, and Russia. Raw material dependencies rest on natural gas benchmarks, ammonia synthesis catalysts, and polymer encapsulation resins. Single-source vulnerability runs through integrated ammonia producers controlling both base chemical and coating technology. Distribution runs through agronomy retail networks displacing traditional feed dealer channels in Iowa and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shift toward controlled-release formulations that command handler-safety premiums and emissions-compliance value capture.
For Market Incumbents: Deploy backward integration into ammonia feedstock to defend against natural gas volatility and integrated producer encroachment. Capture Nordic dairy cooperative relationships through captive supply infrastructure. Counter the threat of precision-feeding hardware vendors by acquiring coating chemistry capabilities that lock in formulation differentiation. For New Entrants and Emerging Players: Agricultural cooperatives in the North American corn belt represent the most penetrable channel archetype. Target India's organized dairy sector in Gujarat and Punjab where Bureau of Indian Standards caps create compliant-formulation white space. Establish go-to-market positioning through blockchain-enabled traceability pilots that satisfy Middle Eastern export certification demands. For Investors and Strategic Acquirers: Asymmetric upside sits with controlled-release specialists possessing polymer membrane technology and existing REACH registration dossiers. Long-term viability over the projection horizon favors suppliers with dual capability in base ammonia production and encapsulation chemistry. Watch for EU Green Deal farm-to-fork target acceleration as the inflection signal for carbon credit monetization pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Yara International ASA leverages captive Nordic ammonia infrastructure to capture margin pools from independent blenders. |
| Controlled-Release Formulation Development | Cargill Incorporated anchors automated dairy system relationships through dust-free biuret with synchronized ammonia release kinetics. |
| Direct-to-Farmer Channel Expansion | Nutrien Ltd bundles feed-grade urea with crop nutrient programs to displace traditional feed dealer relationships in Iowa and Illinois. |
| Blockchain-Enabled Traceability Pilot | Danish dairy cooperatives verify nitrogen source origin for Middle Eastern export certification through distributed ledger systems. |
| REACH Registration Dossier Investment | Specialty chemical suppliers prioritize biuret variants with existing safety profiles to bypass extended toxicity submission timelines. |
Methodological Framework
Direct dialogue with feed mill procurement managers, dairy cooperative nutritionists, ammonia plant operations directors, and regulatory affairs specialists at compound feed manufacturers grounded the qualitative foundation. Secondary validation drew from Bureau of Indian Standards filings, ANVISA regulatory circulars, EU F-Gas Regulation enforcement guidance, and EPA Clean Water Act discharge permit databases. Bottom-up and top-down triangulation cross-checked volume estimates against trade flow data and production capacity disclosures.
Bottom-up modeling segmented the market across product type, application, physical form, and end-user procurement scale throughout the forecast period. CAGRs were derived from regression analysis against protein substitution economics, ammonia emissions compliance stringency indices, and precision-feeding hardware penetration curves. Industry-specific forecast inputs incorporated rumen microbiology formulation expertise scarcity and pneumatic handling infrastructure capex cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas benchmark volatility, EU Green Deal target acceleration, and Brazilian oilseed crushing capacity expansion. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and microbial protein synthesis rate optimization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Animal Nutrition Market