
 Feed Carotenoids Market | 2026-2036
Feed Carotenoids Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Carotenoids Market Foresight
China is tilting the feed carotenoids supply map as domestic fermentation capacity expands to serve aquaculture and poultry sectors. BASF SE leverages its integrated chemical platform to sustain astaxanthin output for salmonid feed. Kemin Industries anchors its position through lutein specialization for poultry yolk pigmentation. DSM-Firmenich competes via biotechnology leadership in microbial carotenoid production.
Feed carotenoids comprise lipid-soluble tetraterpenoid pigments—beta-carotene, astaxanthin, lutein, and canthaxanthin—synthesized chemically or extracted from algae and fermentation biomass, typically formulated at inclusion rates of 10–100 ppm to enhance animal product coloration, fertility, and immune response. Astaxanthin commands premium positioning in aquaculture nutrition where pigment deposition determines salmon marketability, while beta-carotene retains mature volume leadership across ruminant reproductive health applications. The powder form dominates feed manufacturing integration, though liquid emulsions are gaining traction in automated dosing systems for large-scale poultry operations.
EFSA and the EU Green Deal shape European additive approval pathways, with REACH compliance now prerequisite for synthetic carotenoid market access. China's MEE enforces stricter effluent standards on fermentation plants, elevating capital requirements for domestic producers. The FDA's GRAS self-affirmation pathway continues to govern U.S. entry for novel microbial sources. Stakeholders must monitor regulatory divergence between jurisdictions as biomanufacturing claims and natural-origin labeling requirements harden into trade barriers.
Market Dynamics
Fermentation-based astaxanthin production is displacing synthetic chemical synthesis as China's MEE effluent rules tighten and salmon integrators demand natural-origin certification for EU market access.
Growth Catalysts
- Aquaculture pigment premium:Salmon farmers in Norway and Chile now require astaxanthin deposition verification for retail contracts, pulling algae-derived volumes into feed formulations at 25–50 ppm inclusion rates.
- REACH synthetic restrictions:ECHA authorization requirements for synthetic canthaxanthin are redirecting R&D budgets toward microbial fermentation platforms with lower environmental footprint.
- Poultry yolk standardization:Chinese layer operations are adopting lutein premixes to meet domestic supermarket color-grade specifications, creating pull-through for carotenoid blend suppliers.
Market Restraints
- Feedstock cost volatility:Corn oil and soybean lecithin prices fluctuate with biofuel policy shifts in the US and Brazil, compressing margins for emulsion-form carotenoid producers.
- Fermentation capacity concentration:Commercial-scale astaxanthin bioreactors cluster in Yunnan and Shandong provinces, creating single-source risk for international offtake agreements.
- Synthetic price anchoring:Chemically synthesized beta-carotene from petrochemical feedstocks retains 30–40% cost advantage over algal alternatives in ruminant applications.
Strategic Opportunities
- Shrimp aquaculture expansion:Indonesian and Vietnamese intensive shrimp farms remain underpenetrated for astaxanthin supplementation, offering volume growth outside saturated salmonid channels.
- EU Green Deal biomanufacturing incentives:Horizon Europe funding streams favor carbon-negative fermentation projects, advantaging applicants with integrated algae-fermentation platforms.
- Precision dosing automation:Liquid carotenoid emulsions paired with IoT-enabled feed mill systems enable real-time inclusion rate adjustment, opening premium service revenue streams.
Industry Challenges
- Fermentation scale-up expertise:PhD-level strain optimization and bioprocess engineering talent concentrates in Basel, Boston, and Shanghai clusters, creating recruitment bottlenecks for mid-cap producers.
- GRAS timeline compression:FDA self-affirmation pathways for novel microbial carotenoid sources require 18–24 month toxicology packages, delaying commercial launch schedules.
- Legacy premix integration:Powder-form carotenoid incumbents face technical friction retrofitting liquid emulsion handling systems into existing feed mill infrastructure without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Carotenoids Market |
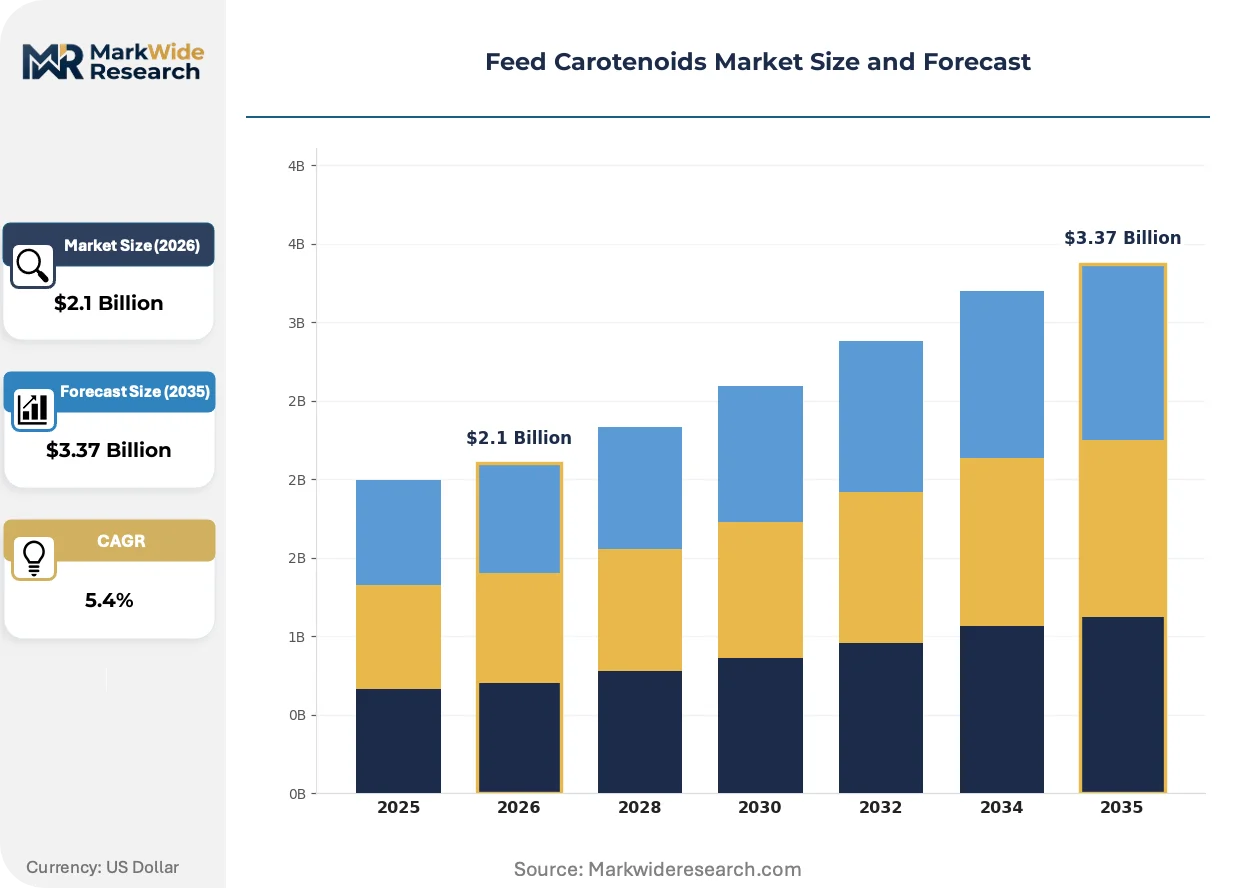
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Carotene, Lutein, Astaxanthin, Canthaxanthin Animal Type: Poultry, Swine, Aquaculture, Ruminants Form: Powder, Liquid, Granule, Emulsion Application: Nutrition, Color Enhancement, Immunity, Antioxidant |
| Companies Covered | BASF SE, Kemin Industries, DSM-Firmenich, Novus International, Cyanotech Corporation, Chr. Hansen Holding A/S, FMC Corporation, Allied Biotech Corporation, Biochem Products B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Carotenoids Market Shifts & Advancements
Biomanufacturing platforms are converging with digital traceability systems to create verified natural-origin supply chains that command price premiums in regulated protein markets.
Algae-fermentation hybrid production is hybridizing astaxanthin manufacturing economics. Haematococcus pluvialis cultivation in closed photobioreactors now integrates with heterotrophic fermentation for biomass density gains. Norwegian and Chilean salmon feed compounders are qualifying these dual-process inputs for 2025 contract renewals, compressing the cost gap versus synthetic alternatives.
REACH authorization timelines for synthetic carotenoids are tightening ingredient approval pathways. ECHA's 2024 substance evaluation work program prioritizes canthaxanthin and astaxanthin dossier reviews, forcing reformulation timelines. EU compound feed manufacturers are accelerating natural-origin qualification programs to preempt supply disruption, with beta-carotene from Blakeslea trispora gaining traction in premix portfolios.
Buyer concentration among integrated poultry processors is consolidating procurement leverage. Brazilian and Thai broiler giants now mandate carotenoid supplier ESG certification and batch-level blockchain traceability. This specification creep disadvantages smaller chemical synthesis operations lacking sustainability audit infrastructure, while favoring vertically integrated fermentation players with captive algae cultivation assets.
Feed Carotenoids Market Segmentation
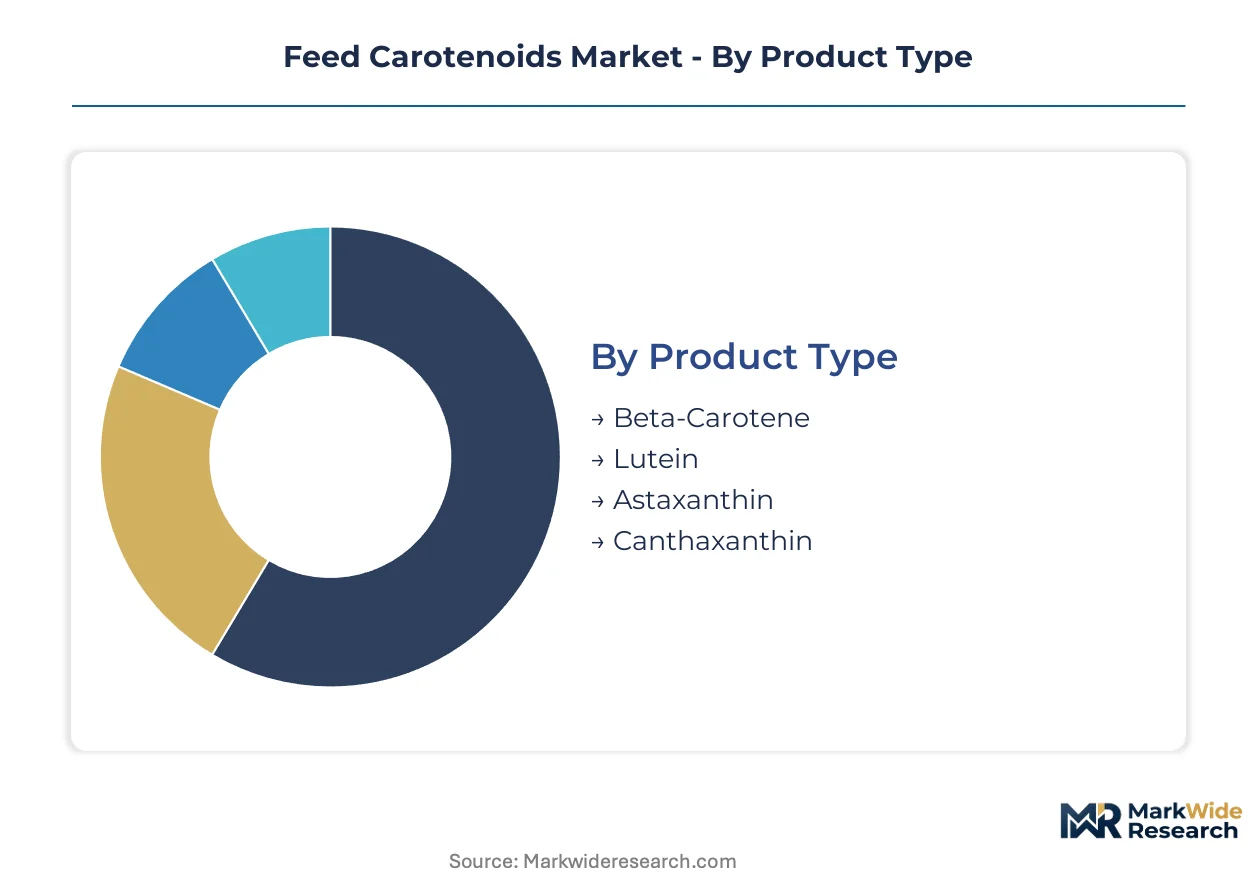
Feed carotenoid procurement cycles vary sharply by product chemistry and animal species, with aquaculture pigment contracts resetting annually while ruminant beta-carotene agreements often span three-year terms. Understanding these turnover rhythms helps suppliers align inventory planning with customer budgeting windows.
Product Type:
Astaxanthin and lutein turn inventory fastest due to aquaculture and poultry contract volatility, whereas beta-carotene and canthaxanthin move through longer replenishment cycles tied to ruminant health programs and layer yolk standardization.
- Astaxanthin:Haematococcus pluvialis-derived tetraterpenoid pigment with 25–50 ppm inclusion rates for salmonid flesh coloration. Norwegian and Chilean integrators now mandate natural-origin verification for retail contracts, pulling fermentation volumes from Yunnan and Shandong bioreactors. EFSA batch testing requirements extend procurement lead times.
- Lutein:Xanthophyll pigment concentrated in marigold oleoresin extracts, formulated for poultry yolk pigmentation at 10–30 ppm. Chinese layer operations in Shandong and Hebei provinces drive volume as domestic supermarkets enforce color-grade specifications. REACH-compliant natural extraction methods command 15–20% price premiums over synthetic alternatives.
- Beta-Carotene:Provitamin A carotenoid from Blakeslea trispora fermentation or petrochemical synthesis, dominant in dairy cow fertility protocols. ECHA authorization pressures are redirecting ruminant premix formulations toward microbial sources despite synthetic cost advantages.
- Canthaxanthin:Keto-carotenoid for broiler skin pigmentation and egg yolk intensification, facing ECHA 2024 substance evaluation prioritization. EU compounders are accelerating natural-origin qualification to preempt supply disruption.
Beta-carotene dominates installed base through mature ruminant applications. Astaxanthin is where expansion concentrates as salmon integrators phase out synthetic alternatives.
Animal Type:
Cost tiers separate commodity livestock from premium aquaculture, with salmonid feed commanding per-kilogram carotenoid expenditures tenfold above broiler operations.
- Aquaculture:Salmon and trout farming absorb premium astaxanthin volumes where pigment deposition directly determines marketability. Norwegian Mowi and Chilean AquaChile procurement specifications now require carbon-negative fermentation credentials.
- Poultry:Layer and broiler operations consume lutein and canthaxanthin blends for yolk and skin color standardization. Brazilian BRF and Thai CP Group mandate ESG certification and blockchain traceability from suppliers.
- Ruminants:Dairy and beef cattle receive beta-carotene for reproductive performance and mastitis prevention. Synthetic sources retain cost advantage though EU Green Deal incentives favor biomanufacturing transitions.
- Swine:Limited carotenoid penetration relative to other species, with occasional beta-carotene supplementation for sow fertility. Pork integrators prioritize amino acid and enzyme additives over pigment investments.
Poultry commands volume leadership across geographies. Aquaculture represents the steepest expansion trajectory as natural-origin premiums reshape procurement specifications.
Form:
Manufacturing automation divides powder legacy from liquid precision, with large-scale poultry mills retrofitting emulsion handling systems while ruminant premixers retain dry blending infrastructure.
- Powder:Spray-dried crystalline or beadlet formulations dominating existing feed mill integration. Legacy premix producers in the US Corn Belt and Brazilian soy belt resist capital-intensive liquid system conversions.
- Liquid:Oil-based suspensions and emulsions enabling IoT-enabled dosing automation. Thai and Vietnamese poultry operations are adopting real-time inclusion rate adjustment systems.
- Emulsion:Stabilized aqueous dispersions with enhanced bioavailability for shrimp and salmon feeds. Corn oil and soybean lecithin feedstock volatility compresses producer margins.
- Granule:Extruded matrix formulations for controlled release in ruminant slow-release applications. Limited adoption outside specialized dairy nutrition programs.
Powder formulations dominate installed base. Liquid and emulsion forms are where expansion concentrates as precision dosing automation penetrates integrated poultry processors.
Application:
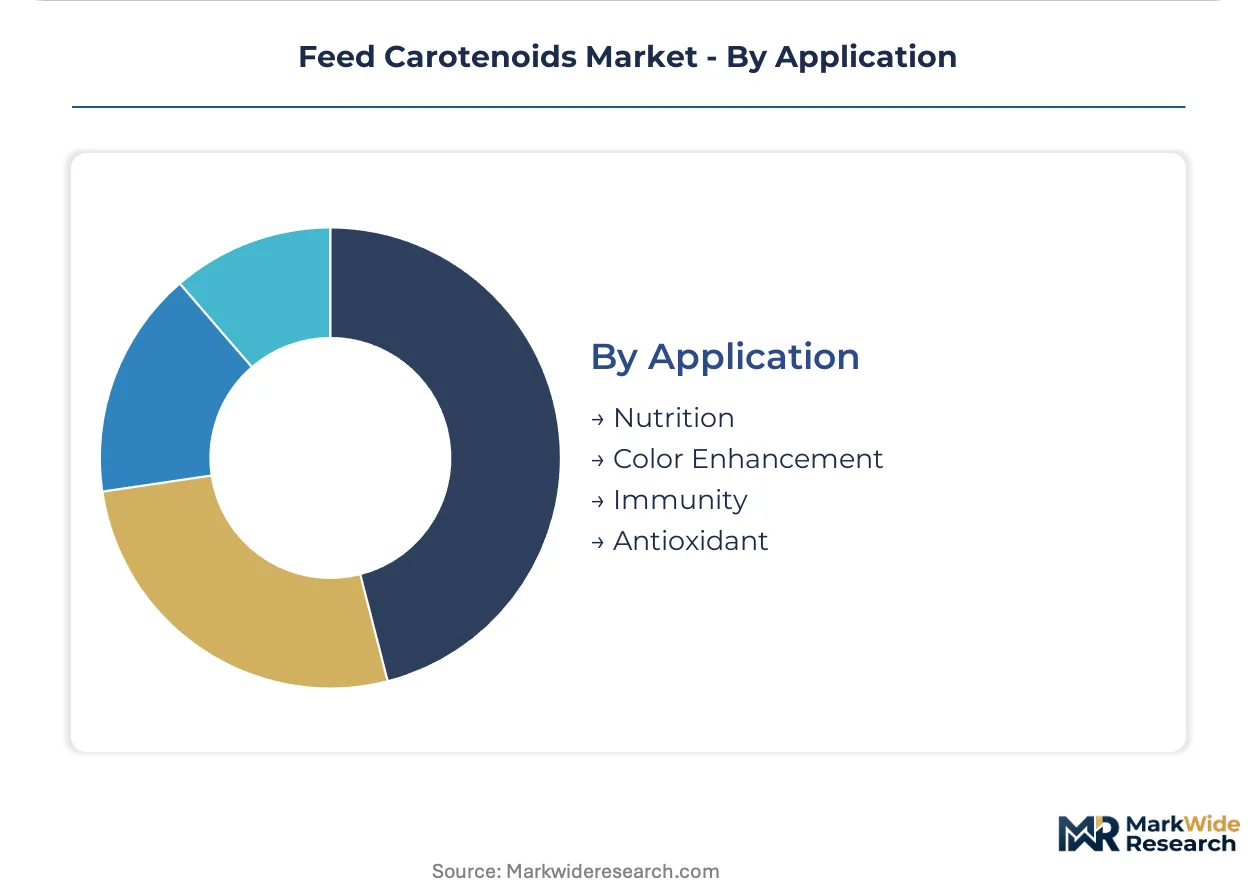
Functional claims stratify pricing tiers, with color enhancement commanding pure commodity economics while immunity and antioxidant positioning enable value-added premix premiums.
- Color Enhancement:Flesh, yolk, and skin pigmentation driving baseline demand across salmon, layer, and broiler sectors. Retail color-score specifications in EU and Chinese markets enforce minimum inclusion rates.
- Nutrition:Provitamin A conversion and reproductive health applications in ruminant and swine diets. Beta-carotene's role in dairy cow fertility programs supports stable demand despite pigment commoditization elsewhere.
- Antioxidant:Oxidative stress mitigation in high-performance aquaculture and poultry genetics. Astaxanthin's radical scavenging capacity supports premium positioning beyond coloration alone.
- Immunity:Immune modulation claims gaining traction in broiler and shrimp hatchery feeds. EFSA health claim substantiation requirements limit marketing differentiation in EU markets.
Color enhancement dominates installed base. Immunity applications are where expansion concentrates as hatchery biosecurity investments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Norwegian salmon integrators demand natural-origin astaxanthin certification for EU retail access, while Chinese layer operations prioritize cost-efficient lutein premixes for domestic yolk color grading. Brazilian broiler giants impose ESG audit requirements that reshape supplier qualification protocols.
China
Domestic fermentation capacity in Yunnan and Shandong provinces now supplies both aquaculture and poultry sectors. MEE effluent standards tightened in 2024, elevating capital barriers for new bioreactor installations. Qingdao and Weifang clusters host integrated algae-fermentation platforms serving regional feed compounders.
Norway
Salmon farmers Mowi and Lerøy mandate carbon-negative astaxanthin credentials for 2025 feed contracts. EFSA batch testing requirements extend procurement lead times for imported fermentation volumes. Bergen and Stavanger serve as qualification hubs for natural-origin pigment verification.
United States
Corn Belt premix producers retain powder-form beta-carotene infrastructure for dairy cow fertility programs. FDA GRAS self-affirmation governs novel microbial carotenoid entry, requiring 18–24 month toxicology packages. Iowa and Illinois feed mills resist capital-intensive liquid emulsion retrofits.
Brazil
Integrated processors BRF and JBS impose blockchain traceability and ESG certification requirements on carotenoid suppliers. Soybean lecithin feedstock volatility compresses margins for emulsion-form producers. São Paulo and Paraná states concentrate poultry premix manufacturing capacity.
Germany
REACH authorization pressures redirect ruminant premix formulations toward microbial beta-carotene sources. ECHA's 2024 substance evaluation prioritizes canthaxanthin dossier reviews, accelerating natural-origin qualification timelines. Ludwigshafen and Frankfurt clusters anchor chemical synthesis and fermentation R&D respectively.
Feed Carotenoids Market Competitive Landscape
Capability concentration sits with fermentation specialists and integrated chemical platforms; scale advantage sits with diversified nutrition multinationals. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive synthesis capacity, mid-cap biotechnology firms with strain optimization expertise, and regional premix blenders with distribution density. Dominant competitive moves include backward integration into algae cultivation assets and technology licensing partnerships for bioreactor scale-up.
Within the integrated chemical tier, BASF SE and DSM-Firmenich occupy positions defined by platform breadth and biotechnology leadership respectively. Kemin Industries exemplifies the specialization archetype, anchoring its market presence through focused expertise in natural extraction methodologies. These three entities collectively represent the competitive spectrum spanning petrochemical synthesis, microbial fermentation, and botanical processing approaches.
| Leading Market Players |
|---|
| BASF SE |
| Kemin Industries |
| DSM-Firmenich |
| Novus International |
| Cyanotech Corporation |
| Chr. Hansen Holding A/S |
| FMC Corporation |
| Allied Biotech Corporation |
| Biochem Products B.V. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Yunnan and Shandong fermentation clusters determines both the premium spread for natural-origin astaxanthin and the geographic configuration of international offtake agreements. MEE effluent enforcement compresses synthetic-alternative price advantages while elevating capital barriers that stratify supplier tiers.
Pricing Analysis
Chinese domestic markets trade lutein premixes at discounts to REACH-compliant EU quotations, with natural-extraction certification commanding 15–20% premiums over synthetic alternatives. Three-tier pricing structure across natural-origin verified, standard fermentation, and synthetic chemical grades reflects ESG audit depth and batch traceability infrastructure. Cost compression in synthetic beta-carotene is intensifying because petrochemical feedstock volatility lags behind algal cultivation cost curves. Ruminant premixers show highest price sensitivity; salmon integrators absorb premium spreads for natural-origin verification.
Supply Chain Analysis
Tariff exposure between China and Norway dominates supply chain risk as EFSA batch-testing requirements extend procurement lead times for fermentation volumes. Commercial-scale astaxanthin bioreactors concentrate in Yunnan and Shandong provinces, with secondary fermentation capacity emerging in India and Vietnam. Corn oil and soybean lecithin feedstock dependencies tether emulsion-form producers to biofuel policy volatility in Brazil and the US. Distribution runs through integrated poultry processors and salmon feed compounders with direct supplier qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived carotenoids face substitution pressure from novel microbial chassis engineering that could collapse natural-origin premiums if scaled commercially. Incumbents must navigate this threat while defending established qualification relationships with integrated protein processors.
For Market Incumbents: Insulate natural-origin certification premiums by securing captive algae cultivation assets in low-regulatory-cost jurisdictions before MEE standards replicate globally. Accelerate backward integration into Haematococcus pluvialis photobioreactor networks to preempt supply disruption from Chinese effluent enforcement. Defend against synthetic price anchors by embedding carbon-negative credentials into contract structures with Norwegian and Chilean salmon integrators.
For New Entrants and Emerging Players: Indonesian and Vietnamese intensive shrimp farms represent the most penetrable entry point for astaxanthin supplementation outside saturated salmonid channels. Mid-cap biotechnology firms with strain optimization expertise can exploit fermentation talent scarcity in Basel and Boston clusters through remote bioprocess engineering partnerships. Lead with precision dosing automation bundled with liquid emulsion formulations to differentiate from powder-form incumbents.
For Investors and Strategic Acquirers: The market sits at a substitution defense phase that favors vertically integrated fermentation platforms with captive algae assets. Long-term viability hinges on qualification relationships with buyer-concentrated poultry processors and salmon integrators over the next decade. Watch ECHA authorization timelines for canthaxanthin and astaxanthin as inflection indicators for natural-origin demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae Cultivation | Captive Haematococcus pluvialis assets secure natural-origin supply for EU retail contracts. |
| Fermentation Capacity Expansion | MEE-compliant bioreactor installations in Yunnan and Shandong defend Chinese domestic market position. |
| Precision Dosing Automation Partnership | IoT-enabled liquid emulsion systems open premium service revenue with Thai poultry integrators. |
| REACH Natural-Origin Qualification | Blakeslea trispora beta-carotene dossiers preempt ECHA synthetic authorization disruptions. |
| Carbon-Negative Certification Program | Horizon Europe funding eligibility advantages applicants with integrated algae-fermentation platforms. |
Research Methodology
Cross-validation between regulatory filing analysis and feed compounder procurement data anchors the qualitative findings in documented approval pathways and contract specifications. Primary interviews with fermentation plant managers, aquaculture nutrition directors, poultry procurement leads, and ECHA regulatory affairs specialists combined with secondary validation from customs trade records, EFSA additive dossiers, SEC 10-K disclosures, and MEE effluent enforcement notices. Bottom-up capacity modeling and top-down consumption estimates triangulate volume figures across the analysis window.
Calibration against historical price spreads between synthetic and natural-origin grades informs the projection framework across product chemistry, animal species, formulation type, and functional application dimensions. CAGRs derive from segment-level growth rate reconciliation with macro drivers including aquaculture output expansion, EU Green Deal biomanufacturing incentives, and poultry processor consolidation patterns. Industry-specific forecast inputs include salmon integrator natural-origin adoption curves and Chinese layer operation lutein premix penetration rates.
Practitioners should monitor ECHA substance evaluation timelines, MEE enforcement escalation, and novel microbial carotenoid GRAS submissions for early signals of supply disruption or substitution acceleration. Forecasts reflect assumptions about regulatory divergence persistence and fermentation scale-up constraint continuity. Material shifts in REACH authorization scope or breakthroughs in heterotrophic fermentation economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market