
 Livestock Grow Lights Market | 2026-2036
Livestock Grow Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Grow Lights Market Outlook
REACH compliance is realigning the cost-of-entry calculus for livestock lighting manufacturers serving European agricultural markets. OSRAM leverages its vertical integration across LED chip fabrication and optical design to sustain pricing power in premium spectrum-controlled systems. Signify Holding anchors its position through deep channel relationships with dairy equipment distributors across Northern Europe. Big Dutchman competes by bundling lighting controls with its ventilation and feeding automation platforms.
Livestock grow lights are engineered lighting systems that manipulate photoperiod, intensity, and spectral composition to regulate animal circadian rhythms, reproductive cycles, and feed conversion efficiency; LED variants now dominate new installations due to their tunable 2700K-6500K color temperature range and 50,000-hour operational lifespan. The technology dimension shows LED commanding replacement demand while HPS retains residual share in low-margin contract broiler operations where upfront capital constraints persist. Application segmentation reveals dairy farming generating the highest per-unit lighting spend due to 18-hour photoperiod protocols, whereas aquaculture represents the fastest-growing addressable pool as recirculating indoor systems multiply.
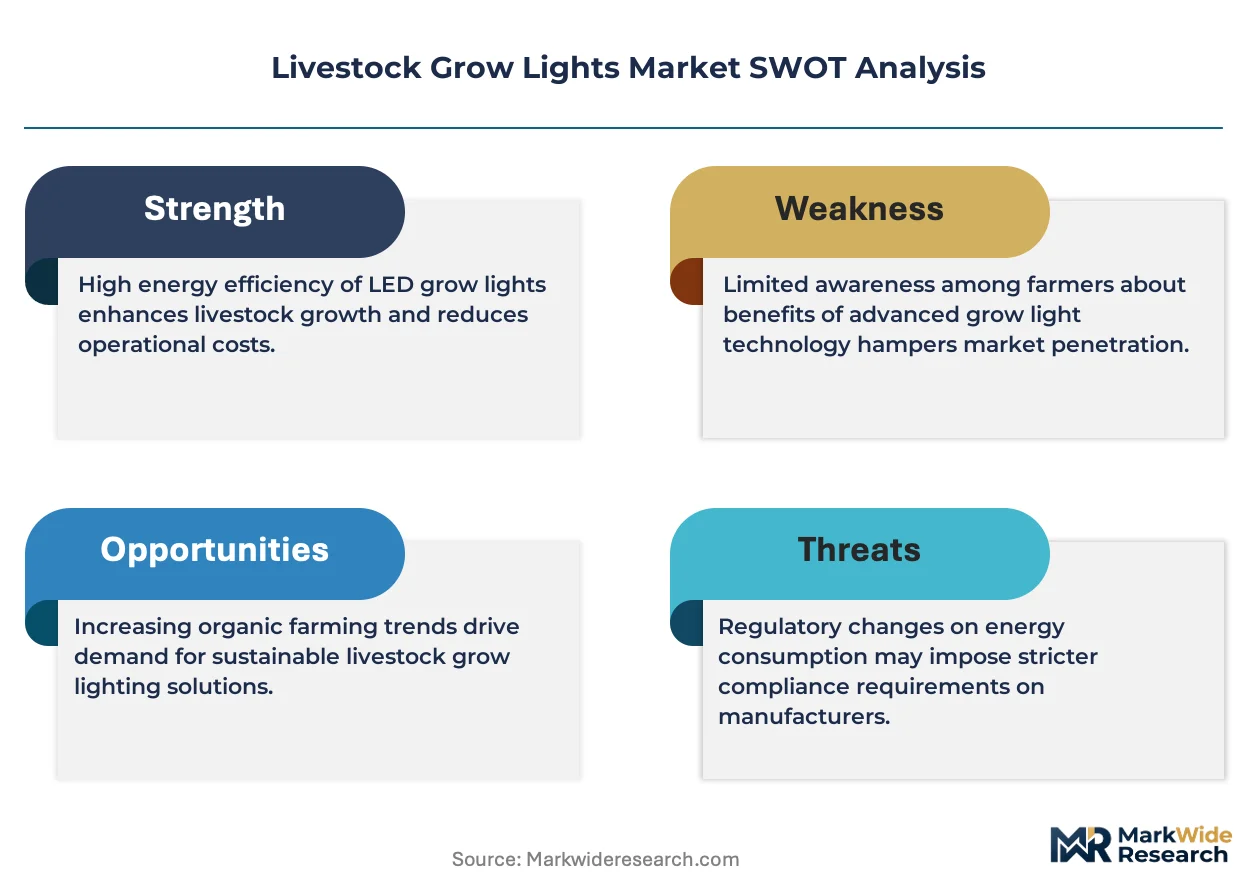
The EU Green Deal and F-Gas Regulation are tightening energy-efficiency benchmarks for agricultural equipment, while ECHA chemical restrictions on mercury-containing lamps are accelerating phase-out timelines for legacy MH and T5 fluorescent technologies. USDA conservation programs in the United States now subsidize LED retrofits in qualifying dairy operations, creating parallel demand stimulus outside European jurisdictions. Stakeholders must monitor how evolving animal welfare certification standards integrate lighting quality metrics into premium supply chain access requirements.
Market Dynamics
LED spectrum-tuning capabilities are compressing replacement cycles across European livestock barns as energy-efficiency mandates from Brussels force capital redeployment away from legacy discharge lamps.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated gases are accelerating barn infrastructure electrification, pushing integrators toward solid-state lighting architectures that eliminate refrigerant-dependent climate control loads.
- Dairy photoperiod protocols:18-hour lighting regimens in high-yield milking operations are expanding fixture density per animal unit, particularly in Netherlands precision farming clusters.
- Recirculating aquaculture systems:Indoor fish production facilities are deploying wavelength-specific arrays to regulate maturation rates, creating a new equipment category with shorter replacement intervals than terrestrial livestock.
Market Restraints
- LED driver component concentration:Power electronics supply chains cluster in East Asian manufacturing zones, exposing European fixture assemblers to input cost volatility and extended lead times.
- Mercury lamp legacy lock-in:Low-margin contract broiler operations retain T5 fluorescent and MH installations due to near-zero residual value recovery and tenant-landlord split-incentive structures.
- Spectral calibration expertise scarcity:Qualified agricultural lighting designers capable of optimizing melanopic lux levels for species-specific welfare outcomes remain concentrated in Northern European technical universities.
Strategic Opportunities
- USDA EQIP conservation incentives:Cost-share programs for qualifying dairy LED retrofits in Wisconsin and New York are creating parallel demand channels outside EU regulatory jurisdiction.
- Poultry welfare certification integration:RSPCA Assured and similar schemes are embedding lighting quality metrics into premium supply chain access protocols, enabling price premiums for certified spectrum-controlled systems.
- IoT convergence with climate control:Sensor-integrated luminaires that modulate output based on ammonia detection and humidity readings are opening bundled service contracts in integrated barn automation.
Industry Challenges
- Species-specific photobiology knowledge gaps:Engineering teams lack standardized protocols for optimizing duck, turkey, and alternative poultry species under LED spectra validated primarily for broilers.
- Retrofit electrical infrastructure:Aging barn circuits in Eastern European agricultural zones require panel upgrades before LED deployment, fragmenting project timelines and contractor coordination.
- REACH substance documentation:Extended supply chain disclosure requirements for phosphors and rare-earth dopants are elongating product registration timelines for new fixture introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Grow Lights Market |
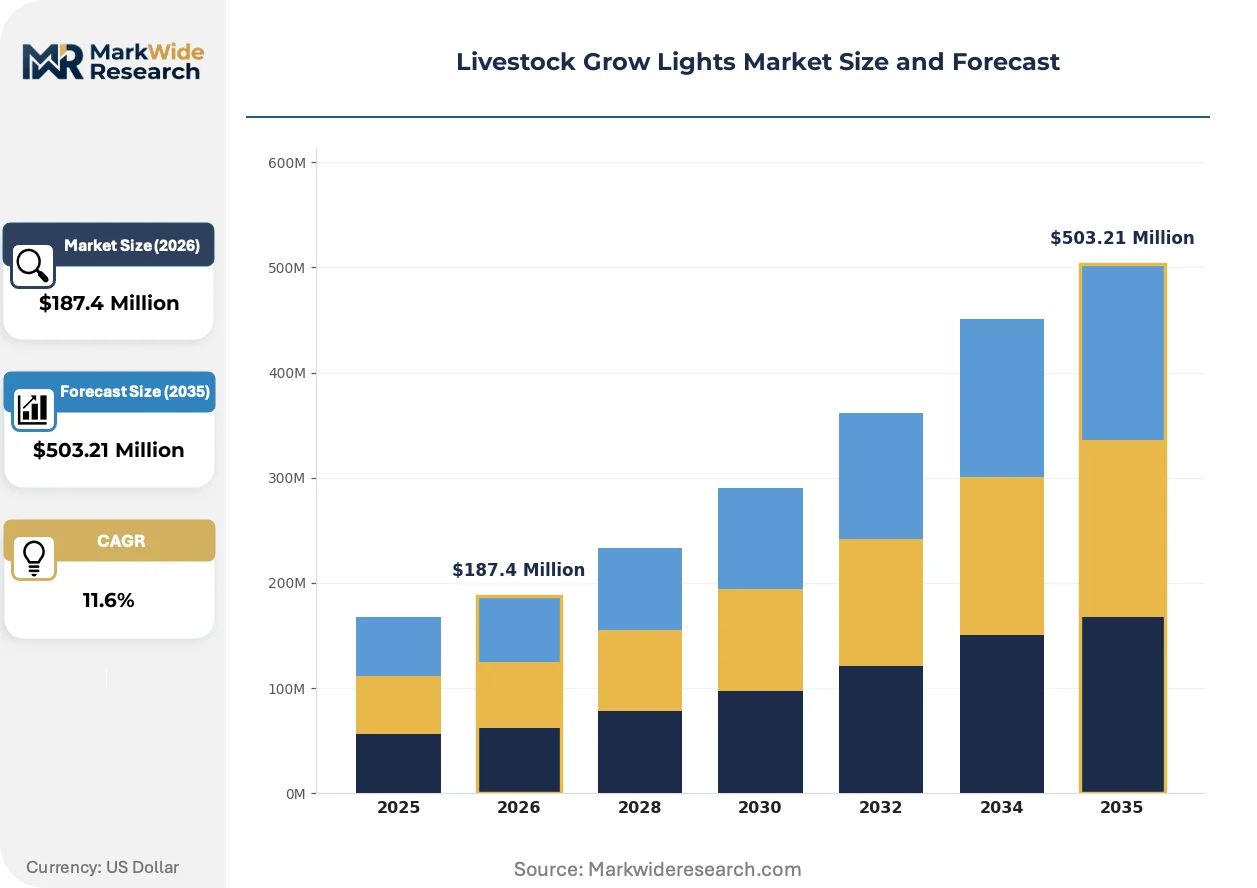
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, HPS, MH, T5 Fluorescent Application: Animal Husbandry, Aquaculture, Poultry, Dairy Farming End User: Farmers, Commercial Growers, Aquaculture Facilities, Research Institutions Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | OSRAM, Signify Holding, DeLaval, Big Dutchman, Uni-light LED, Once Inc., AGRILIGHT BV, HATO BV, Aruna Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Grow Lights Market Strategic Shifts
Spectral programming capabilities are shifting competitive advantage from luminaire manufacturing toward biological optimization services, rewiring how value is captured across the livestock lighting value chain.
Dynamic white-tuning LED engines with independent channel control over cyan and amber wavelengths are rewriting the economics of reproductive cycle management. Large-scale layer operations in Germany are deploying these systems to suppress autumn molt triggers without complete dark periods. The technology is compressing payback periods for premium fixtures by consolidating multiple production objectives into single capital investments.
REACH Annex XIV authorization requirements for mercury compounds are forcing accelerated phase-out timelines for legacy T5 and compact fluorescent technologies in agricultural settings. Dutch equipment distributors are clearing residual MH inventory through fire-sale pricing ahead of 2027 enforcement milestones. Poultry integrators with multi-site portfolios are front-loading LED conversions to avoid stranded asset risk in their Northern European facilities.
Buyer consolidation among protein processors is extending equipment specification authority upstream from individual farmers to corporate procurement functions. JBS and Tyson Foods agricultural divisions are issuing unified lighting standards across their contracted grower networks, displacing fragmented distributor relationships. This pattern is most visible in the US Southeast broiler belt, where processor-mandated LED retrofits now precede contract renewal negotiations.
Livestock Grow Lights Market Segmentation
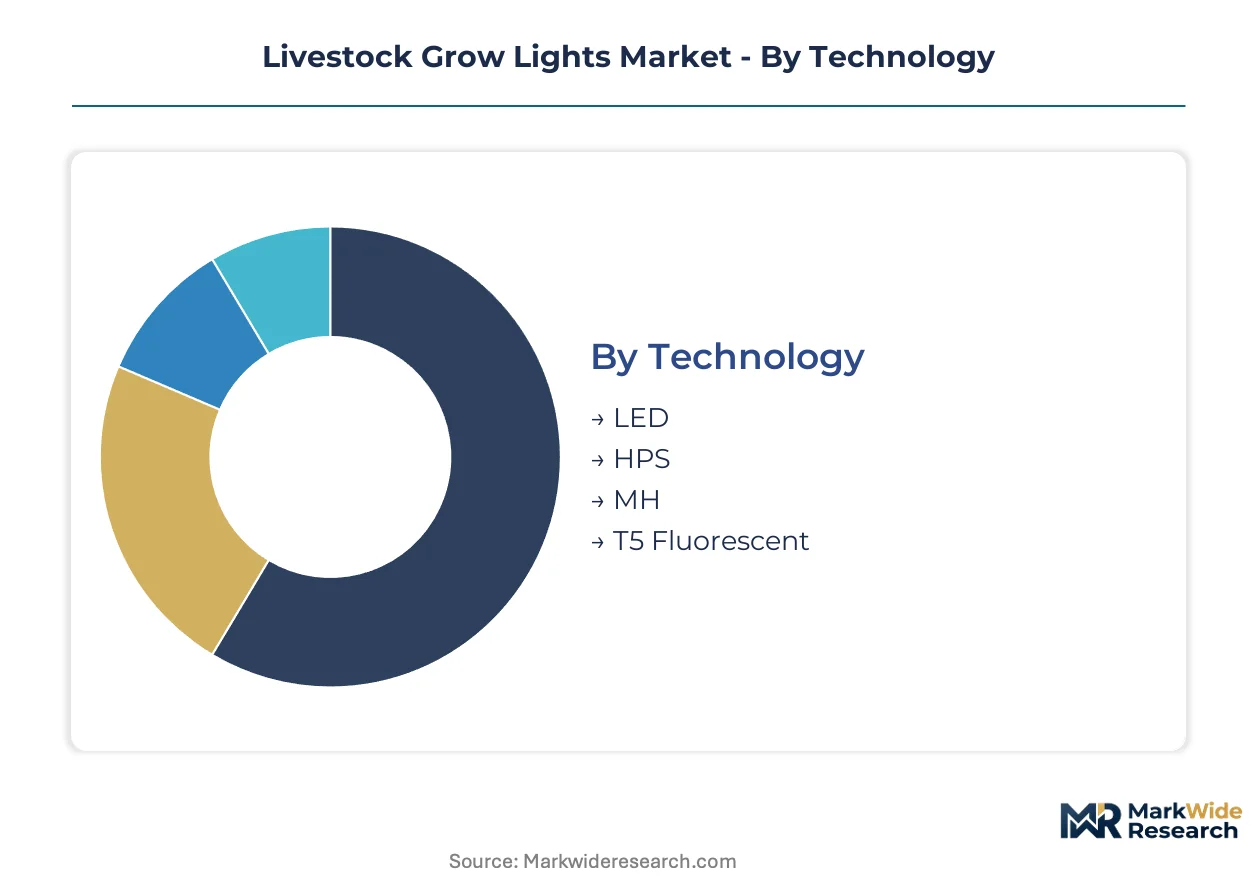
Livestock lighting procurement decisions hinge on species-specific photobiology requirements, energy payback horizons, and integration complexity with existing barn automation. Segment boundaries are blurring as LED platforms absorb functionality once split across discrete hardware categories.
Technology:
Capital recovery timelines and spectral programmability determine technology selection across European livestock operations.
- LED:Tunable 2700K-6500K arrays with 50,000-hour lifespans now dominate Dutch dairy retrofit programs seeking 18-hour photoperiod precision. German poultry integrators specify these systems to meet RSPCA Assured welfare certification requirements while cutting energy intensity per animal unit.
- HPS:High-pressure sodium retains residual share in low-margin contract broiler operations where upfront capital constraints override efficiency gains. Eastern European tenant farming structures perpetuate these installations through landlord-tenant split-incentive barriers.
- MH:Metal halide fixtures face accelerated phase-out under ECHA mercury restrictions, with Dutch distributors liquidating residual inventory ahead of enforcement milestones.
- T5 Fluorescent:Legacy fluorescent tubes persist in aging Eastern European barn infrastructure pending electrical panel upgrades required for LED conversion.
LED leads on scale; aquaculture-specific wavelength programming leads on momentum.
Application:
Per-animal lighting spend varies dramatically by species physiology and production intensity protocols.
- Animal Husbandry:Cattle, swine, and small ruminant operations deploy photoperiod manipulation to synchronize breeding cycles and accelerate weight gain in finishing phases.
- Aquaculture:Recirculating indoor systems deploy cyan-amber wavelength arrays to regulate fish maturation rates, with replacement intervals shorter than terrestrial livestock due to corrosive humid environments.
- Poultry:Layer and broiler houses generate concentrated demand for spectrum-tuned systems that suppress aggressive behavior while optimizing feed conversion ratios under extended photoperiods.
- Dairy Farming:High-yield milking operations in the Netherlands maintain the highest fixture density per animal unit, with 18-hour lighting regimens directly tied to milk yield optimization protocols.
Dairy farming commands the highest per-unit spend; aquaculture claims the steepest expansion trajectory.
End User:
Procurement authority is consolidating from individual operators toward corporate technical standards.
- Farmers:Small-to-midscale owner-operators prioritize payback periods under five years, often deferring to distributor recommendations for retrofit compatibility.
- Commercial Growers:Large-scale integrated operations issue unified lighting specifications across contracted grower networks, displacing fragmented purchasing decisions.
- Aquaculture Facilities:Indoor recirculating system operators demand IP-rated fixtures with corrosion-resistant housings and submersible driver architectures.
- Research Institutions:Wageningen University and technical agricultural colleges validate melanopic lux protocols for species-specific welfare outcomes, establishing de facto industry standards.
Commercial growers lead on procurement volume; research institutions lead on technical specification authority.
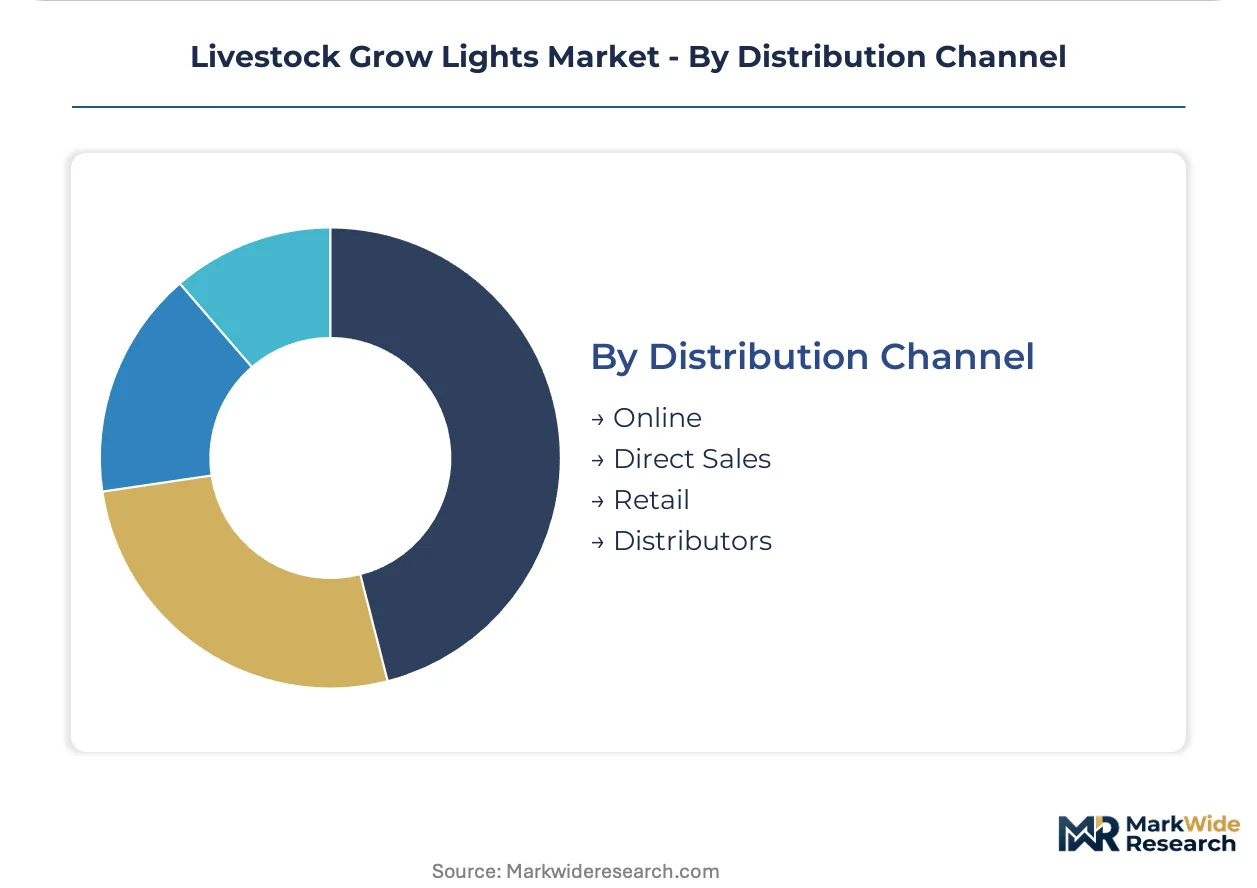
Distribution Channel:
Channel selection reflects installation complexity and buyer technical sophistication.
- Online:E-commerce platforms capture replacement lamp and component sales from technically confident operators in mature LED markets.
- Direct Sales:OSRAM and Signify Holding maintain field engineering teams for large-scale dairy and poultry integrators requiring custom spectral programming.
- Retail:Agricultural supply cooperatives serve smallholder farmers with standardized fixture packages and basic installation guidance.
- Distributors:Big Dutchman and specialized barn equipment distributors bundle lighting controls with ventilation and feeding automation platforms, capturing integrated project value.
Distributors lead on bundled project value; direct sales leads on technical customization depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical universities in Wageningen and Göttingen anchor European photobiology expertise, concentrating spectral calibration talent that shapes livestock lighting standards worldwide.
Netherlands
Dairy cooperatives in Friesland and Gelderland deploy precision lighting for 18-hour photoperiod protocols tied to milk yield optimization. The EU Green Deal's sustainability mandates accelerate LED retrofits across barn infrastructure. Wageningen University validates melanopic lux standards that propagate to integrators throughout Northern Europe.
Germany
Poultry integrators in Lower Saxony and Bavaria replace legacy HPS installations with spectrum-tuned LED arrays to meet RSPCA Assured certification requirements. The F-Gas Regulation forces phase-down of refrigerant-dependent climate control systems, pushing electrification of barn environments. Big Dutchman bundles lighting controls with feeding automation platforms across its contracted grower networks.
United States
USDA EQIP conservation programs subsidize LED retrofits in Wisconsin and New York dairy operations, creating demand channels parallel to European regulatory stimulus. The EPA oversees energy-efficiency benchmarking for agricultural equipment while conservation cost-share programs reduce capital barriers for mid-scale operators. Tyson Foods and JBS agricultural divisions issue unified lighting standards across Southeast broiler belt contract growers.
China
Recirculating aquaculture facilities in Guangdong and Shandong deploy wavelength-specific LED arrays to regulate fish maturation rates in indoor systems. The Ministry of Agriculture and Rural Affairs promotes facility agriculture modernization through subsidy programs for intelligent barn equipment. Yangtze River Delta equipment manufacturers concentrate driver electronics production, exposing European assemblers to input cost volatility.
Brazil
Integrated poultry processors in São Paulo and Paraná adapt European welfare certification protocols for export market access, embedding lighting quality metrics into supply chain requirements. ANVISA regulates agricultural equipment safety standards while the national agricultural research corporation validates tropical photoperiod adaptations. Contract broiler operations retain cost-optimized fluorescent installations where capital constraints override efficiency gains.
Livestock Grow Lights Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. OSRAM and Signify Holding leverage optical engineering heritage and channel relationships to anchor premium spectrum-controlled segments. Tier-two regional fabricators compete on retrofit compatibility and distributor proximity. Dominant competitive moves include backward integration into LED chip supply and strategic bundling of lighting controls with climate automation platforms.
Within the diversified lighting technology tier, OSRAM and Signify Holding exemplify scale-driven positions anchored by vertical fabrication depth and Northern European channel relationships. Big Dutchman occupies a specialist position integrating luminaire hardware with barn automation software. Among Netherlands-based agricultural equipment specialists, DeLaval represents dairy-focused system integration. Uni-light LED and Once Inc. exemplify mid-tier specialists competing on species-specific spectral programming capabilities rather than manufacturing scale.
| Leading Market Players |
|---|
| OSRAM |
| Signify Holding |
| DeLaval |
| Big Dutchman |
| Uni-light LED |
| Once Inc. |
| AGRILIGHT BV |
| HATO BV |
| Aruna Lighting |
| Others |
Value Chain & Pricing Dynamics
Large-scale poultry integrators in Germany and the Netherlands concentrate procurement authority, forcing fixture suppliers toward project-based pricing bundled with installation and spectral calibration services rather than transactional hardware sales.
Pricing Analysis
Bundled service contracts encompassing hardware, installation, and biological optimization programming command premium positioning against unbundled fixture-only transactions. Price differentiation rests on RSPCA Assured certification tier and volume scale across multi-site grower networks. Cost compression in economy-tier LED arrays intensifies as Yangtze River Delta manufacturers expand output. Smallholder farmers in Eastern Europe exhibit highest price sensitivity due to capital constraints and split-incentive tenant structures.
Supply Chain Analysis
Warehouse-distribution layers in the Netherlands and Germany operate hub-and-spoke patterns radiating from Rotterdam and Hamburg to serve concentrated dairy clusters in Friesland and Lower Saxony. LED driver electronics production centers on China and South Korea, while phosphor and rare-earth dopant refining concentrates in China. Single-source vulnerability in semiconductor-grade gallium nitride substrates poses structural risk. Distribution runs through specialized agricultural equipment distributors that bundle lighting with climate control platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestock grow lights represent a margin-expansion trajectory as LED chip cost curves flatten and premium spectrum-controlled systems capture welfare-certification price premiums.
For Market Incumbents: Anticipate processor-led procurement consolidation by deepening direct sales engineering teams for JBS and Tyson Foods contract networks. Prioritize backward integration into LED chip supply to defend margin position against Yangtze River Delta cost competitors. Anchor channel control through exclusive distributor arrangements in Netherlands dairy equipment networks. For New Entrants and Emerging Players: Species-specific spectral programming for aquaculture maturation protocols offers the most penetrable white-space target, as recirculating indoor systems multiply faster than terrestrial livestock lighting replacement cycles. Target Guangdong and Shandong recirculating aquaculture facilities with IP-rated corrosion-resistant fixture architectures. Pursue go-to-market partnerships with Yangtze River Delta driver electronics manufacturers to compress lead times. For Investors and Strategic Acquirers: Agricultural automation conglomerates are the most active acquirer in this space, seeking lighting capabilities to complete integrated barn system portfolios. Five-to-ten year viability hinges on spectral calibration talent scarcity and REACH compliance cost barriers protecting incumbent positions. Monitor RSPCA Assured certification penetration rates as the inflection indicator for premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Supply | Captive gallium nitride wafer production insulates OSRAM from Yangtze River Delta input volatility. |
| Spectral Calibration Service Bundling | Wageningen-validated melanopic lux programming commands premium positioning in Netherlands dairy retrofits. |
| Processor-Mandated Specification Authority | Tyson Foods and JBS unified standards displace fragmented distributor relationships across Southeast broiler belt. |
| Aquaculture-Specific IP-Rated Fixture Development | Corrosion-resistant housings penetrate Guangdong recirculating systems with shorter replacement intervals. |
| REACH Compliance Documentation Investment | Phosphor supply chain disclosure capabilities accelerate product registration timelines ahead of 2027 enforcement. |
Study Parameters
Multiple input streams — structured interviews with dairy operations managers and poultry integrator procurement leads, technical consultations with Wageningen University photobiology researchers, and distributor channel assessments — were reconciled against customs records for LED module imports, EU ETS agricultural energy disclosures, and USDA EQIP conservation program allocations. Secondary validation drew from ECHA substance restriction filings, SEC 10-K disclosures by diversified lighting manufacturers, and Netherlands Enterprise Agency facility agriculture subsidy databases. Bottom-up fixture shipment estimates and top-down energy-efficiency retrofit spending patterns were triangulated to constrain projection variance.
Data-stream reconciliation across technology substitution curves, species-specific photoperiod protocol adoption rates, and regulatory enforcement timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass technology tier, livestock category, farm scale class, and regional regulatory cluster. CAGRs were derived from fitting logistic diffusion curves to LED retrofit penetration patterns and cross-referencing against F-Gas Regulation phase-down schedules. Industry-specific forecast inputs included melanopic lux standard validation timelines and processor-led procurement consolidation velocity.
The model holds under sustained EU Green Deal enforcement and stable Yangtze River Delta electronics supply; deviation in REACH authorization timelines or gallium nitride substrate trade restrictions would shift replacement cycle assumptions. Forecasts reflect documented assumptions regarding welfare certification adoption curves and split-incentive structure persistence in Eastern European tenant farming. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Bean Harvester Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Plow Folding System Market