
 Cow Colostrum Market | 2026-2036
Cow Colostrum Market Size, Share, and Industry Trends Forecast 2026-2036
Cow Colostrum Market Outlook
Ingredient processing margins is narrowing as spray-dried powder commoditizes, pushing value toward fractionated immunoglobulin concentrates and bioactive peptide isolation. PanTheryx leverages its vertically integrated bovine sourcing and colostrum collection networks across North American dairy cooperatives. Glanbia plc anchors its position through scale manufacturing of dairy-derived bioactives for sports nutrition and infant formula customers. NOW Health Group competes on channel breadth, stocking colostrum SKUs across mass-market retail and specialty health store networks.
Cow colostrum constitutes the antibody-rich mammary secretion produced during the first 72 hours post-parturition, containing immunoglobulin G concentrations ranging from 15-200 mg/mL alongside lactoferrin, growth factors, and oligosaccharides; manufacturers employ low-temperature pasteurization and spray-drying to preserve bioactivity for nutraceutical and functional food applications. Powder formulations dominate current production volumes due to stability advantages in bulk ingredient trade and extended shelf life for industrial buyers. Capsule and tablet formats are capturing margin expansion in direct-to-consumer channels where dosing convenience commands price premiums over bulk powder. Liquid colostrum remains a niche segment constrained by cold-chain requirements and shorter expiration windows.
The FDA exercises oversight through New Dietary Ingredient notifications and Current Good Manufacturing Practice enforcement for colostrum supplement labeling and safety substantiation. EFSA novel food evaluations govern market access pathways for colostrum-derived ingredients entering European functional food applications. USDA organic certification and state-level dairy inspection protocols in Wisconsin and California further stratify supplier compliance burdens. Stakeholders must track evolving immunoglobulin content standardization efforts and emerging jurisdiction-specific bioactive labeling requirements to sustain market access.
Market Dynamics
Spray-dried colostrum powder commoditization is compressing ingredient margins and forcing suppliers toward fractionated immunoglobulin concentrates and bioactive peptide isolation to defend value capture.
Growth Catalysts
- FDA New Dietary Ingredient notifications:The notification pathway creates compliance barriers that favor established suppliers with documented safety substantiation, concentrating procurement relationships around qualified vendors.
- Sports nutrition formulations:Athletic recovery applications are expanding colostrum procurement volumes as endurance and strength training segments adopt immunoglobulin-rich supplements for gut permeability and immune modulation.
- Direct-to-consumer supplement channels:Premium positioning in US online retail and specialty health stores is expanding addressable market beyond traditional bulk ingredient trade.
Market Restraints
- Raw colostrum supply volatility:Seasonal calving patterns and dairy cooperative collection logistics create input cost instability for processors dependent on North American bovine sourcing networks.
- Cold-chain liquid colostrum:Refrigeration requirements and abbreviated shelf life constrain distribution reach, limiting this format to regional dairy markets and fresh delivery models.
- Plant-based protein alternatives:Pea and rice protein isolates with added immune-modulating ingredients are capturing price-sensitive consumers in mass-market sports nutrition.
Strategic Opportunities
- Infant formula bioactive enrichment:EFSA novel food evaluation pathways for colostrum-derived ingredients are opening European functional food applications beyond supplements.
- Microencapsulation technology:Converging lipid-coating and spray-chilling processes are enabling shelf-stable liquid formats that bypass traditional cold-chain constraints.
- USDA organic certification tier:Premium pricing for certified organic colostrum is creating differentiation in California and Wisconsin dairy inspection jurisdictions.
Industry Challenges
- Immunoglobulin assay standardization:Absence of harmonized IgG quantification methods across USP, AOAC, and industry protocols creates batch-to-batch variability disputes between suppliers and brand customers.
- Specialized dairy microbiology talent:Shortage of technicians trained in low-temperature pasteurization optimization and bioactive preservation is extending process development timelines for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cow Colostrum Market |
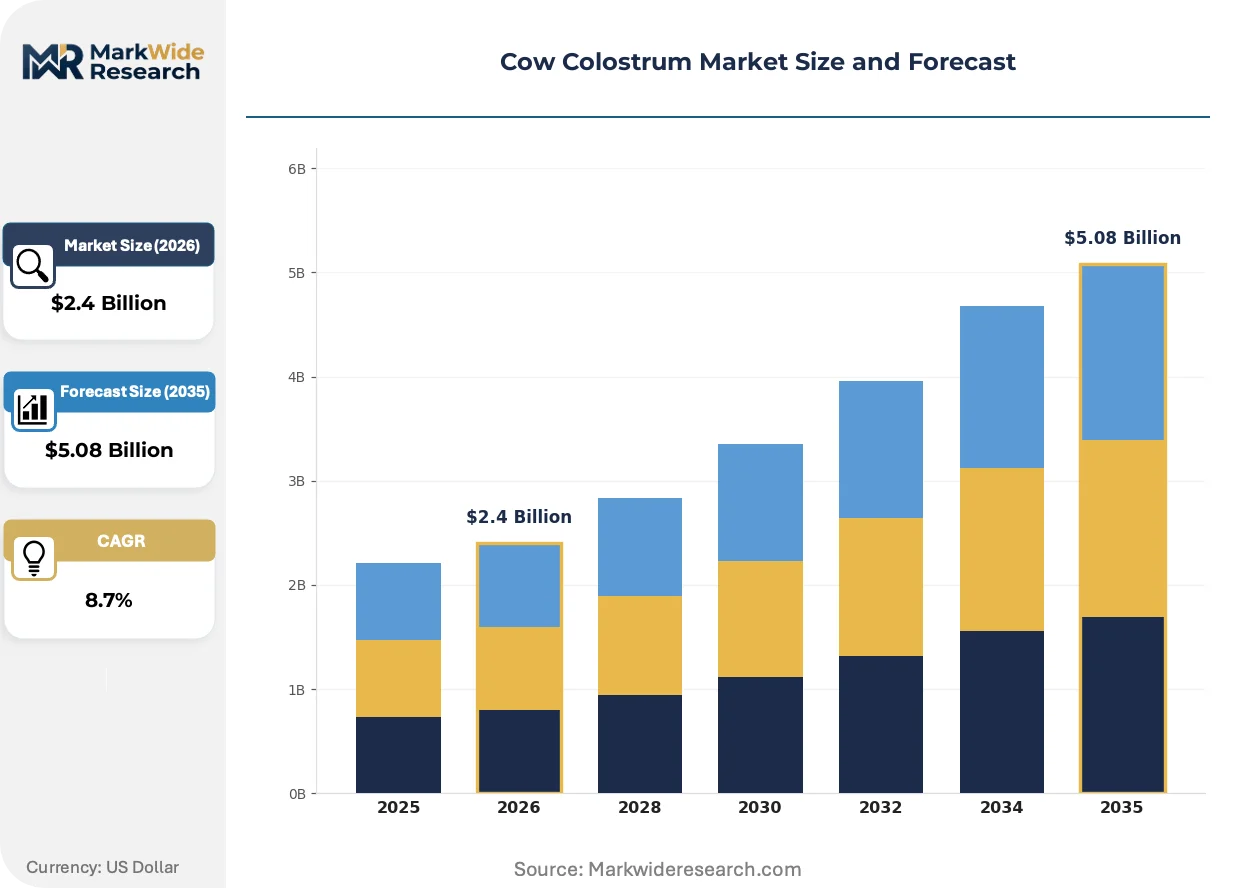
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets End User: Infants, Athletes, Elderly, Adults Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies Application: Nutrition, Immune Support, Supplements, Functional Foods |
| Companies Covered | PanTheryx, NOW Health Group, Glanbia plc, The Saskatoon Colostrum Company, Colostrum BioTec GmbH, Ingredia, Biodane Pharma A/S, ARMRA, Codeage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cow Colostrum Market Strategic Shifts
Processing technology is migrating toward precision fractionation methods that isolate specific bioactives, while regulatory frameworks and procurement patterns are simultaneously restructuring competitive access and channel economics.
Colostrum processing is migrating from whole powder spray-drying to immunoglobulin G concentration and lactoferrin separation protocols. Sports nutrition contract manufacturers in the United States are adopting these methods to support structure-function claims and justify premium capsule pricing. This technology migration from commodity bulk supply toward bioactive-specific ingredients is compressing margins for undifferentiated powder traders while expanding value capture for fractionation-capable processors.
EFSA novel food evaluation requirements are reshaping European market entry for colostrum-derived ingredients intended for functional food applications. The evaluation timeline and safety data requirements are extending commercialization cycles by 18-36 months compared to supplement-only pathways. Infant formula and medical food segments in Germany and France are most affected, with several applicants pursuing equivalence arguments based on existing bovine milk protein approvals.
Athletic recovery brands are consolidating procurement around suppliers with vertically integrated collection networks and documented IgG stability data. Direct-to-consumer channels are displacing traditional bulk ingredient brokers as primary volume drivers for branded finished goods. This pattern is most visible in the United States, where subscription supplement models and influencer-driven launches are compressing switching cycles and demanding faster supplier responsiveness.
Cow Colostrum Market Segmentation
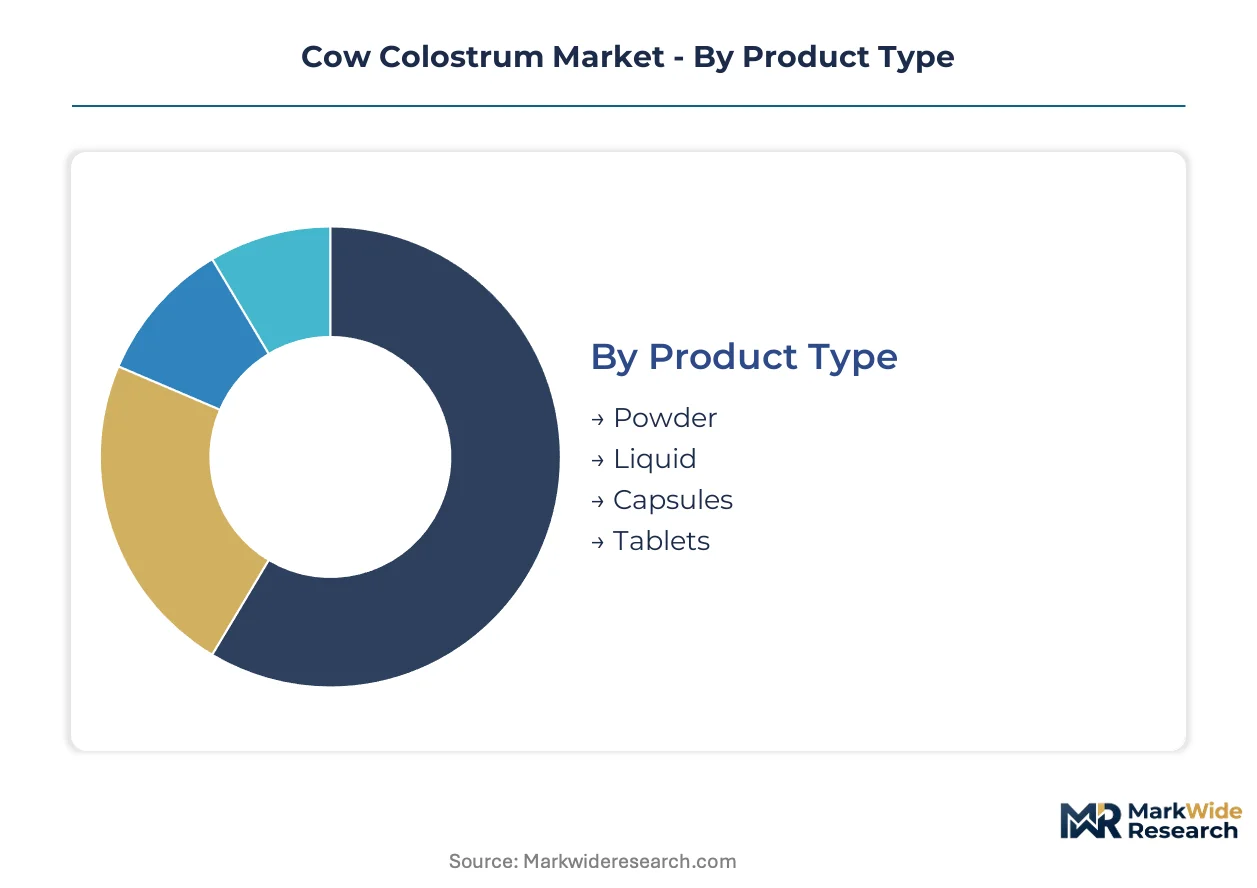
Cow colostrum segmentation reveals divergent margin profiles across format, user physiology, and channel economics. Powder commoditization contrasts with capsule premium capture, while infant formula applications face distinct regulatory barriers versus sports nutrition pathways.
Product Type:
Cost tier stratification separates commodity bulk supply from value-added bioactive isolation formats commanding formulation premiums.
- Powder:Spray-dried bulk powder dominates ingredient trade volumes with 18-24 month shelf stability for industrial buyers. Demand concentrates in North American contract manufacturers supplying sports nutrition brands, though margin compression from undifferentiated supply is accelerating fractionation technology migration.
- Liquid:Cold-chain dependent fresh colostrum retains maximum immunoglobulin bioactivity for regional dairy markets. Distribution remains constrained to 7-14 day expiration windows, limiting reach to farm-direct and subscription delivery models in Wisconsin and California inspection jurisdictions.
- Capsules:Dosing convenience commands direct-to-consumer price premiums over bulk powder in US online retail channels.
- Tablets:Compression formats suit mass-market retail placement with extended stability for pharmacy and supermarket networks.
Powder holds installed capacity. Capsules is rotating up the share rankings.
End User:
Application maturity varies sharply by user physiology, with infant nutrition facing novel food evaluations while athletic recovery navigates structure-function claim pathways.
- Infants:EFSA novel food safety substantiation requirements extend European commercialization cycles by 18-36 months for colostrum-derived infant formula ingredients. Germany and France medical food segments are most affected, with applicants pursuing equivalence arguments based on existing bovine milk protein approvals.
- Athletes:Endurance and strength training segments are expanding procurement volumes for immunoglobulin-rich gut permeability and immune modulation formulations. US sports nutrition contract manufacturers are consolidating supply relationships around vertically integrated collection networks with documented IgG stability data.
- Elderly:Immune senescence applications target aging populations in Japan and South Korea functional food markets.
- Adults:General wellness positioning captures broad supplement channel distribution with lower per-unit dosing requirements.
Athletes holds installed capacity. Infants is rotating up the share rankings.
Distribution Channel:
Channel configuration determines margin capture, with direct-to-consumer displacement of bulk brokers restructuring supplier responsiveness requirements.
- Online:Subscription supplement models and influencer-driven launches in US direct-to-consumer channels are compressing switching cycles and demanding faster supplier turnaround. Amazon and specialized health platforms are displacing traditional ingredient brokers as primary volume drivers for branded finished goods.
- Health Stores:Specialty retail networks stock premium-positioned SKUs with structure-function claim support for educated consumer segments. NOW Health Group and comparable distributors compete on breadth across mass-market and specialty channels.
- Supermarkets:Mass-market placement requires price competitiveness against plant-based protein alternatives with added immune-modulating ingredients.
- Pharmacies:Professional recommendation channels suit medical food positioning with healthcare practitioner education investments.
Health Stores holds installed capacity. Online is rotating up the share rankings.
Application:
Regulatory pathway differentiation separates supplement structure-function claims from functional food novel food evaluations across jurisdictions.
- Supplements:FDA New Dietary Ingredient notification requirements create compliance barriers favoring established suppliers with documented safety substantiation. US procurement relationships are concentrating around qualified vendors with vertically integrated bovine sourcing and colostrum collection networks.
- Functional Foods:EFSA novel food evaluations govern European market access for colostrum-derived ingredients intended beyond supplement applications. The evaluation timeline and safety data requirements are extending commercialization cycles compared to supplement-only pathways.
- Nutrition:General nutritional positioning spans multiple channels with lower regulatory burden but reduced differentiation.
- Immune Support:Structure-function claims require substantiation investment but enable premium pricing in targeted consumer segments.
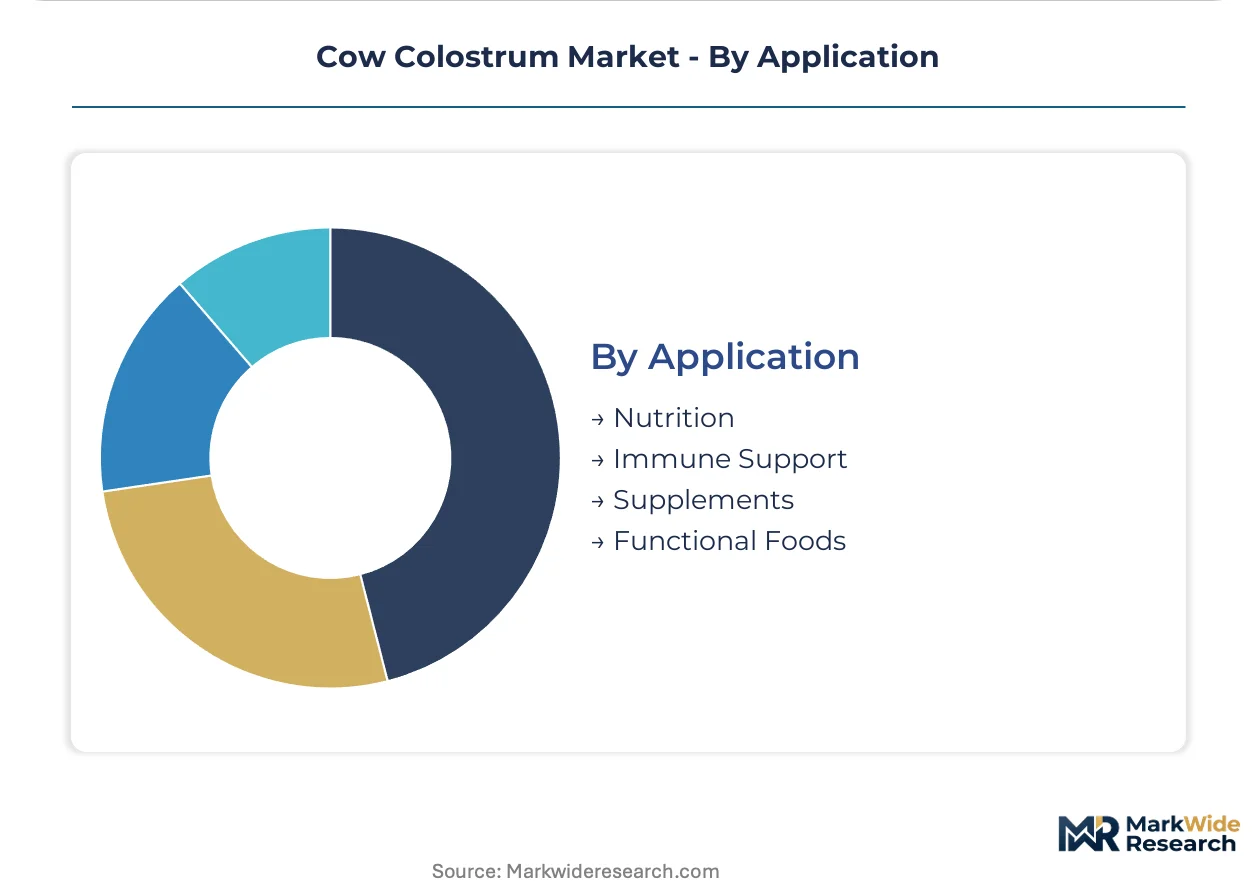
Supplements holds installed capacity. Functional Foods is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dietary supplement channels in the United States command premium positioning for colostrum powders and capsules, while European markets prioritize infant formula bioactive enrichment under stricter novel food evaluation pathways. This consumption-mix differential separates North American sports nutrition procurement from European functional food commercialization cycles.
United States
Direct-to-consumer subscription models and influencer-driven launches compress supplier switching cycles across Amazon and specialty health platforms. FDA New Dietary Ingredient notification requirements concentrate procurement relationships around qualified vendors with documented safety substantiation. Wisconsin and California dairy inspection jurisdictions anchor North American bovine sourcing networks for colostrum collection.
Germany
Infant formula and medical food segments drive demand for immunoglobulin-rich bioactive ingredients. EFSA novel food evaluations extend commercialization cycles by 18-36 months for colostrum-derived ingredients beyond supplement applications. Bavaria and North Rhine-Westphalia host dairy processing clusters adapting to equivalence arguments based on existing bovine milk protein approvals.
France
Medical food positioning targets aging populations with immune senescence applications. ANSM oversight intersects with EFSA novel food pathways for colostrum-derived functional ingredients. The Île-de-France region concentrates pharmaceutical-nutrition hybrid development for bioactive peptide isolation protocols.
Japan
Functional food markets prioritize immune support claims for elderly consumers in Tokyo and Osaka metropolitan areas. METI guidelines on health food labeling shape structure-function claim substantiation investments. Kanto and Kansai regions drive demand for microencapsulated shelf-stable liquid formats bypassing traditional cold-chain constraints.
Australia
Sports nutrition brands expand procurement for athletic recovery formulations targeting endurance and strength training segments. TGA therapeutic goods regulations govern colostrum supplement labeling and safety requirements. New South Wales and Victoria dairy cooperatives supply regional processing facilities for spray-dried powder export.
Cow Colostrum Market Competitive Environment
Capability concentration sits with fractionation specialists mastering immunoglobulin G concentration and lactoferrin separation; scale advantage sits with dairy-derived bioactive manufacturers leveraging existing spray-drying infrastructure. The market structures around three archetypes: vertically integrated bovine sourcing networks, contract manufacturing scale players, and direct-to-consumer channel specialists. Competitive moves center on backward integration into colostrum collection networks and portfolio diversification toward bioactive-specific ingredients.
Within the vertically integrated tier, PanTheryx exemplifies captive supply control over North American dairy cooperative networks. NOW Health Group occupies the channel breadth archetype, stocking colostrum SKUs across mass-market retail and specialty health store networks. Glanbia plc anchors the scale manufacturing position for dairy-derived bioactives serving sports nutrition and infant formula customers.
| Leading Market Players |
|---|
| PanTheryx |
| NOW Health Group |
| Glanbia plc |
| The Saskatoon Colostrum Company |
| Colostrum BioTec GmbH |
| Ingredia |
| Biodane Pharma A/S |
| ARMRA |
| Codeage |
| Others |
Value Chain & Pricing Dynamics
Midwest dairy freight corridors connecting Wisconsin processing clusters to California distribution hubs impose cold-chain cost premiums that stratify downstream pricing power between bulk powder traders and fractionation-capable processors serving premium capsule channels.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between vertically integrated collection networks and sports nutrition contract manufacturers, insulating qualified suppliers from spot volatility. Price differentiation hinges on USDA organic certification tier and documented immunoglobulin G stability data. Pricing pressure stems from spray-dried powder commoditization compressing undifferentiated supply margins. Mass-market retail buyers exhibit highest price sensitivity, while direct-to-consumer subscription channels absorb premium positioning for bioactive-specific ingredients.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements as processors compete for captive colostrum volumes from North American dairy cooperatives. Supply concentrates in the United States, Australia, and Germany, with raw material dependencies spanning bovine colostrum collection logistics, immunoglobulin assay reagents, and low-temperature pasteurization equipment. Single-source vulnerability around Wisconsin and California inspection jurisdictions creates regulatory concentration risk. Distribution runs through direct-to-consumer platforms displacing traditional bulk ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA New Dietary Ingredient notification requirements constitute a regulatory inflection concentrating procurement around qualified vendors, transforming competitive access into a high-growth disruption for bioactive-specific processors.
For Market Incumbents: Entrench supply relationships by securing backward integration into North American dairy cooperative collection networks with documented IgG stability protocols. Invest in microencapsulation technology R&D to bypass cold-chain constraints threatening liquid format viability. PanTheryx's vertically integrated model exemplifies the defensive moat against spot-market volatility.
For New Entrants and Emerging Players: Establish a beachhead in USDA organic-certified colostrum segments where premium pricing tolerates higher input costs. Target Japanese functional food markets for immune senescence applications among elderly populations, leveraging METI labeling guidelines for structure-function claim pathways. Pursue equivalence arguments based on existing bovine milk protein approvals to accelerate EFSA novel food evaluations.
For Investors and Strategic Acquirers: Fractionation specialists mastering immunoglobulin G concentration and lactoferrin separation represent the priority acquisition archetype for long-term viability across the 5-10 year projection horizon. Monitor EFSA novel food evaluation timelines as the critical signal for European market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive supply from Wisconsin and California dairy cooperatives secures input cost stability against seasonal calving volatility. |
| Bioactive Fractionation Capacity Expansion | Immunoglobulin G concentration protocols defend margin capture as spray-dried powder commoditizes. |
| Microencapsulation Technology Licensing | Shelf-stable liquid formats bypass cold-chain constraints limiting regional distribution reach. |
| USDA Organic Certification Investment | Premium pricing tier differentiation commands price absorption in California and Wisconsin inspection jurisdictions. |
| Direct-to-Consumer Channel Development | Subscription models on Amazon and specialty health platforms displace bulk ingredient brokers as primary volume drivers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA New Dietary Ingredient notifications, EFSA novel food evaluation databases, and USDA organic certification records. Primary interviews engaged dairy cooperative procurement managers, sports nutrition contract manufacturing executives, immunoglobulin assay laboratory directors, and direct-to-consumer brand operators. Secondary validation drew from SEC 10-K filings of publicly traded dairy bioactive processors, customs trade data on colostrum powder exports, and state-level dairy inspection protocols. Bottom-up volume modeling triangulated against top-down market sizing across product format, end-user physiology, and distribution channel dimensions.
Forecast inputs span spray-dried powder commoditization trajectories, fractionation technology adoption curves, and regulatory evaluation timeline shifts across the analysis window. Segmentation modeling incorporated product type, user physiology, channel economics, and application regulatory pathway. CAGRs derived from regression analysis of historical volume trends adjusted for technology migration and procurement pattern displacement. Industry-specific inputs included dairy cooperative collection capacity expansion and EFSA equivalence argument success rates.
Stress conditions across raw colostrum supply volatility, immunoglobulin assay standardization disputes, and plant-based protein substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology adoption and regulatory pathway timelines. Macroeconomic contraction, harmonized IgG quantification protocol emergence, or breakthrough microencapsulation cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Animal Growth Promoter Market