
 China Animal Milk Replacer Market | 2026-2036
China Animal Milk Replacer Market Size, Share, and Industry Trends Forecast 2026-2036
China Animal Milk Replacer Market Insights
China's dual carbon goals and tightening agricultural emissions standards are shifting procurement priorities across livestock operations. Cargill leverages its global protein expertise to supply fortified milk replacer formulations tailored to Chinese dairy genetics. Alltech competes through yeast-based nutritional technologies that improve calf gut health and feed conversion. Trouw Nutrition positions its precision nutrition platforms to capture demand from large-scale dairy farms in eastern provinces.
Animal milk replacer denotes a manufactured feed product formulated from dairy derivatives, vegetable proteins, fats, vitamins, and minerals to substitute maternal milk for young livestock. Manufacturers spray-dry emulsified fat-protein slurries into free-flowing powders that reconstitute with water at controlled temperatures for neonatal ruminants and equines. Calf milk replacer dominates value generation due to China's expanding Holstein herd and farm consolidation trends. Powder form anchors volume distribution through extended shelf stability and lower logistics costs versus liquid alternatives. Dairy farms represent the primary end-user segment, with procurement concentrating among operations exceeding five hundred head in Shandong and Hebei provinces.
SAMR enforces feed labeling and additive safety rules under national GB standards, while MEE oversight of livestock methane emissions is pressuring farms toward precision-fed early-life nutrition. China's PLI scheme for agricultural modernization indirectly subsidizes automated calf-feeding systems that integrate milk replacer dosing. Stakeholders must monitor evolving GB standard revisions and provincial environmental compliance timelines to align product portfolios with enforcement intensity across northern dairy belts.
Market Dynamics
GB standards tightening under SAMR enforcement is compressing formulation margins while accelerating consolidation among domestic compound feed manufacturers serving northern dairy belts.
Growth Catalysts
- Dual carbon policy framework:MEE methane emission caps on livestock operations are forcing farms toward precision-fed early-life nutrition that reduces enteric fermentation intensity per head.
- Holstein herd expansion:Dairy operations exceeding five hundred head in Shandong and Hebei provinces are standardizing calf milk replacer protocols to optimize genetic potential of imported breeding stock.
- Automated feeding integration:PLI scheme subsidies for agricultural modernization are driving adoption of sensor-based calf-feeding systems that synchronize milk replacer dosing with individual growth curves.
Market Restraints
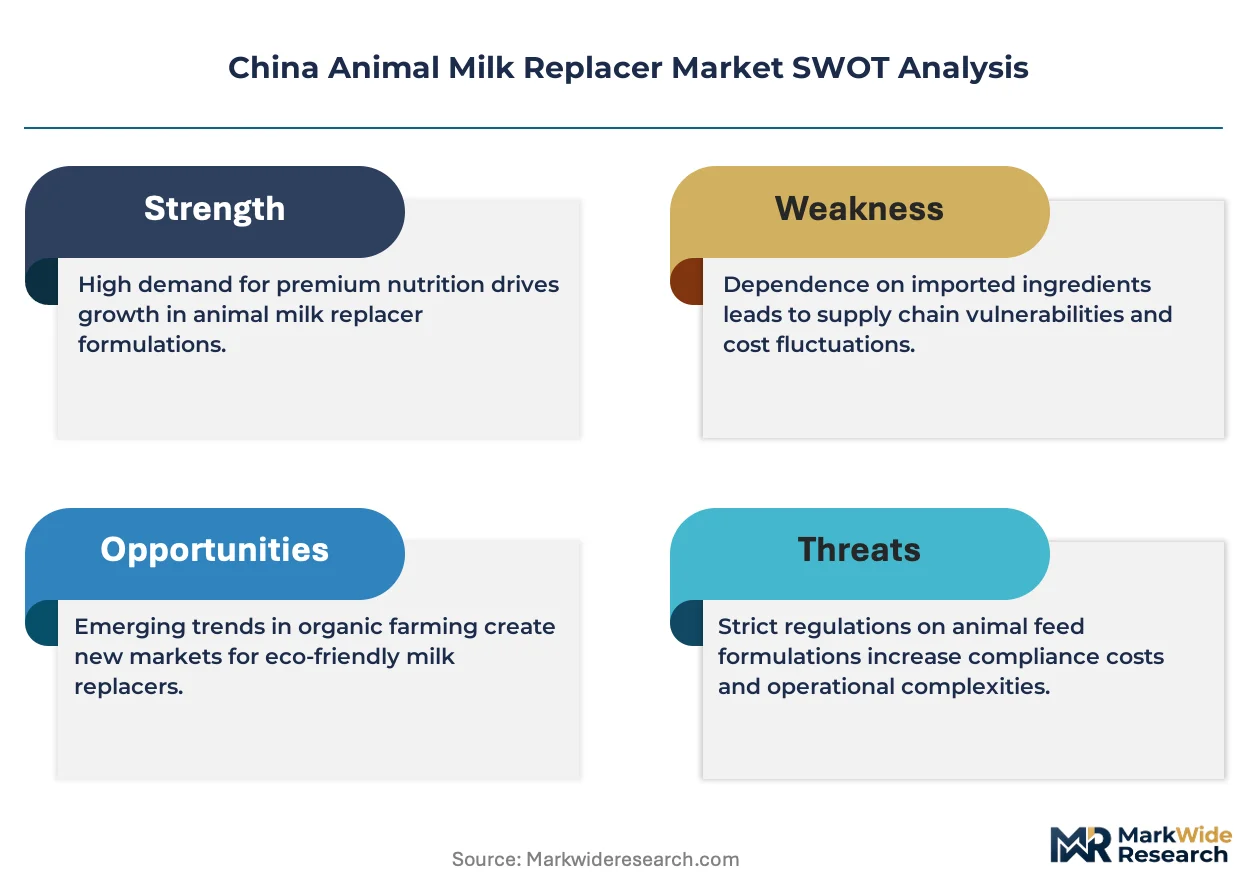
- Whey protein concentrate volatility:Import dependency on European and Oceanian dairy derivatives exposes formulators to currency fluctuation and ocean freight cost spikes.
- Provincial enforcement fragmentation:Inner Mongolia environmental compliance timelines lag Shandong by eighteen to twenty-four months, creating uneven competitive terrain for nationally distributed brands.
- Whole milk substitution persistence:Smallholder operations below two hundred head in Henan continue using on-farm whole milk for neonatal feeding due to capital constraints and traditional husbandry practices.
Strategic Opportunities
- Precision nutrition platforms:Large-scale eastern province dairies are unbundling nutrition consulting from commodity supply, creating margin capture for algorithm-driven formulation services.
- Yeast-based additive convergence:Beta-glucan and nucleotide technologies from human nutraceuticals are crossing into calf gut health applications with documented feed conversion improvements.
- Veterinary channel direct distribution:Provincial livestock service cooperatives in Hebei are consolidating procurement authority, bypassing traditional feed dealer networks for bulk milk replacer contracting.
Industry Challenges
- Formulation chemist scarcity:Domestic universities produce insufficient graduates with combined dairy science and spray-drying process engineering competencies required for GB-compliant product development.
- Legacy system integration friction:Automated calf feeders from European suppliers operate on incompatible data protocols with Chinese farm management software, forcing middleware development costs onto operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Animal Milk Replacer Market |
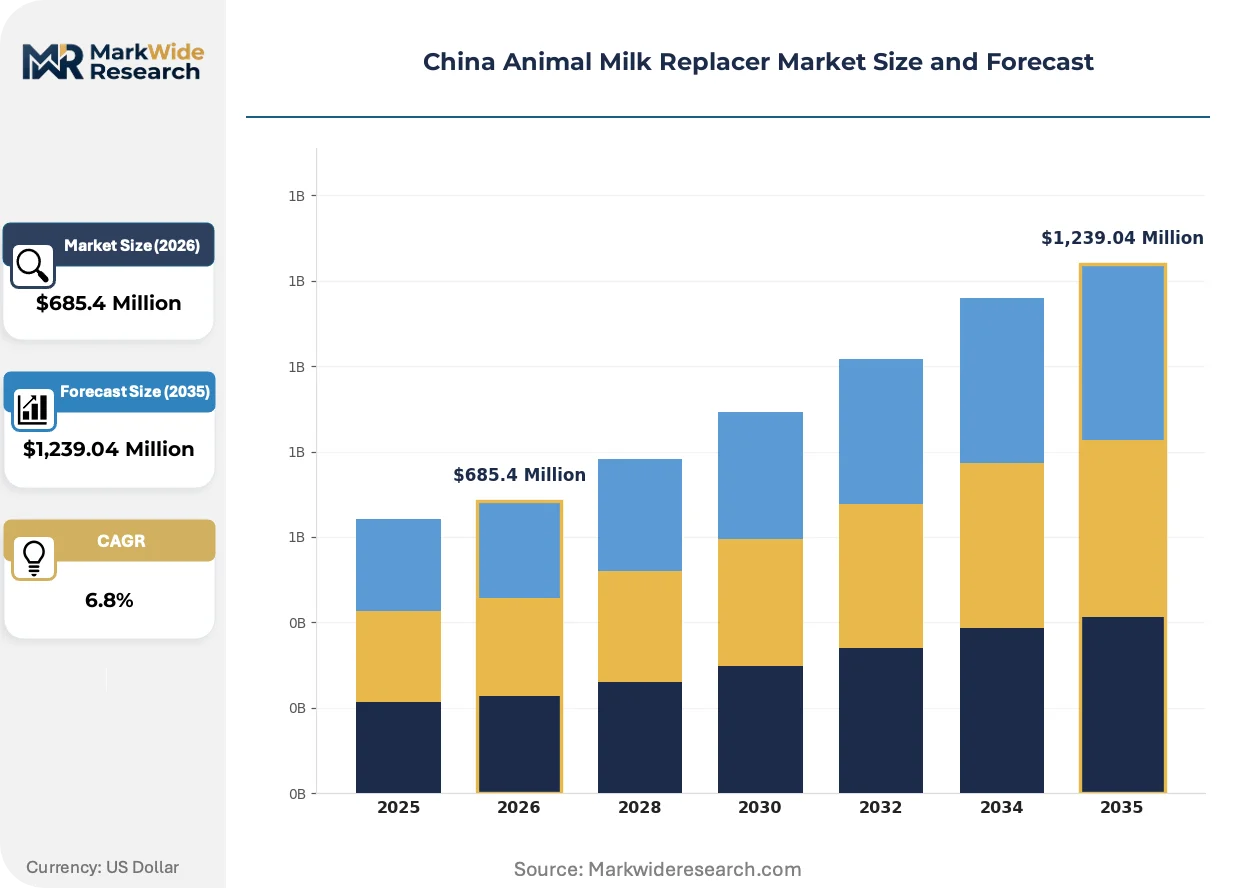
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calf Milk Replacer, Goat Milk Replacer, Sheep Milk Replacer, Foal Milk Replacer Form: Powder, Liquid, Paste, Concentrate End User: Dairy Farms, Livestock Producers, Agricultural Cooperatives, Veterinary Clinics Distribution Channel: Online Retail, Direct Sales, Distributors, Agricultural Shows |
| Companies Covered | Cargill, Archer-Daniels-Midland, CHS Inc, Glanbia, Nutreco, Land O'Lakes, Lactalis Group, Alltech, Trouw Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Animal Milk Replacer Market Trends and Innovations
Technological convergence between precision livestock farming and nutritional biochemistry is redefining value capture in early-life animal feeding systems across Chinese dairy operations.
Encapsulated lipid technologies are electrifying fat digestibility in neonatal ruminant formulations. Large-scale operations in Shandong province are adopting structured triglyceride emulsions at replacement rates exceeding sixty percent of conventional spray-dried fat sources. This shift is compressing the performance gap between milk replacer and whole milk while enabling earlier weaning protocols that accelerate facility turnover.
SAMR's draft revision to GB 13078 feed hygiene standards is mandating tighter microbiological thresholds for Enterobacteriaceae in milk replacer powders. Compound feed manufacturers in Hebei and Inner Mongolia are retrofitting spray-dryer systems with inline rapid microbial detection to preempt enforcement actions. The regulatory pressure is most acute for export-oriented processors supplying cross-border e-commerce channels into Southeast Asian markets.
Consolidated procurement committees at provincial dairy cooperatives are displacing individual farm purchasing autonomy. These committees now negotiate annual volume contracts with formulation houses, unbundling technical service fees from commodity powder pricing. The behavioral shift is most visible in eastern provinces where operations exceeding one thousand head dominate regional supply pools and demand outcome-based calf growth guarantees written into supply agreements.
China Animal Milk Replacer Market Segmentation
Segmentation in China's animal milk replacer market determines which formulation houses bear GB standard compliance costs and which distribution channels absorb provincial environmental enforcement timelines. Dairy farm procurement consolidation across Shandong and Hebei is compressing segment boundaries as large operations demand cross-category performance guarantees.
Product Type:
GB 13078 feed hygiene standards apply unevenly across species-specific formulations, with calf products facing the strictest Enterobacteriaceae thresholds under SAMR's draft revision.
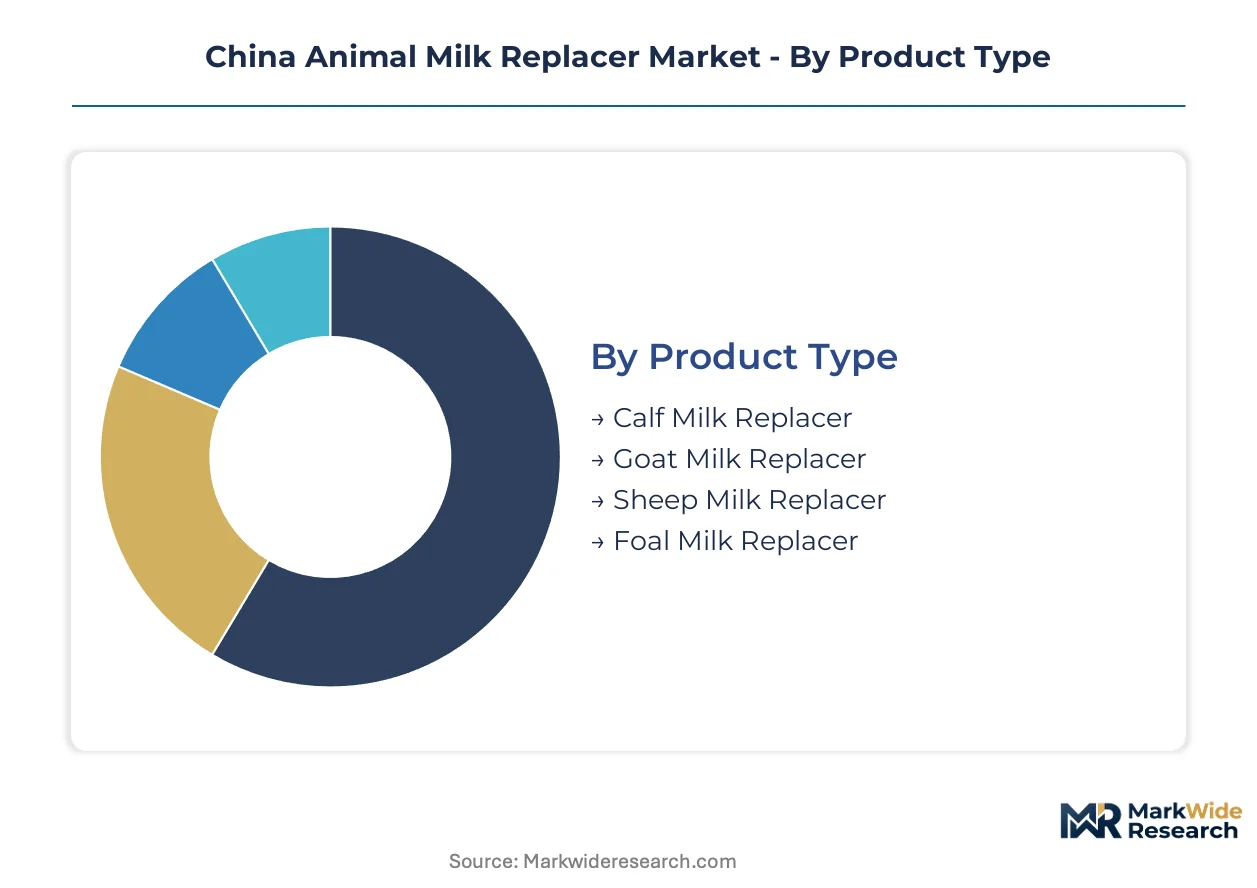
- Calf Milk Replacer:Spray-dried emulsions of dairy derivatives, vegetable proteins, and fortified fats formulated for neonatal Holstein calves. Demand clusters in Shandong and Hebei provinces where operations exceeding five hundred head standardize protocols for imported breeding stock genetic optimization.
- Goat Milk Replacer:Lower-lactose formulations with adjusted protein-fat ratios for caprine neonates. Procurement concentrates among Inner Mongolia pastoral cooperatives where goat dairy expansion lags environmental compliance timelines by eighteen to twenty-four months versus eastern provinces.
- Sheep Milk Replacer:Specialized formulations for ovine maternal milk substitution in northwestern grassland operations.
- Foal Milk Replacer:Equine-specific nutritional blends serving breeding farms in Xinjiang and Inner Mongolia racing stock operations.
Calf milk replacer sits at the top of the volume ranking, with goat milk replacer climbing the fastest as provincial cooperatives consolidate caprine dairy procurement.
Form:
Cost tier stratification separates premium spray-dried powders from economy liquid concentrates based on shelf stability requirements and automated feeder compatibility.
- Powder:Free-flowing spray-dried particles reconstituting at controlled temperatures. Extended shelf stability and lower logistics costs anchor volume distribution across northern dairy belts.
- Liquid:Ready-to-feed emulsions requiring cold chain integrity. Demand concentrates among smallholder operations below two hundred head in Henan province with limited capital for mixing infrastructure.
- Paste:Semi-solid formulations for manual feeding protocols in remote pastoral regions.
- Concentrate:High-solids preparations requiring dilution at point of use.
Powder form dominates procurement volumes, with liquid concentrates gaining share fastest among veterinary clinic direct-distribution channels.
End User:
Customer type determines whether procurement runs through consolidated cooperative committees or fragmented individual farm purchasing.
- Dairy Farms:Primary demand concentration among operations exceeding five hundred head in Shandong and Hebei provinces standardizing calf milk replacer protocols.
- Livestock Producers:Diverse operations spanning beef cattle, sheep, and goat production with variable formulation requirements.
- Agricultural Cooperatives:Provincial livestock service cooperatives in Hebei consolidating procurement authority and bypassing traditional feed dealer networks for bulk contracting.
- Veterinary Clinics:Emerging direct-distribution channel for precision nutrition platforms with outcome-based growth guarantees.
Dairy farms anchor the customer base by volume, with agricultural cooperatives expanding most quickly as procurement committees displace individual farm autonomy.
Distribution Channel:
Supply concentration in spray-dryer manufacturing shapes which channels control formulation pricing power.
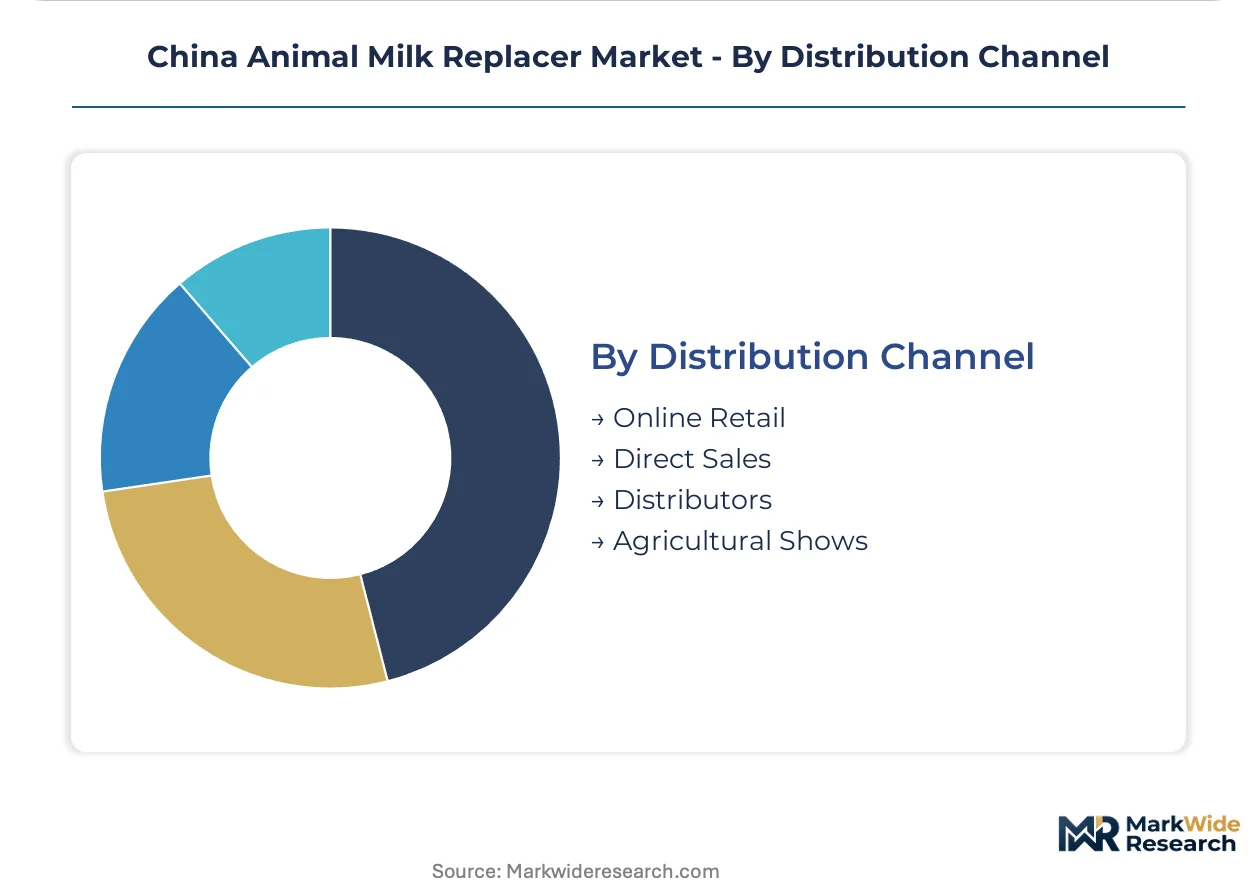
- Direct Sales:Formulation houses contract directly with provincial cooperative procurement committees for annual volume agreements unbundling technical service fees from commodity powder pricing.
- Distributors:Traditional feed dealer networks serving fragmented smallholder operations below two hundred head in Henan and southwestern provinces.
- Online Retail:Cross-border e-commerce channels into Southeast Asian markets requiring stricter microbiological thresholds for export-oriented processors.
- Agricultural Shows:Seasonal demonstration and sampling events for automated calf-feeding system integration.
Direct sales channels capture the largest volume flows, with online retail demonstrating the steepest expansion trajectory as export-oriented processors build Southeast Asian market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's animal milk replacer industry traces its modern scaling to the dairy sector restructuring of the 2000s, when state-led farm consolidation created concentrated demand clusters across northern provinces. Provincial livestock belts now drive procurement patterns shaped by divergent environmental enforcement timelines.
Shandong Province
Holstein operations exceeding one thousand head dominate calf milk replacer procurement, with automated feeding systems penetrating sixty percent of large dairies. SAMR's GB 13078 enforcement is strictest here, forcing spray-dryer retrofits among Hebei-bordering processors. The Jinan-Weifang corridor anchors formulation manufacturing serving the Bohai Rim dairy belt.
Hebei Province
Provincial livestock service cooperatives are consolidating procurement authority, bypassing traditional feed dealer networks for bulk milk replacer contracting. MEE methane emission caps apply full force, accelerating precision-fed early-life nutrition adoption. The Zhangjiakou-Shijiazhuang axis concentrates dairy farm clusters integrating sensor-based calf feeders.
Inner Mongolia
Environmental compliance timelines lag Shandong by eighteen to twenty-four months, creating uneven competitive terrain for nationally distributed brands. Goat milk replacer procurement concentrates among pastoral cooperatives where caprine dairy expansion proceeds slower. The Hohhot-Baotou corridor hosts spray-dryer capacity serving both dairy and racing stock operations.
Henan Province
Smallholder operations below two hundred head persist with on-farm whole milk feeding due to capital constraints and traditional husbandry practices. The provincial agricultural modernization fund indirectly subsidizes automated systems, but uptake remains fragmented. The Zhengzhou periphery anchors distributor networks serving southwestern demand pockets.
Xinjiang Uygur Autonomous Region
Foal milk replacer demand clusters around thoroughbred breeding farms serving racing stock operations. Western logistics constraints favor powder formulations with extended shelf stability over liquid alternatives. The Ürümqi-Changji corridor concentrates equine nutrition procurement linked to Central Asian export channels.
China Animal Milk Replacer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service bundling. The vendor base stratifies into three tiers: global protein majors with spray-dryer ownership, regional compound feed houses with cooperative procurement relationships, and specialty additive suppliers with precision nutrition platforms. Consolidation pressure intensifies as GB standard compliance costs compress mid-tier margins. Dominant competitive moves include backward integration into whey protein concentrate sourcing and algorithm-driven formulation service unbundling.
Within the global protein major tier, Cargill and Glanbia occupy positions leveraging dairy derivatives expertise across Asian markets. Nutreco and Trouw Nutrition exemplify precision nutrition platform specialists competing through outcome-based growth guarantees. Alltech anchors the yeast-based additive convergence with gut health technologies crossing from human nutraceutical applications. These three archetypes—commodity protein majors, precision nutrition specialists, and biotech additive innovators—capture diverging margin pools as procurement committees unbundle technical services from commodity powder pricing.
| Leading Market Players |
|---|
| Cargill |
| Archer-Daniels-Midland |
| CHS Inc |
| Glanbia |
| Nutreco |
| Land O'Lakes |
| Lactalis Group |
| Alltech |
| Trouw Nutrition |
| Others |
Pricing and Supply Chain Analysis
Procurement committees at provincial dairy cooperatives in Hebei and Shandong command annual volume contracts that unbundle technical service fees from commodity powder pricing, compressing margin capture for formulation houses serving fragmented smallholder networks in Henan. This buyer concentration rewards spray-dryer ownership and algorithm-driven formulation capabilities while penalizing distributors without direct cooperative relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates encapsulated lipid formulations with structured triglyceride emulsions from conventional spray-dried powders and unfortified commodity blends. Price differentiation hinges on GB 13078 microbiological compliance certification and automated feeder compatibility rather than brand recognition alone. Cost compression in the economy tier is intensifying because SAMR enforcement retrofits are squeezing mid-tier compound feed manufacturers without captive spray-dryer capacity. Smallholder operations below two hundred head in Henan exhibit the highest price sensitivity, while operations exceeding one thousand head in Shandong prioritize outcome-based growth guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in the Jinan-Weifang corridor and Zhangjiakou-Shijiazhuang axis operate hub-and-spoke patterns radiating into northern dairy belts, with powder formulations dominating logistics economics over liquid alternatives requiring cold chain integrity. Manufacturing concentrates in China, with whey protein concentrate and dairy derivatives drawn from European and Oceanian suppliers. Supply chain risk centers on single-source vulnerability for imported whey protein concentrate exposed to currency fluctuation and ocean freight cost spikes. Distribution runs through direct sales channels to provincial cooperative procurement committees, bypassing traditional feed dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's animal milk replacer market reads as a late-cycle quality story where GB 13078 compliance investments and precision nutrition capabilities separate viable suppliers from margin-compressed commodity players. Demand is shifting toward encapsulated lipid formulations with documented feed conversion improvements.
For Market Incumbents: To counter formulation chemist scarcity and domestic university pipeline gaps, secure backward integration into whey protein concentrate sourcing through long-term offtake agreements with European and Oceanian suppliers. Expand spray-dryer capacity in the Hohhot-Baotou corridor to capture Inner Mongolia procurement as environmental compliance timelines converge with eastern provinces. For New Entrants and Emerging Players: Launch via veterinary clinic direct-distribution channels serving precision nutrition platforms with outcome-based growth guarantees. The most penetrable white space sits among agricultural cooperatives in Hebei consolidating procurement authority, where algorithm-driven formulation services remain unbundled from commodity supply. Target goat milk replacer formulations for Inner Mongolia pastoral cooperatives where caprine dairy expansion lags environmental compliance timelines. For Investors and Strategic Acquirers: Global protein majors with spray-dryer ownership are the most active acquirers in this space, seeking precision nutrition platform specialists with algorithm-driven formulation capabilities. The long-term viability window favors targets with GB 13078 compliance infrastructure and direct cooperative procurement relationships over distributor-dependent models. Monitor SAMR enforcement intensity across northern dairy belts as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Protein Concentrate Sourcing | Reduces import dependency exposure for European and Oceanian dairy derivatives. |
| Precision Nutrition Platform Development | Captures margin from Shandong dairies unbundling consulting from commodity supply. |
| GB 13078 Compliance Infrastructure Investment | Preempts SAMR enforcement actions and secures export-oriented processor status. |
| Provincial Cooperative Direct Sales Channel Expansion | Bypasses traditional feed dealer networks in Hebei and accelerates volume capture. |
| Yeast-Based Additive Convergence R&D | Leverages Alltech-proven beta-glucan technologies crossing from human nutraceuticals. |
Research Methodology
Direct dialogue with spray-dryer operations managers, provincial cooperative procurement committee heads, veterinary nutritionists at large-scale dairies, and SAMR regulatory affairs specialists grounded this analysis in operational reality. Secondary validation drew from GB standard revision drafts, MEE livestock emissions enforcement timelines, PLI scheme subsidy disclosures, and customs records for whey protein concentrate imports. Bottom-up and top-down triangulation cross-checked facility-level production estimates against provincial herd expansion data.
Bottom-up volume modeling segmented by product type, form, end user, and distribution channel across the analysis window, with value outputs derived from unbundled technical service fee structures and commodity powder pricing. CAGRs were computed from normalized base-year positioning through iterative convergence of demand-side procurement patterns and supply-side capacity constraints. Key inputs included Holstein herd expansion rates in Shandong and Hebei, automated calf feeder adoption curves, and SAMR enforcement intensity differentials across provincial livestock belts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt GB standard revision timelines or extended whey protein concentrate supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Feed Electrolytes Market