
 Animal Growth Promoter Market | 2026-2036
Animal Growth Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Growth Promoter Market Analysis
Pharmaceutical-grade specification tiers is collapsing into feed-grade standards across several product lines. Zoetis Inc. anchors its position through R&D intensity in vaccine-based growth promotion. Elanco Animal Health dominates the antibiotic-alternative pipeline with specialized probiotic development programs. Kemin Industries leverages its manufacturing scale to control premix distribution networks across North American livestock corridors.
Animal growth promoters encompass feed additives, supplements, and pharmaceutical agents administered to livestock to improve feed conversion efficiency, accelerate weight gain, and enhance disease resistance, typically formulated as premixes containing defined active concentrations of organic acids, probiotic cultures, or ionophore compounds. The primary commercial purpose centers on reducing production cycle duration while maintaining carcass quality specifications in intensive animal agriculture. Probiotics and amino acids represent the fastest-expanding product categories as antibiotic restrictions tighten across major consuming regions. Feed additives occupy the largest margin pool within formulation types due to integration requirements with compound feed manufacturing. Poultry applications sustain the highest volume throughput among livestock segments, though aquaculture growth promotion commands premium pricing for specialized marine formulations.
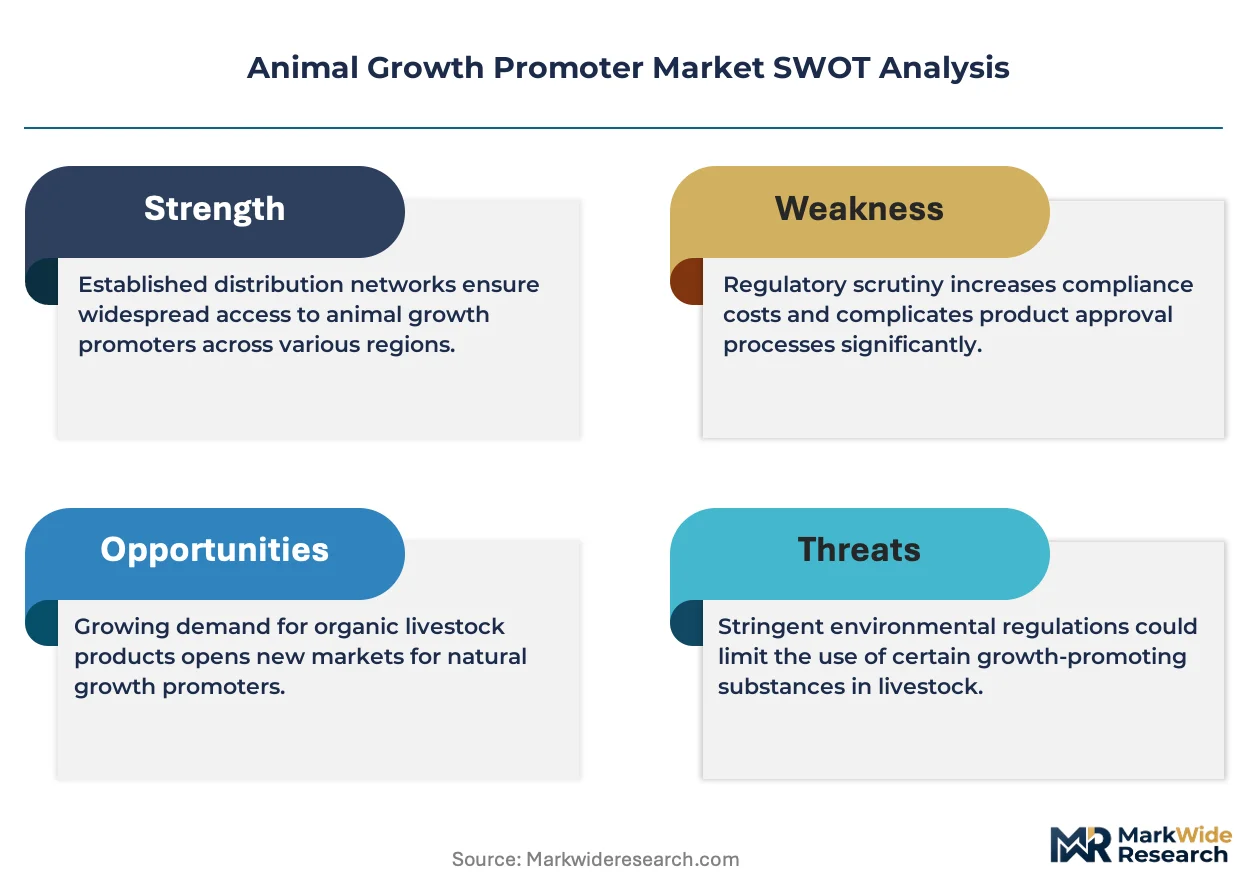
The FDA's Veterinary Feed Directive restricts medically important antibiotic use in livestock feed, reshaping product registration pathways and veterinary oversight requirements in the United States. EFSA's continued assessment of additive safety under EU Regulation 1831/2003 determines market access for novel growth-promoting compounds across European member states. China's Ministry of Agriculture and Rural Affairs maintains its national catalog of permitted feed additives, creating a dual-track compliance environment for domestic and imported formulations. Stakeholders must monitor regulatory divergence between antibiotic-tolerant and antibiotic-restrictive jurisdictions when allocating product development resources and manufacturing capacity.
Market Dynamics
Regulatory bifurcation between antibiotic-permissive and antibiotic-restrictive jurisdictions is fragmenting product development pipelines and forcing parallel formulation strategies for the same active ingredients.
Growth Catalysts
- EFSA's additive safety assessments under EU Regulation 1831/2003:These evaluations accelerate approval pathways for novel probiotic strains and organic acid blends, creating a template that Brazil's ANVISA and China's Ministry of Agriculture increasingly reference for their own feed additive catalogs.
- Poultry sector intensification in Southeast Asia:Commercial integrators in Vietnam and Indonesia are consolidating smallholder supply chains, driving standardized premix adoption through contract farming arrangements that mandate defined growth promoter protocols.
- Precision fermentation for amino acid production:This manufacturing platform reduces feed-grade lysine and methionine costs, enabling broader supplementation in ruminant diets previously constrained by price thresholds.
Market Restraints
- Feed-grade phosphate price volatility:Moroccan and Chinese phosphate rock concentration exposes premix manufacturers to input cost swings that compress margin structures during contract renewal cycles.
- Technical limitation in anaerobic probiotic stabilization:Shelf-life constraints for live culture formulations restrict distribution radius and cold-chain requirements, particularly challenging for aquaculture applications in tropical climates.
- Regulatory friction from FDA's Veterinary Feed Directive:Veterinary oversight requirements for medically important antibiotics add prescription layers that slow feed mill procurement workflows and extend order fulfillment timelines.
Strategic Opportunities
- Underpenetrated aquaculture in Nigeria and Egypt:African catfish and tilapia operations currently rely on minimal supplementation, presenting first-mover advantages for specialized marine probiotic formulations adapted to warm-water species.
- Technology convergence of phage therapy and precision microbiome editing:Combined platforms targeting pathogen-specific suppression without broad-spectrum disruption align with antibiotic-free certification requirements in German and Dutch retail supply chains.
- Direct-to-farm digital distribution channels:Vertical platforms connecting premix manufacturers with mid-scale livestock operations in Australia's Queensland and Victoria bypass traditional distributor markups and capture margin previously allocated to feed dealer networks.
Industry Challenges
- Microbiome characterization skill gaps:Formulation teams lack sufficient bioinformatics capacity to interpret 16S rRNA sequencing data for strain-specific efficacy claims, slowing product development cycles and regulatory dossier preparation.
- Dual-track compliance architecture:Manufacturers serving both antibiotic-tolerant Latin American markets and antibiotic-restrictive European customers must maintain separate production lines, quality systems, and inventory pools, inflating working capital requirements and operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Growth Promoter Market |
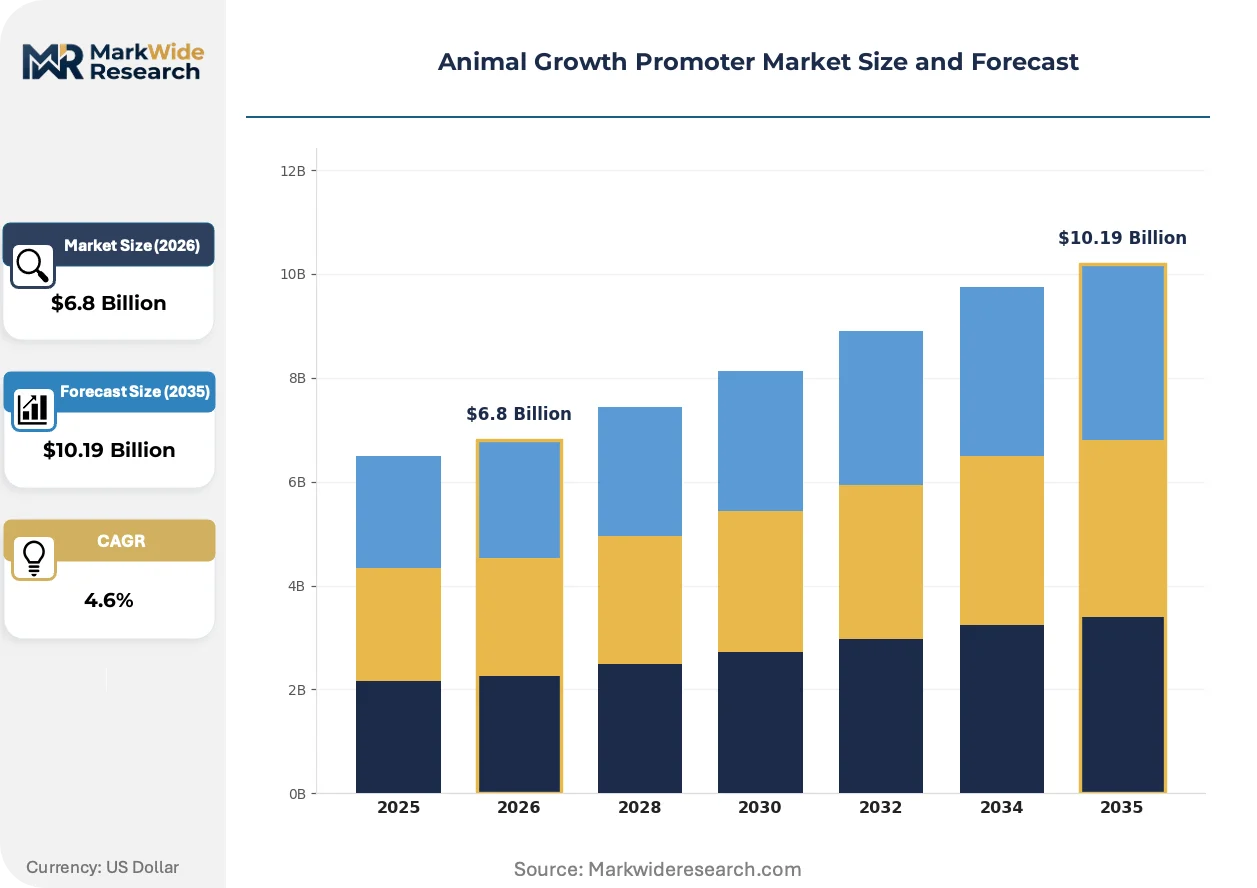
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Antibiotics, Vaccines, Probiotics Active Ingredient: Zinc Bacitracin, Chlortetracycline, Salinomycin, Tylosin Livestock Type: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Feed Additives, Supplements, Liquid Formulations, Premixes |
| Companies Covered | Cargill Inc., Zoetis Inc., DSM-Firmenich, Elanco Animal Health, Alltech Inc., Boehringer Ingelheim, Bayer Animal Health, Kemin Industries, Novonesis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Growth Promoter Market Emerging Trajectories
Biotechnology platforms are compressing the innovation cycle for non-antibiotic growth promotion, while regulatory pressure and buyer consolidation simultaneously reshape how these products reach livestock operations.
Precision microbiome modulation using targeted postbiotic metabolites is displacing live probiotic cultures in intensive poultry systems. Brazilian and Thai integrators are adopting these heat-stable formulations at scale to eliminate cold-chain dependencies. This technology is displacing traditional fermentation-based products in regions where infrastructure constraints previously limited probiotic penetration.
China's GB standards for feed additive safety are tightening residue monitoring and manufacturing practice requirements for both domestic and imported formulations. The Ministry of Agriculture and Rural Affairs now mandates batch-level traceability documentation that mirrors EU audit protocols. Aquaculture growth promoters face the steepest compliance burden, as marine species metabolize additives differently than terrestrial livestock, requiring expanded toxicology dossiers.
Buyer consolidation among North American pork processors is compressing supplier qualification timelines and unbundling technical advisory services from product procurement. Large integrators in Iowa and North Carolina now source amino acid premixes through centralized tenders while retaining independent nutrition consultants, stripping traditional suppliers of service-margin capture. This pattern is most visible in contract grower arrangements where packers dictate feed formulation specifications directly.
Animal Growth Promoter Market Segmentation
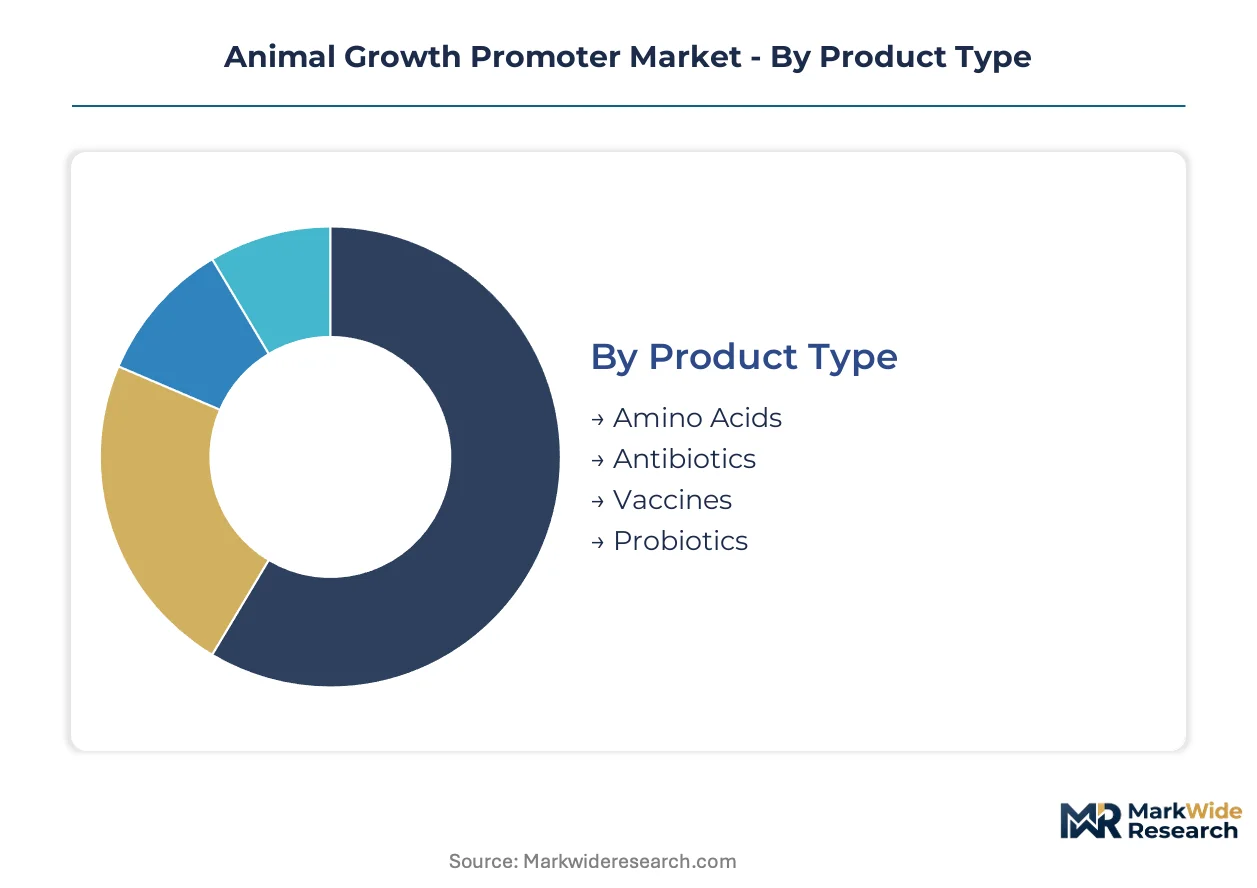
Animal growth promoter manufacturers configure product portfolios across four intersecting dimensions. Each segmentation layer determines formulation economics, regulatory pathway complexity, and customer procurement behavior in distinct ways.
Product Type:
Margin pools concentrate in probiotic and amino acid categories as antibiotic restrictions expand across major livestock-producing jurisdictions.
- Probiotics:Live microbial cultures or spore-forming bacilli delivered via feed or water systems. Vietnamese and Indonesian poultry integrators are mandating these formulations through contract farming protocols to meet export certification requirements. Shelf-life constraints and cold-chain dependencies limit distribution radius in tropical climates.
- Amino Acids:Precision-fermented lysine, methionine, and threonine specified for species-optimized inclusion rates. China's integrated pork producers are adopting premix formats at rates exceeding regional benchmarks as domestic lysine manufacturing scales reduce unit costs.
- Antibiotics:Ionophore coccidiostats and therapeutic agents facing restricted use under FDA Veterinary Feed Directive and EFSA guidelines. Brazilian and Southeast Asian operations retain access but face tightening residue monitoring protocols.
- Vaccines:Immunological growth promotion agents requiring cold-chain infrastructure and veterinary administration. R&D intensity from major animal health companies is compressing development cycles for novel vector platforms.
Probiotics holds installed capacity. Amino acids is rotating up the share rankings.
Active Ingredient:
Cost tier stratification separates legacy antibiotic actives from novel microbiome-modulating compounds across formulation portfolios.
- Salinomycin:Polyether ionophore coccidiostat with established efficacy in broiler operations. Regulatory divergence between antibiotic-permissive Latin American markets and restrictive European jurisdictions forces parallel production lines and inventory pools.
- Zinc Bacitracin:Polypeptide antibiotic growth promoter with residual permitted use in specific markets. Chinese GB standards and EU Regulation 1831/2003 impose divergent residue limits that complicate cross-border formulation strategies.
- Chlortetracycline:Tetracycline-class therapeutic agent now classified as medically important antibiotic in US jurisdictions. Veterinary prescription requirements under FDA guidance extend feed mill procurement timelines.
- Tylosin:Macrolide antibiotic restricted to therapeutic indications in major consuming regions. Withdrawal period specifications vary substantially between national feed additive catalogs.
Salinomycin maintains volume leadership. Zinc bacitracin is gaining share fastest in antibiotic-tolerant markets.
Livestock Type:
Application intensity varies dramatically, with poultry sustaining highest volume throughput while aquaculture commands premium pricing for specialized marine formulations.
- Poultry:Broiler and layer operations with standardized growth cycles driving premix standardization. Southeast Asian commercial integrators are consolidating smallholder supply chains through mandated supplementation protocols.
- Swine:Integrated pork production systems with phase-feeding programs optimizing amino acid inclusion by growth stage. Chinese operations are outpacing regional adoption benchmarks for advanced premix formats.
- Ruminants:Cattle and sheep operations with rumen-protected formulation requirements limiting product transferability from monogastric species. Precision fermentation cost reductions are enabling broader amino acid supplementation previously constrained by price thresholds.
- Aquaculture:Warm-water and cold-water species with distinct metabolization profiles requiring expanded toxicology dossiers. Nigerian catfish and Egyptian tilapia operations present underpenetrated demand for specialized marine probiotic formulations.
Poultry holds installed capacity. Aquaculture is climbing the fastest in revenue per ton terms.
Formulation Type:
Supply concentration in premix manufacturing creates margin capture opportunities for integrated compound feed producers relative to standalone additive suppliers.
- Premixes:Defined-concentration blends requiring precision mixing infrastructure and batch-level traceability documentation. China's Ministry of Agriculture now mandates documentation mirroring EU audit protocols for both domestic and imported formulations.
- Feed Additives:Direct inclusion products integrated at compound feed manufacturing stage. North American pork processor consolidation is compressing supplier qualification timelines and unbundling technical advisory services from procurement.
- Supplements:Top-dress or water-soluble formats for targeted intervention periods. Distribution runs through veterinary and feed dealer channels with regional variation in advisory service bundling.
- Liquid Formulations:Water-delivery systems for large-scale operations with automated dosing infrastructure. Australian direct-to-farm digital platforms are bypassing traditional distributor markups in Queensland and Victoria livestock corridors.
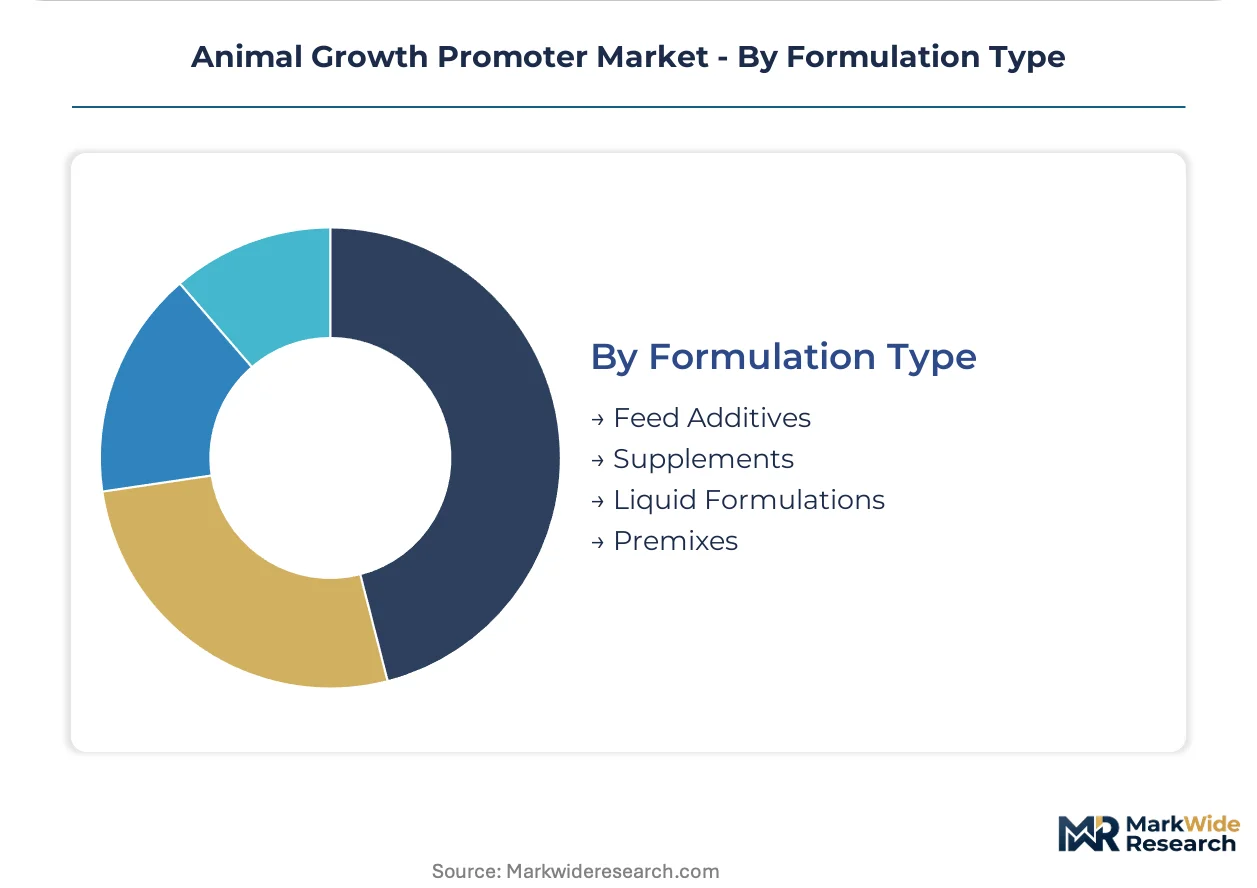
Premixes holds installed capacity. Feed additives is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented livestock operations in Brazil and Southeast Asia drive formulation demand, while import-dependent markets in the Middle East and North Africa create premix distribution opportunities. Regulatory divergence between antibiotic-restrictive and antibiotic-permissive jurisdictions fragments supply chains and forces parallel inventory strategies.
United States
Integrated pork processors in Iowa and North Carolina dictate amino acid premix specifications through centralized procurement tenders. The FDA's Veterinary Feed Directive mandates veterinary oversight for medically important antibiotics, extending feed mill order fulfillment timelines. Commercial broiler operations in Georgia and Arkansas sustain the highest domestic volume throughput for non-antibiotic growth promoters.
China
Domestic lysine manufacturing scale reduces unit costs and accelerates premix adoption across integrated pork production systems. The Ministry of Agriculture and Rural Affairs mandates batch-level traceability documentation mirroring EU audit protocols for both domestic and imported formulations. Yangtze River Delta feed compounders concentrate advanced premix manufacturing capacity serving coastal livestock corridors.
Brazil
Commercial integrators expand probiotic supplementation in poultry operations to maintain export certification for European and Japanese buyers. ANVISA references EFSA additive safety assessments when updating the national feed additive catalog, accelerating approval pathways for novel strains. São Paulo state anchors premix distribution networks serving the southeastern livestock belt.
Germany
Retail supply chain antibiotic-free certification requirements from Dutch and German packers drive phage therapy and precision microbiome editing investments. EFSA assessments under EU Regulation 1831/2003 determine market access for novel growth-promoting compounds across member states. Lower Saxony's dense livestock concentration generates concentrated demand for specialized rumen-protected formulations.
Vietnam
Commercial integrators consolidate smallholder supply chains through contract farming arrangements mandating standardized growth promoter protocols. The country's national agricultural regulator increasingly references EFSA safety templates for domestic feed additive approvals. Mekong Delta poultry operations drive regional volume for heat-stable postbiotic formulations eliminating cold-chain dependencies.
Animal Growth Promoter Market Vendor Landscape
Concentration sits with diversified animal health conglomerates and specialized feed additive suppliers rather than standalone pharmaceutical manufacturers. Three archetypes dominate: vertically integrated nutrition companies controlling premix distribution networks, R&D-intensive animal health firms prioritizing vaccine-based growth promotion, and regional fermentation specialists supplying precision-manufactured amino acids. Competitive moves center on backward integration into active ingredient production and geographic expansion through distributor acquisition in underpenetrated livestock corridors.
Within the diversified animal health tier, Zoetis Inc. and Elanco Animal Health occupy positions exemplifying R&D intensity in non-antibiotic alternatives, while Kemin Industries represents the manufacturing-scale archetype controlling North American premix distribution networks. Cargill Inc. anchors the nutrition-integrated segment through captive supply chain control. These three entities collectively illustrate how competitive positioning stratifies between research-driven product development and logistics-dominated market access.
| Leading Market Players |
|---|
| Cargill Inc. |
| Zoetis Inc. |
| DSM-Firmenich |
| Elanco Animal Health |
| Alltech Inc. |
| Boehringer Ingelheim |
| Bayer Animal Health |
| Kemin Industries |
| Novonesis |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day premix order fulfillment cycles concentrate pricing power with integrated compound feed manufacturers who control mixing infrastructure and batch-level traceability documentation. This lead-time band reflects regulatory compliance burdens under China's Ministry of Agriculture mandates and EFSA audit protocols, which simultaneously inflate working capital requirements and create margin capture opportunities for vertically integrated nutrition companies.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across amino acid and probiotic categories. Price differentiation hinges on certification grade under EU Regulation 1831/2003 and FDA Veterinary Feed Directive compliance tiers, alongside volume scale commitments from integrated pork processors. Cost compression in feed-grade phosphate inputs is intensifying because Moroccan and Chinese rock concentration exposes manufacturers to commodity swings. Smallholder contract growers exhibit highest price sensitivity, while North American pork packers retain lowest due to centralized procurement scale.
Supply Chain Analysis
Forty-five-day cold-chain inventory thresholds for live probiotic cultures constrain distribution radius and inflate logistics costs across tropical livestock corridors. Manufacturing gravity centers on China for precision-fermented lysine, the United States for vaccine-vector platforms, and Brazil for poultry-focused premix formulation. Active ingredient production draws from phosphate rock deposits, corn-derived fermentation feedstocks, and marine biomass for specialized aquaculture applications. Single-source vulnerability concentrates in Moroccan phosphate supply. Distribution runs through feed dealer networks and direct-to-farm digital platforms in Australian livestock corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation cost curves and regulatory bans on antibiotic growth promoters are compressing innovation cycles for non-antibiotic alternatives, creating high-growth disruption as biotechnology platforms displace legacy formulation economics.
For Market Incumbents: Fortify backward integration into active ingredient production, particularly precision-fermented amino acid capacity, to defend margin structures against phosphate price volatility and fermentation feedstock cost swings. Deepen channel control through distributor acquisition in underpenetrated Nigerian and Egyptian aquaculture corridors, where minimal supplementation creates first-mover insulation against emerging regional fermentation specialists.
For New Entrants and Emerging Players: EFSA additive safety fast-tracks under EU Regulation 1831/2003 accelerate approval pathways for novel probiotic strains, enabling entry ahead of domestic catalog updates in Vietnam and Indonesia. Target warm-water aquaculture in African markets through heat-stable postbiotic formulations that eliminate cold-chain dependencies, leveraging direct-to-farm digital distribution to bypass entrenched feed dealer markups.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified animal health conglomerates seeking to divest non-core feed additive portfolios amid buyer consolidation among North American pork processors. Focus on mid-scale premix manufacturers with captive distribution networks in antibiotic-tolerant Latin American markets, where regulatory divergence sustains parallel inventory strategies. Watch for inflection when China's Ministry of Agriculture tightens GB standards residue monitoring, accelerating domestic consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captive lysine and methionine production insulates margin structures from phosphate feedstock volatility. |
| Direct-to-Farm Digital Distribution Launch | Vertical platforms connecting premix manufacturers with Queensland livestock operations bypass traditional dealer markups. |
| EFSA Additive Safety Fast-Track Pursuit | Novel probiotic strain approvals create template referenced by Brazil's ANVISA and China's Ministry of Agriculture. |
| Heat-Stable Postbiotic Formulation Development | Tropical climate adaptation eliminates cold-chain dependencies and extends distribution radius in Southeast Asia. |
| Aquaculture Premix Manufacturing Scale-Up | Specialized marine formulations for Nigerian catfish and Egyptian tilapia capture premium pricing in underpenetrated markets. |
Methodological Framework
A spread of perspectives from feed compounder procurement directors, veterinary nutrition consultants, regulatory affairs leads at animal health companies, and precision fermentation R&D heads converged on the working assumptions. Secondary validation drew from FDA Veterinary Feed Directive guidance documents, EFSA additive safety assessments under EU Regulation 1831/2003, China's Ministry of Agriculture feed additive catalogs, and customs trade data for amino acid imports. Bottom-up volume modeling across livestock species and top-down value reconciliation against premix manufacturing capacity established triangulation boundaries.
Product type, active ingredient class, livestock application, and formulation format segmented the analytical framework across the analysis window. Growth trajectories were derived from elasticity modeling of regulatory restriction intensity against adoption curves for non-antibiotic alternatives. Species-specific feed conversion efficiency improvements and phase-feeding program penetration in integrated pork systems informed projection inputs.
The analysis sits within stated boundaries; outcomes outside sustained EFSA and FDA regulatory pressure, or reversal of antibiotic restriction trends in European and North American markets, would require recalibration. Forecasts reflect documented assumptions regarding precision fermentation cost reduction curves and cold-chain infrastructure expansion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
China Animal Milk Replacer Market