
 Feed Anticoccidials Market | 2026-2036
Feed Anticoccidials Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Anticoccidials Market Analysis
Buyer concentration among large-scale poultry integrators is decoupling from traditional distributor networks across key production belts. Zoetis Inc. leverages its veterinary channel depth to sustain direct relationships with vertically aligned farm groups. Huvepharma anchors European supply through specialized ionophore manufacturing scale. Phibro Animal Health Corporation competes on regulatory dossier breadth across multiple national jurisdictions.
Feed anticoccidials are prophylactic agents administered in poultry and livestock rations to prevent coccidiosis, a protozoal intestinal disease; ionophores such as monensin and salinomycin function by disrupting sodium and potassium ion transport across parasite cell membranes, while synthetic chemicals like nicarbazin target specific life-cycle stages of Eimeria species. The product-type split shows ionophores occupying the largest volume share due to decades of proven efficacy and residual growth-promotion benefits in some jurisdictions, yet natural products and vaccines are gaining structural traction where regulatory pressure on chemical residues intensifies. Poultry farms dominate end-user demand, though pig production represents a differentiated margin pool with fewer approved active ingredients and higher technical barriers to entry.
FDA's Veterinary Feed Directive and EMA's guidelines on antimicrobial alternatives jointly shape product registration requirements and prescribing protocols across North America and Europe. REACH compliance and residue monitoring programs administered by EFSA constrain synthetic chemical formulations while creating market access advantages for dossier-heavy suppliers. Stakeholders must weigh regulatory trajectory against biological efficacy when allocating R&D across ionophore, synthetic, and vaccine platforms.
Market Dynamics
Poultry integrators in Brazil are consolidating procurement decisions, shifting volume toward suppliers with complete regulatory dossiers and forcing smaller compounders to exit or merge. This buyer concentration is restructuring supplier relationships across major production belts.
Growth Catalysts
- FDA Veterinary Feed Directive:The directive mandates veterinary oversight for medicated feeds, creating compliance-driven demand for pre-approved anticoccidial formulations and favoring dossier-complete suppliers.
- Southeast Asia contract farming zones:Industrial poultry operations in Vietnam, Thailand, and Indonesia are expanding feed-medicated disease prevention programs as biosecurity standards tighten.
- Ionophore efficacy legacy:Decades of proven coccidiosis control and residual growth-promotion benefits in permitted jurisdictions sustain replacement demand among established farm operations.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates synthesis of salinomycin and monensin intermediates, exposing formulators to supply disruption risks from single-source dependencies.
- REACH compliance burden:ECHA registration requirements for synthetic anticoccidials impose multi-year timelines and substantial testing costs that freeze out mid-scale entrants.
- Vaccine substitution pressure:Live coccidiosis vaccines are displacing chemical prophylaxis in premium poultry segments where residue-free certification commands price premiums.
Strategic Opportunities
- Natural product regulatory tailwinds:EFSA's positive opinions on certain botanical extracts are opening novel feed additive categories that sidestep chemical residue monitoring.
- Pig production technical barriers:Fewer approved actives for swine coccidiosis create margin pools for suppliers with species-specific formulation expertise and regulatory data packages.
- Direct-to-integrator channels:Large Brazilian and US poultry groups are bypassing traditional distributors, creating openings for manufacturers with technical service capabilities and inventory financing.
Industry Challenges
- Regulatory dossier compilation timelines:EMA and FDA residue depletion studies require 18-36 months, compressing product development windows against patent cliffs.
- Multi-jurisdiction label harmonization:Divergent withdrawal period requirements across Brazil, the US, and EU markets fragment production runs and complicate inventory planning.
- Legacy ionophore resistance management:Eimeria strain rotation protocols demand continuous field surveillance investment that strains technical service budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Anticoccidials Market |
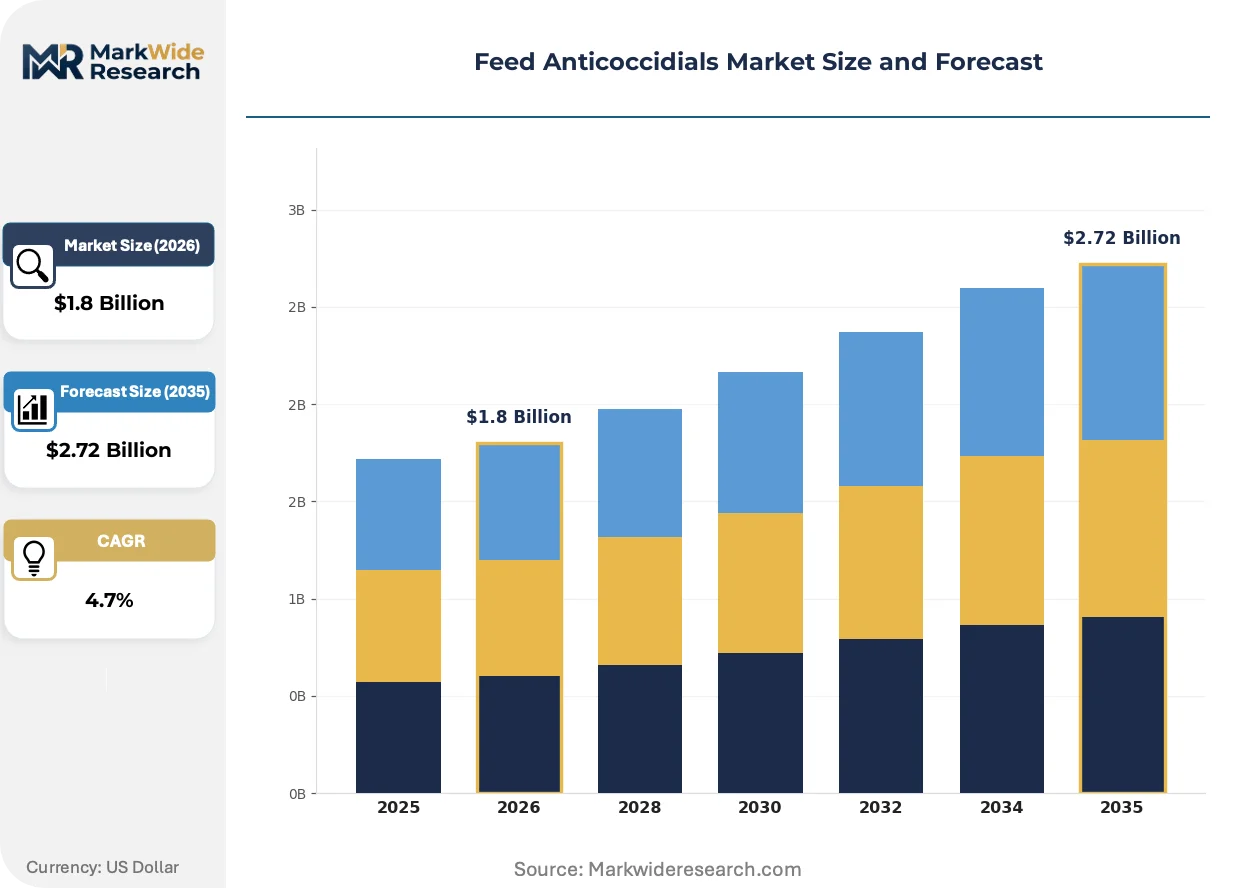
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionophores, Synthetic Chemicals, Vaccines, Natural Products Form: Granules, Powders, Liquids, Pellets End User: Poultry Farms, Pig Production, Dairy Farms, Veterinary Clinics Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Huvepharma, Ceva Animal Health, Zoetis Inc., Kemin Industries, BASF SE, Elanco Animal Health Incorporated, Phibro Animal Health Corporation, Adisseo France SAS, Merck Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Anticoccidials Market Emerging Trajectories
Anticoccidial development is pivoting from pure chemical efficacy toward integrated health management platforms that combine prophylaxis, diagnostics, and production data analytics. This convergence is redrawing competitive boundaries between pharmaceutical and technology suppliers.
Precision delivery systems for ionophores are integrating micro-encapsulation technologies that protect active molecules from feed processing heat and enable targeted release in the avian intestinal tract. Large Brazilian integrators are piloting these formulations to reduce dosage rates while maintaining efficacy. The technology is integrating feed manufacturing and veterinary medicine disciplines, compressing margins for conventional premix suppliers lacking formulation science capabilities.
EMA's guidelines on antimicrobial alternatives are tightening residue monitoring thresholds for synthetic chemicals across member states, forcing reformulation of legacy nicarbazin-based products. Poultry exporters to EU markets face enhanced border inspection frequencies for coccidiostat violations. Suppliers with early investment in metabolite characterization studies are securing provisional approvals ahead of competitors still compiling depletion data.
Contract poultry growers in Vietnam and Thailand are consolidating feed purchasing through integrator-managed programs, displacing independent distributor networks that previously supplied smallholder operations. Large processing groups are specifying approved anticoccidial suppliers in grower contracts, concentrating volume among three to four approved vendors per region. This pattern is most visible in the Mekong Delta and Central Plains production clusters where vertical coordination has advanced furthest.
Feed Anticoccidials Market Segmentation
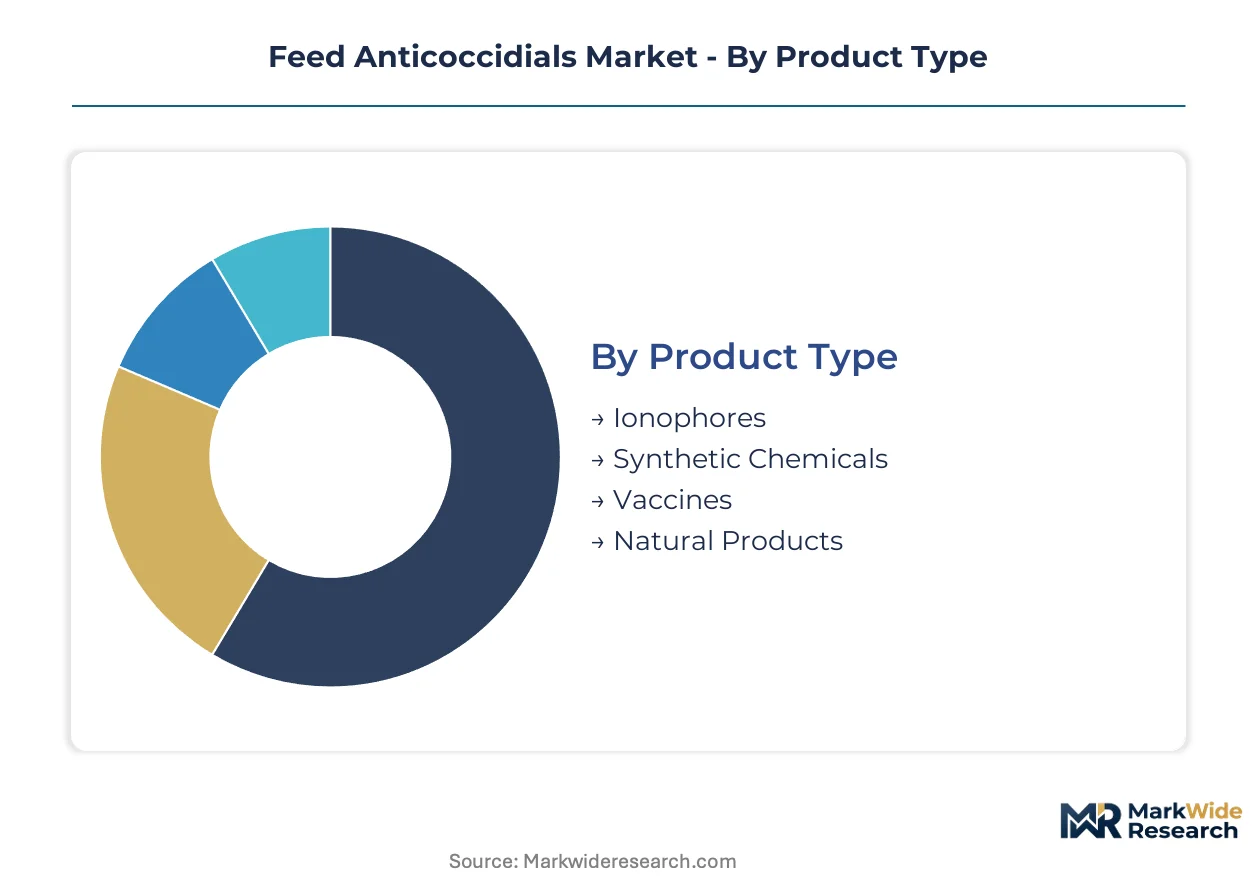
Feed anticoccidials fragment across four structural dimensions that determine formulation requirements, regulatory pathways, and margin capture. Each category reflects distinct upgrade cycles—from ionophore resistance rotation schedules to precision delivery system adoptions—that reshape supplier positioning.
Product Type:
Upgrade cycles vary sharply across product classes, with ionophore resistance management forcing rotation protocols every 18-24 months in intensive poultry operations.
- Ionophores:Polyether antibiotics including monensin, salinomycin, and lasalocid disrupt Eimeria cell membrane ion transport. Broiler integrators in Brazil and Thailand anchor procurement volumes here, though resistance strain surveillance consumes rising technical service budgets.
- Synthetic Chemicals:Nicarbazin, diclazuril, and toltrazuril target specific protozoal life-cycle stages with precise withdrawal period requirements. EMA residue threshold tightening is compressing approved supplier lists to dossier-complete manufacturers with metabolite characterization data.
- Vaccines:Live attenuated Eimeria strains administered in ovo or at hatch. Premium poultry segments in EU markets and organic-certified operations drive adoption where chemical residue-free certification commands price premiums.
- Natural Products:Botanical extracts and essential oil formulations gaining EFSA positive opinions for novel feed additive categories. Southeast Asian contract farming zones pilot these as rotation alternatives to synthetic chemicals.
Volume placements concentrate in Ionophores; the faster expansion belongs to Natural Products.
Form:
Cost tier differentiation separates commodity premix suppliers from formulation science specialists commanding premium positioning.
- Granules:Heat-stable extruded particles protecting actives through pelleting temperatures above 85°C. Brazilian integrators specify micro-encapsulated granule grades for precision release in the avian intestinal tract, reducing dosage rates 8-12%.
- Powders:Standard premix carriers blending into mash feeds with lower capital equipment requirements. Smallholder operations and independent compounders in Vietnam and Indonesia dominate procurement.
- Liquids:Post-pelleting spray applications preserving thermolabile actives. Large US and EU feed mills deploy these for nicarbazin-based formulations where heat degradation risks exceed tolerance thresholds.
- Pellets:Pre-formed medicated feed units for backyard and small-scale operations with limited on-farm mixing infrastructure. Veterinary clinics and retail channels stock these for direct producer sales.
Procurement patterns favor Granules in commercial-scale operations; Liquids gain share fastest in premium export-oriented production.
End User:
Application intensity and regulatory burden vary dramatically across species, with poultry commanding the deepest supplier relationships and swine presenting technical barrier moats.
- Poultry Farms:Broiler, layer, and breeder operations consuming 75-80% of global anticoccidial volumes. Contract farming consolidation in Thailand and Vietnam concentrates purchasing through integrator-managed programs specifying approved supplier lists.
- Pig Production:Fewer approved actives for swine coccidiosis create differentiated margin pools. Suppliers with species-specific formulation expertise and regulatory data packages capture premium positioning in EU and US sow operations.
- Dairy Farms:Coccidiosis prophylaxis in pre-weaned calves represents a niche volume segment with extended withdrawal period requirements constraining product selection.
- Veterinary Clinics:Small-scale and backyard poultry producers source individual treatment courses and diagnostic services, with FDA Veterinary Feed Directive compliance requirements reshaping prescribing protocols.
Revenue concentration sits with Poultry Farms; Pig Production offers the steepest expansion trajectory for specialized suppliers.
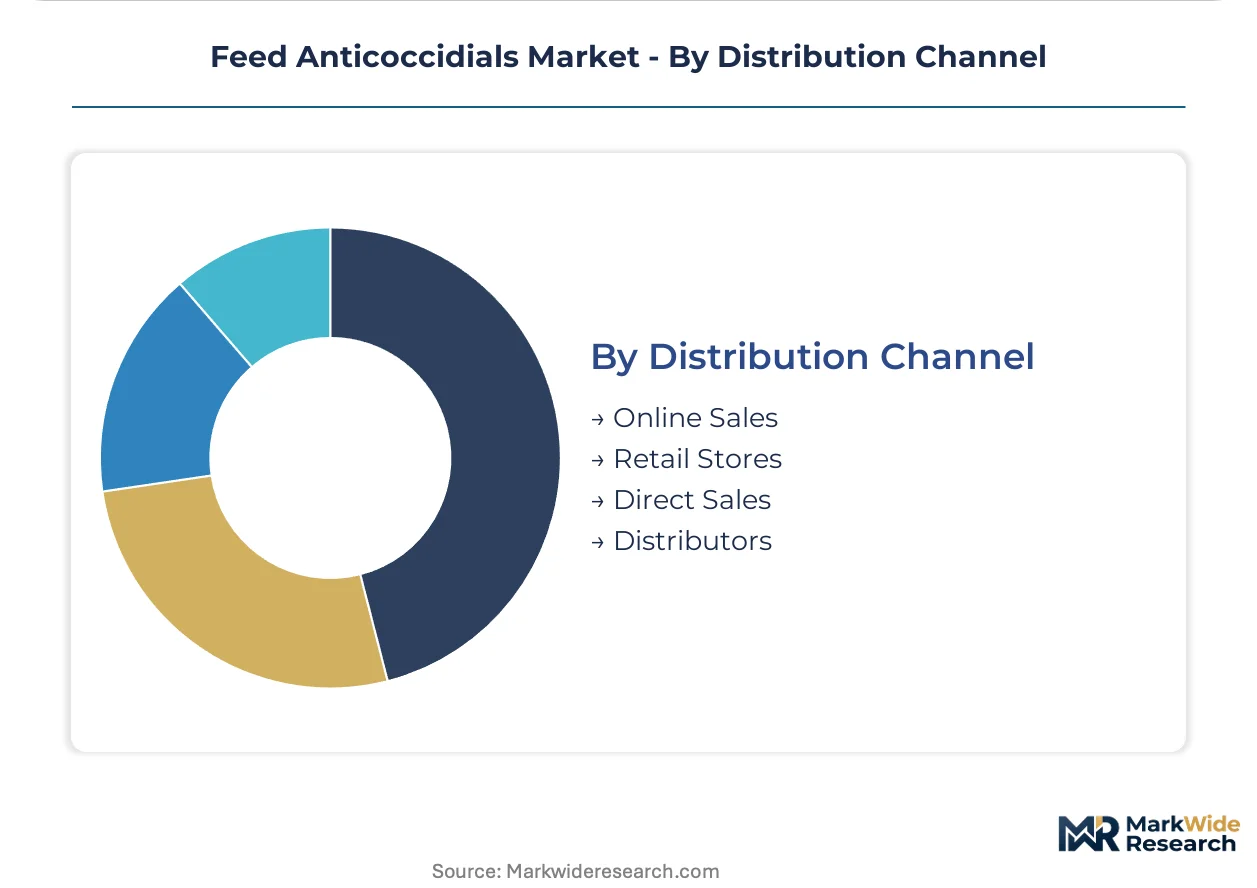
Distribution Channel:
Customer type fragmentation—integrators versus independent producers—determines channel strategy and working capital requirements.
- Direct Sales:Manufacturers with technical service teams and inventory financing capabilities bypass traditional distributors to serve large Brazilian and US poultry integrators. This channel commands 35-40% of value despite lower volume share.
- Distributors:Regional compounders and feed additive specialists aggregate smallholder demand across Southeast Asia and Latin America. Buyer consolidation is compressing margins and forcing distributor mergers.
- Online Sales:E-commerce platforms serving backyard poultry keepers and small veterinary practices with smaller pack sizes. Regulatory compliance complexity limits growth in prescription-required jurisdictions.
- Retail Stores:Agricultural supply cooperatives and farm stores stocking over-the-counter products for non-medicated feed categories and natural product alternatives.
Volume flow concentrates through Distributors; Direct Sales captures value fastest as integrator consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese chemical synthesis clusters supply the bulk of salinomycin and monensin intermediates that feed formulators worldwide. This upstream concentration shapes downstream market dynamics across consuming regions.
United States
Large broiler integrators in Georgia, Arkansas, and Alabama consolidate procurement through direct manufacturer relationships. FDA's Veterinary Feed Directive mandates veterinary oversight for all medicated feeds, favoring suppliers with complete regulatory dossiers. The Delmarva Peninsula poultry corridor drives concentrated demand for ionophore premixes.
Brazil
Vertical integration across São Paulo and Paraná production belts shifts volume toward dossier-complete suppliers. ANVISA registration requirements for feed additives create compliance barriers that smaller compounders cannot surmount. The western Paraná cluster around Toledo anchors national procurement decisions for major integrators.
Germany
EMA guidelines on antimicrobial alternatives tighten residue thresholds for synthetic chemicals entering EU markets. REACH compliance costs freeze out mid-scale entrants from nicarbazin formulation. Lower Saxony's intensive livestock zone concentrates demand for EFSA-approved natural product alternatives.
Thailand
Contract farming expansion across the Central Plains concentrates feed purchasing through integrator-managed programs. Biosecurity standard tightening drives medicated feed adoption among industrial operations. The Chachoengsao-Saraburi corridor specifies approved anticoccidial suppliers in grower contracts.
Vietnam
Mekong Delta poultry operations consolidate previously fragmented smallholder demand through processing group contracts. The national veterinary regulator enforces feed additive registration that favors established international suppliers. Dong Thap and Long An provinces pilot botanical extract rotations as synthetic chemical alternatives.
Feed Anticoccidials Market Vendor Landscape
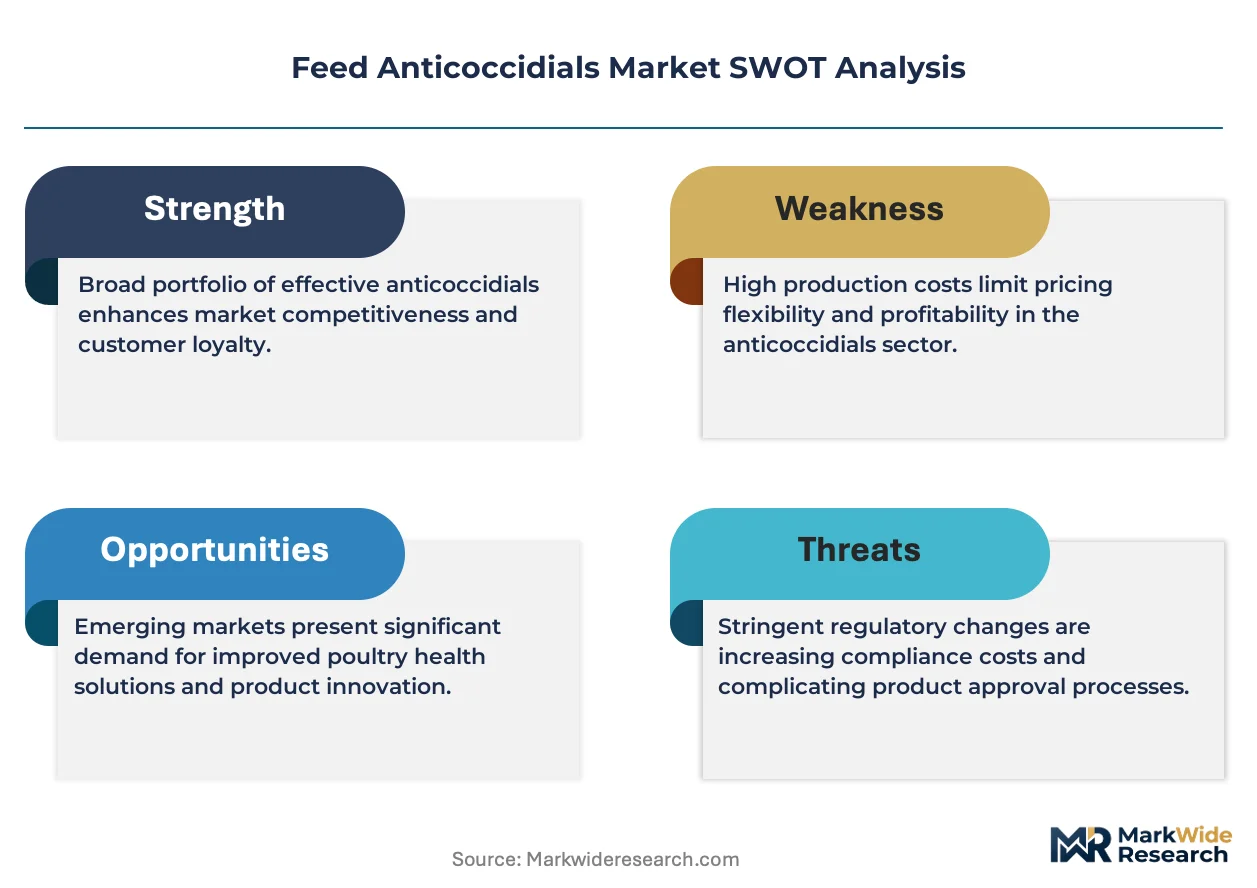
Established producers occupy the standard tier; emerging entrants pursue natural product and precision delivery niches. The supplier base consolidates around three to four approved vendors per major production region as integrator procurement centralizes. Three archetypes dominate: ionophore specialists with fermentation scale, synthetic chemical dossier compilers, and integrated health platform providers. Capacity expansion and direct-to-integrator channel development constitute the primary competitive vectors.
Among the dossier-heavy pharmaceutical tier, Huvepharma anchors European supply through specialized manufacturing infrastructure. Zoetis Inc. occupies a position leveraging veterinary channel depth for direct integrator relationships. Phibro Animal Health Corporation exemplifies the multi-jurisdiction regulatory compiler archetype. These three represent distinct competitive positioning vectors rather than interchangeable market participants.
| Leading Market Players |
|---|
| Huvepharma |
| Ceva Animal Health |
| Zoetis Inc. |
| Kemin Industries |
| BASF SE |
| Elanco Animal Health Incorporated |
| Phibro Animal Health Corporation |
| Adisseo France SAS |
| Merck Animal Health |
| Others |
Supply Flow & Price Mechanics
Monensin and salinomycin intermediate prices from Chinese chemical synthesis clusters cascade through formulation tiers, compressing margins for premix compounders lacking captive fermentation capacity while enabling dossier-complete suppliers to command technical-service premiums in direct integrator negotiations.
Pricing Analysis
Technical service bundling separates premium positioning from commodity premix tiers, with residue depletion study support and inventory financing included in direct sales contracts to Brazilian and US integrators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard premix tiers intensifies as distributor consolidation squeezes compounder margins. Independent smallholders in Southeast Asia exhibit highest price sensitivity; large integrators with approved supplier lists prioritize regulatory security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by ANVISA-registered Brazilian integrators and FDA-compliant US poultry groups force qualification of backup fermentation suppliers beyond dominant Chinese intermediate producers. Active pharmaceutical ingredient synthesis concentrates in China, with formulation and premix processing anchored in Brazil, Germany, and Thailand. Raw material dependencies span salinomycin fermentation broths, specialized ionophore extraction solvents, and EFSA-compliant natural extract carriers. Single-source vulnerability from geographic concentration of polyether antibiotic fermentation exposes formulators to supply disruption. Distribution runs through integrator-managed procurement programs displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed anticoccidials is becoming a vertical-integration race, with backward integration into fermentation capacity and forward control over direct-to-integrator channels as the decisive levers separating sustainable margin capture from commodity premix erosion.
For Market Incumbents: Anticipate vaccine substitution pressure in EU premium segments by accelerating precision delivery system investments and metabolite characterization data packages that secure provisional EMA approvals ahead of residue threshold tightening. Deepen captive ionophore fermentation capacity in Brazil and Thailand to defend against supply disruption risks from Chinese intermediate concentration. Channel control through technical service teams and inventory financing locks in integrator relationships that resist price-based displacement.
For New Entrants and Emerging Players: Enter via natural product regulatory tailwinds in Vietnam and Thailand, where EFSA-positive botanical extracts face lower technical barriers than synthetic chemical dossier compilation. Pig production applications in EU sow operations present the most penetrable margin pool given fewer approved actives and species-specific formulation requirements. A go-to-market angle anchored in direct technical service partnerships with mid-scale integrators bypasses distributor consolidation squeeze.
For Investors and Strategic Acquirers: Distressed-cycle entries favor dossier-heavy synthetic chemical specialists in Germany and Brazil facing REACH compliance cost pressures but holding irreplaceable regulatory data packages. Long-term viability across the analysis window hinges on positioning for post-chemical residue monitoring regimes where precision delivery and natural product platforms displace legacy formulations. Watch Eimeria strain rotation protocol adoption rates as the inflection signal for technical service budget allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive salinomycin and monensin capacity insulates Brazilian formulators from Chinese intermediate volatility. |
| Precision Delivery System Development | Micro-encapsulated granule formulations reduce dosage rates 8-12% while maintaining efficacy in avian intestinal tracts. |
| Direct-to-Integrator Channel Expansion | Technical service teams with inventory financing bypass distributor consolidation in São Paulo and Paraná production belts. |
| Natural Product Regulatory Dossier Investment | EFSA-positive botanical extract approvals open novel feed additive categories sidestepping chemical residue monitoring. |
| Multi-Jurisdiction Label Harmonization | Coordinated FDA, EMA, and ANVISA residue depletion studies compress development timelines against patent cliffs. |
Methodological Framework
Document review covered FDA Veterinary Feed Directive implementation records, EMA guideline publications on antimicrobial alternatives, ANVISA feed additive registration databases, and EFSA novel feed additive opinions, complemented by interviews with poultry integrator procurement directors, feed mill technical managers, regulatory affairs specialists at dossier-heavy suppliers, and veterinary channel distribution executives. Secondary validation drew from customs trade data on salinomycin and monensin intermediate flows, SEC 10-K filings of publicly listed animal health companies, and ECHA REACH registration timelines. Bottom-up volume estimates from country-level poultry production statistics and top-down value triangulation from supplier revenue disclosures were reconciled across analytical approaches.
Segment-level projections across ionophore, synthetic chemical, vaccine, and natural product categories were generated through regression frameworks incorporating regulatory approval velocity, resistance rotation protocol adoption, and integrator consolidation rates over the projection horizon. Modeled dimensions spanned product type, formulation grade tier, end-use species intensity, and distribution channel structure. CAGRs were derived from logistic diffusion curves fitted to historical penetration data and elasticity-adjusted for withdrawal period harmonization progress. Industry-specific forecast inputs included Eimeria strain surveillance investment cycles and precision delivery system pilot adoption thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH residue threshold revisions or Chinese intermediate export restriction scenarios. Projections reflect assumptions regarding regulatory dossier compilation timelines and integrator procurement centralization velocity. Deviation in ANVISA or FDA feed additive registration pathways would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Cattle Nutrition Market