
 Anhydrous Milk Fat (Butter Oil) Market | 2026-2036
Anhydrous Milk Fat (Butter Oil) Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrous Milk Fat (Butter Oil) Market Intelligence
Fractionation-as-a-service and customized fat-blend subscriptions is restructuring how dairy processors monetize anhydrous milk fat, shifting revenue from commodity volume to tailored lipid solutions. Fonterra Co-operative Group Limited leverages its New Zealand-origin supply base to anchor premium butter oil positioning across Asian bakery chains. Lactalis Group sustains manufacturing scale through integrated cream-to-butter oil streams in Europe and South America. Arla Foods differentiates via cooperative-owned traceability systems that compete on clean-label credentials in Northern European retail channels.
Anhydrous milk fat, commonly termed butter oil, consists of milk fat concentrated to at least 99.8% purity through melting, centrifugation, and vacuum drying of butter or cream, yielding a shelf-stable lipid with minimal moisture and protein content. Industrial buyers deploy it as a functional fat source in chocolate tempering, laminated dough production, and recombined dairy formulations where precise melting profiles and oxidative stability matter. The natural product type occupies the dominant share as clean-label bakery and confectionery brands reject hydrogenated alternatives, though organic grades command disproportionate margin pools amid supply scarcity. Application-wise, bakery consumes the largest volume while confectionery represents the fastest-expanding segment as Asian chocolatiers adopt butter oil for snap and gloss control in tropical climates.
The European Food Safety Authority enforces contaminant thresholds for milk fat used in infant nutrition and confectionery, while the FDA governs GRAS status and labeling standards for butter oil sold into U.S. food manufacturing, collectively elevating analytical and documentation burdens for exporters. Codex Alimentarius standards on milk fat identity further shape cross-border trade flows, particularly for recombined dairy operations in the Middle East and Africa. Stakeholders must monitor evolving methane-reduction commitments under the EU Green Deal and emerging carbon-border adjustments that could restructure competitive sourcing between Oceanian and European suppliers.
Market Dynamics
Fractionation-as-a-service is restructuring how dairy processors monetize anhydrous milk fat, shifting revenue from commodity volume sales toward tailored lipid solutions with recurring subscription structures.
Growth Catalysts
- Southeast Asian Bakery Expansion:Indonesia and Vietnam drive volume adoption as expanding middle-class diets shift toward premium laminated doughs and artisanal baked goods requiring precise melting profiles.
- EU F-Gas Regulation:European dairy sustainability mandates push processors toward lower-emission fractionation technologies, accelerating capital deployment into membrane-based separation systems.
- Clean-Label Rejection of Hydrogenates:Natural anhydrous milk fat grades capture displaced demand from partially hydrogenated oils as confectionery brands reformulate for tropical climate stability without trans fats.
Market Restraints
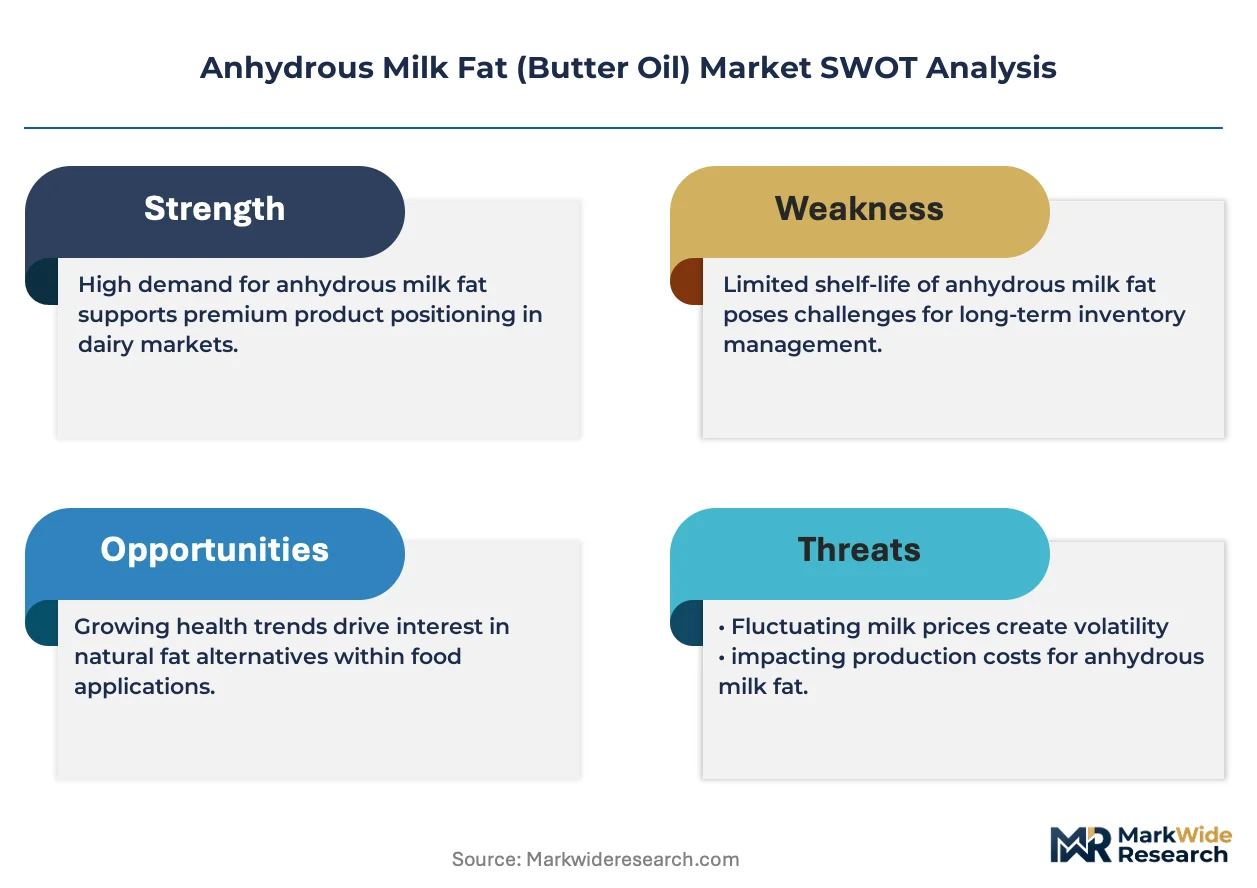
- Butter Price Volatility:Cream input costs fluctuate with seasonal milk production cycles and feed grain prices, compressing processor margins during supply troughs.
- Oceanian Supply Concentration:New Zealand and Australia-origin butter oil dominates premium export tiers, creating geographic vulnerability to drought-induced production shortfalls.
- Plant-Based Fat Substitution:Cocoa butter equivalents and shea-based alternatives threaten confectionery applications where cost sensitivity outweighs functional performance requirements.
Strategic Opportunities
- Philippines and Myanmar Penetration:Underdeveloped cold-chain infrastructure in these markets currently limits butter oil distribution, creating first-mover advantage for shelf-stable fractionated products.
- Infant Nutrition Grade Certification:EFSA contaminant thresholds for milk fat in early-life nutrition create premium tier pricing for processors achieving analytical documentation compliance.
- Carbon-Border Adjustment Positioning:EU Green Deal methane-reduction commitments favor Oceanian suppliers with verified lower-emission grazing systems against European competitors.
Industry Challenges
- Fractionation Specialist Talent Scarcity:Deep expertise in lipid crystallization kinetics and polymorphism control remains concentrated among retiring European technical staff.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA GRAS documentation, Codex Alimentarius alignment, and national dairy identity standards extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrous Milk Fat (Butter Oil) Market |
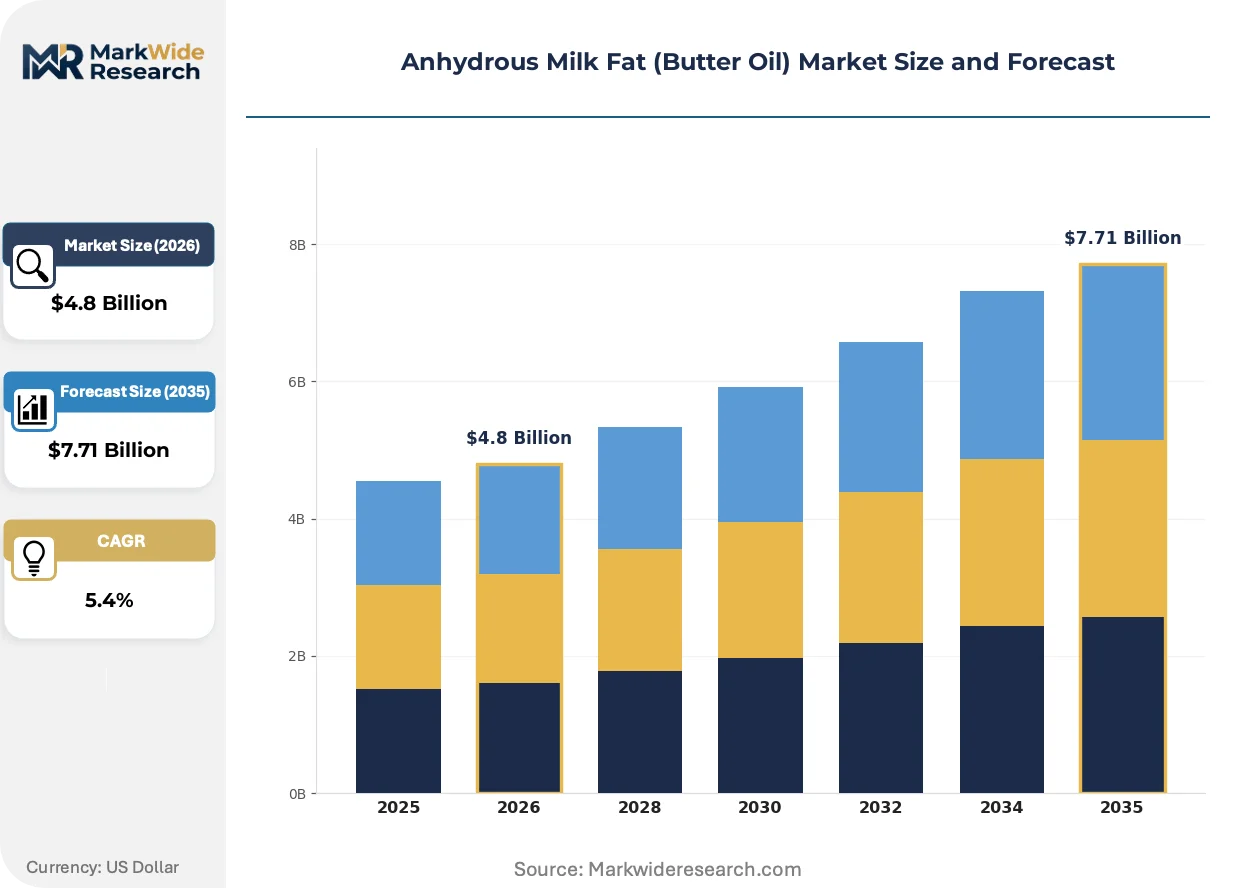
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Organic, Conventional, Flavored Application: Bakery, Confectionery, Dairy Products, Spreads End User: Food Industry, Catering Services, Retailers, Manufacturers Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Lactalis Group, Saputo Inc., Fonterra Co-operative Group Limited, Glanbia PLC, Yili Industrial Group Co., Ltd., FrieslandCampina N.V., Arla Foods, Synlait Milk Limited, Dairy Farmers of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrous Milk Fat (Butter Oil) Market Strategic Shifts & Innovations
Membrane filtration and enzymatic interesterification are actively displacing conventional solvent-based fractionation, enabling processors to achieve precise melting-point tailoring while eliminating hexane residue concerns.
Supercritical carbon dioxide extraction is overtaking traditional crystallization methods for high-value milk fat fractions, particularly among Asian chocolatiers seeking snap and gloss control without tropical bloom defects. Industrial bakeries in Indonesia and Vietnam adopt these premium grades at accelerating pace as laminated dough production scales. This technology is compressing the competitive window for commodity butter oil suppliers unable to achieve equivalent functional specificity.
REACH chemical safety registration and the EU F-Gas phase-down are forcing reformulation of cooling systems used in fractionation plants across Northern Europe. Industrial consequence includes accelerated capital replacement cycles and retrofitting of existing crystallization infrastructure. German and Dutch dairy processors most affected are consolidating production into fewer, larger facilities with integrated carbon-capture systems.
Bakery chains are consolidating supplier relationships from transactional spot purchasing toward multi-year fat-blend subscription contracts with guaranteed volume and specification consistency. This procurement evolution displaces traditional commodity brokers and concentrates buying power with integrated processors capable of custom fractionation. The shift is most visible across Southeast Asian quick-service bakery networks where central kitchens demand supply security for standardized product output.
Anhydrous Milk Fat (Butter Oil) Market Segmentation
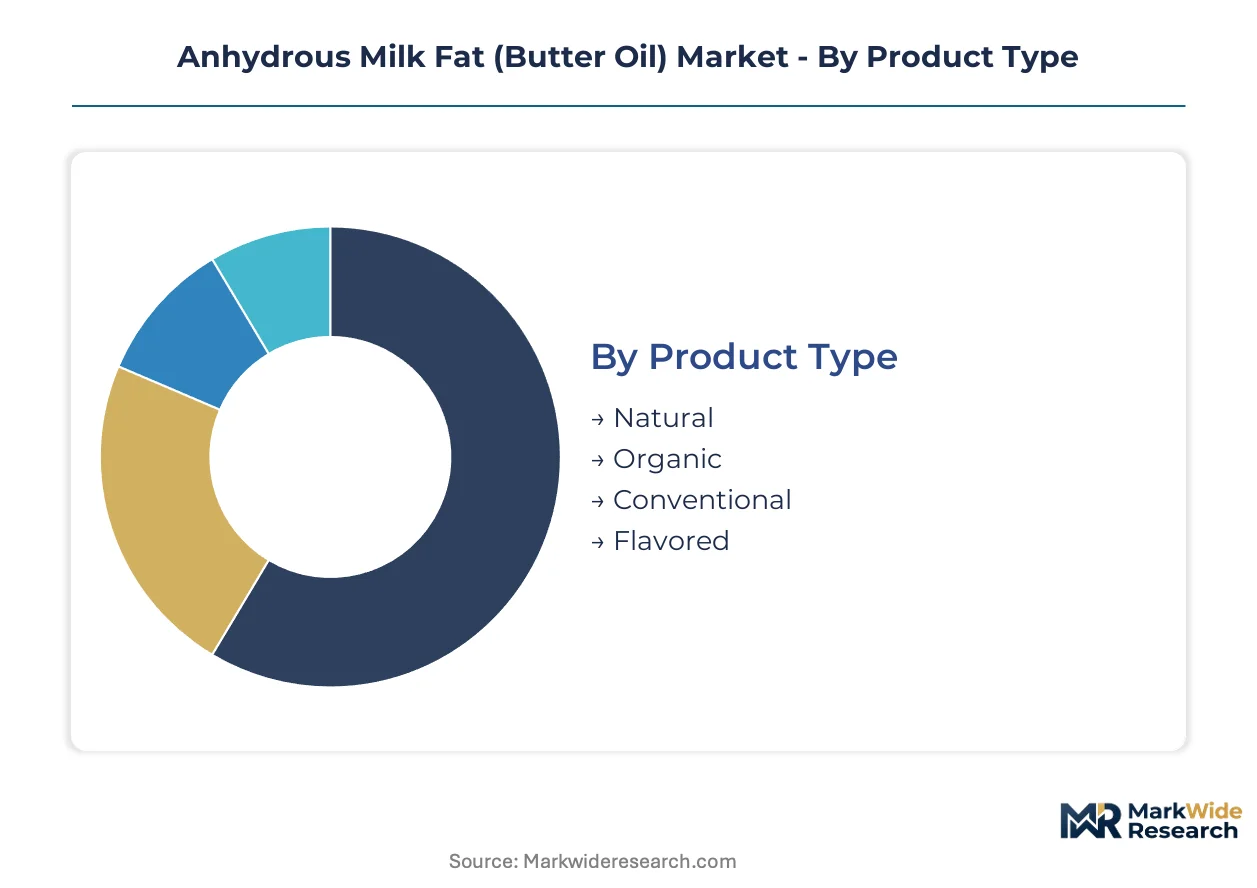
Anhydrous milk fat segmentation reflects divergent certification burdens across product grades and end-use specifications. FDA GRAS documentation, EFSA contaminant thresholds, and Codex Alimentarius identity standards each apply selectively to segments, shaping competitive barriers and margin structures.
Product Type:
Certification intensity varies sharply across grades, with infant nutrition and organic tiers demanding exhaustive analytical documentation while conventional grades face lighter regulatory scrutiny.
- Natural:Milk fat concentrated to minimum 99.8% purity through physical separation methods without chemical modification. Southeast Asian bakery chains in Indonesia and Vietnam absorb the largest volumes as laminated dough production scales, driven by clean-label rejection of hydrogenated alternatives and tropical climate stability requirements.
- Organic:Derived from certified organic milk supply chains with full pasture-access documentation and prohibited synthetic input verification. Supply scarcity concentrates pricing power among cooperative-owned processors in New Zealand and Northern Europe, where verified lower-emission grazing systems align with EU Green Deal procurement preferences.
- Conventional:Standard-grade butter oil produced through conventional dairy farming systems without organic certification requirements.
- Flavored:Butter oil infused with natural or artificial flavoring agents for specialty food manufacturing applications.
Natural sits at the top of the volume ranking, with Organic climbing the fastest.
Application:
End-use specifications dictate functional performance requirements, with chocolate tempering and infant nutrition imposing the strictest lipid polymorphism and contaminant thresholds.
- Bakery:Dominant volume segment serving laminated dough production, croissant manufacturing, and industrial bread formulations. Indonesian and Vietnamese quick-service bakery networks consolidate procurement toward multi-year fat-blend subscription contracts as central kitchens demand supply security.
- Confectionery:Fastest-expanding application as Asian chocolatiers adopt supercritical carbon dioxide extracted fractions for snap and gloss control without tropical bloom defects. Supercritical extraction technology compresses the competitive window for commodity suppliers unable to achieve equivalent functional specificity.
- Dairy Products:Recombined milk and cheese processing applications requiring precise fat standardization.
- Spreads:Table-grade butter oil blends for direct consumer packaging and foodservice portion control.
Bakery generates the largest revenue pool, though Confectionery gains share fastest on premium fractionation adoption.
End User:
Procurement sophistication stratifies sharply, with multinational food manufacturers maintaining dedicated lipid laboratories while catering services rely on distributor specifications.
- Food Industry:Integrated processors and branded food manufacturers with in-house fractionation capabilities and direct New Zealand-origin supply contracts.
- Catering Services:Foodservice operators purchasing through wholesale distributors with limited technical specification negotiation leverage.
- Retailers:Private-label and branded butter oil packagers for consumer shelf-stable fat segments.
- Manufacturers:Industrial ingredient blenders and compound fat producers serving secondary food processing tiers.
Food Industry commands the deepest technical engagement, with Manufacturers expanding procurement most aggressively on recombined dairy growth.
Distribution Channel:
Cold-chain infrastructure maturity determines channel viability, with shelf-stable fractionated products unlocking penetration in underdeveloped logistics markets.
- Online:Emerging direct procurement platform for specialty organic grades and small-batch artisanal processors bypassing traditional broker networks.
- Offline:Established cash-and-carry and distributor relationships dominating conventional grade volume movement.
- Direct Sales:Long-term supply agreements between integrated processors and multinational bakery chains with guaranteed volume and specification consistency.
- Wholesalers:Regional distributors serving fragmented catering and small-manufacturer demand with consolidated multi-origin sourcing.
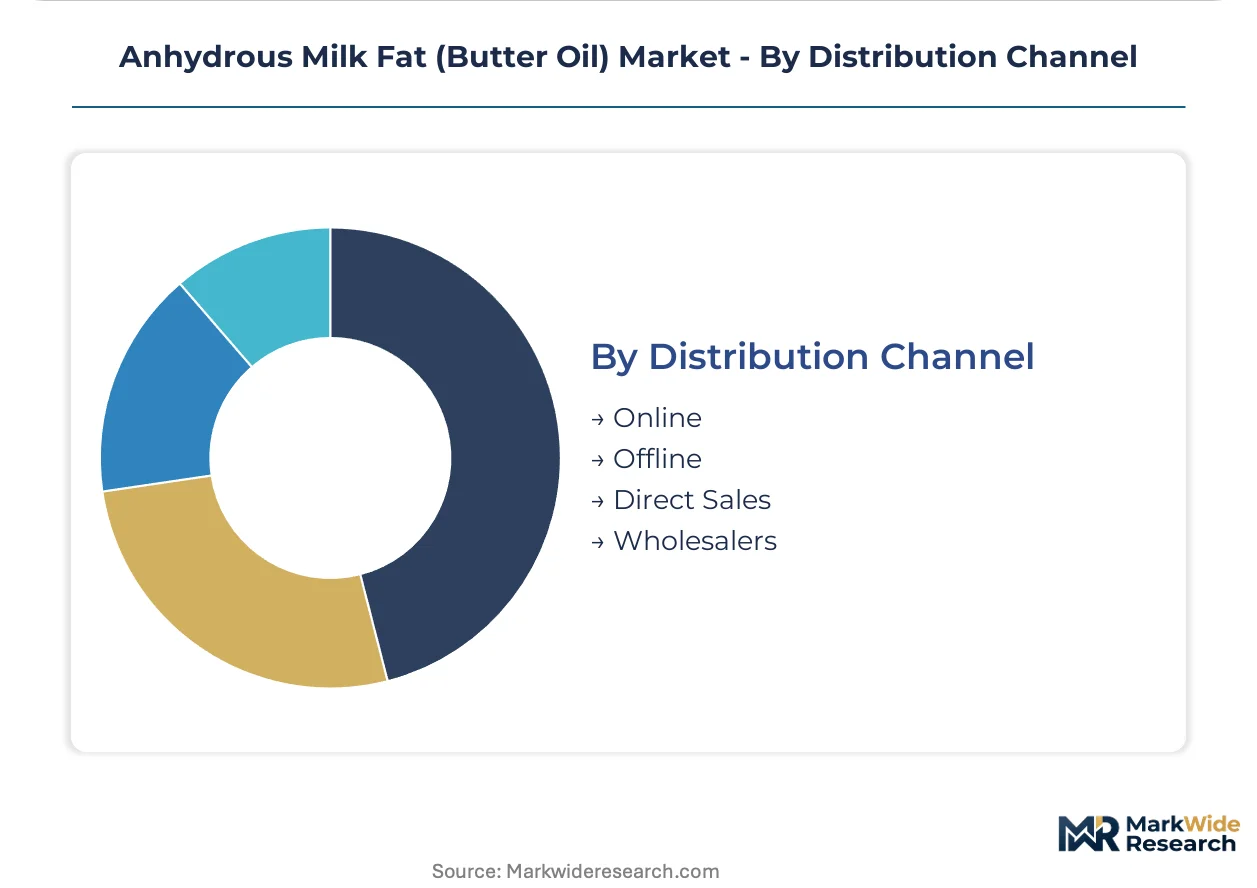
Direct Sales anchors the largest contract value, with Online expanding most quickly on organic grade discovery and procurement transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia absorbs more anhydrous milk fat volume than Vietnam, yet both Southeast Asian markets exhibit divergent regulatory pressures and cold-chain maturity that reshape procurement patterns for butter oil suppliers.
Indonesia
Quick-service bakery networks in Jakarta and Surabaya consolidate procurement through multi-year fat-blend subscription contracts as laminated dough production scales. The country's national food and drug regulator enforces halal certification requirements that extend to milk fat imports, adding documentation layers for exporters. West Java industrial zones host the largest concentration of central kitchen facilities demanding supply security for standardized croissant and pastry output.
Vietnam
Expanding middle-class diets in Ho Chi Minh City and Hanoi shift toward premium baked goods requiring precise melting profiles that natural butter oil grades deliver. The Ministry of Health implements food safety standards aligned with Codex Alimentarius, elevating analytical burdens for recombined dairy operations. Da Nang emerging as a secondary distribution hub where shelf-stable fractionated products penetrate underdeveloped cold-chain infrastructure.
New Zealand
Cooperative-owned processors leverage verified lower-emission grazing systems to align with EU Green Deal procurement preferences across Asian export markets. The country's environmental regulator monitors methane-reduction commitments that favor Oceanian suppliers in carbon-border adjustment scenarios. Canterbury dairy processing clusters concentrate fractionation capacity serving premium bakery and confectionery tiers in Southeast Asia.
Germany
REACH chemical safety registration and the EU F-Gas phase-down force reformulation of cooling systems in Northern European fractionation plants. The Federal Environment Agency accelerates capital replacement cycles through emissions mandates that consolidate production into fewer, larger facilities. Bavarian dairy processors retrofit crystallization infrastructure with integrated carbon-capture systems to maintain confectionery-grade output.
United States
Industrial food manufacturers maintain dedicated lipid laboratories for chocolate tempering applications where FDA GRAS documentation governs butter oil incorporation. The Food and Drug Administration enforces labeling standards that extend product launch cycles for exporters seeking dual jurisdiction compliance. Wisconsin and California dairy processing belts anchor domestic fractionation capacity serving recombined dairy growth in Latin American markets.
Anhydrous Milk Fat (Butter Oil) Market Key Industry Players
Top-tier vendors anchor premium-origin supply contracts, while mid-scale processors compete on custom fractionation capabilities and regional distribution density. The vendor base stratifies across integrated dairy cooperatives with captive cream streams, independent fractionation specialists, and multinational ingredient blenders. Two strategic archetypes dominate: Oceanian-origin suppliers leveraging verified low-emission grazing credentials, and European processors deploying membrane-based separation technologies. Competitive moves concentrate on backward integration into cream supply and technology licensing for supercritical carbon dioxide extraction systems.
Within the cooperative-owned tier, Fonterra Co-operative Group Limited and Arla Foods exemplify archetypes competing on traceability systems and clean-label credentials. FrieslandCampina N.V. occupies a position among European processors navigating REACH and F-Gas regulatory pressures. These entities represent divergent geographic origin strategies—Oceanian versus Continental European—each anchoring distinct premium positioning in Asian bakery and confectionery procurement channels.
| Leading Market Players |
|---|
| Lactalis Group |
| Saputo Inc. |
| Fonterra Co-operative Group Limited |
| Glanbia PLC |
| Yili Industrial Group Co., Ltd. |
| FrieslandCampina N.V. |
| Arla Foods |
| Synlait Milk Limited |
| Dairy Farmers of America Inc. |
| Others |
Cost & Logistics Intelligence
Cream input costs trace a volatile path from seasonal pasture conditions through New Zealand and European processing clusters into tiered butter oil pricing. New Zealand-origin supply scarcity compresses margins for commodity-grade processors while premium fractionation specialists capture spread expansion through supercritical extraction capabilities.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for conventional grades as REACH and EU F-Gas compliance costs accelerate consolidation into fewer production sites. Three-tier pricing structure across premium, standard, and economy levels separates infant nutrition-certified fractions from bakery-grade natural butter oil and commodity recombined dairy inputs. Pricing pressure stems from plant-based fat substitution in cost-sensitive confectionery applications where cocoa butter equivalents undercut functional performance claims. Foodservice catering operators exhibit highest price sensitivity against multinational bakery chains with locked subscription contracts.
Supply Chain Analysis
Fractionation specialist scarcity in Northern European technical labor pools constrains throughput expansion at existing facilities. Supply concentrates in New Zealand, Australia, and Germany, with raw material dependencies on seasonal milk production cycles, feed grain availability, and hexane solvent alternatives for crystallization processes. Single-source vulnerability runs through Oceanian drought exposure that disrupts premium export tiers without geographic diversification. Distribution runs through direct long-term agreements between integrated processors and multinational bakery chains, bypassing traditional commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anhydrous milk fat procurement functions as a geographic-arbitrage play where EU Green Deal methane-reduction commitments favor verified lower-emission Oceanian grazing systems against European competitors facing carbon-border adjustment exposure.
For Market Incumbents: Anchor premium positioning through backward integration into certified organic milk supply chains with full pasture-access documentation. Defend against membrane filtration technology displacement by licensing supercritical carbon dioxide extraction capabilities to Asian chocolatiers seeking tropical climate stability. Consolidate manufacturing scale through captive cream-to-butter oil streams that insulate margin compression from spot market volatility. For New Entrants and Emerging Players: Supercritical carbon dioxide extraction systems offer technology-first entry into premium confectionery fractions where commodity suppliers lack functional specificity. Penetrate Philippines and Myanmar distribution gaps through shelf-stable fractionated products that bypass underdeveloped cold-chain infrastructure. Target infant nutrition grade certification as the most penetrable premium tier where EFSA contaminant thresholds create analytical documentation barriers for incumbent processors. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation specialist talent scarcity concentrates technical capability among retiring European staff. Five-to-ten year viability favors processors with verified lower-emission grazing credentials aligned with EU procurement preferences. Acquire cooperative-owned traceability systems that compete on clean-label credentials. Watch carbon-border adjustment implementation timelines as inflection indicator for competitive sourcing shifts between Oceanian and European suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Milk Supply | Captures pasture-access documentation required for EU Green Deal procurement preferences. |
| Supercritical Extraction Technology Licensing | Enables Asian chocolatiers to achieve snap and gloss control without tropical bloom defects. |
| Infant Nutrition Grade Certification Investment | Unlocks premium tier pricing through EFSA contaminant threshold compliance documentation. |
| Carbon-Capture System Retrofitting | Satisfies German Federal Environment Agency mandates for confectionery-grade output continuity. |
| Multi-Year Fat-Blend Subscription Contracts | Secures volume commitments from Indonesian quick-service bakery central kitchens. |
Research Approach
Direct dialogue with dairy processing executives, fractionation technology specialists, bakery chain procurement directors, and regulatory affairs leads at cooperative-owned suppliers grounded qualitative assessment. Secondary validation drew from EFSA contaminant threshold documentation, FDA GRAS filings, Codex Alimentarius milk fat identity standards, and EU F-Gas Regulation implementation records. Bottom-up volume modeling across product grades and applications triangulated against top-down trade flow analysis from New Zealand and Australian export statistics.
Segment-level outputs across the analysis window reflect modeled interactions between natural, organic, and conventional grades against bakery, confectionery, and infant nutrition applications. CAGRs derived from elasticity-adjusted demand projections incorporating clean-label substitution rates and supercritical extraction adoption curves. Forecast inputs included seasonal milk production cycle patterns, feed grain price volatility indices, and carbon-border adjustment scenario weighting.
The model holds under stable EU Green Deal implementation timelines and sustained Southeast Asian bakery expansion; deviation in Oceanian drought frequency or accelerated plant-based fat substitution would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Milk Protein Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Lactic Butter Market
Dairy Products
Camel Dairy Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Japan Casein Market
Dairy Products
South America Yogurt Market
Dairy Products
Filled Cheese Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Sour Milk Drinks Market