
 Lactic Butter Market | 2026-2036
Lactic Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Butter Market Analysis
EU Green Deal carbon-border adjustments is decoupling small churners from scale-dependent compliance pathways. Arla Foods amba leverages its cooperative structure to sustain Nordic organic sourcing. Lactalis Group anchors Southern European private-label supply through backward integration into Normandy creameries. FrieslandCampina N.V. competes on whey-butter coproduct economics across Benelux retail channels.
Lactic butter denotes a fermented dairy fat produced by inoculating cream with Lactococcus or Leuconostoc strains before churning, yielding diacetyl compounds that impart a tangy aroma and typically 82-84% milk fat content; this cultured profile serves premium baking, sauce emulsification, and direct-spread applications where flavor complexity commands price premiums. Unsalted and cultured product types lead margin pools in artisanal bakery and restaurant procurement, while whipped formats accelerate in convenience-oriented retail channels seeking spreadability without tempering. Food industry and bakery end users dominate volume offtake, though direct-to-consumer online distribution channels represent the fastest-growing access point for specialty churners bypassing traditional wholesale tiers.
EFSA safety assessments for starter-culture strains and REACH compliance for processing aids shape formulation choices across European manufacturing bases, while BIS standards in India and FDA pasteurization mandates in the United States create divergent import-certification burdens for exporters. Stakeholders must monitor regulatory divergence between EU novel-food pathways and U.S. GRAS self-affirmation regimes when positioning cultured-fat products across jurisdictions.
Market Dynamics
The EU F-Gas Regulation is forcing refrigeration-dependent lactic butter processors toward energy-efficient cold chains, restructuring capital allocation across European dairy clusters. This regulatory pressure compounds with artisanal bakery demand concentration in France's Normandy and Brittany regions.
Growth Catalysts
- Artisanal bakery expansion:Western European bakery chains are standardizing cultured butter specifications for laminated dough applications, creating pull-through demand for higher-fat-content churns.
- REACH-compliant processing aids:ECHA-approved emulsifier alternatives enable cleaner-label formulations that command shelf-space premiums in Benelux and Nordic retail.
- Normandy creamery clustering:Geographic concentration of heritage dairy infrastructure supports protected-designation-of-origin credentialing for export markets.
Market Restraints
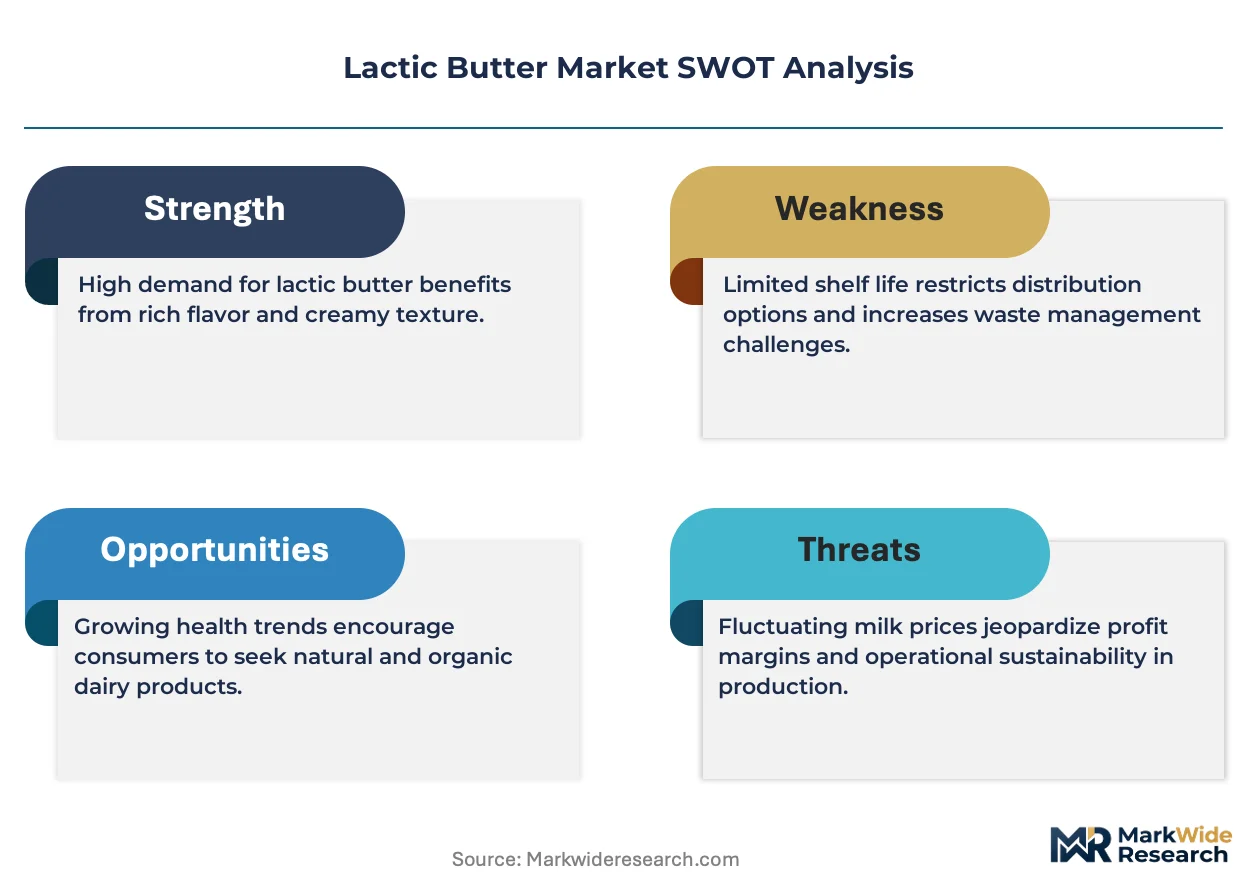
- Cream input volatility:Fluid milk price swings in EU dairy markets compress churn margins, particularly for small-batch producers lacking forward-contract coverage.
- Starter-culture supply concentration:Dependence on Danish and French culture houses creates vulnerability to strain-approval delays under EFSA novel-food assessments.
- Plant-fat substitution:Cultured vegan spreads leveraging precision fermentation are capturing price-sensitive foodservice accounts in urban European markets.
Strategic Opportunities
- Direct-to-consumer channels:Specialty churners are bypassing wholesale tiers through subscription models targeting home bakers in Germany and the Netherlands.
- EU Green Deal carbon-border adjustments:Early compliance investments position cooperative processors for preferential access to carbon-conscious procurement tenders.
- Whey-butter coproduct integration:Dairy processors with captive whey streams can capture value from protein-isolation byproduct flows in Benelux retail channels.
Industry Challenges
- Master churner skill scarcity:Traditional batch-culture expertise is retiring faster than vocational programs in France and Denmark can replenish qualified operators.
- EFSA strain-certification timelines:Novel starter-culture approvals stretch 18-24 months, freezing formulation innovation pipelines for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Butter Market |
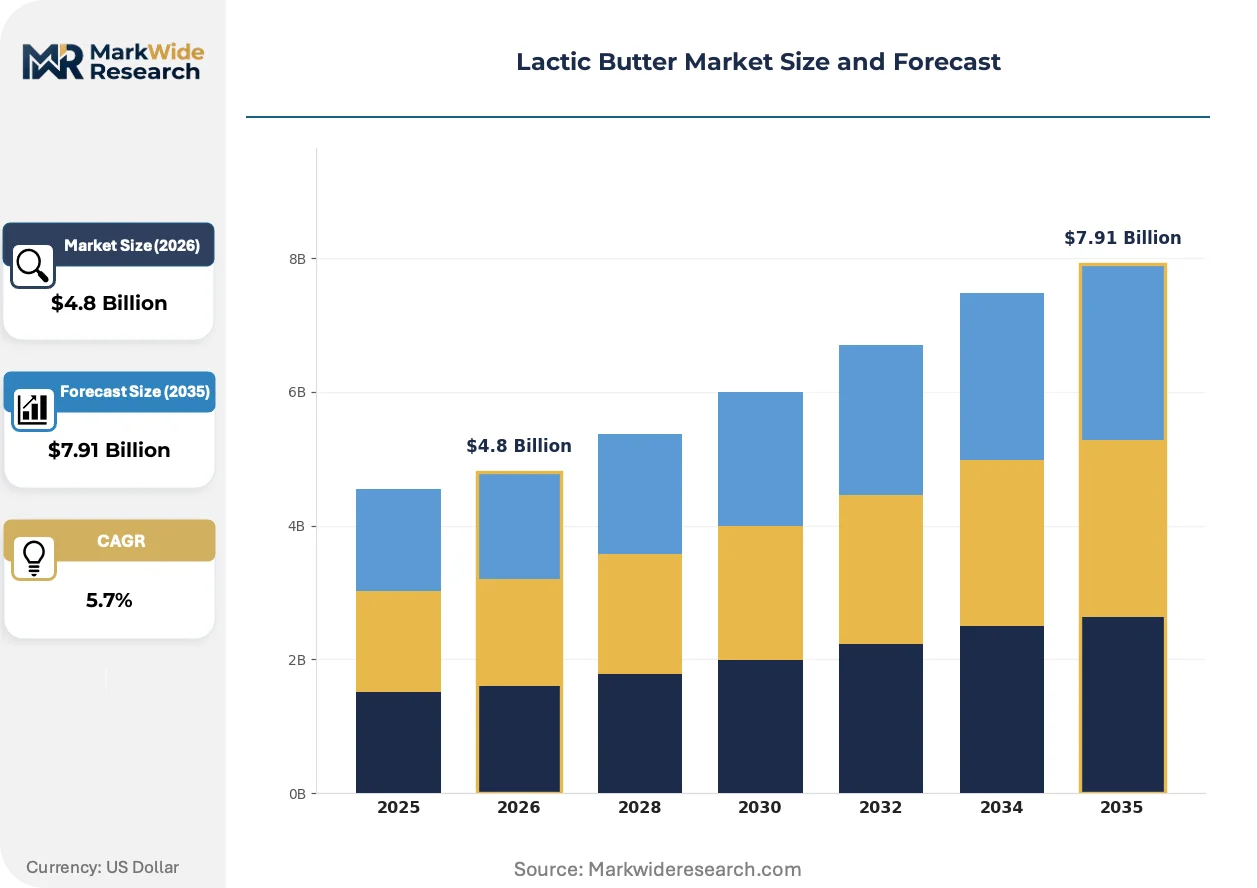
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salted, Unsalted, Cultured, Whipped End User: Food Industry, Bakery, Restaurants, Retail Packaging Type: Tubs, Blocks, Pouches, Sachets Distribution Channel: Online, Supermarkets, Convenience Stores, Farmers Markets |
| Companies Covered | Arla Foods amba, Lactalis Group, Fonterra Co-operative Group, FrieslandCampina N.V., Organic Valley, Ornua, Land O'Lakes, Anchor, DMK Deutsches Milchkontor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Butter Market Emerging Trajectories
Automation of temperature-controlled cream maturation and in-line pH monitoring is compressing batch-to-batch variability, enabling scale without sacrificing the diacetyl-forward flavor profile that defines premium positioning.
Continuous-flow culture systems are automating the traditionally manual cream-inoculation phase, reducing labor dependency for industrial churners in Denmark and the Netherlands. Large cooperatives are deploying these units to maintain output volumes amid workforce constraints. This automation is compressing the cost gap between artisanal batch methods and continuous production without sacrificing the 82-84% milk fat thresholds required by laminated-dough specifications.
REACH restrictions on synthetic processing aids are redirecting formulation R&D toward fermentation-derived alternatives, particularly in German and French manufacturing bases. ECHA's expanding candidate list of substances of very high concern is forcing reformulation of emulsifier packages used in whipped butter formats. Southern European private-label suppliers are responding fastest, leveraging backward integration into Normandy creameries to secure cleaner-label supply chains ahead of 2027 compliance deadlines.
Bakery procurement teams are consolidating supplier panels around churners offering carbon-footprint certification and traceable cream sourcing, displacing spot-market purchasing. This concentration favors cooperatives with integrated farm-to-churn traceability systems, particularly in Nordic markets where Arla Foods amba's organic sourcing credentials command preferential placement. France's artisanal bakery chains represent the most visible early adopters, embedding sustainability scoring into annual vendor reviews.
Lactic Butter Market Segmentation
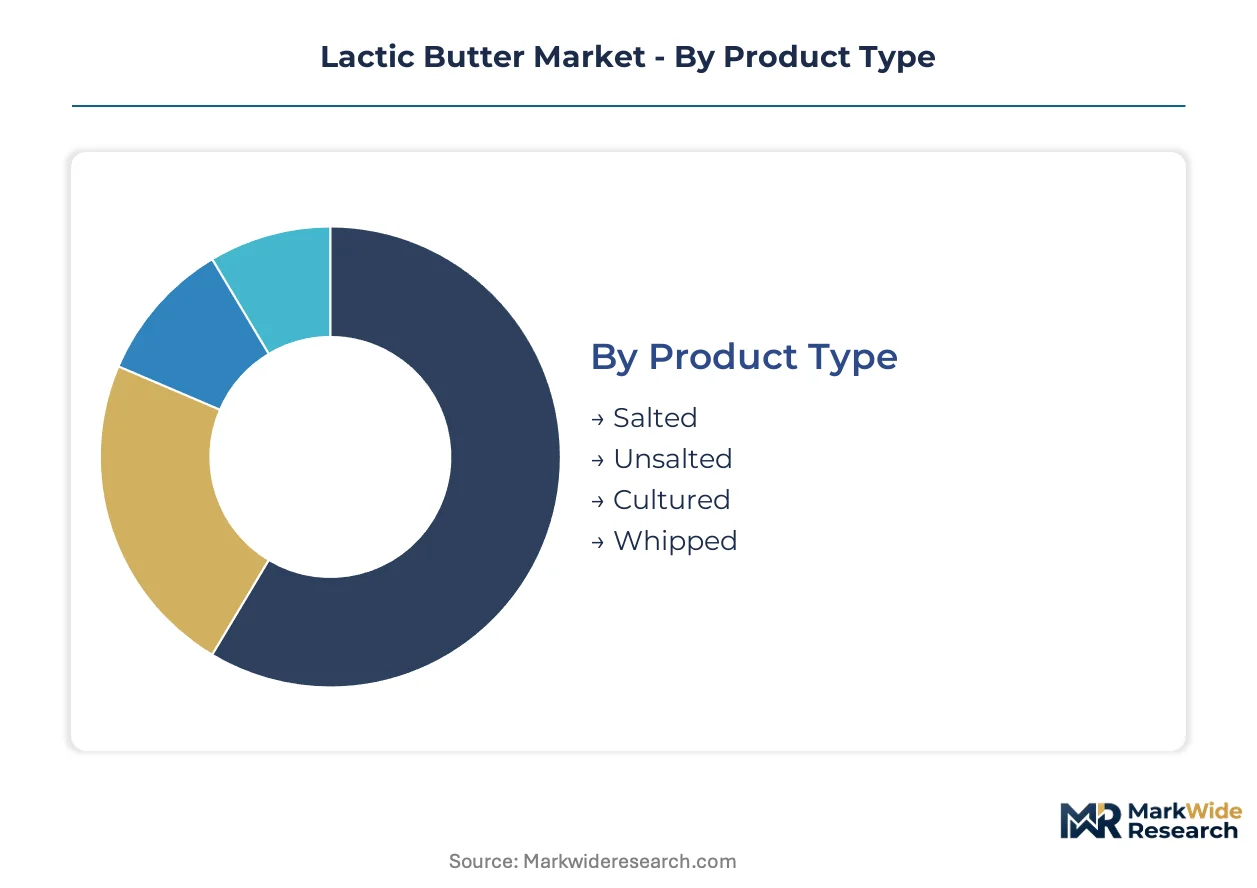
Lactic butter segmentation reflects divergent value capture across formulation complexity and channel access. Upgrade cycles in professional kitchens favor cultured formats, while convenience retail drives packaging and distribution innovation.
Product Type:
Reformulation cycles in premium baking and foodservice are reshaping product mix priorities across European dairy clusters.
- Unsalted:Contains no added sodium chloride, delivering pure milk fat at 82-84% concentration for precise recipe control. Artisanal bakery chains in France's Normandy and Brittany regions specify this format for laminated dough applications where salt levels must be calibrated separately. EFSA starter-culture approvals for diacetyl-producing strains directly influence flavor consistency in this segment.
- Cultured:Fermented with Lactococcus or Leuconostoc strains before churning, generating tangy diacetyl compounds that command price premiums in sauce emulsification and direct-spread positioning. Restaurant procurement panels in Western Europe are consolidating supplier relationships around churners offering carbon-footprint certification and traceable cream sourcing for this variety.
- Salted:Standard table-grade format with 1.5-2% sodium chloride content for direct consumption and basic cooking applications.
- Whipped:Aerated structure achieved through mechanical incorporation of nitrogen or air, improving spreadability without tempering for convenience-oriented retail channels in Benelux and Nordic markets.
Cultured sits at the top of the volume ranking, with whipped climbing the fastest.
End User:
Cost tier differentiation separates specification-grade procurement from spot-market purchasing across professional and consumer channels.
- Bakery:Laminated dough applications require precise fat crystallization behavior and consistent plasticity across temperature ranges. Western European artisanal chains standardize 82-84% milk fat specifications, creating pull-through demand that favors cooperatives with integrated farm-to-churn traceability systems.
- Food Industry:Industrial sauce and prepared meal manufacturers prioritize batch-to-batch consistency through automated temperature-controlled cream maturation. Large processors deploy continuous-flow culture systems to maintain output volumes amid workforce constraints in Denmark and the Netherlands.
- Restaurants:Fine-dining and casual dining establishments source cultured varieties for finishing butter and compound butter applications.
- Retail:Direct-to-consumer channels represent the steepest expansion trajectory for specialty churners bypassing traditional wholesale tiers through subscription models targeting home bakers in Germany and the Netherlands.
Food industry sits at the top of the volume ranking, with retail gaining share fastest.
Packaging Type:
Application requirements dictate format selection across professional versus consumer use cases.
- Blocks:Traditional rectangular format wrapped in parchment or foil, preferred by professional bakers for precise weight measurement and controlled portioning in high-throughput operations.
- Tubs:Rigid plastic containers with resealable lids for repeated access in household refrigeration; dominant in supermarket retail across Southern Europe.
- Pouches:Flexible laminated film structures reducing material weight for e-commerce fulfillment and direct-to-consumer subscription channels.
- Sachets:Single-serve portions for foodservice condiment packs and airline catering applications.
Blocks sit at the top of the volume ranking, with pouches expanding most quickly.
Distribution Channel:
Margin structure varies sharply between consolidated retail procurement and fragmented direct access routes.
- Supermarkets:Centralized category management by retail banners in France, Germany, and the Netherlands drives private-label concentration and sustainability scoring in annual vendor reviews. Lactalis Group anchors Southern European supply through backward integration into Normandy creameries.
- Online:Specialty churners leverage subscription models and direct fulfillment to capture margin otherwise absorbed by wholesale tiers. Arla Foods amba's cooperative structure sustains Nordic organic sourcing credentials that command preferential placement in digital channels.
- Convenience Stores:Impulse-oriented small-format retail with limited cold-chain infrastructure, favoring long-shelf-life salted formats.
- Farmers Markets:Hyperlocal direct sales at heritage dairy cluster locations, concentrated in France's protected-designation-of-origin zones.
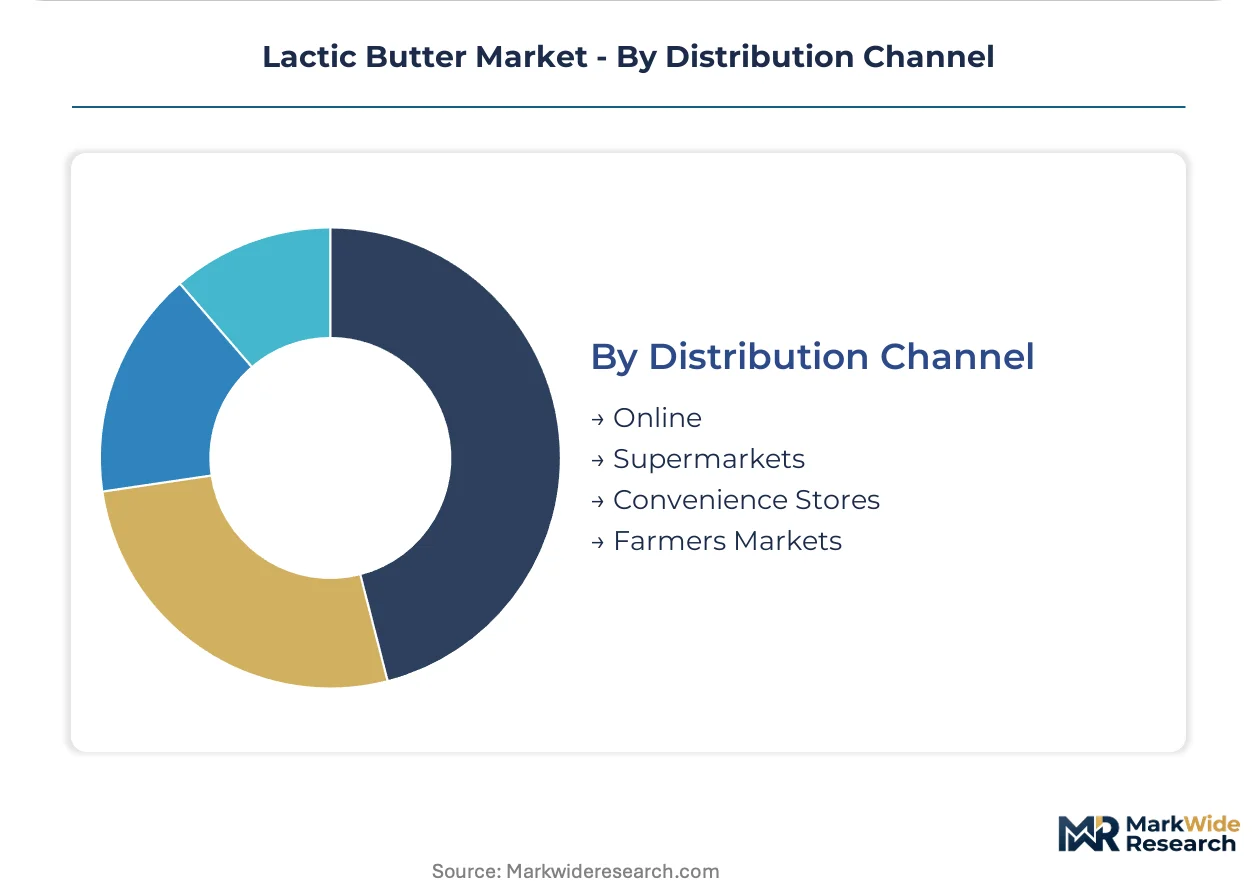
Supermarkets sit at the top of the volume ranking, with online climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master churner expertise clusters in France's Normandy and Brittany dairy belts, anchoring European supply for laminated-dough applications. Danish and Dutch cooperatives leverage automated culture systems to offset workforce constraints. Regulatory divergence between EFSA strain-approval timelines and FDA pasteurization mandates shapes export certification burdens for cross-border suppliers.
France
Artisanal bakery chains in Paris and Lyon standardize cultured butter specifications for croissant and puff-pastry production. The EU F-Gas Regulation pressures processors in Normandy to retrofit refrigeration-dependent creameries with energy-efficient cold chains. Brittany's protected-designation-of-origin zones concentrate heritage dairy infrastructure for export credentialing.
Germany
Industrial sauce manufacturers in North Rhine-Westphalia prioritize batch-to-batch consistency through automated pH monitoring systems. ECHA's REACH restrictions on synthetic emulsifiers redirect formulation R&D toward fermentation-derived processing aids. Direct-to-consumer subscription models targeting home bakers in Berlin and Hamburg represent the fastest-growing access channel for specialty churners.
Netherlands
Benelux retail channels drive demand for whipped-format spreadability without tempering. Large cooperatives deploy continuous-flow culture systems to maintain output volumes amid workforce constraints. FrieslandCampina N.V. competes on whey-butter coproduct economics across supermarket and digital distribution tiers.
Denmark
Nordic organic sourcing credentials command preferential placement in carbon-conscious procurement tenders. Arla Foods amba leverages its cooperative structure to sustain traceable farm-to-churn systems. Starter-culture supply concentration in Danish culture houses creates vulnerability to EFSA novel-food assessment delays.
United States
FDA pasteurization mandates create divergent import-certification burdens for European exporters seeking foodservice accounts. Organic Valley and Land O'Lakes anchor domestic supply through backward integration into regional creameries. Urban markets on the coasts show early adoption of cultured vegan spreads leveraging precision fermentation.
Lactic Butter Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cooperative structures dominate volume supply through captive farm networks, while private-label anchors concentrate Southern European distribution. Three archetypes define competitive positioning: heritage creameries with protected-designation credentials, industrial cooperatives with whey-coproduct integration, and digital-native specialty churners bypassing wholesale tiers. M&A activity targets Normandy creamery assets for backward integration, while capacity investments flow toward automated continuous-flow culture systems.
Within the cooperative tier, Arla Foods amba and Fonterra Co-operative Group exemplify farm-to-churn traceability models that satisfy bakery procurement consolidation around carbon-footprint certification. Lactalis Group occupies a position among private-label suppliers leveraging backward integration into heritage French creameries for cleaner-label supply chains ahead of 2027 REACH compliance deadlines. These three entities represent distinct strategic postures—Nordic organic sourcing, Southern European scale, and Normandy heritage credentialing—without overlapping segment focus.
| Leading Market Players |
|---|
| Arla Foods amba |
| Lactalis Group |
| Fonterra Co-operative Group |
| FrieslandCampina N.V. |
| Organic Valley |
| Ornua |
| Land O'Lakes |
| Anchor |
| DMK Deutsches Milchkontor |
| Others |
Supply Flow & Price Mechanics
Family-owned creameries in France's Normandy and Brittany dairy belts anchor premium pricing through protected-designation credentials, while cooperative processors leverage captive farm networks to discipline input costs and defend margin pools against private-label compression.
Pricing Analysis
The bundled-versus-unbundled service split separates specification-grade cultured butter commanding certification premiums from commodity spot-market churns. Three-tier pricing structure across premium PDO-credentialed, standard industrial-grade, and economy private-label levels tracks fat-content thresholds and starter-culture provenance. Pricing pressure stems from fluid milk price volatility compressing churn margins for small-batch producers lacking forward-contract coverage. Food industry procurement panels show lowest price sensitivity, prioritizing batch-to-batch consistency, while convenience retail channels drive hardest bargain on whipped-format tenders.
Supply Chain Analysis
EU Green Deal local-content mandates and carbon-border adjustment mechanisms are reshaping sourcing toward traceable cream provenance within member-state dairy clusters. Supply concentrates in France, Denmark, and the Netherlands, with heritage infrastructure in Normandy feeding premium export pipelines. Raw material flows draw from fluid milk auctions, starter-culture houses in Copenhagen and Paris, and parchment packaging mills in Germany. Single-source vulnerability sits with Danish and French culture houses facing EFSA novel-food assessment delays. Distribution runs through cooperative-owned cold chains into consolidated retail banners and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lactic butter market functions as a stable compounder, with artisanal bakery procurement consolidation in Western Europe generating predictable pull-through demand for specification-grade cultured varieties.
For Market Incumbents: Deploy automated continuous-flow culture systems to offset retiring master churner expertise and compress batch-to-batch variability. Secure backward integration into Normandy creamery assets ahead of REACH compliance deadlines. Defend against precision-fermented plant-fat substitutes by accelerating carbon-footprint certification programs that satisfy bakery sustainability scoring requirements. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting home bakers in Germany and the Netherlands, bypassing wholesale margin absorption. White-space concentrates in whipped-format convenience retail across Benelux and Nordic markets, where spreadability-without-tempering commands shelf-space premiums. Anchor go-to-market positioning around EFSA-approved starter-culture strain transparency and traceable cream sourcing credentials. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier industrial churners lacking PDO credentialing or cooperative farm-network backing. Long-term viability favors assets with captive whey-butter coproduct integration and automated pH-monitoring infrastructure. Watch EFSA strain-certification timeline compression as inflection signal for formulation innovation pipeline reactivation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heritage Creameries | Secures PDO credentialing and cleaner-label supply chains ahead of REACH deadlines. |
| Automated Continuous-Flow Culture Deployment | Compresses labor dependency while maintaining 82-84% milk fat thresholds for laminated dough. |
| Carbon-Footprint Certification Investment | Unlocks preferential placement in bakery procurement panels consolidating around sustainability scoring. |
| Direct-to-Consumer Subscription Launch | Captures margin otherwise absorbed by wholesale tiers in Germany and Netherlands home-baker segments. |
| Whey-Butter Coproduct Integration | Monetizes protein-isolation byproduct flows across Benelux retail and foodservice channels. |
Methodological Framework
Direct dialogue with master churners, dairy cooperative procurement directors, artisanal bakery chain category managers, and EFSA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from EU dairy market auction data, ECHA REACH candidate list updates, customs trade flows for creamery equipment, and cooperative financial disclosures. Bottom-up volume modeling triangulated against top-down macro dairy consumption patterns.
Segment-level projections across product type, end user, packaging format, and distribution channel fed into analytical framework spanning the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timelines and technology adoption curves. Forecast inputs incorporated EU F-Gas Regulation retrofit cost burdens, EFSA strain-approval pipeline status, and artisanal bakery chain expansion capex disclosures.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting cream cross-border flows, novel precision-fermentation breakthroughs displacing dairy-fat demand, and force majeure events disrupting starter-culture house operations. Forecasts reflect documented assumptions regarding regulatory timeline adherence and bakery procurement consolidation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Russia Whey Protein Market
Dairy Products
White Cheese Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Greek Yogurt Market
Dairy Products
Filled Cheese Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Evaporated Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Fluid Milk Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
United States Dairy Market