
 North America Anhydrous Milk Fat Market | 2026-2036
North America Anhydrous Milk Fat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anhydrous Milk Fat Market Intelligence
Market Context
North American butter oil processing capacity is decoupling from fluid milk trends as manufacturers prioritize fat fractionation investments. Grassland Dairy Products leverages its Wisconsin butter churn infrastructure to supply industrial bakeries across the Midwest. Dairy Farmers of America sustains cooperative aggregation networks that pool milk fat from thousands of member farms. Saputo Inc anchors Canadian production through its Quebec and Alberta facilities, competing with U.S. border processors for cross-border foodservice contracts.
Technical Definition and Segment Structure
Anhydrous milk fat is clarified butter oil with moisture content below 0.1 percent by weight, produced through centrifugal separation of cream followed by vacuum drying, and serves as a shelf-stable, high-smoke-point lipid for industrial baking and confectionery manufacturing. The baking application segment leads volume consumption due to laminated dough requirements in croissant and puff pastry production, while confectionery applications command premium pricing for tempering-grade butter oil with precise melting profiles. Drum packaging dominates bulk industrial channels, though pouch formats are gaining traction among artisan bakery manufacturers seeking portion-controlled inventory management.
Regulatory Framework and Outlook
The FDA enforces identity standards for butter oil under 21 CFR 131, while USDA grading programs classify anhydrous milk fat by flavor and moisture thresholds; Canada's CFIA administers parallel dairy compositional rules under the Safe Food for Canadians Regulations. These frameworks shape import access, with Mexican COFEPRIS aligning sanitary protocols through USMCA dairy annex provisions. Stakeholders must monitor evolving fat-standard harmonization talks and decide whether to certify facilities for dual FDA-CFIA compliance or specialize within single-country supply chains.
Market Dynamics
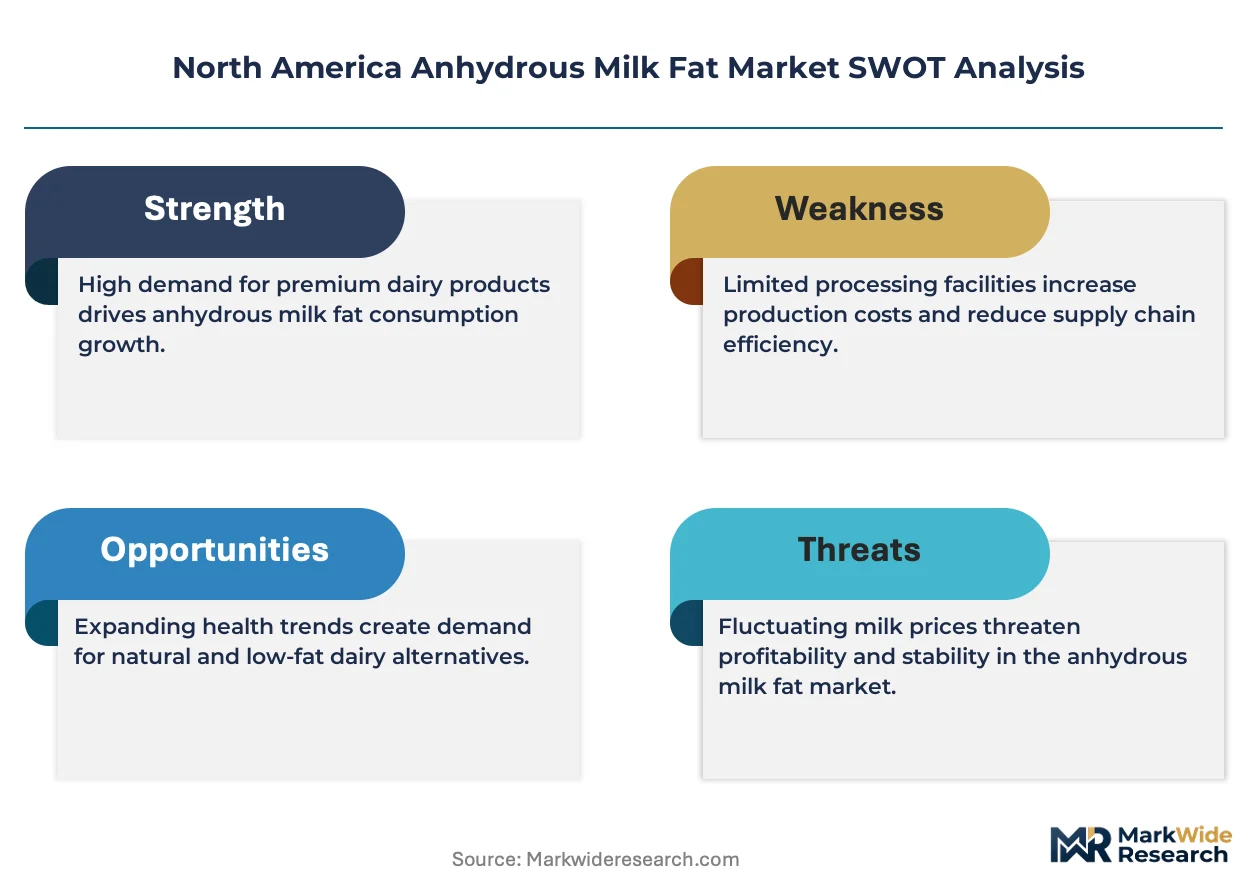
Fat fractionation infrastructure is decoupling from fluid milk processing economics across the Upper Midwest and Quebec, as centrifugal separation capacity expands faster than butter churn output.
Growth Catalysts
- USDA Grading Harmonization:Unified butter oil classification standards under USDA AMS programs are streamlining cross-state procurement for industrial bakeries.
- Laminated Dough Expansion:Artisan croissant production lines in Wisconsin and California are absorbing premium anhydrous milk fat volumes for European-style pastry programs.
- USMCA Dairy Annex:Aligned sanitary protocols between FDA, CFIA, and COFEPRIS are reducing border inspection delays for cross-border milk fat shipments.
Market Restraints
- Cream Supply Volatility:Upper Midwest dairy herd fluctuations constrain raw material predictability for Wisconsin fractionation plants.
- Dual Certification Burden:FDA 21 CFR 131 and CFIA compositional rules impose parallel compliance costs on border processors serving both markets.
- Plant Butter Substitution:Oil-blend laminating fats from palm and shea sources compete on price for mass-market croissant production.
Strategic Opportunities
- Alberta Processing Expansion:Underdeveloped western Canadian fractionation capacity creates white space for foodservice distribution to British Columbia and prairie provinces.
- Tempering-Grade Segmentation:Premium confectionery applications for precise melting-profile butter oil command pricing premiums from chocolate manufacturers.
- Pouch Format Adoption:Portion-controlled packaging is penetrating artisan bakery channels previously locked into drum logistics.
Industry Challenges
- Vacuum Drying Technician Scarcity:Specialized fat processing expertise concentrates in aging workforce cohorts across Wisconsin and Quebec facilities.
- Moisture Threshold Validation:Sub-0.1% certification timelines stretch quality control departments under tightened FDA sampling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anhydrous Milk Fat Market |
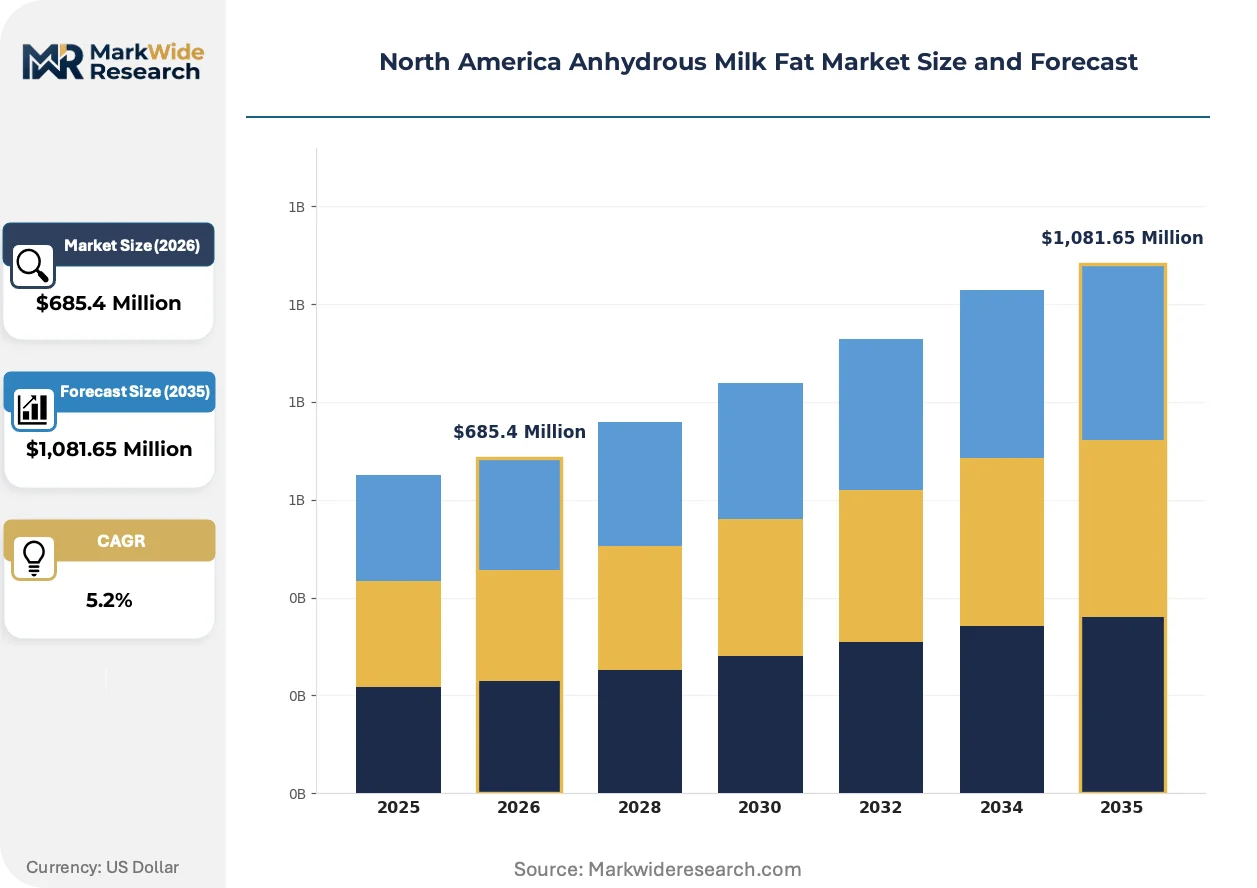
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Oil, Cream, Cooking Fats, Dairy Blends Application: Baking, Confectionery, Dairy Products, Snacks End User: Food Industry, Bakery Manufacturers, Confectioners, Chefs Packaging Type: Tubs, Pouches, Drums, Cartons |
| Companies Covered | Grassland Dairy Products, Inc., Agropur Dairy Cooperative, Dairy Farmers of America, Land O'Lakes, Associated Milk Producers Inc., Saputo Inc, California Dairies Inc., Arla Foods, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anhydrous Milk Fat Market Strategic Shifts & Innovations
Automation of separation and drying workflows is compressing unit economics while regulatory alignment across USMCA jurisdictions reshapes cross-border supply routing.
Membrane filtration systems paired with centrifugal separators are automating cream concentration stages that previously required manual density monitoring. Large-scale cooperatives in the Upper Midwest are deploying these integrated lines to reduce labor headcount per kilogram of butter oil output. The technology is automating quality consistency checks that formerly delayed batch release by hours.
CFIA's updated compositional verification protocols under Safe Food for Canadians Regulations are mandating third-party laboratory certification for moisture content claims. This enforcement shift is forcing Quebec processors to invest in in-house gas chromatography capacity or outsource to accredited labs in Ontario. Bulk industrial buyers now require documentation trails that previously sufficed with producer declarations.
Foodservice distributors are consolidating purchasing of tempering-grade and baking-grade specifications through single-source contracts rather than splitting orders across multiple suppliers. This bundling behavior is compressing vendor lists for laminated pastry manufacturers in California and artisan chocolate producers in Ontario. The concentration is most visible in metropolitan bakery supply chains where logistics costs favor consolidated drop schedules.
North America Anhydrous Milk Fat Market Segmentation
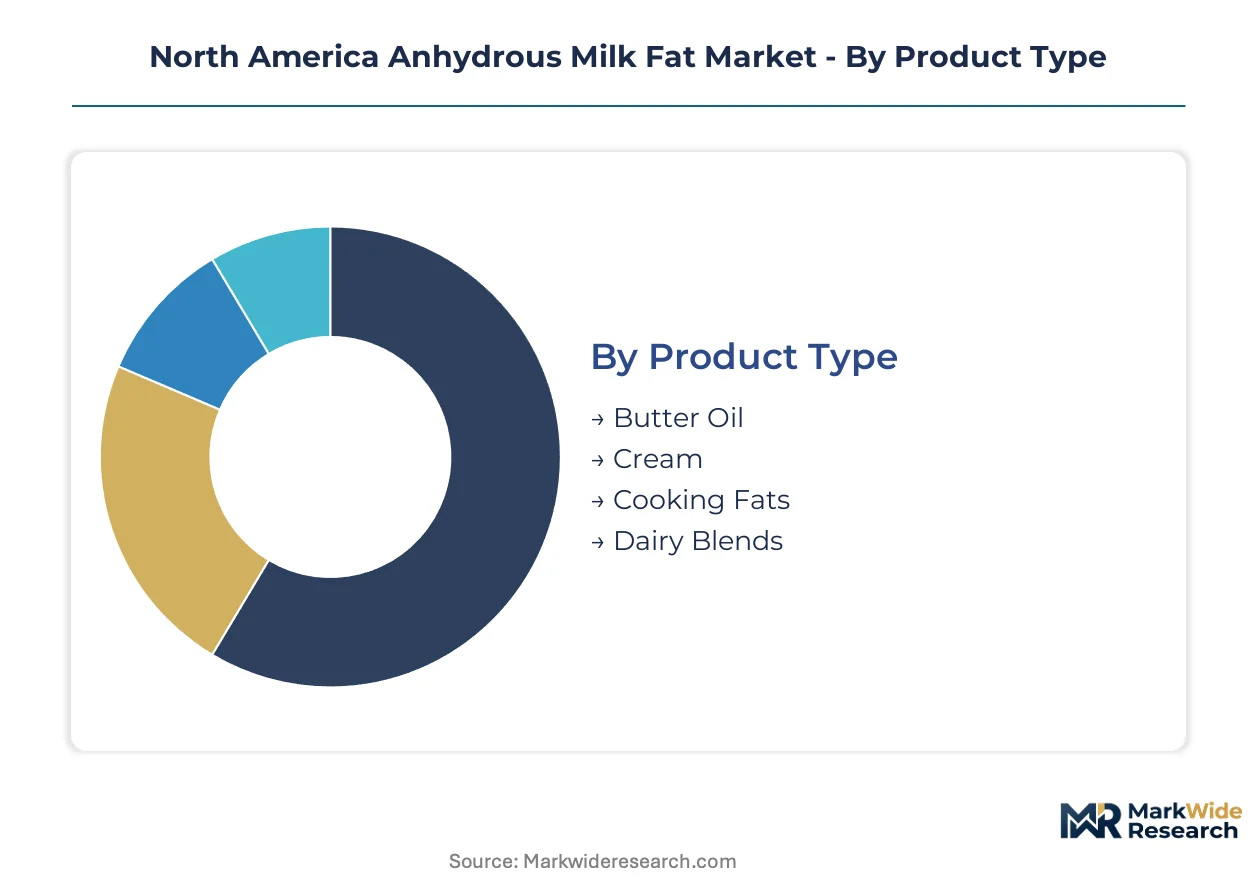
Anhydrous milk fat procurement patterns diverge sharply across product specifications and end-use requirements. Wisconsin and Quebec processing clusters calibrate their fractionation output to match these segment-specific demand profiles.
Product Type:
Supply concentration in Upper Midwest churn infrastructure directly shapes which product categories achieve scale economies.
- Butter Oil:Clarified lipid with moisture content below 0.1 percent by weight, produced through centrifugal separation followed by vacuum drying. Wisconsin's Grassland Dairy and Quebec's Saputo facilities concentrate output for industrial bakery procurement across the Great Lakes corridor.
- Cream:High-fat dairy fraction serving as feedstock for downstream fractionation or direct whipping applications. California's Central Valley processors supply fresh cream to Los Angeles and San Francisco bakery manufacturers demanding shorter supply chains.
- Cooking Fats:Blended or fractionated lipids formulated for high-heat stability. Midwest foodservice distributors stock these for institutional kitchen contracts.
- Dairy Blends:Milk fat combined with vegetable oils to balance cost and functionality. Alberta processors are expanding capacity for prairie province foodservice accounts.
Today's leader: Butter Oil. Tomorrow's challenger: Dairy Blends.
Application:
Margin structures vary dramatically across these use cases, with precision requirements determining pricing tiers.
- Baking:Laminated dough production for croissants and puff pastries demands precise plasticity ranges. Artisan bakery expansion in California and Wisconsin absorbs premium volumes for European-style pastry programs.
- Confectionery:Tempering-grade specifications for chocolate manufacturing require narrow melting point tolerances. Ontario chocolate producers pay premiums for batch-certified butter oil with documented thermal profiles.
- Dairy Products:Recombined milk and cheese processing utilize anhydrous milk fat for standardized fat content. Upper Midwest dairy cooperatives pool member farm output for these industrial channels.
- Snacks:Flavored and coated applications prioritize cost efficiency over precise functionality. Mass-market processors in the Southeast source through consolidated foodservice distributors.
Volume concentrates in Baking. Value expansion is climbing the fastest in Confectionery.
End User:
Procurement sophistication separates these customer tiers, with specification intensity rising at each level.
- Food Industry:Broad industrial category encompassing processed food manufacturers. Multi-plant operators negotiate long-term supply agreements with Upper Midwest cooperatives.
- Bakery Manufacturers:Dedicated croissant, bread, and pastry producers with exacting fat functionality requirements. Wisconsin and California facilities specify tempering-grade or baking-grade certifications in purchase orders.
- Confectioners:Chocolate and candy producers requiring documented melting curves. Ontario and Quebec processors maintain dedicated quality control protocols for this segment.
- Chefs:Restaurant and catering operations sourcing through foodservice distributors. Portion-controlled pouch formats are gaining traction among high-volume kitchen operations.
Contract scale favors Food Industry. Specification intensity peaks with Confectioners.
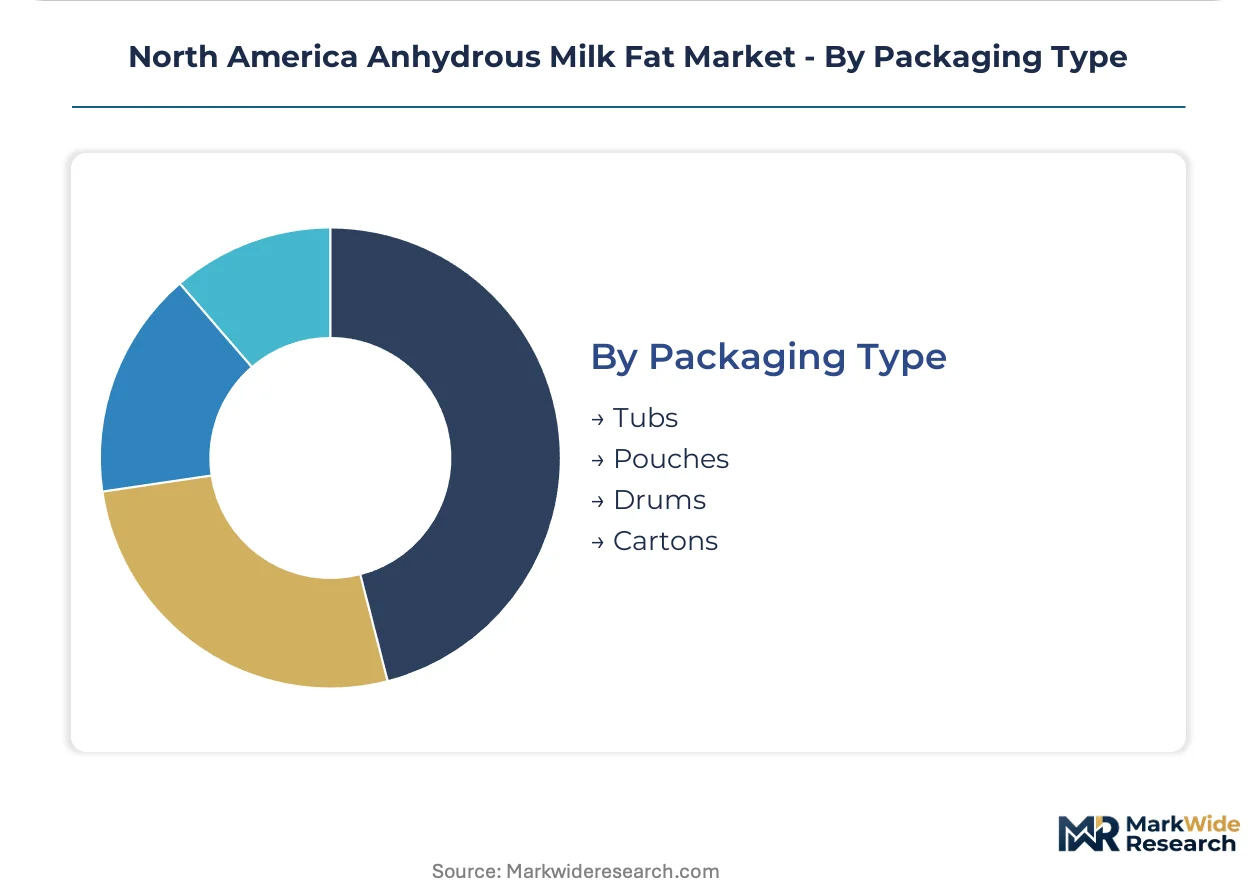
Packaging Type:
Logistics economics and inventory turnover rates determine format selection across customer segments.
- Drums:Bulk industrial standard for high-volume bakery and confectionery procurement. Rail-served Wisconsin plants load outbound drums for national distribution.
- Pouches:Flexible portion-controlled formats for artisan bakeries and chef channels. California distributors are consolidating pouch SKUs to reduce warehouse complexity.
- Tubs:Intermediate containers for foodservice and smaller industrial accounts. Midwest dairy suppliers stock tub formats for regional delivery routes.
- Cartons:Retail-oriented packaging for specialty grocery and direct-to-consumer channels. Limited penetration in industrial anhydrous milk fat markets.
Drums dominate tonnage. Pouches are gaining share fastest in artisan channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA and CFIA compliance costs is redirecting fractionation investments toward jurisdictions with streamlined certification pathways. Producers weigh single-market specialization against dual-certification overhead when siting new vacuum drying capacity.
United States
Wisconsin and California processing clusters absorb the majority of North American foodservice demand for laminated pastry production. FDA's 21 CFR 131 identity standards enforce moisture thresholds below 0.1 percent by weight, with USDA grading programs adding flavor classification layers. Grassland Dairy Products leverages rail-served Green County infrastructure to supply industrial bakeries across the Great Lakes corridor.
Canada
Quebec and Alberta facilities compete for cross-border contracts with US border processors under CFIA's Safe Food for Canadians Regulations. Saputo Inc anchors domestic production through Montreal and Lethbridge plants, while western Canadian capacity remains underdeveloped relative to prairie province foodservice demand. Third-party laboratory certification for moisture content claims is now mandatory under updated compositional verification protocols.
Mexico
COFEPRIS aligns sanitary protocols with FDA and CFIA frameworks through USMCA dairy annex provisions, reducing border inspection delays for imported milk fat shipments. Mexican confectionery and bakery manufacturers source through consolidated distributors rather than direct processor relationships. Northern border states concentrate import handling infrastructure for re-export to Central American markets.
North America Anhydrous Milk Fat Market Key Industry Players
United States producers anchor the scale-driven tier; Canadian specialists hold cooperative-structured positions with integrated member farm networks. Market structure tilts toward consolidated procurement power at the buyer level, with foodservice distributors consolidating vendor lists for laminated pastry manufacturers. Three archetypes dominate: large-scale cooperatives pooling thousands of member farms, privately held regional processors with captive churn infrastructure, and cross-border diversified dairy conglomerates. Competitive moves center on fractionation capacity expansion and backward integration into cream supply.
Within the cooperative archetype, Dairy Farmers of America and Associated Milk Producers Inc exemplify member-governed structures that aggregate raw milk fat across dispersed farm networks. Grassland Dairy Products occupies a position among privately held regional processors with established Wisconsin butter churn infrastructure. Saputo Inc represents the cross-border diversified model, with facilities spanning Quebec and Alberta that compete directly with US border plants for foodservice contracts.
| Leading Market Players |
|---|
| Grassland Dairy Products, Inc. |
| Agropur Dairy Cooperative |
| Dairy Farmers of America |
| Land O'Lakes |
| Associated Milk Producers Inc. |
| Saputo Inc |
| California Dairies Inc. |
| Arla Foods |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Artisan bakery procurement consolidation across California and Wisconsin is forcing fractionation plants to certify for dual FDA-CFIA compliance, compressing margins on cross-border shipments while elevating premiums for single-origin certified butter oil.
Pricing Analysis
Distributor margins absorb the steepest compression as foodservice buyers consolidate vendor lists for laminated pastry programs. Three-tier pricing structure across premium, standard, and economy levels separates tempering-grade confectionery certifications from industrial baking specifications and blended dairy-vegetable alternatives. Pricing pressure stems from palm and shea oil substitutes in mass-market croissant production. Mass-market snack manufacturers exhibit highest price sensitivity; Ontario chocolate producers show lowest sensitivity due to narrow melting-point tolerances.
Supply Chain Analysis
Vacuum drying technician scarcity across Wisconsin and Quebec plants constrains throughput expansion at existing fractionation facilities. Supply concentrates in the Upper Midwest dairy belt and Canadian prairie provinces, with California's Central Valley serving fresh cream to West Coast bakeries. Raw material flows draw from Upper Midwest dairy herds, Alberta cream pooling networks, and cross-border whey fat recovery operations. Single-source vulnerability looms in specialized gas chromatography certification capacity for moisture validation. Distribution runs through rail-served Wisconsin plants and consolidated foodservice distributors in metropolitan bakery supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA's updated 21 CFR 131 sampling protocols and CFIA's mandatory third-party laboratory certification are accelerating demand for verified supply chain documentation.
For Market Incumbents: To counter plant butter substitution in mass-market channels, Grassland Dairy Products and Saputo Inc should deepen backward integration into Upper Midwest cream supply while certifying additional facilities for dual FDA-CFIA compliance to capture cross-border foodservice contracts. For New Entrants and Emerging Players: CFIA's Safe Food for Canadians Regulations in Alberta opens a window for western Canadian fractionation capacity to serve underpenetrated prairie province foodservice demand through pouch-format portion control targeting artisan bakery channels. For Investors and Strategic Acquirers: Asymmetric upside sits with privately held regional processors possessing captive Wisconsin churn infrastructure and established rail distribution networks, with inflection signaled by sustained cream price volatility forcing cooperative consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FDA-CFIA compliance unlocks cross-border procurement from Ontario chocolate manufacturers. |
| Backward Integration into Cream Supply | Captive Upper Midwest dairy herd contracts insulate against raw material volatility. |
| Pouch Format Manufacturing Scale-Up | Portion-controlled packaging penetrates California artisan bakery channels previously locked into drums. |
| Gas Chromatography Certification | In-house moisture validation capacity satisfies CFIA's mandatory third-party laboratory protocols. |
| Alberta Processing Expansion | Western Canadian fractionation addresses underdeveloped prairie province foodservice infrastructure. |
Research Approach
Bottom-up bakery and confectionery procurement modeling reconciled against top-down fractionation capacity tracking forms the analytical core of this study. Primary interviews with Wisconsin plant managers, Ontario chocolate producer procurement leads, California artisan bakery owners, and CFIA regulatory affairs specialists combined with secondary validation from USDA AMS grading reports, FDA 21 CFR 131 filings, CFIA compositional verification protocols, and Upper Midwest dairy cooperative aggregation disclosures. Triangulation between demand-side specification intensity and supply-side certification capacity anchors volume and value estimates.
Historical trendline analysis of butter oil pricing spreads against cream input costs established baseline elasticity patterns across the projection horizon. Segmentation dimensions modeled include product type, application functionality, end-user procurement sophistication, and packaging format logistics. CAGRs derived from fitted growth curves incorporating regulatory alignment milestones, laminated dough production line expansion, and tempering-grade certification adoption rates. Industry-specific forecast inputs capture USMCA dairy annex implementation timing and FDA sampling protocol enforcement intensity.
Revisions become necessary when dairy herd contraction exceeds modeled thresholds, CFIA moisture certification backlogs materialize, or palm oil price collapses accelerate plant butter substitution. Forecasts reflect documented assumptions about regulatory enforcement consistency and artisan bakery expansion sustainability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Dairy Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Dairy Spreads Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Probiotic Cheese Market
Dairy Products
UHT Milk Market
Dairy Products
Goat Milk Products Market
Dairy Products
Evaporated Milk Market
Dairy Products
Condensed Milk Market
Dairy Products
Butter and Margarine Market
Dairy Products
United States Casein Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Dry Whole Milk Powder Market