
 Canada Milk Protein Market | 2026-2036
Canada Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Milk Protein Market Outlook
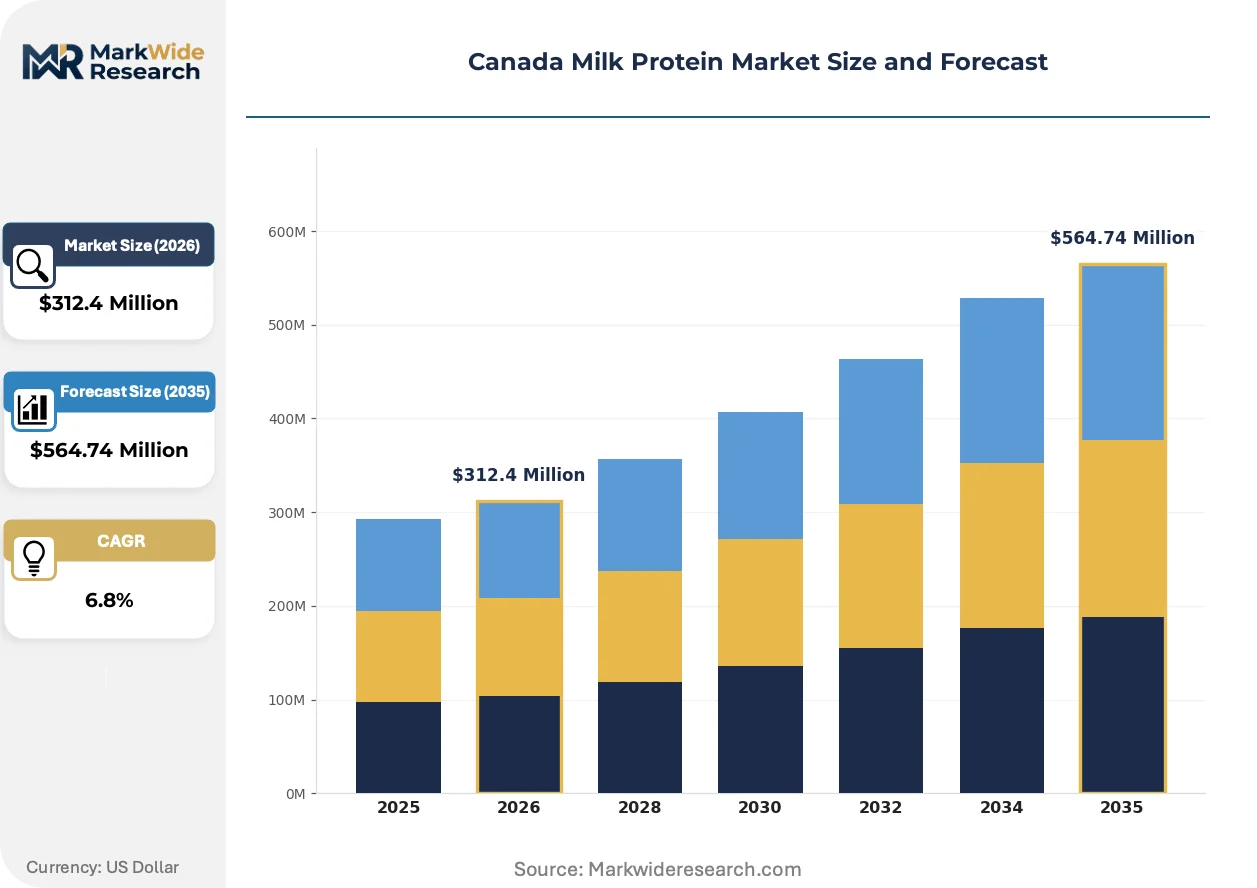
Modular ingredient bundling is hardening as the dominant procurement pattern, with buyers combining whey protein concentrates, isolates, and hydrolysates into single-source contracts rather than spot purchasing. Glanbia plc leverages its North American processing footprint to anchor large-volume supply agreements with Canadian sports nutrition manufacturers. Saputo Inc. competes through backward integration into dairy farming cooperatives, securing fluid milk access that sustains casein production margins.
Canada milk protein comprises the nitrogenous compounds extracted from bovine milk, primarily encompassing whey proteins with globular structures and casein micelles containing alpha, beta, and kappa fractions, typically standardized to protein concentrations ranging from 34% to 90% depending on processing intensity. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources across food systems. Whey protein leads volume flows due to its rapid absorption profile and dominance in sports nutrition formulations, while milk protein concentrate captures expanding share in infant formula applications where nutritional completeness commands premium positioning. Casein and caseinates retain stable demand in bakery and processed cheese systems where functional properties outweigh cost sensitivity.
Health Canada sets compositional standards through the Food and Drugs Act and Regulations, while the Canadian Food Inspection Agency enforces labeling and safety protocols that shape product claims and import requirements. The Safe Food for Canadians Regulations mandate preventive control plans that increase compliance costs for smaller ingredient suppliers. Provincial dairy boards under the Canadian Dairy Commission framework control milk pricing and quota allocation, directly constraining raw material availability for protein fractionation. Stakeholders must monitor quota policy negotiations and novel food approval pathways to anticipate supply constraints and positioning opportunities.
Market Dynamics
Modular ingredient bundling now dominates Canadian procurement, with sports nutrition manufacturers consolidating whey protein concentrates, isolates, and hydrolysates into multi-year single-source contracts rather than fragmented spot purchases.
Growth Catalysts
- Clean-label infant formula demand:Parents in Ontario and Quebec prioritize nutritional completeness over cost, pulling milk protein concentrate into premium pediatric formulations.
- Sports nutrition expansion:Canadian athletic supplement brands scale whey protein volumes for rapid-absorption recovery products targeting amateur and professional athletes.
- Functional food fortification:Bakery and processed cheese systems embed casein for emulsification and gelling properties that plant proteins cannot replicate.
Market Restraints
- Supply-side quota rigidity:Provincial dairy boards under the Canadian Dairy Commission constrain fluid milk allocation, capping raw material throughput for fractionation facilities.
- Regulatory compliance burden:Health Canada's novel food notification requirements for modified protein isolates extend approval timelines and elevate testing expenditures.
- Plant protein substitution:Pea and oat protein isolates capture share in mass-market nutrition bars where functional performance requirements are less stringent.
Strategic Opportunities
- Underpenetrated Atlantic provinces:Nova Scotia and New Brunswick lack local dairy processing infrastructure, creating whitespace for regional distribution hubs serving maritime food manufacturers.
- Medical nutrition applications:Enteral and clinical nutrition formulations require precise amino acid profiles that hydrolyzed whey proteins deliver with superior bioavailability.
- Sustainable packaging mandates:Quebec's extended producer responsibility regulations incentivize suppliers offering bulk concentrate in reusable tote systems versus single-use bags.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized protein separation and membrane filtration expertise concentrates in Ontario and Quebec, limiting facility expansion elsewhere.
- Preventive control plan costs:The Canadian Food Inspection Agency's Safe Food for Canadians Regulations mandate documented hazard controls that strain smaller ingredient suppliers' quality assurance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Milk Protein Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Caseinates, Milk Protein Concentrate End User: Dairy Industry, Food & Beverage, Nutritional Supplements, Bakery Application: Functional Food, Infant Formula, Sports Nutrition, Dietary Supplements Distribution Channel: Online Sales, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Glanbia plc, Arla Foods amba, Lactalis Ingredients, Hilmar Ingredients, Fonterra Co-operative Group Limited, Saputo Inc., Kerry Group plc, Milk Specialties Global, Agropur Dairy Cooperative, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Milk Protein Market Strategic Shifts
Technology convergence and procurement rationalization are compressing traditional supply relationships, with Canadian buyers demanding integrated ingredient-service bundles that extend beyond commodity exchange.
Microfiltration and ultrafiltration membrane systems are absorbing capital investment across Ontario processing corridors. Equipment suppliers report twelve-month order backlogs as dairy cooperatives retrofit facilities for higher-value protein fractionation. This technology shift is absorbing mid-tier whey processors into larger integrated networks, consolidating tolling relationships.
Health Canada's Food Directorate tightened compositional standards for protein isolate labeling claims under the Food and Drugs Act. Manufacturers must now substantiate amino acid profile declarations through third-party verification, adding analytical costs but reducing adulteration incidents. Sports nutrition brands in British Columbia and Alberta accelerate reformulation to preempt enforcement actions.
Consolidated contracting now displaces fragmented purchasing across Canadian food manufacturing. Mid-size bakery and nutrition companies aggregate annual whey and casein volumes into eighteen-month agreements with penalty clauses for volume shortfalls. This pattern concentrates procurement leverage with Ontario-based dairy processors while marginalizing spot-market traders.
Canada Milk Protein Market Segmentation
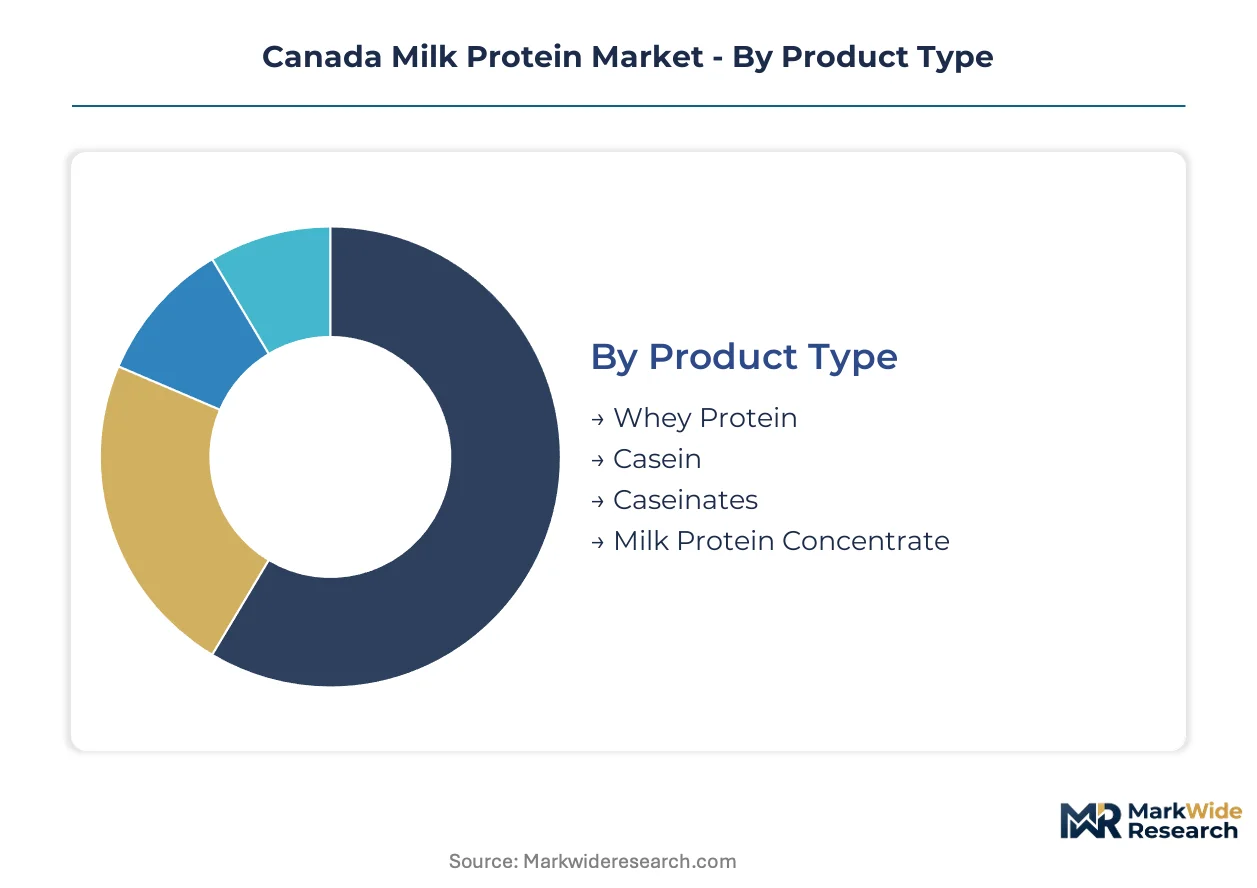
Protein fractionation technology upgrades are reshaping how Canadian manufacturers select ingredient specifications across product portfolios. Buyers now align procurement cycles with membrane filtration capacity expansions rather than traditional commodity purchasing calendars.
Product Type:
Upgrade cycles in ultrafiltration equipment are pushing processors toward higher-concentration isolates that command premium positioning in reformulated applications.
- Whey Protein:Globular protein fractions standardized from 34% concentrate to 90%+ isolate purity through crossflow membrane separation. Ontario sports nutrition manufacturers in the Greater Toronto Area anchor volume demand for rapid-absorption hydrolysates targeting amateur athlete recovery segments.
- Casein:Micellar protein structures containing alpha, beta, and kappa fractions that form sustained-release amino acid matrices. Quebec processed cheese systems embed casein for emulsification stability where functional performance outweighs cost sensitivity in aged cheddar production.
- Caseinates:Soluble salts of casein produced through alkali treatment that enhance water-binding in comminuted meat systems.
- Milk Protein Concentrate:Combined whey and casein fractions retaining native micellar structure for nutritional completeness in pediatric formulations.
Whey protein sits at the top of the volume ranking, with milk protein concentrate climbing the fastest.
End User:
Customer procurement sophistication varies sharply across buyer types, with nutritional supplement manufacturers demanding certificate-of-analysis documentation that dairy cooperatives rarely provide.
- Dairy Industry:Internal protein fractionation for cheese whey valorization and standardized ingredient production.
- Food & Beverage:Clean-label protein fortification in ready-to-drink beverages and dairy alternatives where Health Canada compositional standards constrain formulation flexibility.
- Nutritional Supplements:Precision amino acid profiling for sports recovery and clinical nutrition applications requiring third-party verification under tightened Food Directorate labeling rules.
- Bakery:Casein and caseinate incorporation for dough conditioning and crumb structure enhancement in industrial bread production.
Nutritional supplements generate the steepest margin expansion, while bakery maintains the most stable contract volumes.
Application:
Application-specific formulation requirements are concentrating procurement leverage with processors capable of custom amino acid profiling and allergen segregation protocols.
- Functional Food:Protein fortification in mainstream grocery categories where consumer label literacy drives specification transparency demands.
- Infant Formula:Nutritional completeness mandates in Ontario and Quebec pediatric markets where parental preference for domestic sourcing supports premium positioning for milk protein concentrate.
- Sports Nutrition:Rapid-absorption whey hydrolysates for pre- and post-workout formulations targeting British Columbia and Alberta fitness demographics.
- Dietary Supplements:Capsule and tablet applications requiring low-moisture protein isolates with extended shelf stability.
Sports nutrition commands the highest volume growth rate, with infant formula sustaining the most resilient pricing structure.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with large manufacturers bypassing intermediaries to secure direct quality assurance relationships.
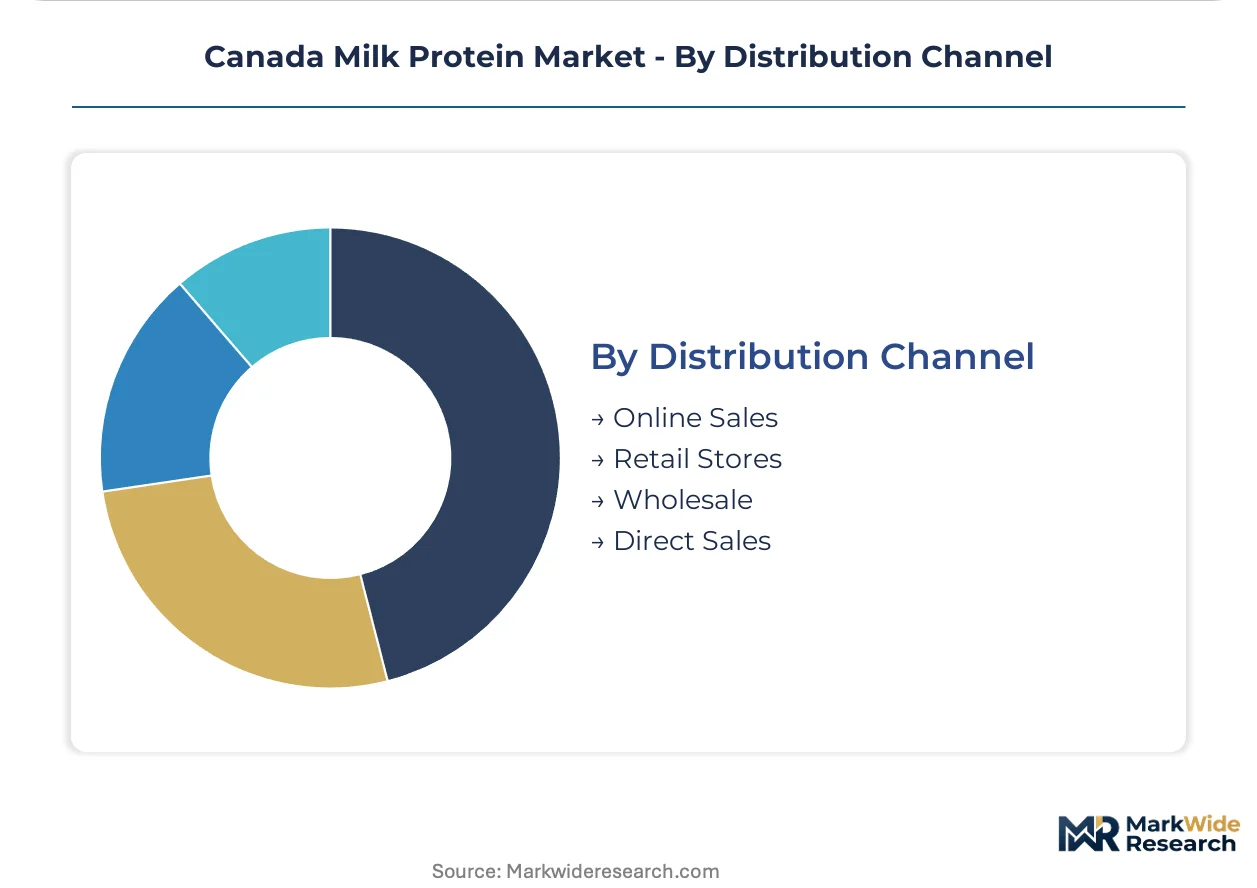
- Online Sales:E-commerce platforms serving small-scale supplement brands and direct-to-consumer protein powder merchants.
- Retail Stores:Mass-market grocery and pharmacy chains distributing consumer-packaged protein supplements.
- Wholesale:Ingredient distributors aggregating volumes for mid-size food manufacturers lacking direct processor relationships.
- Direct Sales:Large-volume contracts between dairy processors and national brand manufacturers with dedicated account management.
Direct sales capture the largest revenue concentration, with online channels expanding most quickly among emerging regional brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy protein fractionation in Canada traces its industrial roots to post-war cooperative consolidation in Ontario and Quebec, where fluid milk pooling arrangements first enabled large-scale whey and casein extraction. Federal supply management under the Canadian Dairy Commission subsequently entrenched regional processing clusters around quota-allocation centers.
Ontario
The Greater Toronto Area anchors national whey protein demand, with sports nutrition manufacturers contracting for rapid-absorption hydrolysates. Health Canada's Food Directorate enforces compositional standards for protein isolate labeling claims that extend approval timelines. Guelph-Waterloo corridor membrane filtration facilities retrofit ultrafiltration systems to capture higher-value isolate fractions.
Quebec
Processed cheese systems in aged cheddar production embed casein for emulsification stability where functional performance outweighs cost sensitivity. Provincial dairy boards under the Canadian Dairy Commission framework control milk pricing and quota allocation, directly constraining raw material throughput. Montreal-area dairy cooperatives consolidate tolling relationships as mid-tier processors absorb into integrated networks.
Alberta
Fitness demographics in Calgary and Edmonton pull whey protein volumes for pre- and post-workout formulations targeting amateur athlete recovery segments. The Canadian Food Inspection Agency's Safe Food for Canadians Regulations mandate preventive control plans that strain smaller ingredient suppliers' quality assurance budgets. Edmonton distribution hubs serve underpenetrated Prairie Provinces where local dairy processing infrastructure remains sparse.
British Columbia
Clean-label infant formula demand concentrates in Vancouver pediatric markets where parental preference for domestic sourcing supports premium positioning. British Columbia's extended producer responsibility regulations incentivize suppliers offering bulk concentrate in reusable tote systems versus single-use bags. Vancouver Island lacks local fractionation facilities, creating whitespace for maritime distribution partnerships.
Atlantic Canada
Nova Scotia and New Brunswick food manufacturers source protein ingredients through Ontario and Quebec intermediaries due to absent regional processing infrastructure. The Canadian Dairy Commission quota negotiations determine fluid milk availability for maritime fractionation investment decisions. Halifax regional distribution hubs could capture whitespace serving bakery and nutritional supplement manufacturers with consolidated procurement contracts.
Canada Milk Protein Market Competitive Environment
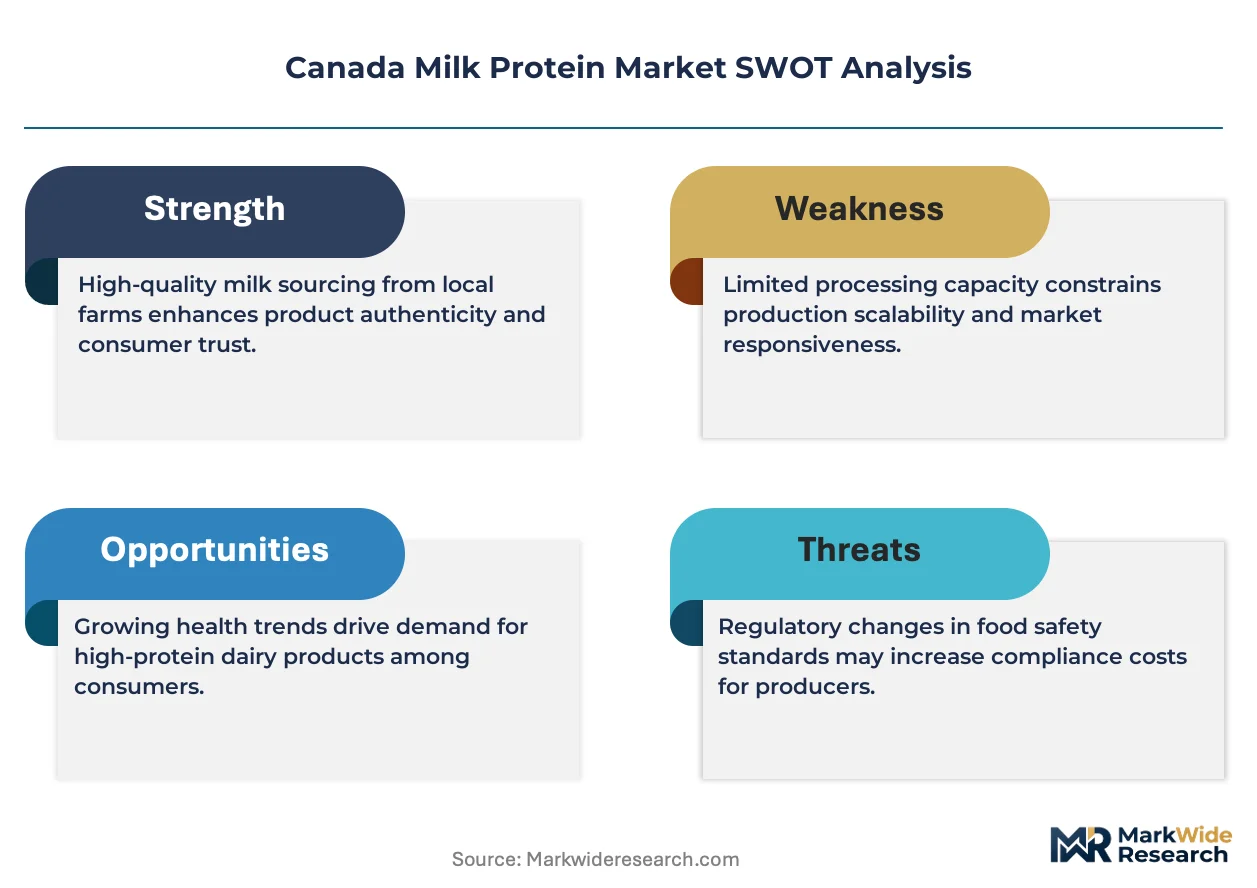
Premium-margin players sit above commodity-margin players across protein purity tiers and certification sophistication, with isolate-grade specialists commanding pricing power over concentrate-grade bulk suppliers. The Canadian market exhibits moderate consolidation, with multinational dairy processors and domestic cooperatives controlling membrane filtration capacity while smaller toll processors face absorption into integrated networks. Three archetypes dominate: Irish-Danish cooperative giants with North American fractionation footprints, Canadian dairy cooperatives leveraging backward integration into fluid milk quotas, and US-based ingredient specialists anchoring large-volume supply agreements. Capacity expansion and consolidated contracting displace fragmented spot purchasing as the dominant competitive moves.
Within the multinational processor tier, Glanbia plc and Arla Foods amba exemplify premium-margin positioning through integrated ingredient-service bundles that extend beyond commodity exchange. Saputo Inc. occupies a distinct archetype as a Montreal-based dairy cooperative leveraging captive fluid milk access under Canadian supply management. Kerry Group plc represents the formulation-technology vector, embedding protein ingredients within broader taste and nutrition systems rather than standalone commodity sales. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic actions.
| Leading Market Players |
|---|
| Glanbia plc |
| Arla Foods amba |
| Lactalis Ingredients |
| Hilmar Ingredients |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Kerry Group plc |
| Milk Specialties Global |
| Agropur Dairy Cooperative |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration technology upgrades across Ontario and Quebec simultaneously compress per-unit production costs and consolidate processing capacity within integrated dairy cooperatives, tightening procurement leverage for buyers while elevating barriers for smaller toll processors.
Pricing Analysis
Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade hydrolysate levels dominates Canadian milk protein transactions, with purity certification and volume scale serving as the primary differentiation drivers. Pricing pressure stems from plant protein substitution in mass-market nutrition bars, compressing margins at the economy tier. Nutritional supplement manufacturers exhibit the highest price sensitivity due to reformulation flexibility, while infant formula producers absorb premium pricing for domestic-sourced milk protein concentrate.
Supply Chain Analysis
Direct-to-processor contracts handle national-brand manufacturer demand, while wholesale distributors aggregate volumes for mid-size food manufacturers lacking direct relationships. Canadian milk protein supply draws from domestic dairy farming cooperatives under Canadian Dairy Commission quota management, with supplemental whey volumes sourced from US and European processors. Raw material dependencies center on fluid milk allocation, membrane filtration equipment, and alkali reagents for caseinate production. Single-source vulnerability concentrates in Ontario membrane filtration capacity, where twelve-month equipment order backlogs constrain facility expansion elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada milk protein market represents a late-cycle quality story as parental demand for nutritional completeness in infant formula pulls specification standards upward, rewarding processors with isolate-grade capabilities and third-party verification infrastructure.
For Market Incumbents: Acquire membrane filtration engineering talent pools to anchor technical service differentiation as plant protein substitution threatens commodity-tier margins. Expand ultrafiltration capacity in the Guelph-Waterloo corridor to capture sports nutrition contract consolidation. Secure backward integration into fluid milk quotas under provincial dairy board negotiations to defend raw material throughput. For New Entrants and Emerging Players: Launch via regional distribution hubs serving Atlantic Canada maritime food manufacturers, where absent local processing infrastructure creates whitespace for consolidated procurement contracts. Target medical nutrition applications requiring precise amino acid profiling that hydrolyzed whey proteins deliver. Emphasize sustainable packaging compliance with Quebec extended producer responsibility regulations as a go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier toll processors facing absorption into integrated networks, offering consolidation plays for buyers with captive fluid milk access. Long-term viability favors processors with membrane filtration capacity and Health Canada Food Directorate compliance infrastructure. Watch Canadian Dairy Commission quota policy negotiations as the signal for raw material availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Captures premium isolate demand from Ontario sports nutrition manufacturers upgrading to rapid-absorption hydrolysates. |
| Backward Integration into Dairy Cooperatives | Secures fluid milk quota access under Canadian Dairy Commission framework, sustaining casein production margins. |
| Third-Party Verification Investment | Meets tightened Health Canada Food Directorate amino acid profile declaration requirements for protein isolate labeling. |
| Regional Distribution Hub Establishment | Serves Nova Scotia and New Brunswick food manufacturers lacking local dairy processing infrastructure. |
| Sustainable Packaging Transition | Aligns with Quebec extended producer responsibility regulations incentivizing reusable tote systems over single-use bags. |
Study Parameters
Direct dialogue with dairy cooperative procurement managers, sports nutrition brand formulators, membrane filtration equipment suppliers, and Health Canada regulatory affairs specialists grounded the qualitative foundation, cross-referenced against Canadian Dairy Commission quota records, CFIA enforcement disclosures, provincial dairy board pricing circulars, and industry trade flow data. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand segmentation across infant formula, sports nutrition, and functional food applications.
Bottom-up modeling anchored the analytical framework, with value projections derived from price-tier assumptions across the analysis window. Segmentation dimensions included protein fraction type, end-use industry, application category, and distribution channel complexity. CAGRs emerged from trend extrapolation of membrane filtration adoption rates, quota policy stability assumptions, and substitution elasticity estimates for plant protein displacement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Canadian Dairy Commission quota reallocation scenarios or accelerated Health Canada novel food notification enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Dairy Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Camel Dairy Market
Dairy Products
Dairy Carton Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Africa Yogurt Market
Dairy Products
Goat Milk Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
North America Cheese Market
Dairy Products
North America Casein and Caseinate Market