
 Japan Casein Market | 2026-2036
Japan Casein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Casein Market Intelligence
Dairy protein processing expertise is redrawing competitive boundaries in the Japanese casein sector. Lacto Japan Co., Ltd. leverages its domestic sourcing network to secure raw milk supply contracts across Hokkaido. Meiji Holdings Co., Ltd. anchors its position through integrated dairy operations spanning farm to ingredient processing. Morinaga Milk Industry Co., Ltd. specializes in functional protein fractions for medical and nutritional applications.
Casein denotes a family of phosphoproteins precipitated from skim milk through acidification or enzymatic treatment, typically containing 80% protein on a dry basis with bound calcium and phosphorus micelle structures. The material functions as an emulsifier, texture modifier, and slow-release amino acid source in formulated foods and clinical nutrition. Rennet casein commands premium positioning in cheese analog and industrial adhesive applications due to superior melt characteristics. Caseinates dominate volume flows into sports nutrition and infant formula sectors where solubility and digestibility specifications drive procurement. Acid casein maintains stable demand from wood adhesive and paper coating industries where moisture resistance properties outweigh protein functionality metrics.
METI oversees food ingredient manufacturing standards under Japan's Food Sanitation Act, while JIS standards govern industrial-grade casein specifications for non-food applications. PMDA scrutiny of functional food claims shapes how nutraceutical companies formulate and market casein-derived bioactive peptides. Stakeholders must track evolving standards for protein content labeling and allergen declaration protocols as export-oriented dairy ingredient production expands.
Market Dynamics
METI's functional food ingredient standardization initiative is compressing quality variance and forcing processors to upgrade filtration and fractionation capabilities. Hokkaido's raw milk sourcing concentration gives integrated dairy groups structural advantages over standalone ingredient specialists.
Growth Catalysts
- Sports Nutrition Expansion:Protein powder manufacturers in Tokyo's food technology cluster are expanding caseinate procurement for slow-release amino acid formulations. Volume commitments from fitness-focused consumer brands are stabilizing processor capacity utilization.
- Functional Food Claims Pathway:PMDA's evolving framework for bioactive peptide health claims is opening regulatory space for casein-derived ingredients in nutraceutical applications. Medical nutrition developers are filing dossiers for muscle maintenance and satiety positioning.
- Acid Casein Industrial Demand:Wood adhesive and paper coating sectors in the Kanto region maintain steady offtake for moisture-resistant industrial-grade material. JIS specification compliance creates captive demand for domestic acid casein production.
Market Restraints
- Raw Milk Supply Concentration:Hokkaido dairy cooperatives control the majority of skim milk feedstock, creating bottleneck risk for non-integrated processors. Spot milk pricing volatility compresses margin predictability for standalone casein manufacturers.
- Rennet Casein Import Dependency:Premium cheese analog applications rely on imported rennet casein due to limited domestic enzymatic precipitation capacity. Currency exposure and shipping lead times constrain formulation flexibility for industrial users.
- Plant Protein Substitution:Pea and rice protein isolates are capturing share in mass-market sports nutrition where solubility specifications are less stringent. Price-sensitive formulators are blending down casein content in flavored ready-to-drink products.
Strategic Opportunities
- Medical Nutrition Specialization:Aging demographics in the Kansai region are expanding clinical nutrition demand for micellar casein in dysphagia and sarcopenia applications. Hospital and long-term care procurement channels offer premium pricing for pharmaceutical-grade material.
- Export-Oriented Production:Southeast Asian infant formula manufacturers are qualifying Japanese caseinate suppliers for clean-label positioning. METI quality certification provides competitive differentiation against European and Oceania alternatives in ASEAN markets.
- Bioactive Peptide Fractionation:Enzymatic hydrolysis technology convergence with chromatographic separation is enabling production of ACE-inhibitory and opioid-like peptide fractions. Functional food developers in the Nagoya corridor are sourcing these for blood pressure management positioning.
Industry Challenges
- Specialized Technician Scarcity:Dairy protein fractionation requires expertise in membrane filtration and spray drying parameter optimization. Hokkaido technical colleges are not graduating sufficient process engineers to staff capacity expansions.
- Allergen Labeling Complexity:METI's evolving declaration protocols for milk-derived ingredients in compound foods are extending product reformulation timelines. Export-bound manufacturers must reconcile Japanese and destination-market allergen thresholds.
- Legacy Equipment Retrofit Costs:Acid casein plants built for industrial adhesive markets require capital-intensive upgrades to meet food-grade membrane filtration standards. Smaller processors face binary choices between exit and major reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Casein Market |
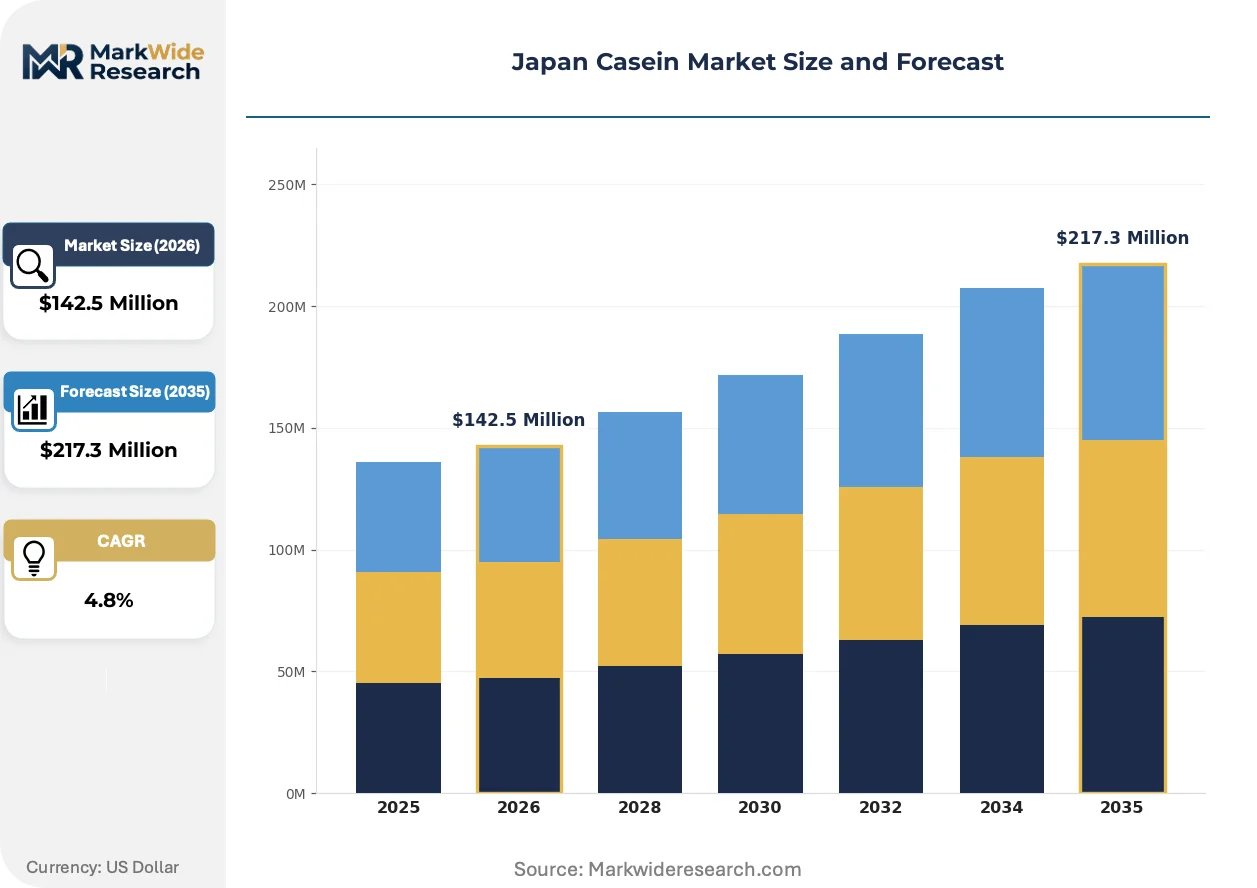
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
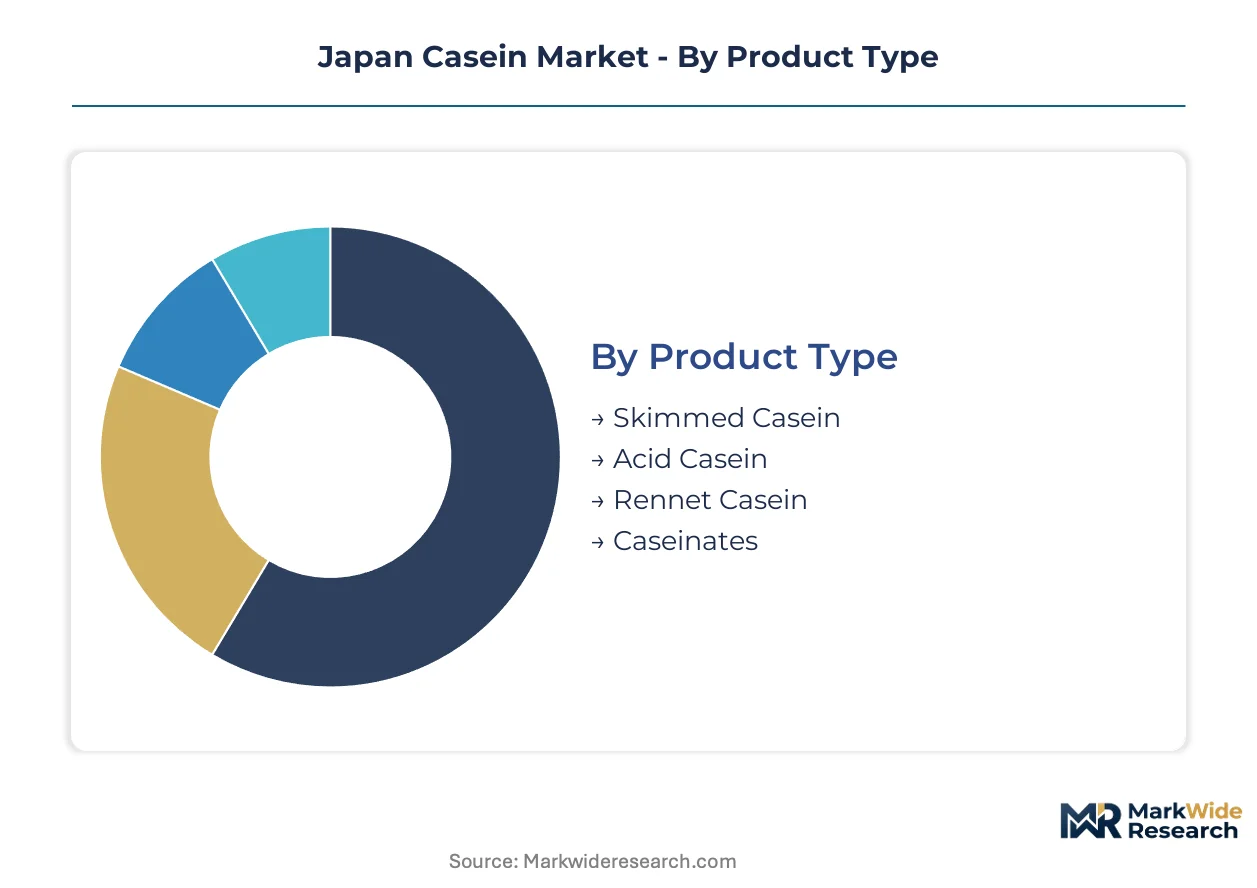
| Segmentation | Product Type: Skimmed Casein, Acid Casein, Rennet Casein, Caseinates End User: Dairy Manufacturers, Food Industry, Nutraceutical Companies, Pharmaceuticals Application: Food Products, Dietary Supplements, Infant Formulas, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA (Sigma-Aldrich), Lacto Japan Co., Ltd., Royal FrieslandCampina N.V., Arla Foods amba, Fonterra Co-operative Group Limited, Meiji Holdings Co., Ltd., Morinaga Milk Industry Co., Ltd., Glanbia PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Casein Market Strategic Shifts & Innovations
Membrane filtration advances and enzymatic modification techniques are expanding the functional property range of Japanese casein ingredients. Regulatory clarity on health claims is accelerating premium product development.
Microfiltration and ultrafiltration systems optimized for phosphocasein micelle preservation are displacing traditional isoelectric precipitation in high-value nutritional applications. Infant formula manufacturers in the Kanto cluster are adopting ceramic membrane configurations to achieve superior protein integrity and reduced mineral ash content. This technology shift is compressing the addressable market for conventional acid casein in premium nutritional segments.
METI's 2023 functional food ingredient notification system revision is tightening evidentiary requirements for protein-derived bioactive claims. Casein hydrolysate manufacturers must now submit peptide sequence identification and clinical endpoint data for satiety or muscle protein synthesis positioning. The regulatory friction is favoring larger processors with dedicated regulatory affairs capacity over mid-tier competitors.
Direct procurement relationships between sports nutrition brands and Hokkaido dairy processors are shortening traditional trading house intermediation. Volume commitments with quality premiums attached are replacing spot market transactions for micellar casein isolate. The channel restructuring is most visible in Tokyo's functional food startup ecosystem, where venture-backed brands negotiate exclusive supply agreements for differentiated positioning.
Japan Casein Market Segmentation
Casein procurement patterns in Japan diverge sharply across end-use specifications, with pharmaceutical-grade material commanding fundamentally different channel structures than industrial acid casein. Understanding these segment boundaries clarifies where margin pools concentrate and which technical capabilities determine supplier viability.
Product Type:
Channel flows split between direct B2B contracting for nutritional grades and trading-house intermediation for industrial variants, with membrane filtration capability becoming the decisive supplier qualification.
- Skimmed Casein:Derived from isoelectric precipitation of skim milk with minimal fat retention, typically standardized to 90% protein dry basis. Tokyo's infant formula cluster sources this through direct processor contracts with Hokkaido dairies, bypassing traditional distributors to secure lot traceability for export qualification.
- Acid Casein:Precipitated via mineral acid addition to skim milk, forming insoluble curd with retained calcium phosphate structure. Kanto wood adhesive and paper coating manufacturers procure through established trading houses, with JIS K-5908 compliance filtering supplier eligibility regardless of price positioning.
- Rennet Casein:Enzymatic coagulation produces superior melt characteristics for cheese analog applications. Limited domestic precipitation capacity forces reliance on European imports, with currency-hedged annual contracts dominating procurement.
- Caseinates:Soluble salts formed by neutralizing acid casein with sodium or calcium hydroxide. Sports nutrition brands in Osaka and Nagoya corridors negotiate exclusive supply agreements for micellar isolate grades, attaching quality premiums to volume commitments.
Acid casein dominates installed base by volume. Caseinates are where expansion concentrates.
End User:
Customer technical sophistication creates tiered service requirements, with pharmaceutical and nutraceutical buyers demanding peptide mapping documentation that dairy manufacturers rarely require.
- Dairy Manufacturers:Integrated processors like Meiji Holdings consume casein internally for cheese and fermented product lines, with captive supply eliminating external procurement for major groups. Standalone cheese analog producers represent the addressable third-party demand.
- Food Industry:Processed meat and bakery formulators in the Chubu region utilize casein for emulsion stability and water binding. Functional property specifications vary by application, with lower protein grades acceptable in cost-competitive segments.
- Nutraceutical Companies:Firms developing functional food positioning under PMDA's evolving notification system require hydrolysate peptide characterization. METI's tightened evidentiary standards favor suppliers with dedicated regulatory affairs capacity.
- Pharmaceuticals:Clinical nutrition developers in Kansi's hospital supply chain procure pharmaceutical-grade micellar casein for dysphagia and sarcopenia applications. GMP certification and batch release documentation command substantial price premiums over food-grade material.
Food industry offtake represents the volume anchor. Pharmaceuticals are climbing the fastest.
Application:
Performance specifications fragment the addressable market, with infant formula protein integrity requirements incompatible with industrial adhesive functionality metrics.
- Food Products:Cheese analogs, coffee whiteners, and processed meat applications utilize casein for emulsification and texture modification. Kanto food technology startups are reformulating with reduced casein content where plant protein solubility permits partial substitution.
- Dietary Supplements:Capsule and tablet formulators source calcium caseinate for mineral fortification positioning. Direct-to-consumer brands in Tokyo's venture-backed ecosystem are consolidating procurement through Hokkaido processor relationships.
- Infant Formulas:Micellar casein isolate demand concentrates among export-oriented manufacturers qualifying for ASEAN clean-label positioning. Ceramic membrane filtration adoption is displacing conventional acid casein in premium nutritional segments.
- Sports Nutrition:Slow-release amino acid positioning drives caseinate demand from protein powder manufacturers. Fitness-focused consumer brands are stabilizing processor capacity utilization through annual volume commitments.
Food products retain the broadest installed base. Sports nutrition is gaining share fastest.
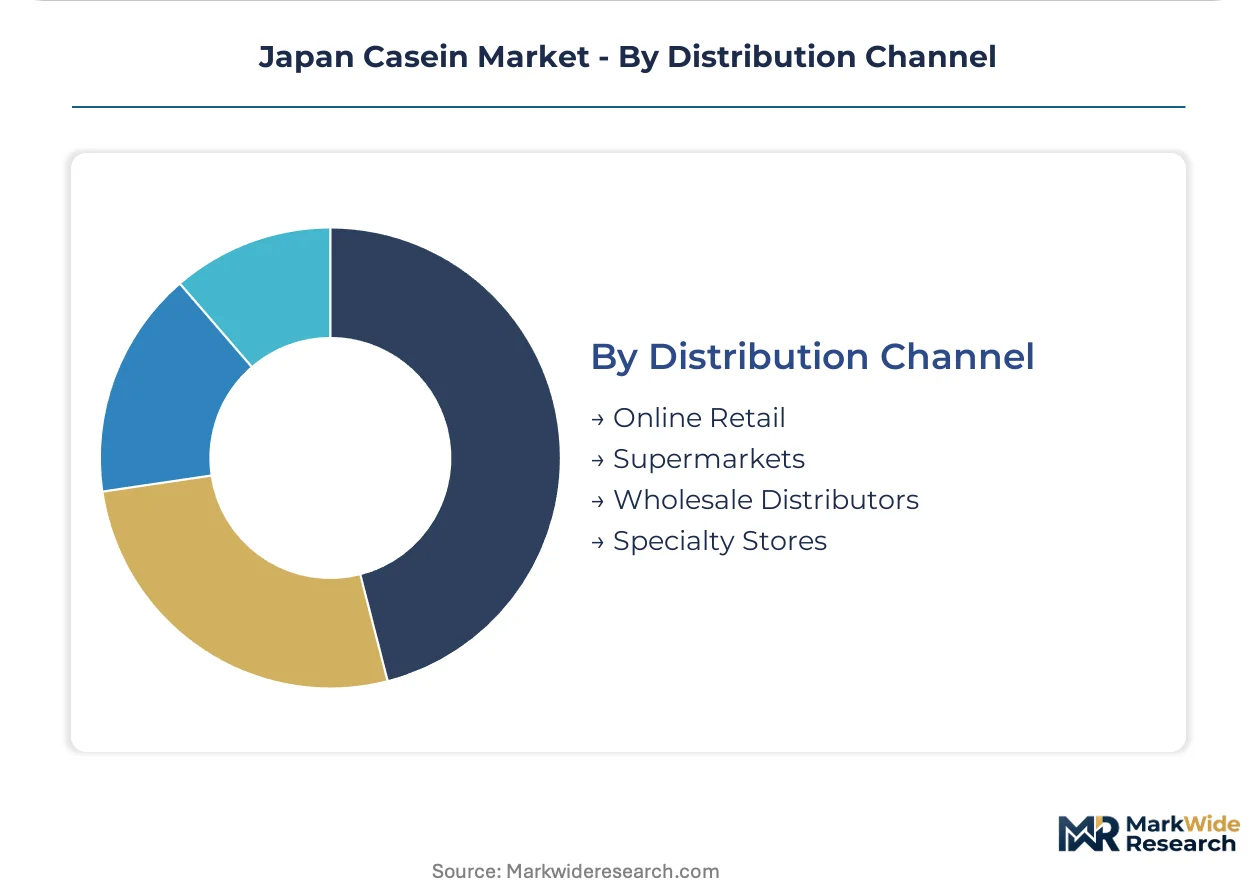
Distribution Channel:
Channel restructuring is compressing trading house margins as direct procurement relationships proliferate for high-specification material.
- Online Retail:Bulk ingredient platforms serve small-scale formulators and research institutions with minimum order quantities below traditional distributor thresholds. Quality verification remains buyer-managed.
- Supermarkets:Consumer-packaged casein products for home baking and specialty diets occupy niche shelf space. Retail penetration is limited by low household recognition of casein as a distinct ingredient category.
- Wholesale Distributors:Trading houses including Mitsubishi Corporation and Sojitz handle industrial acid casein flows and import-dependent rennet casein. Logistics integration with port infrastructure in Yokohama and Kobe maintains their relevance for bulk material.
- Specialty Stores:Sports nutrition retailers in Tokyo's Shibuya and Osaka's Umeda districts stock branded casein protein powders. These outlets function as marketing channels rather than significant volume drivers for bulk ingredient suppliers.
Wholesale distributors anchor current volume flows. Online retail is where channel experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
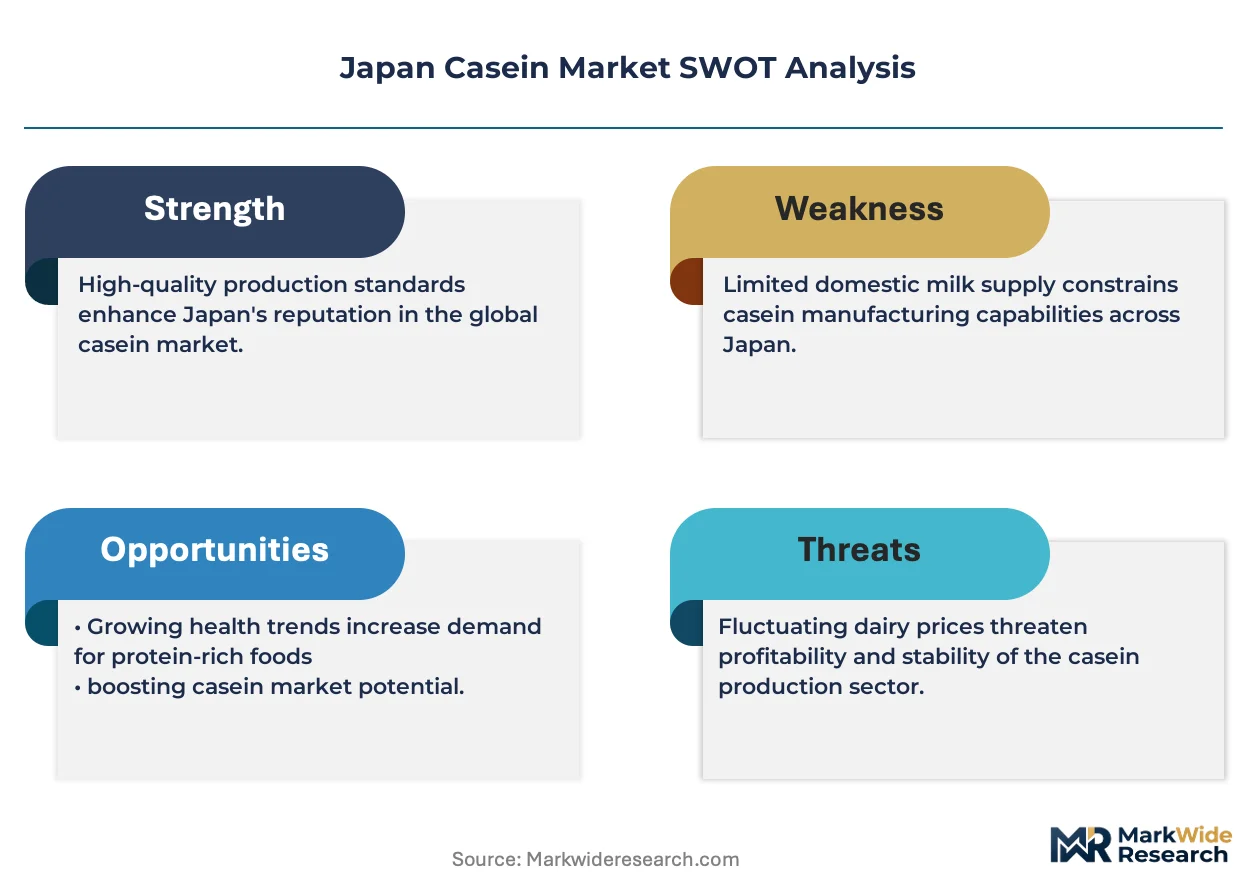
METI anchors regulatory oversight across Japan's casein processing network, with regional demand clustering around three industrial corridors where dairy infrastructure and food technology R&D concentrate.
Kanto/Tokyo
Sports nutrition manufacturers and infant formula developers drive premium caseinate procurement in the capital region. METI's functional food ingredient standardization initiative reshapes quality benchmarks for processors supplying this cluster. Tokyo's food technology startup ecosystem negotiates direct supply agreements with Hokkaido dairies, bypassing traditional trading house channels.
Kansai/Osaka
Aging demographics expand clinical nutrition demand for pharmaceutical-grade micellar casein in dysphagia and sarcopenia applications. PMDA scrutiny of functional food claims shapes how regional nutraceutical companies formulate bioactive peptide products. Hospital and long-term care procurement channels in Osaka and Kyoto command premium pricing for GMP-certified material.
Hokkaido
Raw milk supply concentration gives integrated dairy groups structural procurement advantages over standalone ingredient specialists. JIS standards govern industrial-grade casein specifications for regional wood adhesive and paper coating applications. Technical colleges in Sapporo and Asahikawa struggle to graduate sufficient process engineers for membrane filtration capacity expansions.
Chubu/Nagoya
Enzymatic hydrolysis technology convergence with chromatographic separation enables bioactive peptide production for blood pressure management positioning. Functional food developers in the Nagoya corridor source ACE-inhibitory and opioid-like peptide fractions from qualified processors. Regional trading houses maintain relevance for bulk acid casein flows to industrial users.
Kyushu
Export-oriented infant formula manufacturers qualify suppliers for Southeast Asian clean-label positioning. METI quality certification provides competitive differentiation against European and Oceania alternatives in ASEAN markets. Fukuoka's logistics infrastructure supports port consolidation for caseinate shipments to regional formula producers.
Japan Casein Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Japan's casein sector. Integrated dairy conglomerates with captive raw milk supply dominate high-specification nutritional segments, while specialized ingredient processors compete on fractionation capabilities and regulatory dossier expertise. Three archetypes define competitive positioning: backward-integrated dairy majors controlling Hokkaido milk supply, standalone protein specialists with membrane filtration assets, and trading houses managing import-dependent rennet casein flows. Capacity expansion and direct procurement relationship-building constitute the dominant competitive moves, with processors securing volume commitments from sports nutrition brands and infant formula exporters.
Among domestic dairy-integrated operators, Meiji Holdings Co., Ltd. and Morinaga Milk Industry Co., Ltd. occupy positions exemplifying captive supply chain control from farm through ingredient processing. Lacto Japan Co., Ltd. represents the specialist archetype, with its company name indicating dedicated dairy protein focus and domestic sourcing network configuration. These three entities anchor the competitive structure, with their respective positions reflecting divergent strategic bets on vertical integration depth versus specialized fractionation capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA (Sigma-Aldrich) |
| Lacto Japan Co., Ltd. |
| Royal FrieslandCampina N.V. |
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Meiji Holdings Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Glanbia PLC |
| Others |
Cost & Logistics Intelligence
Pea and rice protein substitution in mass-market sports nutrition is simultaneously redrawing supply geography toward Southeast Asian plant protein hubs and compressing casein pricing premiums in Japan's standard-tier segments. This displacement dynamic forces domestic processors to defend position through quality certification investments while trading houses absorb currency exposure on European rennet casein imports.
Pricing Analysis
Price spreads between pharmaceutical-grade micellar casein and industrial acid casein span multiple certification tiers across Japan's regional procurement clusters. Three-tier pricing structure separates GMP-certified pharmaceutical material from food-grade caseinates and JIS-compliant industrial grades, with METI's functional food standardization tightening evidentiary requirements at the premium boundary. Pricing pressure stems from plant protein blending in flavored ready-to-drink formulations, eroding volume commitments at the standard tier. Food industry formulators exhibit highest price sensitivity, while clinical nutrition developers accept substantial premiums for batch release documentation.
Supply Chain Analysis
Hokkaido's raw milk concentration creates a chokepoint where dairy cooperatives control skim milk feedstock access for non-integrated processors. Domestic supply draws from Hokkaido integrated dairies and European rennet casein imports, with sodium hydroxide and calcium hydroxide neutralization agents sourced from Chubu chemical manufacturers. Single-source vulnerability concentrates in Hokkaido dairy cooperative supply contracts, exposing standalone processors to spot milk pricing volatility. Distribution runs through direct B2B contracting for nutritional grades and trading-house intermediation for industrial acid casein flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as plant protein isolates capture share in solubility-tolerant applications, forcing incumbents to differentiate through bioactive peptide fractionation capabilities and regulatory dossier depth.
For Market Incumbents: Fortify captive raw milk supply through exclusive Hokkaido cooperative contracts and deepen membrane filtration capacity for micellar isolate production. METI's tightened health claim evidentiary requirements favor processors with dedicated regulatory affairs capacity over mid-tier competitors lacking peptide characterization infrastructure. For New Entrants and Emerging Players: Anchor in bioactive peptide fractionation for blood pressure management positioning, where enzymatic hydrolysis technology convergence creates white space outside integrated dairy majors' core competence. Nagoya corridor functional food developers represent the most penetrable buyer segment for ACE-inhibitory peptide sourcing, with direct technical partnership offering faster qualification than trading-house channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed standalone protein specialists possessing membrane filtration assets but lacking backward integration into Hokkaido milk supply. Long-term viability hinges on securing captive raw material access or exclusive offtake agreements with export-oriented infant formula manufacturers qualifying for ASEAN clean-label positioning. Watch PMDA functional food claim approval velocity as inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic microfiltration adoption displaces conventional acid casein in premium infant formula segments. |
| Backward Integration into Hokkaido Milk Supply | Exclusive raw milk contracts eliminate spot pricing volatility and secure lot traceability for export qualification. |
| Bioactive Peptide Regulatory Dossier Investment | PMDA notification system compliance opens positioning for muscle maintenance and satiety claims. |
| Direct Procurement Relationship Building | Tokyo sports nutrition startups bypass trading houses through volume commitments with quality premiums attached. |
| ASEAN Export Market Qualification | METI quality certification differentiates Japanese caseinate against European and Oceania alternatives. |
Research Approach
Initial hypotheses were tested against primary input from dairy protein processing engineers, sports nutrition procurement managers, infant formula regulatory affairs leads, and METI standards officials, then refined through secondary validation against JIS specification documents, PMDA functional food notification filings, Hokkaido dairy cooperative supply reports, and customs trade data for rennet casein imports. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Variance decomposition across product type, end user sophistication tier, application performance specification, and distribution channel structure anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro dairy consumption trends and functional food regulatory velocity. Forecast inputs incorporated membrane filtration technology adoption curves and plant protein substitution elasticity in mass-market sports nutrition.
Decision-makers should treat outputs as directional under assumptions of stable METI standardization timelines and continued Hokkaido dairy cooperative supply concentration; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA bioactive peptide claim approval criteria and ASEAN import qualification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Butter Concentrate Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Lactose Market
Dairy Products
Dairy Foods Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
North America Dairy Market
Dairy Products
Dairy Protein Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Organic Cheese Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Japan Dairy Market
Dairy Products
Sour Cream Market
Dairy Products
North America A2 Milk Market