
 Global Fresh Milk Market | 2026-2036
Global Fresh Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fresh Milk Market Analysis
Food service demand is rebalancing toward cafés and quick-service restaurants as post-pandemic consumption patterns solidify. Lactalis S.A. sustains manufacturing scale across European dairy clusters. Fonterra Co-operative Group Limited anchors Oceania supply through cooperative farmer networks. Inner Mongolia Yili Industrial Group Co., Ltd. dominates domestic distribution depth in China.
Fresh milk denotes raw or minimally heat-treated bovine secretions standardized to specific fat content, typically processed through pasteurization at 72°C for 15 seconds to eliminate pathogens while preserving sensory profile. The product serves as a foundational ingredient in direct consumption, beverage formulation, and culinary preparation across commercial and residential settings. Whole milk occupies the largest volume share among product type segments, though flavored milk generates disproportionate margin contribution through value-added positioning. Supermarkets control the dominant share of distribution channel flows, yet online retail registers the fastest expansion as cold-chain last-mile capabilities mature.
EU Green Deal targets and F-Gas Regulation phase-down schedules compel processor investment in low-global-warming-potential refrigeration systems across member states. FDA Grade A Pasteurized Milk Ordinance standards govern interstate commerce specifications and safety protocols in the United States. India's FSSAI fortification mandates and BIS quality certifications shape product composition and labeling requirements for organized sector participants. Stakeholders must monitor regulatory divergence between carbon-accounting jurisdictions and assess cold-chain capital allocation against emerging channel mix trajectories.
Market Dynamics
EU Green Deal carbon-accounting mandates and F-Gas Regulation phase-down schedules are forcing processors to redirect capital toward low-global-warming-potential refrigeration systems, compressing margins for operators with aging cold-chain infrastructure.
Growth Catalysts
- Urban household penetration:India's organized retail milk continues deepening in metropolitan corridors as cold-chain reliability improves and consumer trust consolidates around branded supply.
- F-Gas Regulation compliance:European processors investing in natural refrigerant systems capture operational cost advantages once retrofit cycles complete and energy efficiency scales.
- Food service recovery:Out-of-home consumption patterns solidify across cafés and quick-service restaurants, absorbing larger standardized volumes from dairy processors.
Market Restraints
- Feed input volatility:Fodder cost fluctuations compress processor margins unpredictably, particularly for cooperatives without captive grain sourcing.
- Supply concentration risk:Oceania supply anchors through cooperative farmer networks create geographic vulnerability to climate-induced production swings.
- Refrigerant transition friction:EU F-Gas Regulation retrofit timelines strain capital allocation for mid-scale operators with limited balance sheet flexibility.
Strategic Opportunities
- Last-mile cold-chain maturation:Online retail expansion enables direct-to-consumer subscription models where temperature-controlled logistics infrastructure reaches residential zones.
- FSSAI fortification mandates:India's micronutrient enrichment requirements create premium positioning for organized sector participants with laboratory certification capabilities.
- ESG-linked procurement:Carbon-accounting convergence between EU Green Deal standards and buyer sustainability scorecards rewards early refrigerant transition investments.
Industry Challenges
- Retrofit capex intensity:Low-global-warming-potential refrigeration system deployment demands substantial upfront capital, straining processors with fragmented facility footprints.
- Cross-jurisdictional compliance:Divergence between FDA Grade A Pasteurized Milk Ordinance standards and EU hygiene requirements complicates export-oriented quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Milk Market |
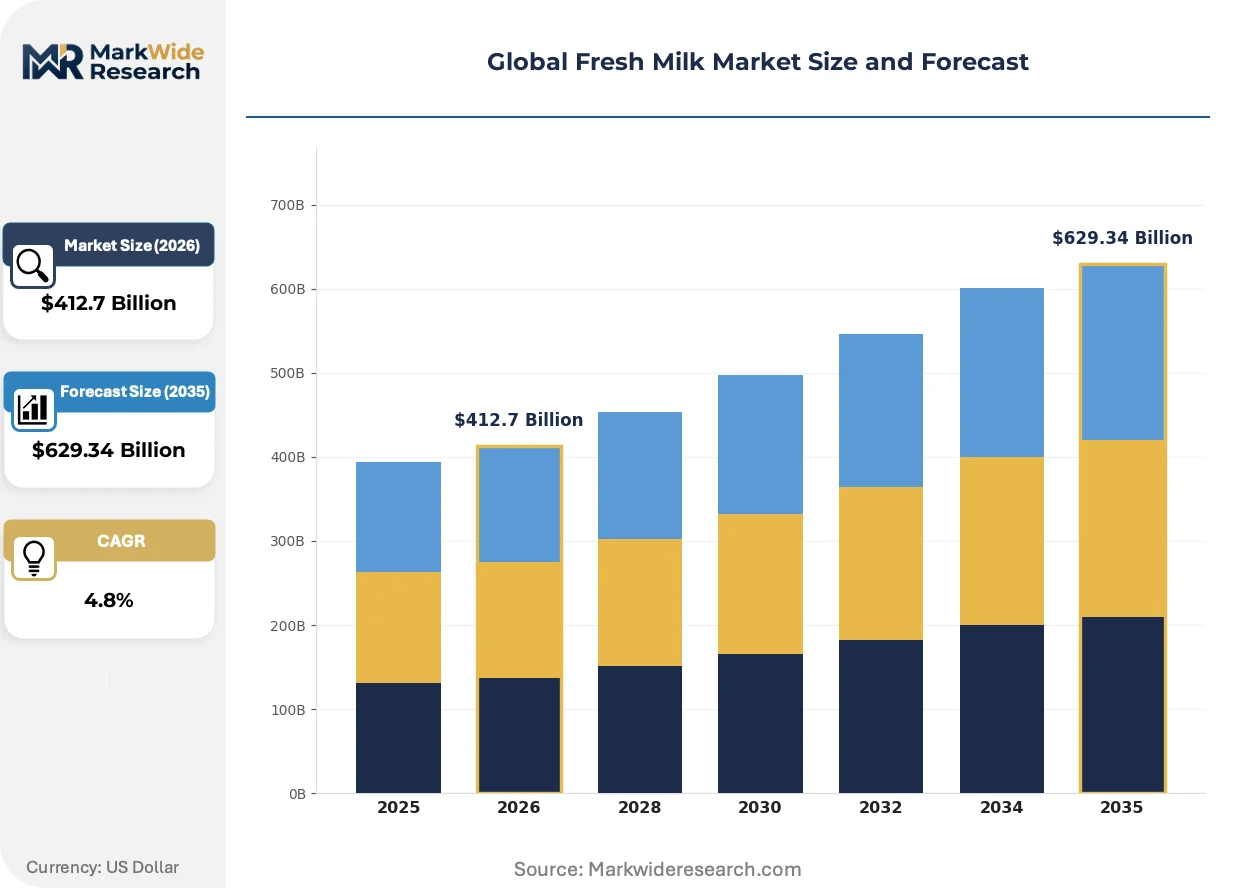
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Semi-Skimmed Milk, Flavored Milk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Direct Sales Packaging Type: Cartons, Plastic Bottles, Glass Bottles, Pouches End User: Households, Restaurants, Cafés, Food Service |
| Companies Covered | Lactalis S.A., Nestlé S.A., Dairy Farmers of America, Inc., Danone S.A., Inner Mongolia Yili Industrial Group Co., Ltd., Fonterra Co-operative Group Limited, Arla Foods amba, Koninklijke FrieslandCampina N.V., China Mengniu Dairy Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Milk Market Emerging Trajectories
Fresh milk processing is undergoing systematic cold-chain modernization as regulatory pressure intersects with channel diversification, reshaping where and how minimally heat-treated dairy reaches end consumers.
Continuous flow pasteurization systems equipped with real-time microbiological sensors are rewriting safety assurance protocols across high-volume processing lines. European dairy clusters deploy these units to reduce thermal degradation while maintaining pathogen elimination standards. The technology is rewriting competitive differentiation between processors with automated traceability and those relying on batch-based quality verification.
EU F-Gas Regulation phase-down schedules mandate refrigerant transitions across member-state cold-chain infrastructure by specific reduction milestones. Industrial consequence includes accelerated obsolescence of hydrofluorocarbon-dependent equipment and redirected investment toward ammonia and CO2-based systems. Processors in Germany and France face the most compressed retrofit timelines as national transposition deadlines precede broader EU harmonization.
Direct-to-subscriber delivery models are displacing traditional supermarket dominance among urban households with reliable cold-chain access. Quick-commerce platforms and specialized dairy subscription services capture morning-consumption routines through guaranteed pre-breakfast delivery windows. This behavioral pivot is most visible in Chinese tier-one cities and Indian metropolitan corridors where smartphone penetration and logistics density converge.
Global Fresh Milk Market Segmentation
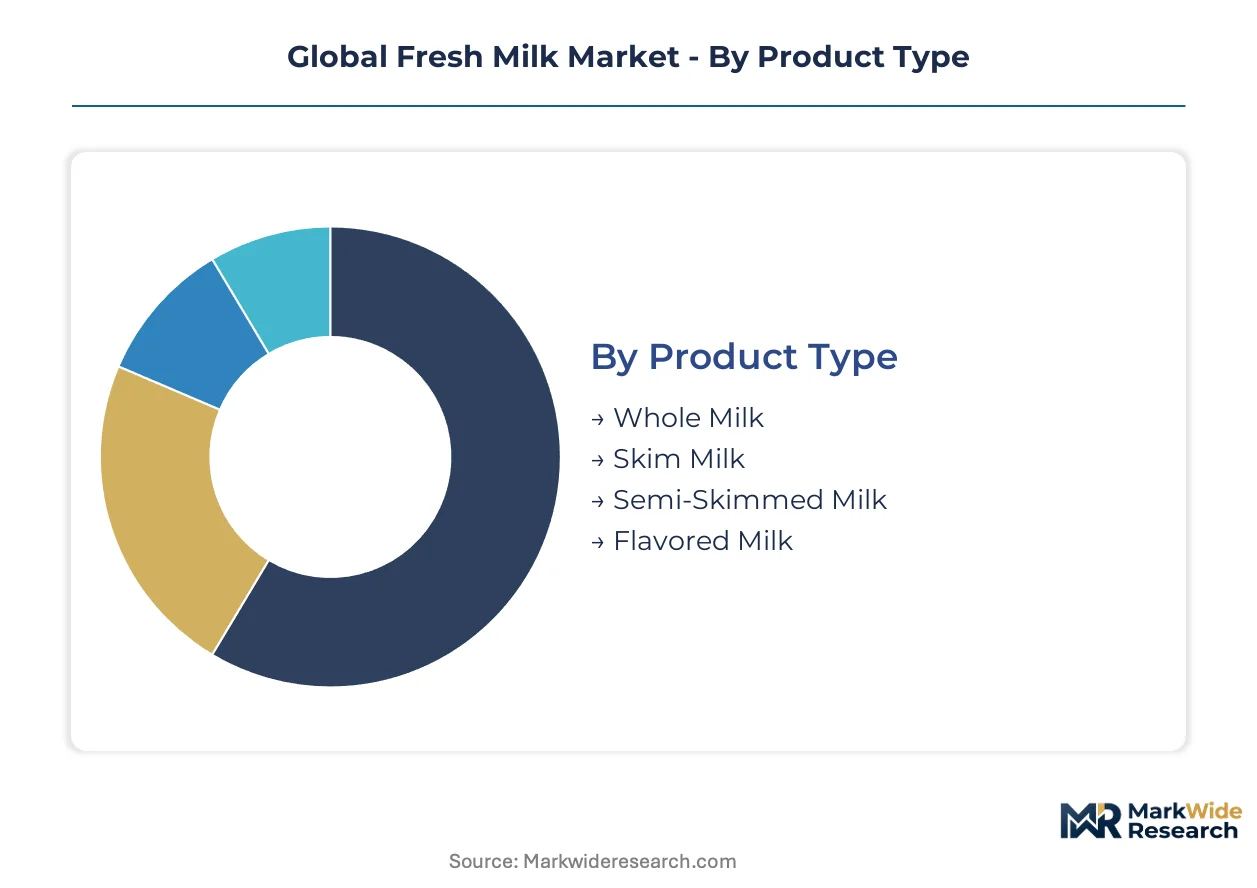
Fresh milk segmentation reveals how regulatory compliance burdens and channel economics fragment procurement patterns across product formulations. Each dimension carries distinct certification requirements that reshape competitive positioning for processors and distributors.
Product Type:
Whole milk and flavored variants face divergent fortification mandates under FSSAI, FDA, and EU hygiene regulations, while skim and semi-skimmed categories navigate fat-content labeling standards across jurisdictions.
- Whole Milk:Unstandardized bovine secretion retaining natural butterfat content, typically 3.25-4% fat by weight. Demand concentrates in Indian metropolitan corridors where branded whole milk commands household trust through cold-chain reliability improvements. FSSAI fortification mandates apply variably based on regional micronutrient deficiency profiles.
- Flavored Milk:Value-added formulation incorporating cocoa, strawberry, or vanilla flavoring systems with elevated sugar content. Cafés and quick-service restaurants in Chinese tier-one cities absorb disproportionate volumes as out-of-home consumption solidifies. FDA labeling requirements govern added-sugar disclosure thresholds for interstate commerce.
- Skim Milk:Centrifugally separated product with fat content below 0.5%, positioned for health-conscious residential consumption.
- Semi-Skimmed Milk:Intermediate fat standardization, typically 1.5-2% butterfat, dominating European retail shelves under EU quality certifications.
Leading the category by volume: Whole Milk. Growing fastest: Flavored Milk.
Distribution Channel:
Channel selection dictates cold-chain capital intensity, with direct-to-consumer models requiring last-mile temperature control investments that supermarkets amortize across broader SKU ranges.
- Supermarkets:Temperature-controlled retail environments with centralized procurement contracts. European dairy clusters and Indian organized retail chains leverage scale economics to compress unit logistics costs. EU F-Gas Regulation compliance costs concentrate in this channel's refrigeration infrastructure.
- Online Retail:Direct-to-subscriber platforms with guaranteed delivery windows. Chinese quick-commerce operators and Indian dairy subscription services capture morning-consumption routines through smartphone-enabled logistics density. Cold-chain last-mile capabilities remain the binding constraint.
- Convenience Stores:Proximity-driven impulse purchase locations with limited refrigeration capacity.
- Direct Sales:Cooperative farmer networks and dairy-owned delivery routes bypassing retail intermediation.
Highest volume flows through: Supermarkets. Steepest expansion trajectory: Online Retail.
Packaging Type:
Material selection intersects with shelf-life extension requirements and sustainability procurement scorecards, particularly under EU Green Deal circular economy targets.
- Cartons:Multi-layer laminated board with aluminum barrier protection, dominant in European retail due to recyclability credentials under extended producer responsibility schemes. Lactalis manufacturing facilities deploy high-speed filling lines optimized for this format. Carbon-accounting convergence rewards carton selection in ESG-linked procurement.
- Plastic Bottles:HDPE or PET formats with resealable closures, prevalent in North American retail under FDA food-contact substance regulations. Lightweighting initiatives reduce transport emissions but face microplastic scrutiny.
- Glass Bottles:Returnable deposit systems with premium positioning in specialty channels.
- Pouches:Flexible film formats with reduced material intensity, expanding in Indian price-sensitive segments.
Dominant by throughput: Cartons. Gaining share fastest: Plastic Bottles.
End User:
Demand concentration varies sharply between residential consumption with quality-certification sensitivity and food service procurement with volume standardization requirements.
- Households:Residential consumption units purchasing through retail or subscription channels. Indian urban households demonstrate deepening organized retail penetration as cold-chain reliability consolidates consumer trust around branded supply. FSSAI fortification mandates shape product composition for this segment.
- Food Service:Aggregated institutional procurement including restaurants, cafés, and quick-service operators. Out-of-home consumption recovery absorbs larger standardized volumes from processors with continuous flow pasteurization capabilities. FDA Grade A standards govern specifications for US interstate supply.
- Restaurants:Full-service dining establishments with ingredient-grade milk requirements.
- Cafés:Beverage-focused operators with foaming-performance specifications for espresso-based drinks.
Largest volume absorption: Households. Expanding most quickly: Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes the largest volumes of fresh milk worldwide, yet production surpluses from New Zealand and European dairy clusters supply deficit markets across Asia and the Middle East. This geographic mismatch between output centers and consumption hubs defines cold-chain investment priorities and trade flow patterns.
India
Urban households in Mumbai, Delhi-NCR, and Bangalore deepen organized retail penetration as branded cold-chain reliability consolidates consumer trust. FSSAI fortification mandates for Vitamin A and D reshape product composition requirements for organized sector participants. The Gujarat and Maharashtra dairy belts anchor cooperative processing capacity expansion.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen absorb disproportionate flavored milk volumes as out-of-home consumption solidifies in cafés and quick-service restaurants. SAMR food safety regulations govern pasteurization standards and labeling requirements for domestic and imported supply. Inner Mongolia maintains concentrated raw milk production infrastructure serving coastal processing demand.
United States
Midwestern dairy clusters across Wisconsin and California supply fluid milk requirements for food service recovery and retail channel replenishment. FDA Grade A Pasteurized Milk Ordinance standards govern interstate commerce specifications and pathogen control protocols. The Northeast corridor experiences processing capacity consolidation as smaller cooperatives face feed cost volatility pressures.
Germany
Bavarian and Lower Saxony dairy processors navigate compressed F-Gas Regulation retrofit timelines for cold-chain infrastructure. EU Green Deal carbon-accounting mandates redirect capital toward ammonia and CO2-based refrigeration systems. The Münsterland cluster sustains high-volume manufacturing scale for carton-format export supply.
New Zealand
Cooperative farmer networks across the Waikato and Canterbury regions anchor Oceania supply through seasonal production cycles. Fonterra's processing infrastructure exports standardized volumes to Chinese and Southeast Asian deficit markets. Climate-induced pasture variability creates geographic vulnerability to production swings affecting global commodity pricing.
Global Fresh Milk Market Vendor Landscape
Top-tier vendors anchor cooperative and multinational scale, while regional specialists and private-label operators occupy fragmented mid-market positions. The structure concentrates processing capacity among dairy cooperatives with captive farmer supply and publicly traded conglomerates with diversified beverage portfolios. Three archetypes dominate: cooperative-owned processors with backward-integrated milk supply, multinational CPG conglomerates with cross-category distribution leverage, and state-affiliated dairy groups with protected domestic channel access. Competitive moves center on cold-chain infrastructure retrofit compliance and direct-to-consumer subscription platform deployment.
Among cooperative-structured processors, Fonterra Co-operative Group Limited and Arla Foods amba exemplify farmer-owned governance models with geographic supply concentration. Lactalis S.A. occupies a position within the privately held multinational tier, representing family-controlled scale across European dairy clusters. Inner Mongolia Yili Industrial Group Co., Ltd. anchors the state-affiliated archetype with domestic distribution depth in Chinese metropolitan corridors.
| Leading Market Players |
|---|
| Lactalis S.A. |
| Nestlé S.A. |
| Dairy Farmers of America, Inc. |
| Danone S.A. |
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| Koninklijke FrieslandCampina N.V. |
| China Mengniu Dairy Company Limited |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation retrofit mandates force processors to absorb capital costs for low-global-warming-potential refrigeration systems, compressing margins and redirecting procurement toward suppliers with certified energy-efficient equipment portfolios.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as food service channels demand guaranteed pre-breakfast delivery windows in Chinese tier-one cities and Indian metropolitan corridors. Three-tier pricing structure across premium, standard, and economy levels separates branded fortified supply from private-label alternatives and unorganized sector offerings. Pricing pressure stems from feed input volatility squeezing cooperative processor margins. Price-sensitive household segments in Indian price-sensitive corridors gravitate toward pouch formats, while premium cafés absorb branded carton premiums without volume negotiation.
Supply Chain Analysis
FDA Grade A certification and EU hygiene standard qualifications gate access to export-oriented procurement contracts, filtering processor eligibility for interstate US commerce and European retail shelf placement. Raw milk supply concentrates in New Zealand, India, and Germany, with seasonal pasture variability in Oceania creating production swing exposure. Feed grain, refrigerant gases, and laminated packaging board constitute critical input dependencies. Single-source vulnerability runs through cooperative farmer network concentration in the Waikato region. Distribution runs through supermarket centralized procurement with online retail last-mile capabilities maturing fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain infrastructure retrofit bottlenecks constrain processing capacity expansion across European dairy clusters, propping pricing power for operators with completed ammonia and CO2-based system deployments.
For Market Incumbents: Anticipate margin compression from feed cost volatility by securing captive grain sourcing through cooperative backward integration or long-term offtake agreements with agricultural suppliers. Defend market position by accelerating F-Gas Regulation compliance ahead of national transposition deadlines to capture operational cost advantages and ESG-linked procurement preference from sustainability-scorecard-driven buyers. For New Entrants and Emerging Players: Quick-commerce platforms represent the most penetrable channel partner type for subscription-based direct-to-consumer models in Indian metropolitan corridors where smartphone penetration and logistics density converge. Target morning-consumption routine capture through guaranteed pre-breakfast delivery windows, leveraging FSSAI fortification mandates as a premium positioning lever against unorganized sector competitors lacking laboratory certification capabilities. For Investors and Strategic Acquirers: The window for entry favors processors with completed natural refrigerant retrofits and established direct-to-subscriber platforms. Long-term viability centers on cold-chain capital efficiency and channel diversification beyond supermarket dependence. Watch for EU Green Deal carbon-accounting convergence with buyer sustainability scorecards as the inflection signal rewarding early refrigerant transition investments.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Retrofit | F-Gas Regulation compliance captures operational cost advantages once ammonia and CO2 systems scale across German and French processing clusters. |
| Direct-to-Consumer Subscription Launch | Smartphone-enabled logistics density in Chinese tier-one cities enables morning-consumption routine capture through guaranteed pre-breakfast delivery windows. |
| FSSAI Fortification Certification | Micronutrient enrichment capabilities create premium positioning for organized sector participants against unorganized competitors in Indian metropolitan corridors. |
| Cooperative Farmer Network Expansion | Backward integration into captive milk supply buffers feed input volatility and secures volume commitments for continuous flow pasteurization lines. |
| Online Retail Channel Partnership | Quick-commerce platform integration addresses last-mile cold-chain constraints and displaces traditional supermarket dominance among urban households. |
Methodological Framework
Independent corroboration across dairy processor executives, cold-chain logistics operators, and food service procurement managers underwrites the qualitative findings, validated against FSSAI fortification compliance records, EU ETS carbon-accounting disclosures, and customs trade flow data. Primary interviews with cooperative farmer network representatives and supermarket category buyers combined with secondary validation from SEC dairy segment filings and national dairy board production statistics. Bottom-up volume triangulation across product type segments reconciled with top-down value estimates from processor revenue disclosures.
Historical reference periods spanning pre-pandemic baseline through post-recovery normalization anchored the forecast window, with CAGR derivation reflecting segment-specific growth trajectories across the projection horizon. Segmentation dimensions modeled include product type formulation, distribution channel structure, packaging material format, and end-user consumption context. Forecast inputs incorporated F-Gas Regulation phase-down schedules, urban household penetration rates in Indian metropolitan corridors, and food service channel recovery velocity.
Caveats apply where EU Green Deal regulatory acceleration or climate-induced pasture variability in Oceania could materially shift the outlook. Forecasts reflect assumptions regarding cold-chain infrastructure investment continuity and consumer trust consolidation around branded supply. A model refresh is warranted upon material change in refrigerant retrofit compliance timelines or direct-to-consumer subscription penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Recombined Milk Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Natural Cheese Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
China Dairy Market
Dairy Products
Dairy Foods Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Smoked Cheese Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Canada Dairy Market
Dairy Products
South America Dairy Protein Market