
 North America Flavored Milk Market | 2026-2036
North America Flavored Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flavored Milk Market Analytics
Canada's dairy processing corridor is rewriting supply dynamics for value-added milk beverages. Fairlife LLC leverages ultrafiltration technology to sustain premium positioning in protein-enriched flavored offerings. Saputo Inc. anchors Canadian production scale while competing with U.S.-based cooperatives for cross-border shelf space. H.P. Hood LLC dominates traditional chocolate milk distribution in New England convenience channels.
Flavored milk denotes pasteurized dairy beverages incorporating sweeteners, natural or artificial flavoring agents, and stabilizers, typically containing between one percent and two percent milk fat with standardized protein content above eight grams per serving. The product serves as a palatable calcium delivery vehicle for younger demographics while offering post-workout recovery functionality for adult consumers. Chocolate formulations occupy the largest volume share across North American retail, though vanilla and caramel variants capture disproportionate margin in specialty coffee shop and foodservice channels. Online retail represents the fastest-growing distribution pathway, driven by subscription-based replenishment models and direct-to-consumer packaging innovations.
The FDA enforces nutrition labeling standards that compel added-sugar disclosure, while USDA school meal guidelines determine institutional eligibility for flavored milk in federal feeding programs. Health Canada and the Canadian Food Inspection Agency administer parallel compositional standards that restrict certain artificial colorants permitted in U.S. formulations. Stakeholders must monitor evolving school nutrition policy debates and sugar taxation proposals at state and provincial levels to anticipate demand shifts between institutional and retail channels.
Market Dynamics
Ultrafiltration technology is compressing traditional pasteurization economics while FDA added-sugar disclosure rules force simultaneous reformulation across institutional and retail channels.
Growth Catalysts
- School Nutrition Programs:USDA school meal guidelines sustain institutional procurement of single-serve flavored milk cartons across the United States, locking in predictable volume for processors serving federal feeding programs.
- Protein Enrichment Technology:Ultrafiltration methods enable protein concentration above eight grams per serving, expanding flavored milk's addressable market into adult post-workout recovery segments.
- Southeast Processing Clusters:Dairy processing concentration in Georgia and Florida supports regional brand expansion through captive supply chains and reduced distribution costs to population centers.
Market Restraints
- Added-Sugar Disclosure Requirements:FDA nutrition labeling standards compel prominent added-sugar disclosure, increasing consumer price sensitivity and pressuring margin on traditional formulations.
- Cross-Border Regulatory Friction:Health Canada's restrictions on artificial colorants permitted in U.S. formulations create product differentiation costs for processors seeking Canadian shelf space.
- Fresh Milk Substitution:Unflavored fresh milk and plant-based alternatives capture health-conscious households, particularly in coastal metropolitan markets with higher disposable incomes.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer packaging innovations enable recurring revenue capture beyond traditional retail, with online retail representing the fastest-growing distribution pathway.
- Specialty Coffee Shop Channels:Vanilla and caramel variants capture disproportionate margin in foodservice applications where premium positioning commands price acceptance.
- State-Level Sugar Taxation Gaps:Absence of unified sugar taxation across U.S. states creates arbitrage opportunities for processors optimizing formulation by destination market.
Industry Challenges
- Dual-Standard Formulation Complexity:Producers must maintain parallel SKUs to satisfy FDA and Health Canada compositional divergences, inflating inventory carrying costs and complicating production scheduling.
- Legacy Equipment Retrofit Requirements:Ultrafiltration adoption demands capital deployment for membrane systems and clean-in-place infrastructure, straining mid-tier processors with constrained balance sheets.
- Institutional Contract Volatility:School nutrition policy debates at state and municipal levels introduce demand uncertainty, forcing processors to hedge procurement commitments between institutional and retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flavored Milk Market |
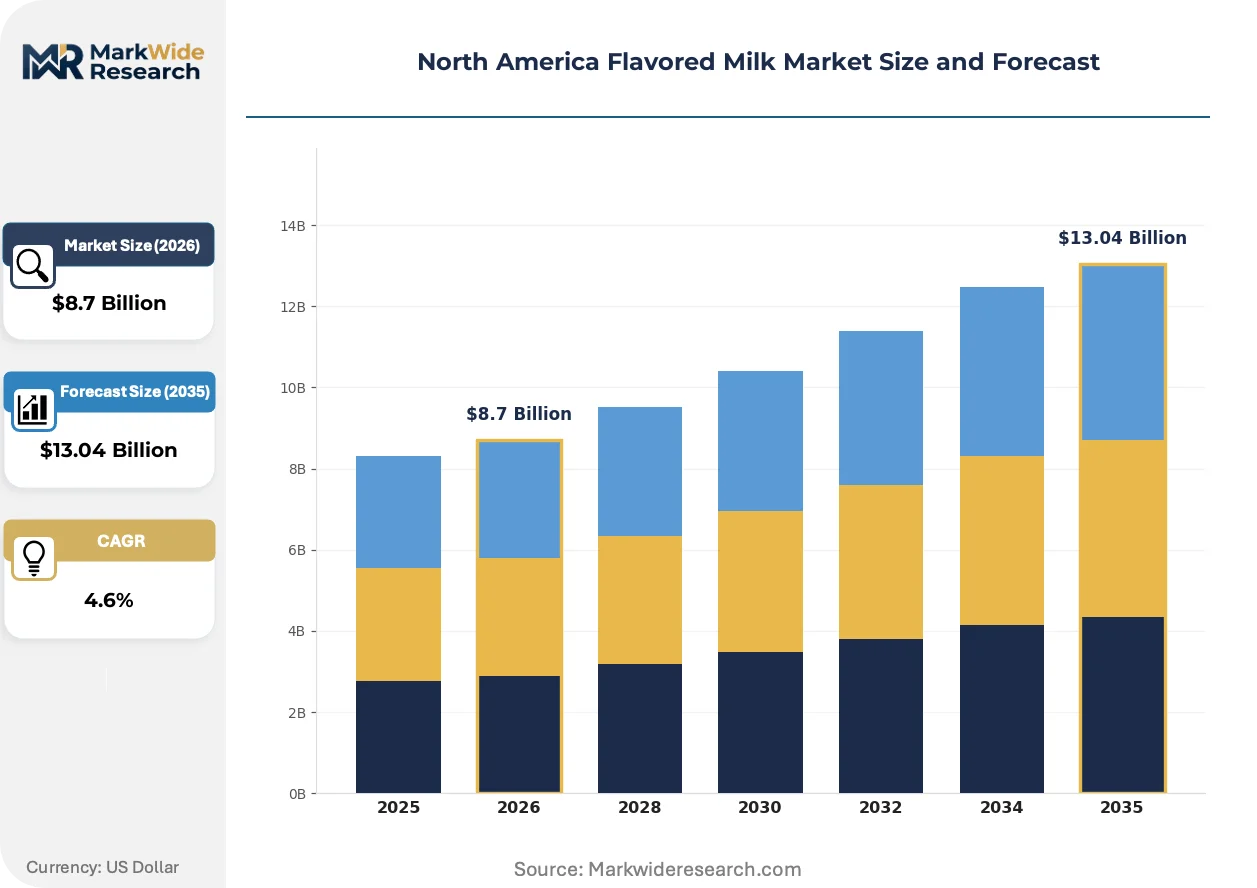
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Strawberry, Vanilla, Caramel Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Carton, Bottle, Tetra Pack, Can End User: Children, Teens, Adults, Seniors |
| Companies Covered | Saputo Inc., Fairlife LLC, Nestlé S.A., Oakhurst Dairy, Agropur Dairy Cooperative, Dairy Farmers of America, The Kraft Heinz Company, H.P. Hood LLC, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flavored Milk Market Evolving Landscape
Reformulation pressures and channel fragmentation are simultaneously compressing traditional product architectures while opening white space for functional positioning and direct distribution models.
Ultrafiltration membrane technology is virtualizing the separation between standard and premium flavored milk tiers. Processors deploy ceramic and polymeric membranes to concentrate protein and reduce lactose without dilution. School districts and fitness-oriented consumers adopt these offerings at accelerating rates. The technology is virtualizing conventional margin structures by collapsing the cost differential between mass-market and functional formulations.
USDA school meal guidelines are tightening added-sugar thresholds for institutional eligibility, forcing processors to rebalance sweetener portfolios. The industrial consequence is accelerated adoption of natural flavor masking systems and stevia blends. Southeast U.S. school districts, where dairy processing clusters enable rapid formulation turnaround, are responding fastest with pilot programs for reduced-sugar chocolate milk.
Direct-to-consumer replenishment is displacing traditional distributor relationships in suburban and exurban markets. Subscription platforms bypass conventional convenience and grocery channels, capturing household-level consumption data. This pattern concentrates in Texas and California metropolitan corridors where delivery density supports unit economics, with processors building captive logistics capabilities to defend margin capture.
North America Flavored Milk Market Segmentation
Segmentation in the North America flavored milk market reveals how formulation choices, channel strategies, and demographic targeting create divergent margin profiles. Understanding these splits enables processors to allocate capital between institutional volume plays and premium direct-to-consumer experiments.
Product Type:
Flavor positioning determines cost tier access and reformulation burden across institutional and retail channels.
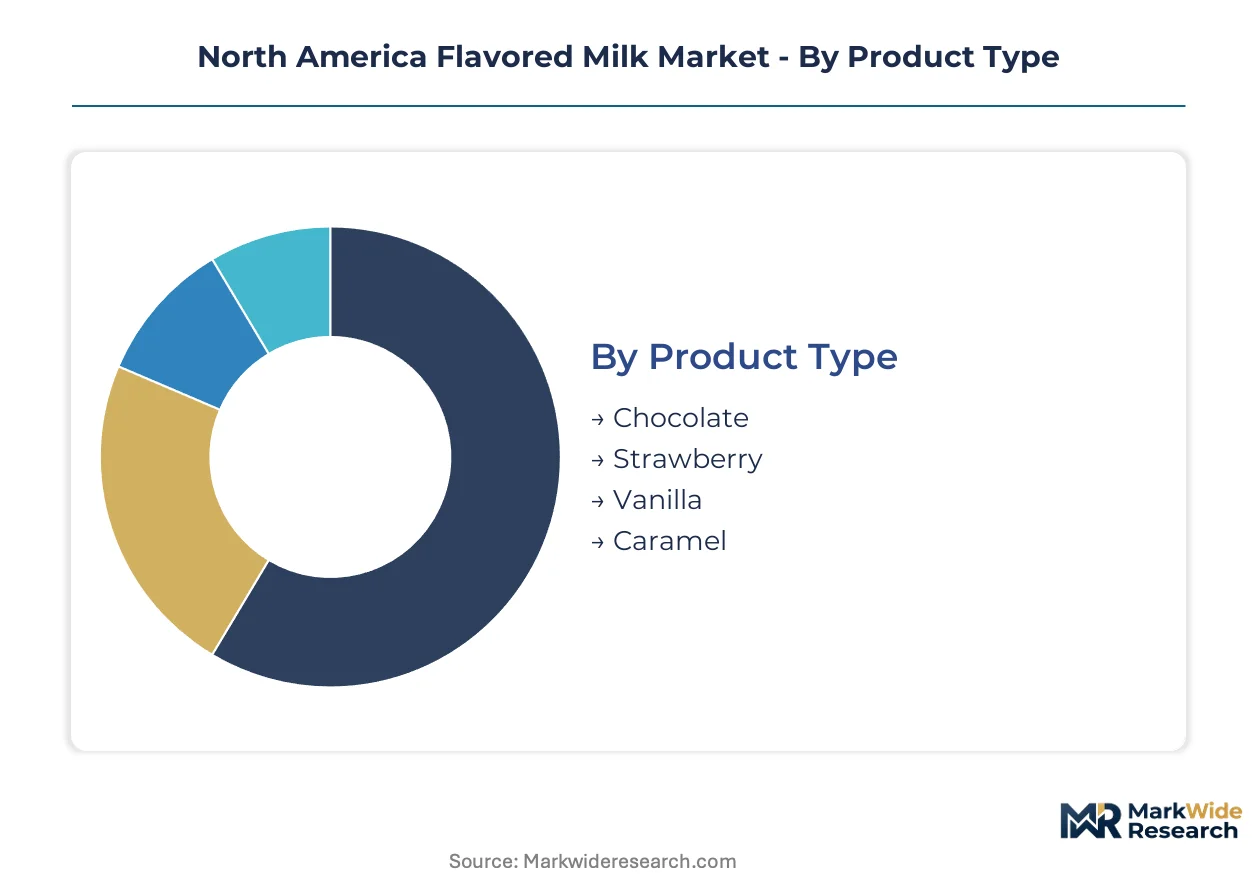
- Chocolate:Formulations with one percent to two percent milk fat and standardized protein above eight grams per serving dominate USDA school meal procurement. Southeast U.S. dairy processing clusters in Georgia and Florida supply reduced-sugar variants to federal feeding programs under tightening added-sugar thresholds.
- Vanilla:Clean-label positioning with natural flavor masking systems commands premium placement in specialty coffee shop channels. Texas and California metropolitan corridors show fastest adoption via subscription replenishment models targeting adult post-workout recovery.
- Strawberry:Artificial colorant restrictions under Health Canada create dual-SKU requirements for cross-border processors.
- Caramel:Foodservice applications in New England convenience channels sustain regional brand loyalty.
Chocolate commands the established base. The steepest expansion runs through vanilla.
Distribution Channel:
Channel selection shapes customer data capture and margin retention for processors navigating distributor relationships.
- Supermarkets:Traditional grocery placement sustains volume throughput for standard chocolate and strawberry formulations. FDA added-sugar disclosure rules intensify price competition on shelf, compressing margin for legacy processors without ultrafiltration capabilities.
- Online Retail:Direct-to-consumer packaging innovations enable subscription-based replenishment with household-level consumption data. Delivery density in suburban Texas and California corridors supports unit economics that bypass conventional convenience store distributors.
- Convenience Stores:Single-serve carton procurement locks in predictable institutional volume for school nutrition programs.
- Specialty Stores:Protein-enriched ultrafiltered offerings target fitness-oriented adult demographics.
Supermarkets anchor volume throughput. Online retail gains share fastest.
Packaging Type:
Packaging format dictates cold chain requirements, shelf stability, and suitability for institutional versus direct-to-consumer deployment.
- Carton:Single-serve gable-top containers dominate USDA school meal guidelines with predictable federal feeding program volume. Southeast processing clusters enable rapid formulation turnaround for reduced-sugar pilot programs.
- Bottle:HDPE and PET formats support protein-enriched ultrafiltered products with extended refrigerated shelf life. Fitness-oriented consumers in California and Texas metropolitan markets prefer resealable formats for post-workout consumption.
- Tetra Pack:Aseptic processing permits ambient distribution without cold chain investment.
- Can:Aluminum formats target convenience channel impulse purchases.
Carton secures institutional lock-in. Bottle climbs the fastest.
End User:
Demographic targeting determines formulation complexity, from child-palatable calcium delivery to adult functional recovery positioning.
- Children:Palatable calcium delivery vehicles with lower added-sugar formulations satisfy USDA school meal guidelines. Southeast U.S. school districts pilot reduced-sugar chocolate milk programs leveraging regional dairy processing concentration.
- Adults:Protein concentration above eight grams per serving via ultrafiltration technology expands addressable market into post-workout recovery. Subscription platforms in Texas and California corridors capture this segment through direct-to-consumer replenishment.
- Teens:Transitional demand splits between institutional programs and independent convenience channel purchases.
- Seniors:Fortified formulations with enhanced bioavailability claims target nutritional supplementation needs.
Children anchor institutional volume. Adults drive the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New York and New Jersey's refrigerated cargo terminals anchor North American distribution for temperature-sensitive dairy beverages, while cross-border rail links between Ontario and Michigan sustain just-in-time supply chains for ultrafiltered milk concentrates.
United States
Southeast dairy processing clusters in Georgia and Florida supply reduced-sugar chocolate milk to federal school nutrition programs. USDA tightening of added-sugar thresholds for institutional eligibility drives rapid formulation turnaround in these captive facilities. Texas and California metropolitan corridors host the fastest-growing subscription replenishment platforms for protein-enriched adult recovery beverages.
Canada
Quebec and Ontario dairy cooperatives leverage supply-managed production quotas to stabilize input costs for value-added milk beverages. Health Canada restrictions on artificial colorants permitted in U.S. formulations force parallel SKU maintenance for cross-border processors. The Montreal-Toronto processing corridor anchors Saputo Inc.'s national production scale while competing for U.S. shelf space.
Mexico
Rising middle-class consumption in Mexico City and Guadalajara metro areas drives demand for shelf-stable flavored milk formats. Mexican federal nutrition labeling standards mirror FDA added-sugar disclosure approaches, creating regulatory alignment for U.S. exporters. Northern border states concentrate dairy processing infrastructure to serve maquiladora corridor demand and re-export positioning.
North America Flavored Milk Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane filtration and natural flavor masking inputs. The North American flavored milk market presents a bifurcated structure where ultrafiltration-capable processors capture premium positioning while legacy pasteurization operators defend volume through institutional contracts. Three archetypes dominate: technology-integrated dairy cooperatives with captive supply chains, multinational beverage conglomerates leveraging cross-category distribution, and regional processors anchored in single-state convenience channel relationships. Competitive moves concentrate on membrane system capacity expansion and direct-to-consumer platform development.
Among U.S.-based technology-integrated processors, Fairlife LLC and H.P. Hood LLC exemplify divergent strategic positioning. Fairlife LLC occupies the protein-enriched premium tier through ultrafiltration-based concentration methods. H.P. Hood LLC anchors traditional chocolate milk distribution in New England convenience channels. Saputo Inc. represents the cross-border cooperative archetype, leveraging Canadian supply management to compete for U.S. retail shelf space against domestically organized competitors.
| Leading Market Players |
|---|
| Saputo Inc. |
| Fairlife LLC |
| Nestlé S.A. |
| Oakhurst Dairy |
| Agropur Dairy Cooperative |
| Dairy Farmers of America |
| The Kraft Heinz Company |
| H.P. Hood LLC |
| Danone |
| Others |
Value Network & Pricing Analysis
Canadian supply-managed dairy quotas anchor input cost stability for cross-border processors, concentrating margin capture in ultrafiltration-equipped facilities serving premium adult recovery segments while legacy pasteurization operators defend institutional volume through fixed-price school nutrition contracts.
Pricing Analysis
FDA added-sugar disclosure rules dictate the pricing tier structure by compressing margin on traditional chocolate formulations while enabling premium extraction for protein-enriched variants. Three-tier pricing structure across premium, standard, and economy levels stratifies by ultrafiltration capability, with post-workout recovery positioning commanding least price sensitivity. Cost compression in standard formulations is intensifying because of stevia blend reformulation expenses and natural flavor masking system adoption. School nutrition program procurement managers exhibit highest price sensitivity due to federal feeding program budget constraints.
Supply Chain Analysis
Export-control regimes on ceramic membrane filtration technology limit equipment flows to mid-tier processors, concentrating ultrafiltration capacity among technology-integrated cooperatives. Geographic supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on milk protein concentrates, natural flavor systems, and aseptic packaging substrates. Single-source vulnerability in membrane supply creates bottlenecks for processors retrofitting legacy pasteurization lines. Distribution runs through refrigerated cargo terminals at the Port of New York and New Jersey, with cross-border rail sustaining just-in-time concentrate flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as school nutrition program procurement rebounds from pandemic-era disruptions and adult functional beverage demand inflects upward.
For Market Incumbents: Harden institutional contract positions by locking multi-year USDA school meal agreements before added-sugar threshold tightening accelerates. Deepen upstream control over ultrafiltration membrane capacity through equipment financing partnerships with technology vendors, defending against emerging protein-beverage specialists. For New Entrants and Emerging Players: Establish a beachhead in subscription-based direct-to-consumer replenishment targeting Texas and California metropolitan corridors where delivery density supports unit economics. Penetrate the vanilla flavor segment for specialty coffee shop channels, leveraging clean-label positioning and natural flavor masking systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultrafiltration-equipped processing capacity, favoring scaled operators with captive supply chains. Over the coming decade, acquisition targets should emphasize mid-tier processors with membrane retrofit completion and established school nutrition program relationships. The signal to watch is state-level sugar taxation adoption patterns that would accelerate reformulation capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrafiltration Capacity Expansion | Membrane system deployment collapses cost differential between mass-market and functional formulations. |
| Direct-to-Consumer Platform Launch | Subscription replenishment in Texas and California corridors bypasses convenience store distributor margin capture. |
| Reduced-Sugar Reformulation Program | Stevia blend adoption satisfies USDA tightening thresholds while maintaining child palatability. |
| Cross-Border SKU Harmonization | Parallel formulation standards for FDA and Health Canada reduce inventory carrying cost inflation. |
| Specialty Coffee Shop Channel Partnership | Vanilla and caramel placement in foodservice commands disproportionate margin through premium positioning. |
Research Methodology
Initial hypotheses were tested against primary input from dairy processing executives, school nutrition program procurement directors, ultrafiltration equipment specialists, and retail category buyers, then refined through secondary validation against USDA school meal guideline documentation, FDA labeling rule filings, Health Canada compositional standards, and Nielsen retail audit data. Bottom-up volume modeling triangulated with top-down market sizing anchored the analysis.
Demand-supply balance framing structured the projection framework across the analysis window, with segmentation dimensions spanning flavor type, distribution channel, packaging format, protein concentration tier, and end-user demographic. CAGRs were derived from iterative convergence of historical trajectory analysis and forward-looking elasticity estimates, incorporating school nutrition policy debate timelines and membrane technology adoption curves as industry-specific inputs.
Sensitivities concentrate around state-level sugar taxation proposals and USDA added-sugar threshold revisions that could accelerate reformulation timelines. Forecasts reflect documented assumptions on institutional contract renewal rates and ultrafiltration capex deployment schedules. Material shifts in federal school nutrition program eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Fermented Milk Products Market
Dairy Products
Skimmed Milk Market
Dairy Products
Kefir Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Lactic Butter Market
Dairy Products
GCC Casein Market
Dairy Products
Processed Cheese Market
Dairy Products
Whipping Cream Market
Dairy Products
Ghee Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Gruyere Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Ultra High Temperature Milk Market