
 Fermented Dairy Ingredients Market | 2026-2036
Fermented Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Dairy Ingredients Market Analysis
Ingredient processing margin pools is fragmenting as value capture shifts from bulk commodity fermentation toward specialized probiotic cultures and functional protein isolates. Chr. Hansen Holding dominates strain development and culture supply for industrial dairy processors. Kerry extends its position through integrated flavor-system partnerships with fermented base ingredient suppliers. Arla Foods Ingredients Group anchors Northern European production capacity for whey-derived fermented ingredients.
Fermented dairy ingredients comprise cultures, enzymes, proteins, and metabolites derived from controlled lactic acid fermentation of milk substrates, typically operating at pH ranges of 4.0 to 4.6 and temperatures between 37°C and 43°C to achieve target microbial profiles and functional properties. These inputs serve primarily as texture modifiers, flavor precursors, and bioactive delivery vehicles across formulated food systems. The yogurt segment within product type categories carries mature volume but faces margin compression, while kefir concentrates represent the fastest-growing fermentation format as beverage innovators seek differentiated probiotic positioning. Within application categories, nutritional supplements command premium pricing relative to traditional dairy product uses, though bakery applications are gaining traction as clean-label fermentation replaces chemical leavening and conditioning agents.
The FDA oversees GRAS self-determination and food additive petitions for novel fermented dairy ingredients entering the US market, while EFSA evaluates health claim substantiation for probiotic strains under EU nutrition and health claims regulation. REACH compliance governs enzymatic processing aids and fermentation-derived substances circulating within European supply chains, directly affecting formulation choices and supplier qualification timelines. Stakeholders must monitor evolving strain-specific approval pathways and carbon intensity disclosure requirements as regulatory frameworks tighten around biotechnology-derived food inputs.
Market Dynamics
Clean-label fermentation protocols are compressing legacy chemical processing margins as EU Green Deal carbon disclosure rules and F-Gas refrigerant phase-downs force dairy processors to reengineer temperature-controlled culture propagation systems.
Growth Catalysts
- Probiotic health claim substantiation:EFSA's evolving strain-specific approval pathways under EU nutrition and health claims regulation are accelerating documented bioactive ingredient development for nutritional supplement formulators seeking differentiated positioning.
- Whey protein upcycling:Circular economy mandates embedded in EU Green Deal frameworks are redirecting acid whey streams from waste treatment toward controlled fermentation for functional protein isolate recovery.
- Kefir concentrate beverage innovation:Beverage manufacturers in Germany and Denmark are expanding procurement of concentrated fermented bases to bypass cold-chain distribution constraints in premium probiotic positioning.
Market Restraints
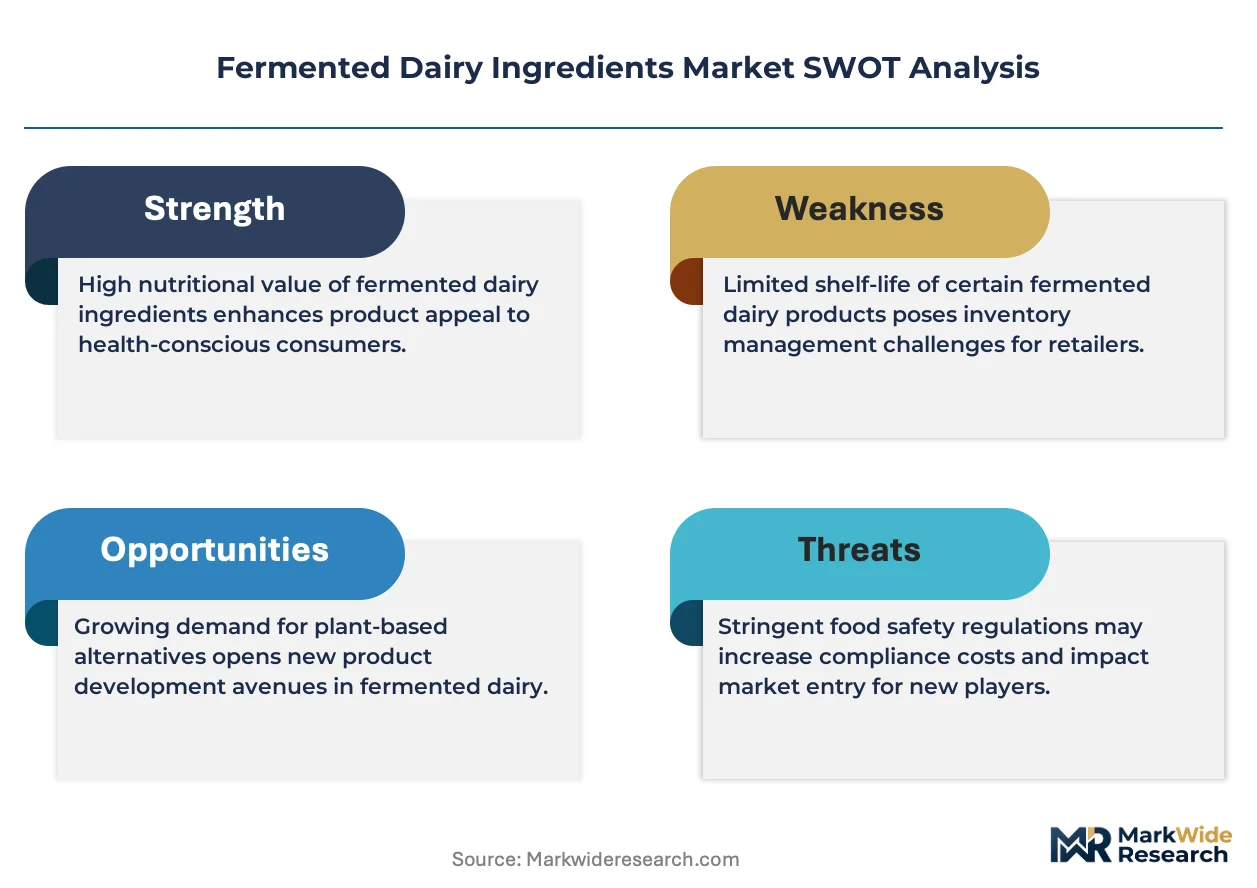
- Strain banking concentration:Industrial culture collections remain concentrated among three European suppliers, creating single-source vulnerability for processors scaling novel fermented ingredient lines.
- Organic acid feedstock volatility:Lactic acid prices fluctuate with corn starch commodity markets, compressing margin predictability for fermentation operations lacking backward integration into carbohydrate substrates.
- Thermophilic propagation energy intensity:Sustained 37°C to 43°C fermentation cycles consume substantial thermal energy, exposing operations to natural gas price spikes and EU carbon border adjustment exposure.
Strategic Opportunities
- Precision fermentation protein:Microbial biomass platforms utilizing engineered yeasts are opening alternative protein pathways that bypass traditional dairy substrate dependencies entirely.
- Bakery clean-label substitution:Chemical leavening displacement through fermented dairy-derived conditioning agents represents underpenetrated volume in industrial bread and pastry manufacturing.
- CSRD-aligned carbon accounting:Corporate sustainability reporting directive disclosure requirements are creating first-mover advantage for fermentation operations with verified low-intensity culture propagation documentation.
Industry Challenges
- Phage contamination protocols:Viral bacteriophage outbreaks in thermophilic starter cultures require dedicated clean-room infrastructure and specialized microbiological expertise that talent pipelines struggle to replenish.
- Strain-specific IP licensing:Proprietary culture ownership fragments across academic institutions, biotech ventures, and heritage dairy cooperatives, complicating freedom-to-operate assessments for new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Dairy Ingredients Market |
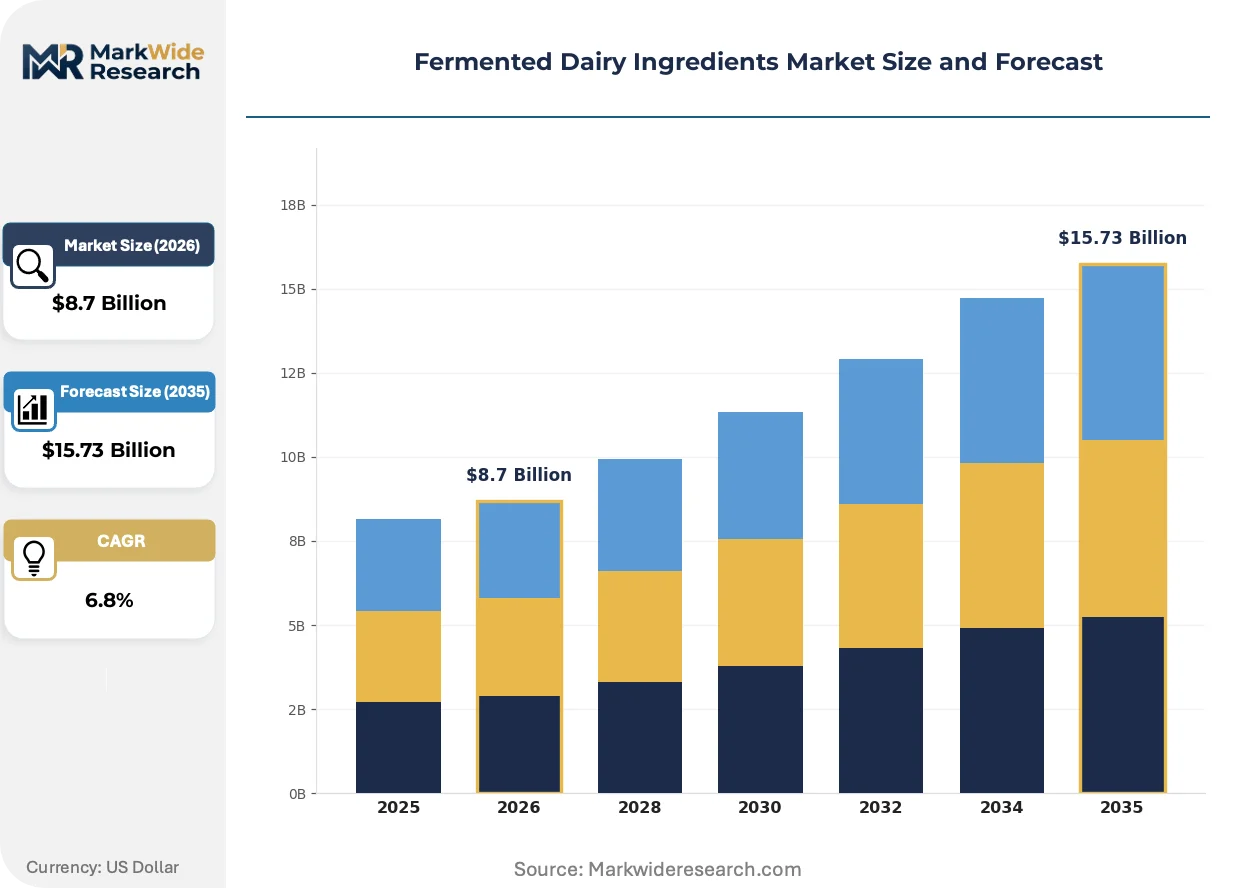
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Cheese, Kefir, Buttermilk Application: Dairy Products, Bakery, Confectionery, Nutritional Supplements End User: Food Manufacturers, Restaurants, Retailers, Health Clubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Cargill Incorporated, E. I. du Pont de Nemours and Company, Chr. Hansen Holding, Arla Foods Ingredients Group, Kerry, Novozymes, Archer Daniels Midland Company, Ingredion Incorporated, Koninklijke DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Dairy Ingredients Market Emerging Trajectories
Continuous fermentation bioreactor designs and AI-guided metabolic flux optimization are displacing batch processing paradigms that have dominated dairy ingredient manufacturing for decades.
Membrane-integrated cell retention systems enable steady-state operation at higher cell densities than traditional batch fermentation, reducing tank turnaround downtime and improving volumetric productivity for whey protein concentrate processors. Dairy ingredient manufacturers in Denmark and the Netherlands are piloting these systems for probiotic biomass production. Thermophilic culture propagation is rendering obsolete the seasonal capacity constraints that forced processors to build redundant fermentation trains for peak demand coverage.
REACH registration requirements for enzymatic processing aids are tightening substance data sheet obligations for fermentation-derived bioactives circulating in European supply chains. Suppliers now face extended dossier preparation timelines and substance evaluation costs that favor larger culture houses with dedicated regulatory affairs capacity. Probiotic strain suppliers serving nutritional supplement formulators are consolidating qualification documentation to preempt authorization delays.
Long-term offtake agreements with fixed volume commitments are displacing spot market purchasing for fermented whey derivatives as bakery and supplement manufacturers seek supply security amid dairy commodity volatility. German dairy processors report contract coverage extending to thirty-six months for acid casein and fermented protein isolate supply. This contractual shift concentrates procurement leverage among buyers with balance sheet capacity to lock in forward positions.
Fermented Dairy Ingredients Market Segmentation
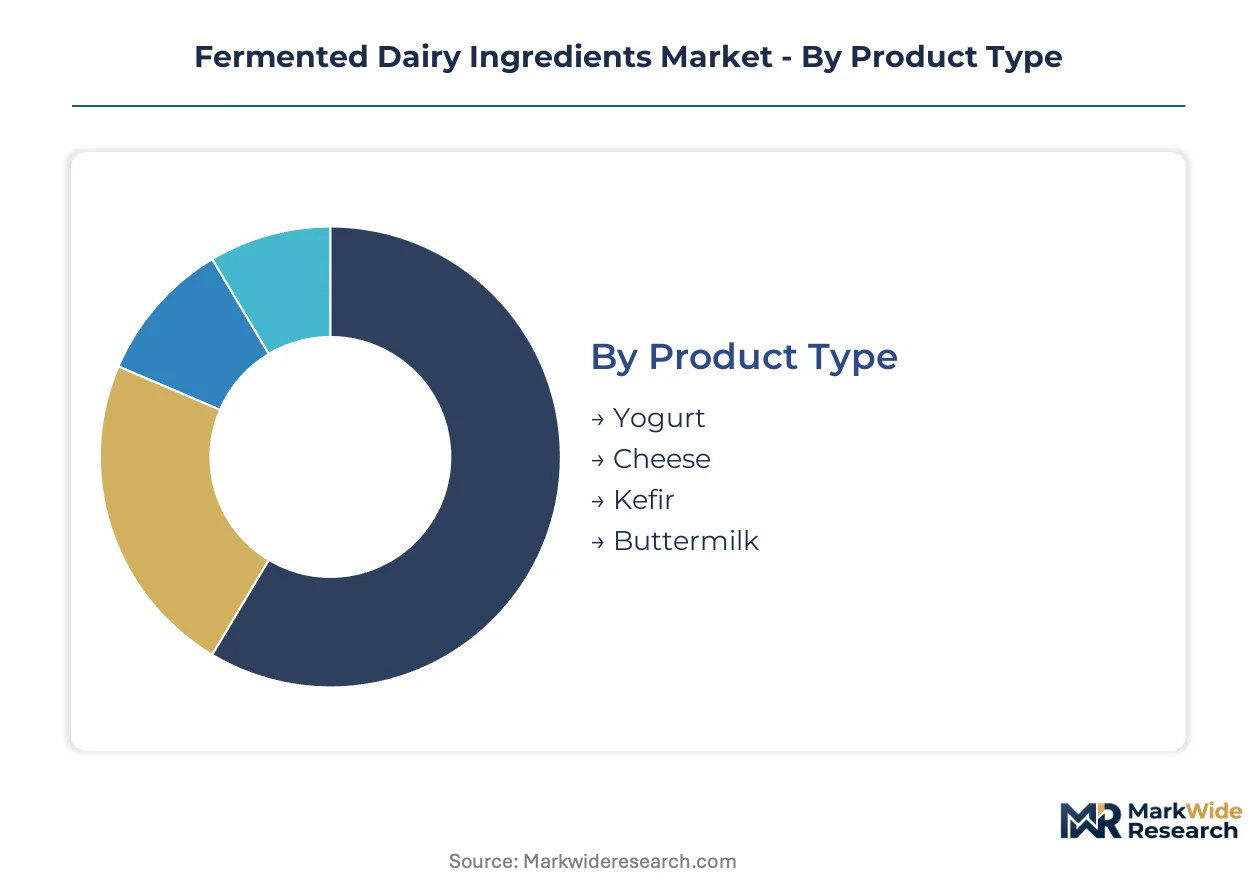
Segmentation in fermented dairy ingredients reveals distinct technical requirements and margin profiles across fermentation formats and customer channels. Each category exposes different vulnerability to cold-chain logistics, regulatory claim substantiation, and ingredient specification variability.
Product Type:
After-sales service intensity varies sharply across fermentation formats, with live culture products demanding technical support for pH monitoring and contamination protocols while processed derivatives require minimal ongoing assistance.
- Yogurt:Thermophilic fermentation at 37°C to 43°C produces standardized cultures with established GRAS status and documented strain stability. German dairy processors concentrate procurement here for nutritional supplement formulations seeking EFSA-aligned health claim substantiation, though margin compression intensifies as commodity bulk volumes dominate.
- Kefir:Heterofermentative complexity involving multiple yeast and bacterial strains creates specification variability that commands premium positioning. Beverage innovators in Denmark expand concentrate procurement to bypass cold-chain constraints, with kefir climbing the fastest among all fermentation formats.
- Cheese:Rennet-coagulated and culture-ripened derivatives span fresh to aged matrices with divergent enzyme requirements.
- Buttermilk:Mesophilic fermentation byproducts serve industrial bakery conditioning with lower culture maintenance overhead.
By volume, yogurt leads. By expansion trajectory, kefir is ahead.
Application:
Cost tier stratification separates commodity-grade dairy uses from premium nutritional positioning, with regulatory burden and claim documentation requirements widening the gap.
- Nutritional Supplements:Strain-specific bioactive concentrates command premium pricing contingent on EFSA health claim authorization or FDA GRAS self-determination. Probiotic biomass with documented CFU stability through shelf life attracts formulators in Germany and the Netherlands seeking differentiated positioning in sports nutrition and gut health segments.
- Bakery:Fermented dairy-derived conditioning agents displace chemical leavening in clean-label industrial bread production. Danish and Dutch manufacturers pilot acid whey upcycling into functional protein isolates for dough conditioning, with bakery applications expanding most quickly as EU Green Deal circular economy mandates accelerate.
- Dairy Products:Traditional yogurt and cheese manufacturing consumes mature volumes with established supply chains.
- Confectionery:Limited penetration due to thermal processing constraints on live culture viability.
By revenue concentration, nutritional supplements lead. By adoption velocity, bakery is ahead.
End User:
Customer type determines specification stringency, with food manufacturers demanding batch documentation and strain traceability that restaurants and retailers rarely require.
- Food Manufacturers:Industrial-scale procurement of standardized cultures with certificate of analysis documentation for each lot. German processors lock thirty-six-month forward contracts for fermented whey derivatives to secure supply amid dairy commodity volatility.
- Restaurants:Artisan fermentation for menu differentiation with minimal technical specification requirements.
- Retailers:Private-label fermented product sourcing with moderate quality tier positioning.
- Health Clubs:Niche protein and probiotic supplement distribution with high service expectations.
By procurement volume, food manufacturers lead. By margin per transaction, health clubs are ahead.
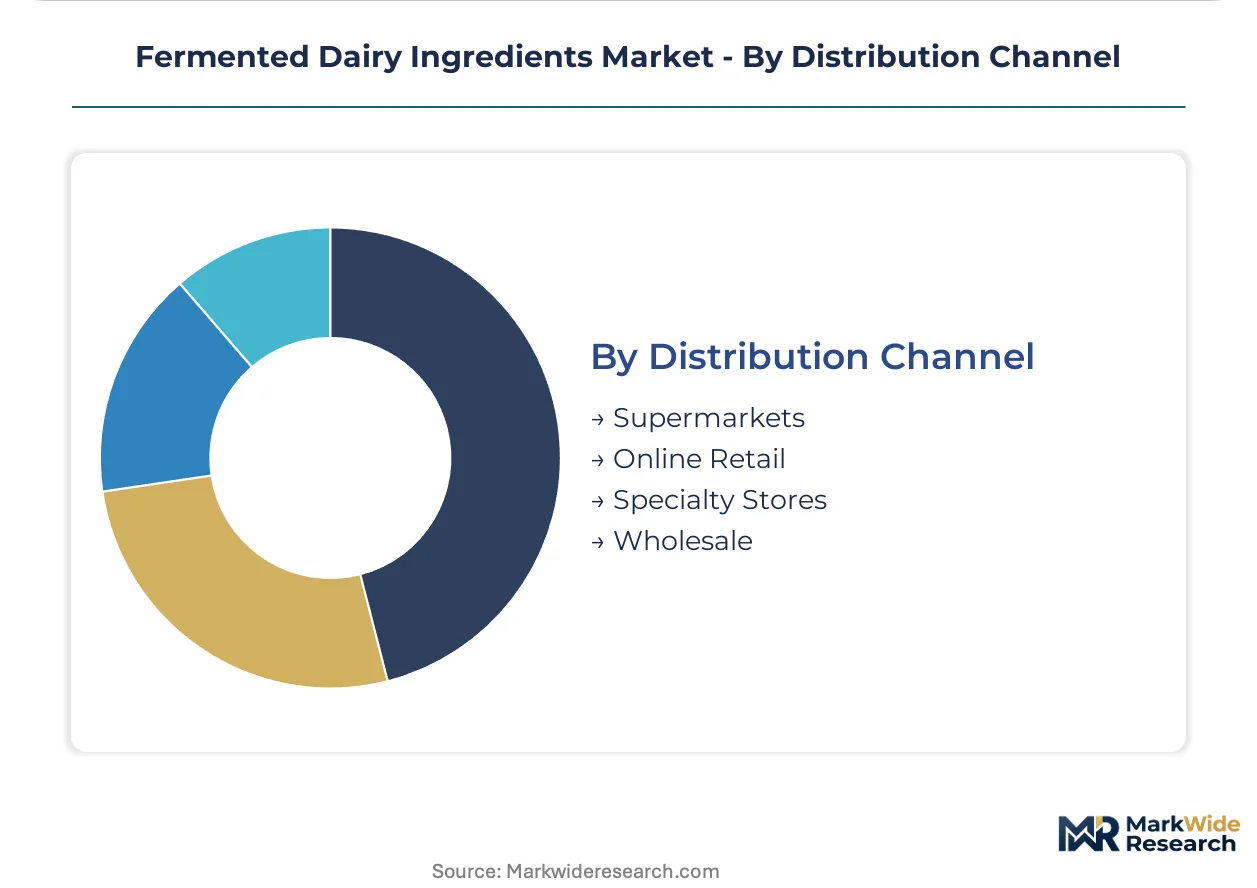
Distribution Channel:
Supply concentration favors wholesale and supermarket consolidation, while specialty and online channels fragment across regional culture houses.
- Supermarkets:Centralized refrigerated distribution for consumer-facing fermented dairy products with established private-label programs.
- Wholesale:Bulk ingredient supply to industrial processors with dedicated cold-chain infrastructure and volume pricing structures.
- Specialty Stores:Artisan and heritage culture sourcing for premium positioning with limited geographic reach.
- Online Retail:Direct-to-consumer probiotic supplements and culture starter kits with temperature-controlled shipping requirements.
By throughput volume, wholesale leads. By channel expansion, online retail is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fermented dairy ingredients primarily for nutritional supplement formulations, while Denmark and the Netherlands prioritize beverage concentrate and bakery conditioning applications respectively. This tripartite demand split distinguishes Northern European procurement patterns from Southern European commodity dairy uses.
Germany
Nutritional supplement manufacturers in Bavaria and North Rhine-Westphalia drive concentrated demand for EFSA-substantiated probiotic strains. The country's national food safety regulator enforces strict health claim documentation under EU nutrition and health claims regulation. Cologne anchors industrial procurement clusters where thirty-six-month forward contracts for fermented whey derivatives now dominate supply security planning.
Denmark
Beverage innovators prioritize kefir concentrate procurement to bypass cold-chain distribution constraints in premium probiotic positioning. EFSA strain-specific approval pathways accelerate documented bioactive development for local formulators. Copenhagen and Aarhus host fermentation technology clusters where continuous bioreactor designs displace legacy batch processing for probiotic biomass production.
Netherlands
Bakery applications expand fastest as clean-label fermentation replaces chemical leavening in industrial bread manufacturing. REACH compliance governs enzymatic processing aids and fermentation-derived substances circulating through Dutch supply chains. Wageningen anchors research-intensive ingredient innovation hubs where acid whey upcycling into functional protein isolates advances under EU Green Deal circular economy mandates.
United States
Food manufacturers pursue GRAS self-determination for novel fermented dairy ingredients entering nutritional supplement channels. FDA oversight of food additive petitions shapes strain development timelines for domestic biotech ventures. Wisconsin and California dairy processing belts concentrate thermophilic culture propagation capacity serving both traditional dairy and emerging precision fermentation protein platforms.
France
Heritage dairy cooperatives maintain proprietary culture collections that fragment intellectual property ownership across academic and commercial boundaries. ANSM and national agricultural regulators enforce labeling requirements aligned with EU Green Deal carbon disclosure frameworks. The Brittany dairy belt preserves artisan fermentation expertise while industrial processors in the Île-de-France region scale contract manufacturing for pan-European supplement brands.
Fermented Dairy Ingredients Market Vendor Landscape
Capability concentration sits with culture development specialists; scale advantage sits with diversified ingredient houses and integrated dairy processors. The vendor base organizes around three strategic tiers: proprietary strain banks commanding premium licensing terms, fermentation-derived ingredient processors securing long-term offtake agreements, and dairy cooperatives leveraging captive whey streams for circular economy positioning. Dominant competitive moves include backward integration into carbohydrate substrate supply and strategic partnerships bridging strain development with finished formulation expertise.
Within the culture innovation tier, Chr. Hansen Holding and Novozymes exemplify proprietary strain ownership models that constrain freedom-to-operate for new market entrants. Kerry occupies a position connecting fermented base ingredient supply with integrated flavor-system partnerships. Arla Foods Ingredients Group anchors Northern European production capacity for whey-derived fermented ingredients. These three archetypes represent divergent pathways for value capture across the fermentation value chain.
| Leading Market Players |
|---|
| Cargill Incorporated |
| E. I. du Pont de Nemours and Company |
| Chr. Hansen Holding |
| Arla Foods Ingredients Group |
| Kerry |
| Novozymes |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Koninklijke DSM |
| Others |
Supply Flow & Price Mechanics
Cologne anchors Northern European procurement clusters where thirty-six-month forward contracts for fermented whey derivatives now dominate supply security planning, compressing spot market liquidity and concentrating pricing power among buyers with balance sheet capacity to lock in forward positions.
Pricing Analysis
Long-term offtake agreements with fixed volume commitments are displacing spot market purchasing for fermented whey derivatives as bakery and supplement manufacturers seek supply security amid dairy commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated probiotic strains from commodity bulk cultures and generic fermentation inputs. Cost compression in commodity-grade yogurt cultures is intensifying because bulk volume dominance erodes margin predictability. Nutritional supplement formulators exhibit least price sensitivity due to health claim substantiation premiums, while industrial dairy processors face acute margin pressure from thermophilic propagation energy costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard for strain banking procurement as culture houses face REACH registration cost burdens and dossier preparation timelines. Supply concentrates in Germany, Denmark, and the Netherlands as dairy processing clusters consolidate near major ingredient innovation hubs. Raw material dependencies center on corn starch-derived lactic acid feedstocks, thermophilic starter cultures, and membrane filtration equipment. Single-source vulnerability from strain banking concentration among three European suppliers creates structural risk for processors scaling novel fermented ingredient lines. Distribution runs through wholesale channels with dedicated cold-chain infrastructure serving industrial food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation protein platforms utilizing engineered yeasts are disrupting traditional dairy substrate dependencies, while EU Green Deal carbon disclosure rules accelerate clean-label fermentation protocol adoption across Northern European processing clusters.
For Market Incumbents: Build proprietary strain ownership moats through exclusive licensing agreements with academic culture collections and heritage dairy cooperatives. Secure backward integration into carbohydrate substrate supply to buffer lactic acid price volatility from corn starch commodity markets. Expand Copenhagen and Aarhus fermentation technology clusters with continuous bioreactor capacity to displace legacy batch processing competitors. For New Entrants and Emerging Players: Bakery clean-label substitution for chemical leavening agents represents the most penetrable entry point for fermented dairy-derived conditioning agents in industrial bread manufacturing. Kefir concentrate procurement for beverage innovators in Denmark offers differentiated probiotic positioning without cold-chain infrastructure requirements. Partner with Wageningen research-intensive ingredient innovation hubs to access acid whey upcycling technology under EU Green Deal circular economy mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among proprietary strain banks commanding premium licensing terms for EFSA-substantiated probiotic cultures. Long-term viability over the next decade hinges on carbon intensity disclosure documentation aligning with CSRD requirements. Target acquisition archetypes include precision fermentation protein ventures with engineered yeast platforms bypassing dairy substrate dependencies entirely. Monitor EFSA strain-specific approval pathway acceleration as the critical signal for bioactive ingredient premiumization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Substrates | Corn starch supply control buffers lactic acid price volatility for fermentation operations. |
| Continuous Bioreactor Technology Deployment | Steady-state operation at higher cell densities displaces seasonal batch capacity constraints in Denmark. |
| EFSA Health Claim Substantiation Investment | Strain-specific approval documentation unlocks premium pricing in German nutritional supplement channels. |
| CSRD-Aligned Carbon Accounting Implementation | Verified low-intensity culture propagation documentation creates first-mover advantage under EU disclosure rules. |
| Acid Whey Upcycling Partnership | Circular economy mandate compliance redirects waste streams toward functional protein isolate recovery in the Netherlands. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation technology directors, dairy processing plant managers, regulatory affairs leads at culture houses, nutritional supplement formulators, and bakery procurement officers. Secondary validation drew from EFSA health claim submissions, REACH substance registration databases, EU Green Deal implementation guidance, dairy industry trade association reports, and customs records for fermented whey derivative trade flows. Bottom-up volume modeling across product type, application, end user, and distribution channel segments was triangulated against top-down macroeconomic indicators.
Calibration against historical volume trajectories and documented capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include fermentation format, functional application, customer type, and regional regulatory cluster. CAGRs were derived through exponential smoothing of annual growth rates adjusted for strain-specific approval pathway timelines and thermophilic propagation energy cost trajectories. Forecast inputs incorporated EFSA authorization probability assessments and EU carbon border adjustment exposure scenarios for natural gas-intensive fermentation operations.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, corn starch commodity markets, or EFSA regulatory processing timelines would shift the trajectory. Forecasts reflect documented assumptions regarding strain banking concentration persistence and clean-label fermentation protocol adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Dairy Desserts Market
Dairy Products
Low Fat Butter Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Buttermilk Powder Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Organic Dairy Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Lactic Butter Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
Yogurt and Probiotic Drink Market