
 Fractionated Pulses Market | 2026-2036
Fractionated Pulses Market Size, Share, and Industry Trends Forecast 2026-2036
Fractionated Pulses Market Analytics
REACH compliance is broadening the cost-of-entry calculus for European fractionated pulse suppliers, as chemical safety documentation requirements now extend to novel protein isolates and modified starches entering food and feed chains. AGT Food and Ingredients leverages its vertically integrated supply chain from Saskatchewan pulse farms to fractionation facilities, sustaining competitive cost structures against imported alternatives. Ingredion Incorporated anchors its position through deep R&D investment in texturized pulse protein systems for meat alternatives. Roquette Frères S.A. differentiates via its proprietary wet-fractionation expertise and long-standing relationships with European bakery and dairy alternative manufacturers.
Fractionated pulses denote the mechanical or wet-processed separation of whole pulse seeds into constituent components—protein concentrates typically achieving 50-85% protein content, native starches with amylose ratios varying by pulse species, and fiber-rich hull fractions—primarily to replace wheat, soy, and animal-derived ingredients in formulated foods. Pulse proteins command the deepest margin pools due to premium pricing in meat alternatives and sports nutrition, while pulse starches occupy mature, volume-driven positions in gluten-free bakery and extruded snacks. The dairy alternatives application segment is expanding fastest, driven by beverage formulators seeking emulsion-stable protein sources with neutral flavor profiles.
The FDA maintains stringent identity standards for pulse-derived ingredients under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees pulse crop grading that indirectly shapes fractionation feedstock quality and pricing. India's FSSAI has implemented progressively tighter contaminant thresholds for processed pulse products, forcing domestic fractionators to upgrade purification infrastructure or exit branded ingredient channels. Stakeholders must monitor how evolving protein content claims regulations across multiple jurisdictions will redefine labeling advantages and reformulation thresholds for finished goods manufacturers.
Market Dynamics
The EU Green Deal's sustainable protein targets are compressing ingredient sourcing timelines for European food manufacturers, forcing rapid qualification of pulse-derived alternatives to soy and animal proteins. This regulatory pressure is cascading through formulation R&D budgets and supplier certification pipelines.
Growth Catalysts
- EU Green Deal protein mandates:Binding sustainability targets for institutional food procurement are redirecting formulation spend toward domestically sourced pulse isolates. Public sector contracts now specify minimum plant protein inclusion rates.
- Meat alternative formulation pipelines:Extruded texturized pulse protein is displacing soy in premium burger and sausage applications. Clean-label positioning drives preference for allergen-free pulse bases over legacy soy systems.
- India:Government-backed pulse processing infrastructure under the PLI scheme is expanding domestic fractionation capacity. State-sponsored cold storage and dehulling investments are reducing feedstock loss rates for protein concentrate production.
Market Restraints
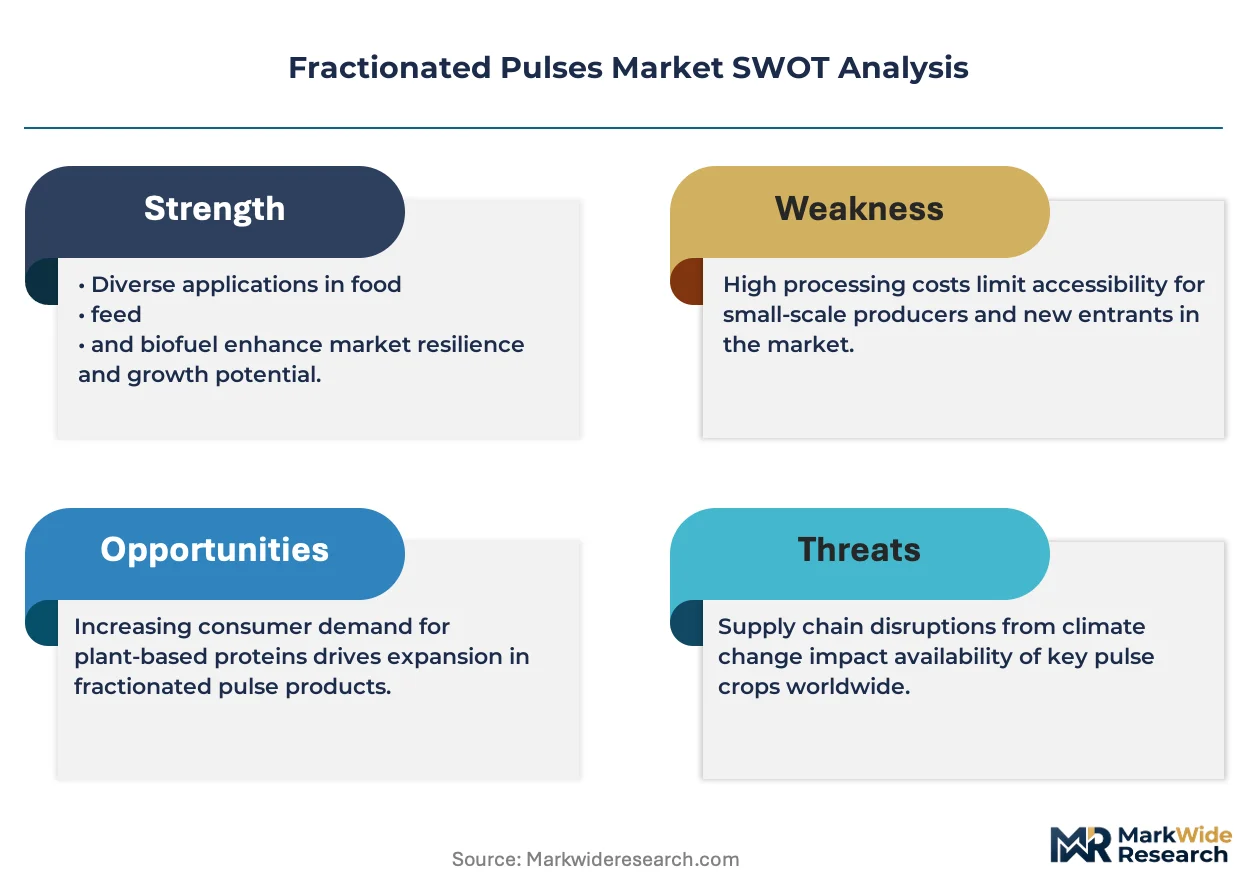
- Yellow pea protein supply concentration:Canadian prairie output dominates high-quality feedstock for fractionation. Weather volatility in Saskatchewan and Alberta propagates directly into isolate pricing volatility.
- REACH documentation burdens:ECHA's extended safety data requirements for novel protein isolates and modified starches are extending new product registration timelines. Small European fractionators face disproportionate compliance cost absorption.
- Flavor masking technology gaps:Native pulse protein bitterness and beany off-notes require expensive enzymatic or physical treatment. Incomplete flavor neutrality limits penetration into delicate dairy alternative applications.
Strategic Opportunities
- Faba bean protein white space:Underdeveloped fractionation infrastructure for this high-yield European crop creates first-mover positioning. Faba's low allergenicity profile unlocks pediatric and senior nutrition applications where soy is excluded.
- Precision fermentation hybrids:Converging wet-fractionation and microbial protein production enables texture-tailored ingredient systems. Hybrid formulations address the fibrous bite gap in whole-muscle meat alternatives.
- Indian domestic retail channel expansion:Branded pulse protein ingredients for home-use fortification remain underpenetrated. Direct-to-consumer protein powder positioning bypasses institutional buyer concentration.
Industry Challenges
- Food protein engineering talent scarcity:Formulation chemists with dual expertise in pulse chemistry and extrusion texturization command premium compensation. Academic pipelines in this intersection remain thin.
- Organic certification timeline compression:Three-year transition requirements for pesticide-free pulse sourcing delay premium product launches. Synchronous farm-level conversion and fractionation facility qualification strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractionated Pulses Market |
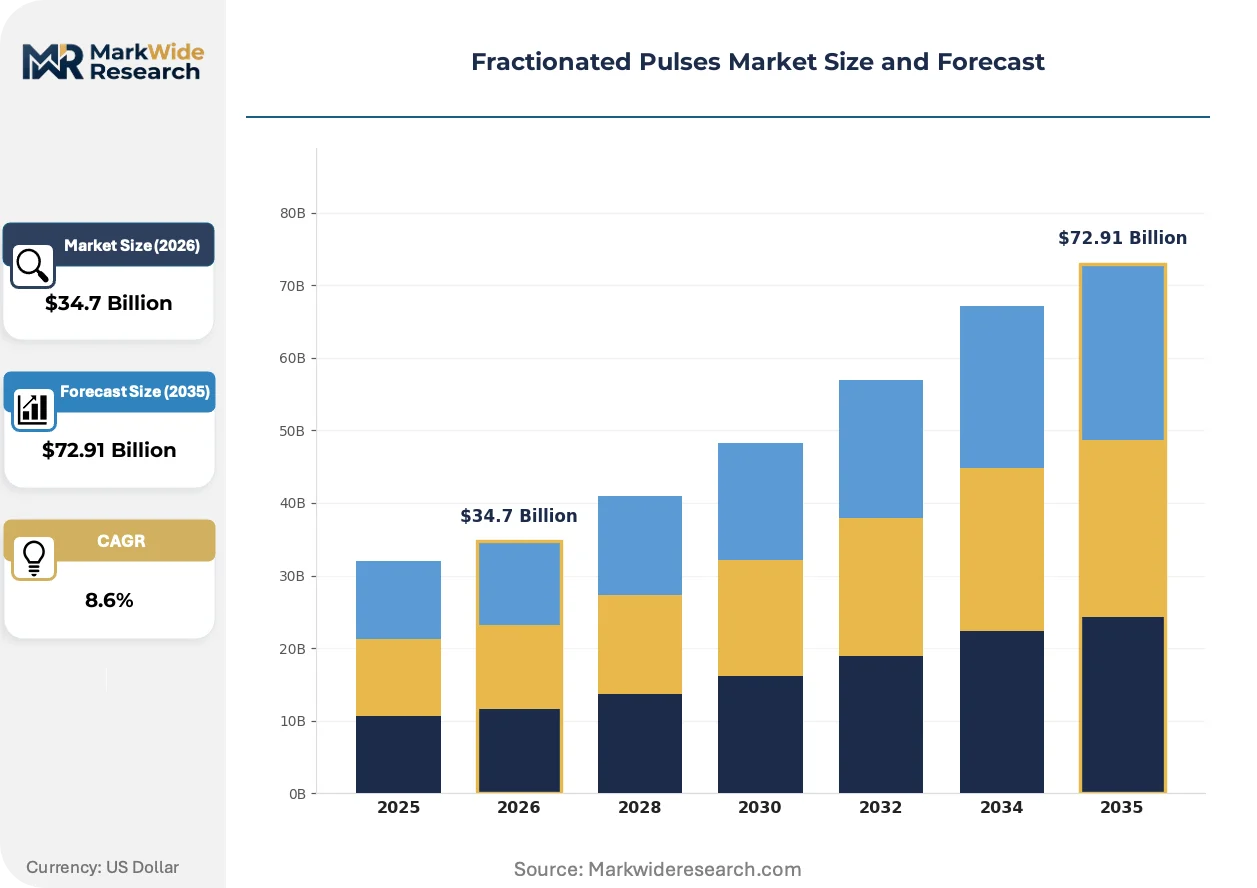
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Flours, Pulse Proteins, Pulse Starch, Pulse Derivatives End User: Food & Beverages, Animal Feed, Nutraceuticals, Cosmetics Application: Meat Alternatives, Bakery Products, Dairy Alternatives, Snacks Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Export |
| Companies Covered | AGT Food and Ingredients, Ingredion Incorporated, Axiom Foods Inc., Emsland Group, Avena Foods Ltd., Cargill, Nutripea, Roquette Frères S.A., Archer-Daniels-Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractionated Pulses Market Evolving Landscape
Wet-fractionation process intensification is compressing water and energy footprints while expanding protein yield recovery rates. Equipment suppliers and ingredient processors are co-developing closed-loop systems that recover starch and fiber fractions for parallel revenue streams.
Air-classification technology paired with dry dehulling is absorbing capital investment from mid-scale fractionators seeking to bypass wet-process infrastructure costs. Regional bakery and snack manufacturers in Germany and the Netherlands are adopting these lower-capital systems for in-house protein concentrate production. The technology is absorbing market share previously captured by centralized wet-fractionation facilities by enabling distributed, smaller-batch production with faster formulation iteration cycles.
REACH compliance documentation for novel protein isolates is extending from industrial chemicals into food and feed ingredient categories. ECHA's expanded substance registration requirements are forcing European fractionators to retroactively compile toxicological dossiers for legacy product lines. Dairy alternative and sports nutrition segments are responding by accelerating supplier audits and dual-sourcing from jurisdictions with harmonized safety recognition.
Ingredient buyers are consolidating supplier relationships around fractionators offering integrated application technical service. Large meat alternative manufacturers in the United States are shifting from transactional commodity purchasing to multi-year partnership structures with guaranteed volume and co-development clauses. This concentration is most visible in California and Illinois, where plant-based R&D clusters have achieved sufficient scale to justify dedicated technical service staffing from pulse protein suppliers.
Fractionated Pulses Market Segmentation
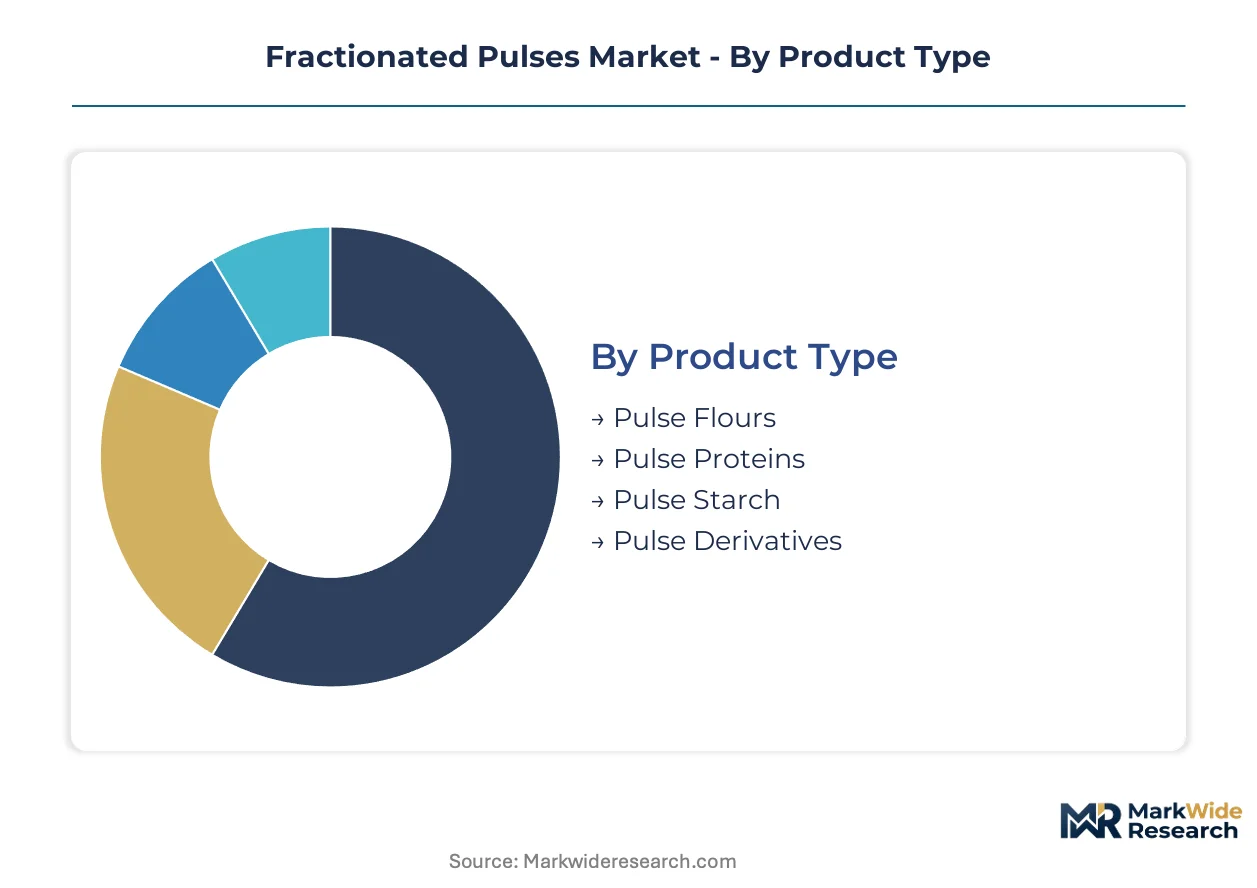
Fractionated pulse suppliers configure production assets around distinct product-property tiers and end-use specifications. Segmentation reveals where margin pools deepen and which application pipelines absorb capital investment fastest.
Product Type:
Equipment upgrade cycles and replacement thresholds vary sharply across fractionation output categories, with protein isolation systems demanding more frequent technology refresh than starch recovery lines.
- Pulse Proteins:Isolates and concentrates achieving 50-85% protein content command premium positioning in meat alternatives and sports nutrition. European formulators in Germany and the Netherlands are accelerating qualification of these ingredients to meet EU Green Deal procurement mandates.
- Pulse Starch:Native starches with species-specific amylose ratios serve gluten-free bakery and extruded snack applications. Indian fractionators under PLI scheme incentives are expanding starch recovery capacity to supply domestic processed food manufacturers.
- Pulse Flours:Whole-seed milling outputs with partial fiber retention target cost-sensitive bakery and pet food formulations.
- Pulse Derivatives:Modified starches, hydrolyzed proteins, and fiber concentrates emerge from secondary processing steps.
Volume placements concentrate in Pulse Starch; the faster expansion belongs to Pulse Proteins.
End User:
Customer procurement sophistication spans from commodity-scale feed operations to specification-intensive nutraceutical contract manufacturers, reshaping technical service requirements.
- Food & Beverages:Beverage formulators and meat alternative manufacturers drive specification tightening for emulsion stability and flavor neutrality. California and Illinois R&D clusters now require dedicated supplier technical service staffing.
- Animal Feed:Compound feed producers in Saskatchewan and Alberta integrate pulse protein concentrates into aquaculture and poultry rations.
- Nutraceuticals:Branded ingredient suppliers target pediatric and senior nutrition segments with allergen-free positioning.
- Cosmetics:Personal care formulators exploit pulse-derived film-forming starches and protein hydrolysates.
Procurement scale peaks with Food & Beverages; Nutraceuticals climbs fastest on premium positioning.
Application:
Formulation reformulation intensity varies by application, with whole-muscle meat alternatives demanding the most extensive texturization R&D investment.
- Meat Alternatives:Extruded texturized pulse protein displaces soy in premium burger and sausage applications. Clean-label positioning favors allergen-free pulse bases.
- Dairy Alternatives:Beverage formulators seek emulsion-stable protein sources with neutral flavor profiles for milk and yogurt analogs. Flavor masking technology gaps currently constrain penetration.
- Bakery Products:Gluten-free bread and pastry applications absorb native pulse starches for structure and moisture retention.
- Snacks:Extruded and puffed formats incorporate pulse flours for protein fortification and texture modification.
Revenue concentration sits with Meat Alternatives; Dairy Alternatives gains share fastest on beverage pipeline expansion.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with large manufacturers bypassing intermediaries while small-batch formulators rely on specialized distributors.
- Supermarkets:Branded consumer packaged goods with finished-product pulse protein positioning reach retail shelves through conventional grocery networks.
- Export:Bulk ingredient shipments from Canadian prairie fractionators supply European and Asian processing facilities.
- Health Food Stores:Niche protein powder and supplement brands target direct-to-consumer fortification use.
- Online Retail:Home-use pulse protein ingredients for recipe fortification remain underpenetrated in direct channels.
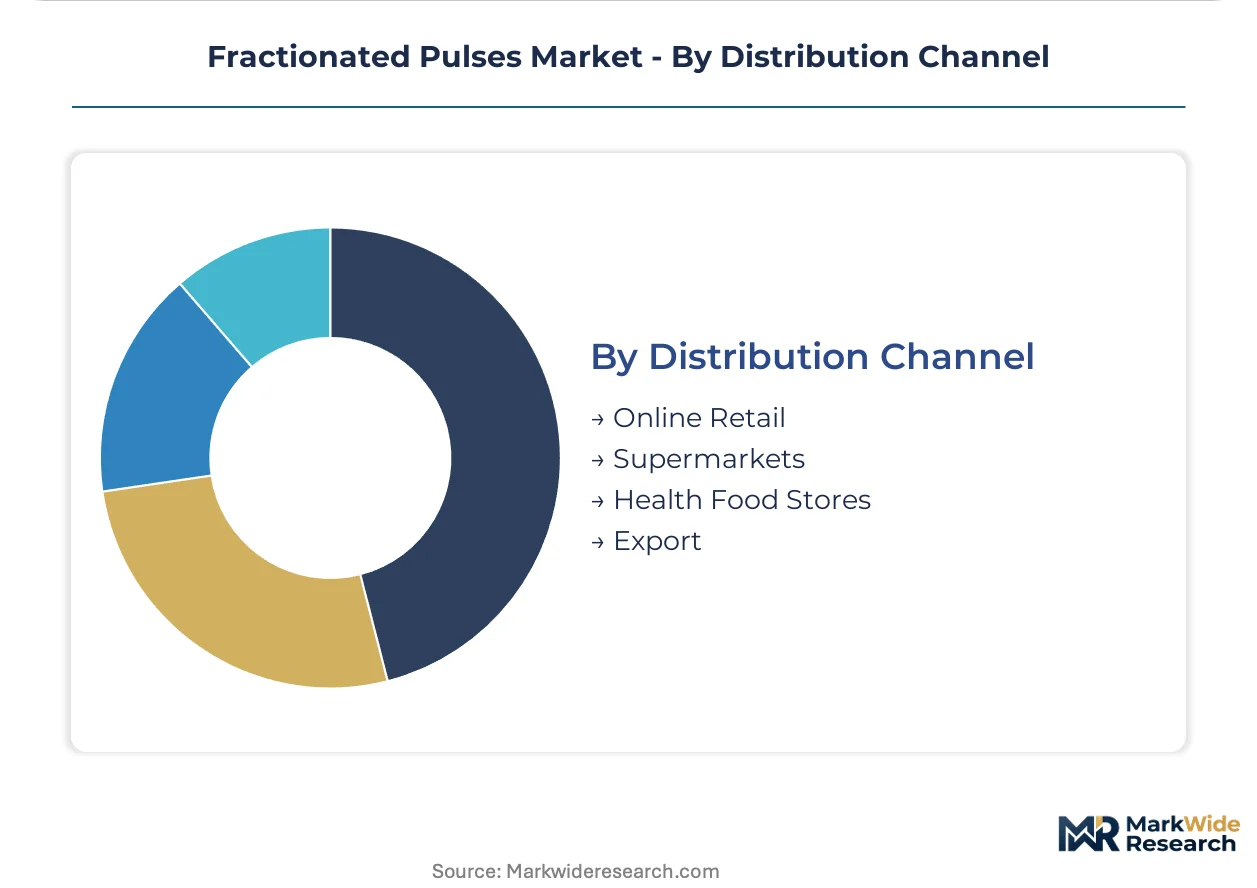
Shipment volumes channel through Export; Online Retail expands most quickly on home-use positioning experiments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Saskatchewan and Alberta concentrate North American fractionation capacity through tax-advantaged processing infrastructure. India's PLI scheme zones are accelerating domestic pulse protein manufacturing scale-up.
United States
California and Illinois R&D clusters demand dedicated supplier technical service staffing for meat alternative formulation. The FDA maintains stringent identity standards for pulse-derived ingredients under the Federal Food, Drug, and Cosmetic Act. Chicago-area extrusion technology centers are expanding pilot-scale texturization capacity for burger and sausage applications.
Canada
Saskatchewan prairie output dominates high-quality yellow pea feedstock for global fractionation supply. Prairie provinces weather volatility propagates directly into isolate pricing instability for international buyers. AGT Food and Ingredients leverages vertically integrated supply chains from Saskatchewan pulse farms to fractionation facilities.
Germany
REACH compliance documentation requirements now extend to novel protein isolates and modified starches entering food chains. ECHA's extended safety data requirements are forcing retroactive toxicological dossier compilation for legacy product lines. Regional bakery and snack manufacturers in Bavaria and Baden-Württemberg are adopting air-classification systems for in-house protein concentrate production.
India
Government-backed pulse processing infrastructure under the PLI scheme is expanding domestic fractionation capacity. The FSSAI has implemented progressively tighter contaminant thresholds for processed pulse products. State-sponsored cold storage and dehulling investments in Maharashtra and Gujarat are reducing feedstock loss rates for protein concentrate production.
France
Roquette Frères S.A. anchors wet-fractionation expertise through long-standing relationships with European bakery and dairy alternative manufacturers. The EU Green Deal's sustainable protein targets are compressing ingredient sourcing timelines for French food manufacturers. Lille-based application laboratories are accelerating qualification of pulse isolates for institutional procurement contracts.
Fractionated Pulses Market Competitive Landscape
Canadian prairie producers anchor one tier; European wet-fractionation specialists hold premium positioning through application technical service. The vendor base splits between vertically integrated agricultural processors and standalone ingredient technology firms. Three archetypes dominate: farm-to-fractionation integrators, R&D-heavy texture systems developers, and proprietary process technology licensors. Capacity expansion and multi-year partnership structures with co-development clauses represent the dominant competitive vectors.
Within the integrator archetype, AGT Food and Ingredients and Cargill exemplify backward control over upstream feedstock supply. Ingredion Incorporated occupies a position representing deep investment in texturized protein systems. Roquette Frères S.A. anchors the European specialist tier through wet-fractionation process expertise. These three names illustrate how geographic origin and corporate structure correlate with strategic positioning across the value chain.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| Ingredion Incorporated |
| Axiom Foods Inc. |
| Emsland Group |
| Avena Foods Ltd. |
| Cargill |
| Nutripea |
| Roquette Frères S.A. |
| Archer-Daniels-Midland Company |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainable protein procurement mandates gate qualified supply access for European food manufacturers, compressing certification timelines and anchoring premium-tier pricing to verified carbon footprint documentation. Buyers without compliant supplier networks face exclusion from institutional contracts, forcing rapid qualification spend that feeds through into ingredient cost structures.
Pricing Analysis
Short lead-time premiums dominate spot procurement for yellow pea protein isolates, with Canadian prairie weather volatility compressing availability windows and amplifying price spikes. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant isolates from conventional grades and feed-tier concentrates. Cost compression in standard grades is intensifying because Indian PLI scheme capacity expansion is flooding starch and flour markets. Compound feed producers exhibit highest price sensitivity; meat alternative manufacturers absorb premiums for texturization-ready isolates.
Supply Chain Analysis
Refurbished dehulling equipment and repurposed wet-fractionation lines from European oilseed processing are absorbing capital flows into secondary pulse protein markets. Saskatchewan, Alberta, and Manitoba concentrate North American feedstock supply; Maharashtra and Gujarat anchor Indian processing expansion. Fractionation capacity draws from yellow pea, faba bean, and lentil cultivation zones. Single-source vulnerability concentrates in Saskatchewan prairie output, where drought risk propagates directly into global isolate pricing. Distribution runs through bulk ingredient export channels to European and Asian processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet-fractionation process intensification is displacing legacy dry-milling infrastructure, with closed-loop water recovery and protein yield optimization becoming table stakes for cost-competitive supply.
For Market Incumbents: Anticipate margin compression from Indian PLI scheme capacity by securing long-term offtake contracts with Maharashtra and Gujarat processors before qualification pipelines saturate. Defend positioning through backward integration into organic-certified Saskatchewan acreage, as three-year transition timelines create captive supply scarcity. Prioritize enzymatic flavor masking R&D to unlock dairy alternative pricing premiums currently captured by soy isolates. For New Entrants and Emerging Players: Launch via direct-to-consumer protein powder channels in Indian urban markets, where home-use fortification remains underpenetrated and institutional buyer concentration is bypassed. Target faba bean fractionation white space in European protein deficit regions, leveraging low allergenicity positioning for pediatric nutrition contracts. Exploit air-classification technology partnerships with German regional bakery manufacturers seeking in-house concentrate production without wet-process capital burden. For Investors and Strategic Acquirers: Roquette Frères S.A.'s acceleration of Lille application laboratory staffing is the leading indicator that institutional procurement contract qualification is becoming the bottleneck asset in European pulse protein supply. Five-to-ten-year viability hinges on wet-fractionation technical service capabilities rather than commodity processing scale. Acquisition targets should prioritize proprietary enzyme treatment IP for flavor neutrality and established relationships with EU Green Deal-compliant ingredient buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Captures Saskatchewan acreage ahead of three-year certification timelines. |
| Enzymatic Flavor Masking R&D Investment | Unlocks dairy alternative segment premiums currently blocked by beany off-notes. |
| Air-Classification Technology Licensing | Enables German and Dutch regional manufacturers to bypass centralized wet-fractionation. |
| Multi-Year Partnership Structures with Co-Development Clauses | Locks California and Illinois meat alternative R&D clusters into dedicated technical service. |
| Faba Bean Fractionation Capacity Buildout | Secures first-mover positioning in European high-yield crop with low allergenicity profile. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with pulse processing plant managers, procurement leads at meat alternative manufacturers, distribution channel partners, and technical R&D directors at fractionation facilities. FDA identity standards documentation, ECHA REACH substance registration databases, FSSAI contaminant threshold notifications, and EU Green Deal procurement specification releases provided regulatory boundary conditions. Bottom-up capacity modeling across Saskatchewan, Alberta, Maharashtra, and Gujarat facilities triangulated against top-down ingredient demand estimates from food and beverage formulation pipelines.
Data-stream reconciliation across production volume records, import-export flows, and end-use consumption patterns informed the analytical framework. Segmentation dimensions modeled include product type tier, application intensity, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories. Forecast inputs incorporated PLI scheme capacity commissioning schedules and REACH compliance timeline compression effects.
Prairie weather volatility, ECHA documentation requirement extensions, and flavor masking technology breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding sustained EU Green Deal procurement mandate enforcement and Indian infrastructure investment continuity. Practitioners should monitor Saskatchewan drought indices, ECHA substance registration backlog data, and enzymatic treatment patent filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Oat Protein Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
India Pea Protein Market