
 Skimmed Milk Powder Market | 2026-2036
Skimmed Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Skimmed Milk Powder Market Analytics
Infant formula manufacturing is broadening its share of skimmed milk powder offtake as birth-rate resilience in select markets sustains premium ingredient demand. Fonterra Co-operative Group Limited leverages its New Zealand-sourced milk pools to dominate bulk ingredient supply chains into Asia. Lactalis Group anchors European production through backward integration into cooperative dairy networks. Arla Foods amba differentiates via farmer-owned governance and sustainability certifications that command shelf-space premiums.
Skimmed milk powder consists of dehydrated non-fat milk solids, typically containing less than 1.5% milk fat and standardized to 34-36% protein content by weight, produced through spray drying or roller drying of pasteurized skim milk for extended shelf stability and reconstitution flexibility. The ingredient serves as a functional protein and solids source across reconstituted dairy, bakery systems, and specialized nutrition formulations. Instant skimmed milk powder occupies the premium tier where cold-water dispersibility commands price premiums over standard spray-dried grades. Organic skimmed milk powder represents the fastest-growing product category as clean-label requirements from nutraceutical companies and retail private labels tighten ingredient provenance standards. Application demand through functional foods is deepening as fortification with vitamins, minerals, and bioactive peptides expands beyond traditional dairy reconstitution.
The EU enforces REACH chemical safety standards and F-Gas Regulation compliance on processing equipment, while the FDA maintains Grade A Pasteurized Milk Ordinance standards that govern import eligibility into the United States. Codex Alimentarius standards coordinated through WHO and FAO provide the international reference point for cross-border trade in dairy powders, with national regulators in India and China adopting aligned but distinct domestic benchmarks. Stakeholders must monitor divergence between EU sustainability disclosure rules under CSRD and emerging carbon-border adjustment mechanisms that could reshape competitive access for powder exporters from less regulated origins.
Market Dynamics
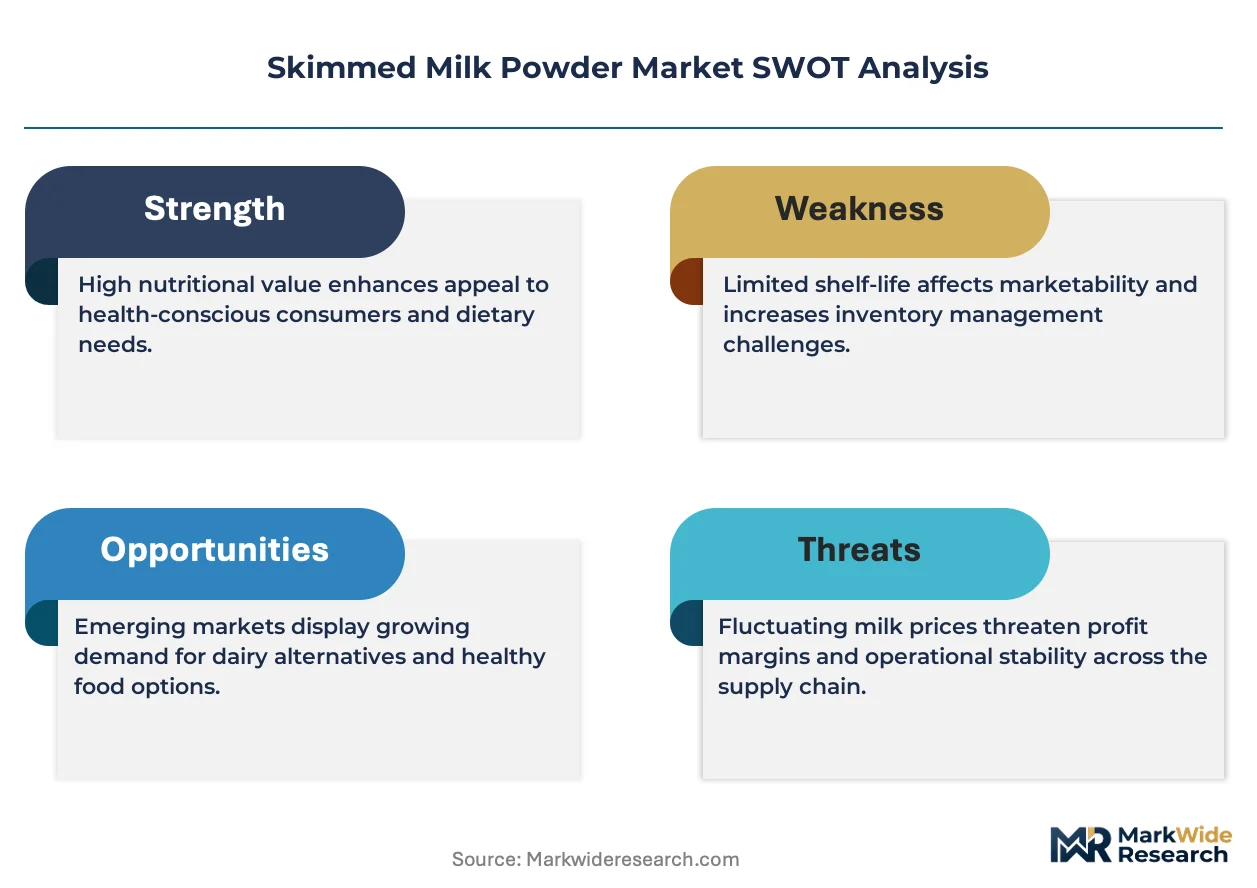
The EU F-Gas Regulation is forcing dairy processors to retrofit spray-drying equipment with lower-GWP refrigerants, compressing operating margins while tightening compliance timelines for cross-border powder shipments.
Growth Catalysts
- India's PLI scheme for food processing:The incentive framework is accelerating capacity additions across Gujarat and Maharashtra, drawing multinational infant formula manufacturers to establish regional blending facilities.
- Instant powder dispersibility standards:Cold-water soluble variants are commanding shelf-space premiums in Southeast Asian retail channels where refrigeration infrastructure remains limited.
- REACH chemical safety alignment:Harmonized substance registration requirements are reducing technical barriers for EU-sourced powders entering Asian nutraceutical supply chains.
Market Restraints
- Whole milk powder substitution:Bakery and confectionery formulators in price-sensitive markets are reformulating toward full-fat alternatives when fat-content regulations permit.
- New Zealand supply concentration:Fonterra's cooperative dominance over Oceania milk pools creates single-origin vulnerability for Asian buyers dependent on bulk ingredient imports.
- EU carbon-border adjustment exposure:Powder exporters from less regulated origins face accumulating compliance costs as the CBAM phase-in tightens emissions documentation requirements.
Strategic Opportunities
- Organic certification pipelines:Clean-label requirements from European retail private labels are tightening ingredient provenance standards, opening premium positioning for certified suppliers.
- Bioactive peptide fortification:Functional food manufacturers are embedding skimmed milk powder as a protein carrier for mineral and vitamin enrichment beyond traditional dairy reconstitution.
- Spray-drying energy recovery systems:Heat-exchanger retrofits are reducing natural gas intensity per ton of powder output, aligning processing economics with CSRD disclosure mandates.
Industry Challenges
- Grade A Pasteurized Milk Ordinance compliance:FDA import eligibility standards require extensive documentation of farm-level hygiene protocols, extending certification timelines for new market entrants.
- Spray-dryer operator skill scarcity:Specialized knowledge of atomization parameters and moisture control is concentrating among aging workforces in traditional dairy regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skimmed Milk Powder Market |
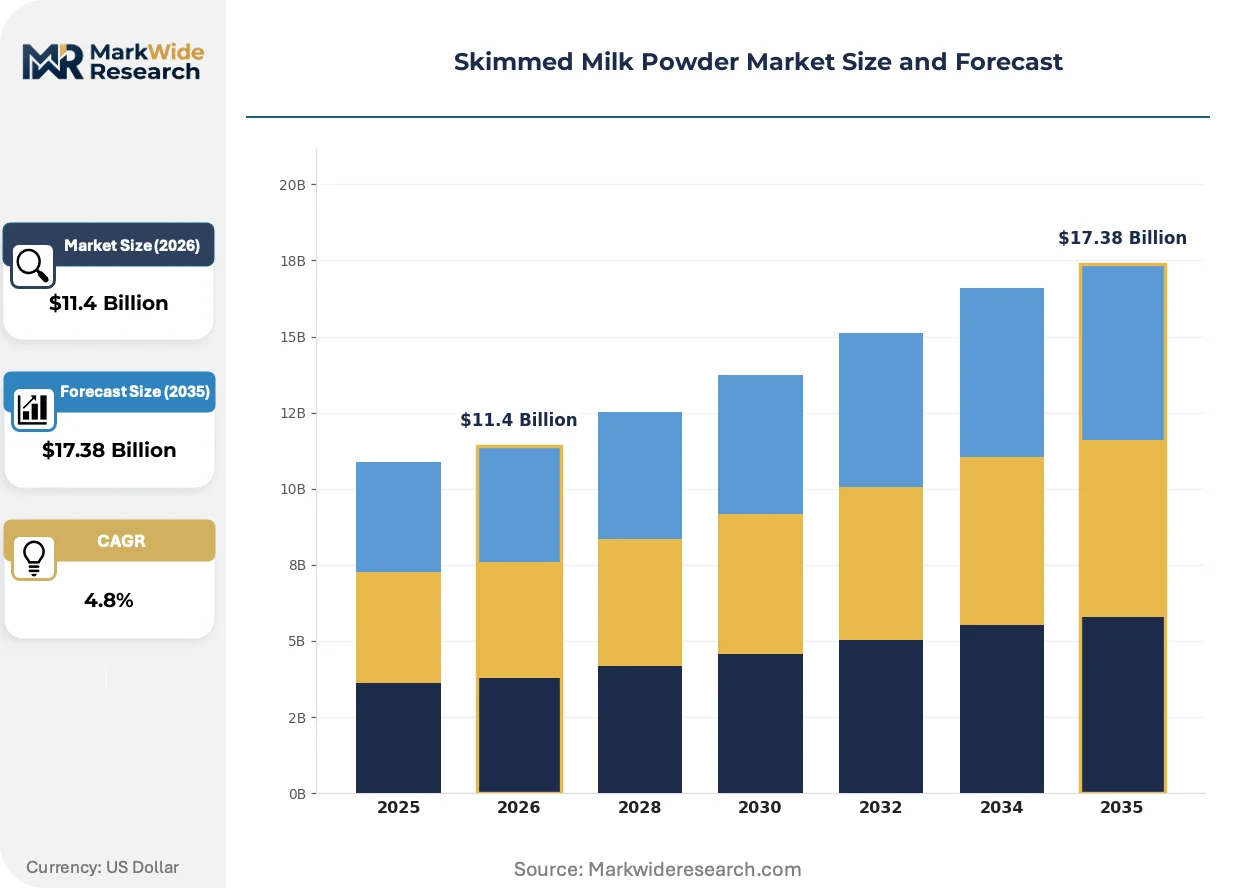
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Skimmed Milk Powder, Spray Dried Skimmed Milk Powder, Retort Skimmed Milk Powder, Organic Skimmed Milk Powder Application: Dairy Products, Bakery Products, Infant Formulas, Functional Foods End User: Retailers, Food Manufacturers, Nutraceutical Companies, HoReCa Packaging Type: Bags, Cans, Tetra Packs, Bottles |
| Companies Covered | Arla Foods amba, Lactalis Group, Fonterra Co-operative Group Limited, Saputo Inc., Dairy Farmers of America, Nestlé S.A., Royal FrieslandCampina N.V., Glanbia plc, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skimmed Milk Powder Market Evolving Landscape
Processing technology and regulatory disclosure requirements are converging to reshape competitive positioning across powder grades, with sustainability certification emerging as a distinct tier of product differentiation.
Membrane filtration pre-concentration is expanding into standard spray-drying workflows, reducing thermal degradation of protein structures during dehydration. Infant formula manufacturers in Germany and the Netherlands are adopting these systems to preserve bioactive whey fractions. The technology is expanding into mid-tier powder grades previously excluded from premium processing economics.
CSRD sustainability disclosure rules are mandating granular emissions reporting across Scope 1-3 boundaries for EU-domiciled dairy processors. The framework requires documented supply-chain carbon intensities from cooperative milk suppliers, reshaping procurement contract structures. Powder exporters to the EU are responding by investing in farm-level methane abatement partnerships to preserve market access.
Direct-procurement relationships between infant formula manufacturers and cooperative dairy networks are displacing traditional commodity broker intermediation. Large-scale buyers in China and Southeast Asia are establishing multi-year offtake agreements with named-region suppliers to secure volume visibility. This pattern is most visible in New Zealand and Denmark where governance structures facilitate transparent origin documentation.
Skimmed Milk Powder Market Segmentation
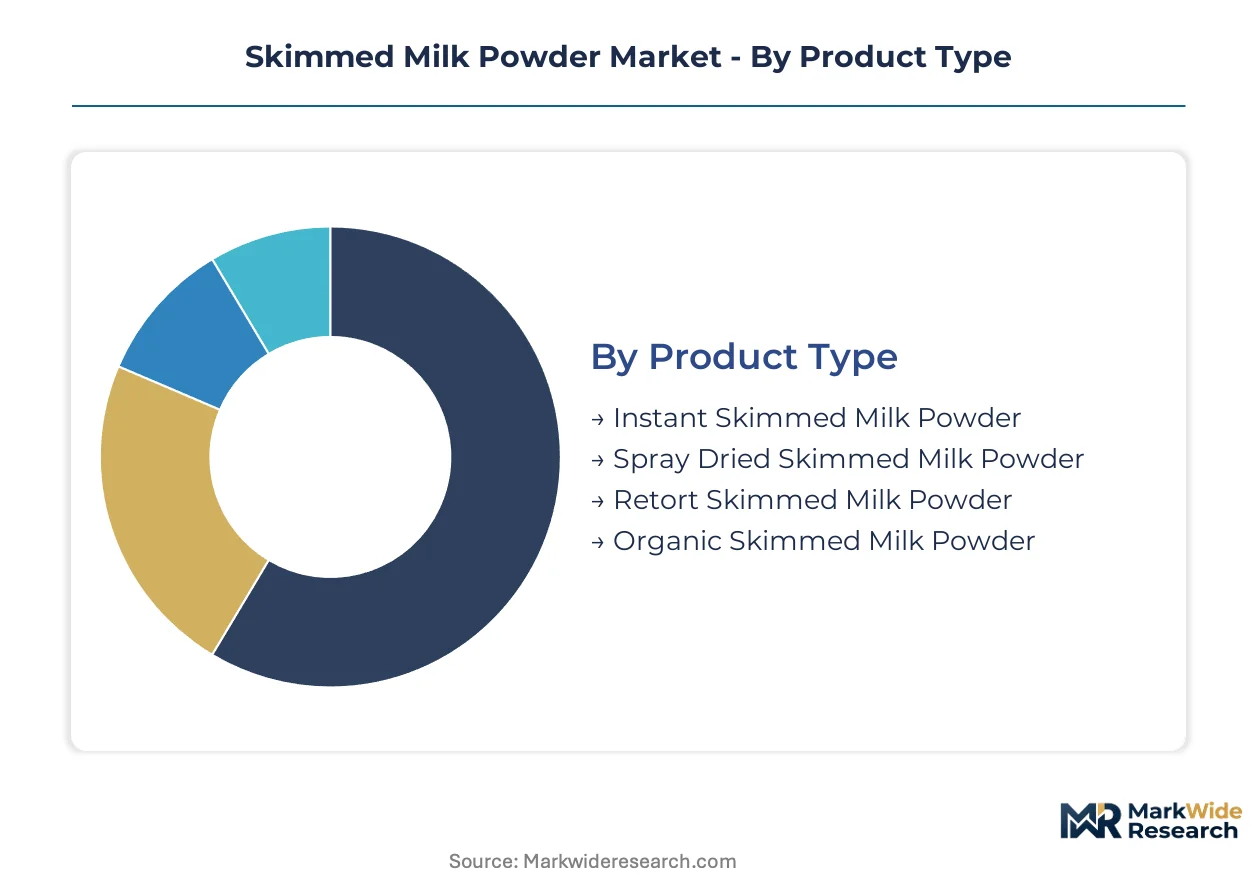
Segmentation in skimmed milk powder tracks divergent compliance burdens across product grades and end-use channels. Each category carries distinct documentation requirements from regulators like the FDA, EFSA, and FSSAI that reshape procurement patterns.
Product Type:
REACH registration and organic certification create tiered regulatory entry barriers across product grades, with instant and organic variants demanding the most extensive substance documentation.
- Instant Skimmed Milk Powder:Agglomerated particles achieve cold-water dispersibility through lecithin coating or steam fusion processes. Infant formula manufacturers in Germany and the Netherlands concentrate procurement here, driven by Southeast Asian retail channels where refrigeration infrastructure remains limited.
- Organic Skimmed Milk Powder:Sourced from herds under certified pasture-access protocols with complete feed-chain traceability. European retail private labels tighten provenance standards fastest here, opening premium positioning for suppliers with EU organic logo accreditation.
- Spray Dried Skimmed Milk Powder:Standard dehydration grade produced through atomization in heated air streams; dominates bulk ingredient volumes into commodity dairy reconstitution.
- Retort Skimmed Milk Powder:Pre-sterilized grade for ultra-high-temperature applications; serves military rations and emergency food programs with extended ambient stability requirements.
Leading the category by volume: Spray Dried Skimmed Milk Powder. Expanding most quickly: Organic Skimmed Milk Powder.
Application:
End-use channels separate by margin structure and formulation complexity, with infant nutrition commanding the steepest premium tiers.
- Infant Formulas:Precision protein standardization to 34-36% content with bioactive fraction preservation. Chinese and Southeast Asian manufacturers concentrate demand here, securing multi-year offtake agreements with named-region New Zealand and Danish suppliers for volume visibility.
- Functional Foods:Fortification vectors for minerals, vitamins, and bioactive peptides beyond traditional dairy reconstitution. Nutraceutical companies in India and Germany deepen embedding of skimmed milk powder as protein carriers, tightening clean-label requirements.
- Dairy Products:Reconstituted milk, yogurt, and cheese systems where cost-efficient solids replacement drives procurement decisions.
- Bakery Products:Protein enrichment and Maillard browning control in bread and confectionery systems; price-sensitive formulators substitute toward whole milk powder where fat regulations permit.
Commanding the highest price realization: Infant Formulas. Steepest expansion trajectory: Functional Foods.
End User:
Procurement scale and technical specification depth vary sharply across buyer types, from bulk commodity tenders to traceability-intensive direct relationships.
- Food Manufacturers:Large-scale dairy and bakery processors with formulation R&D capabilities. India's PLI scheme for food processing draws multinational infant formula manufacturers to establish regional blending facilities in Gujarat and Maharashtra.
- Nutraceutical Companies:Specialized nutrition formulators requiring documented bioactive content and low-heat processing verification.
- Retailers:Private label operators sourcing packed consumer formats; European chains increasingly mandate CSRD-aligned Scope 3 emissions disclosure from cooperative suppliers.
- HoReCa:Hotels, restaurants, and catering operations prioritizing reconstitution convenience and ambient storage stability.
Dominating procurement volume: Food Manufacturers. Gaining share fastest: Nutraceutical Companies.
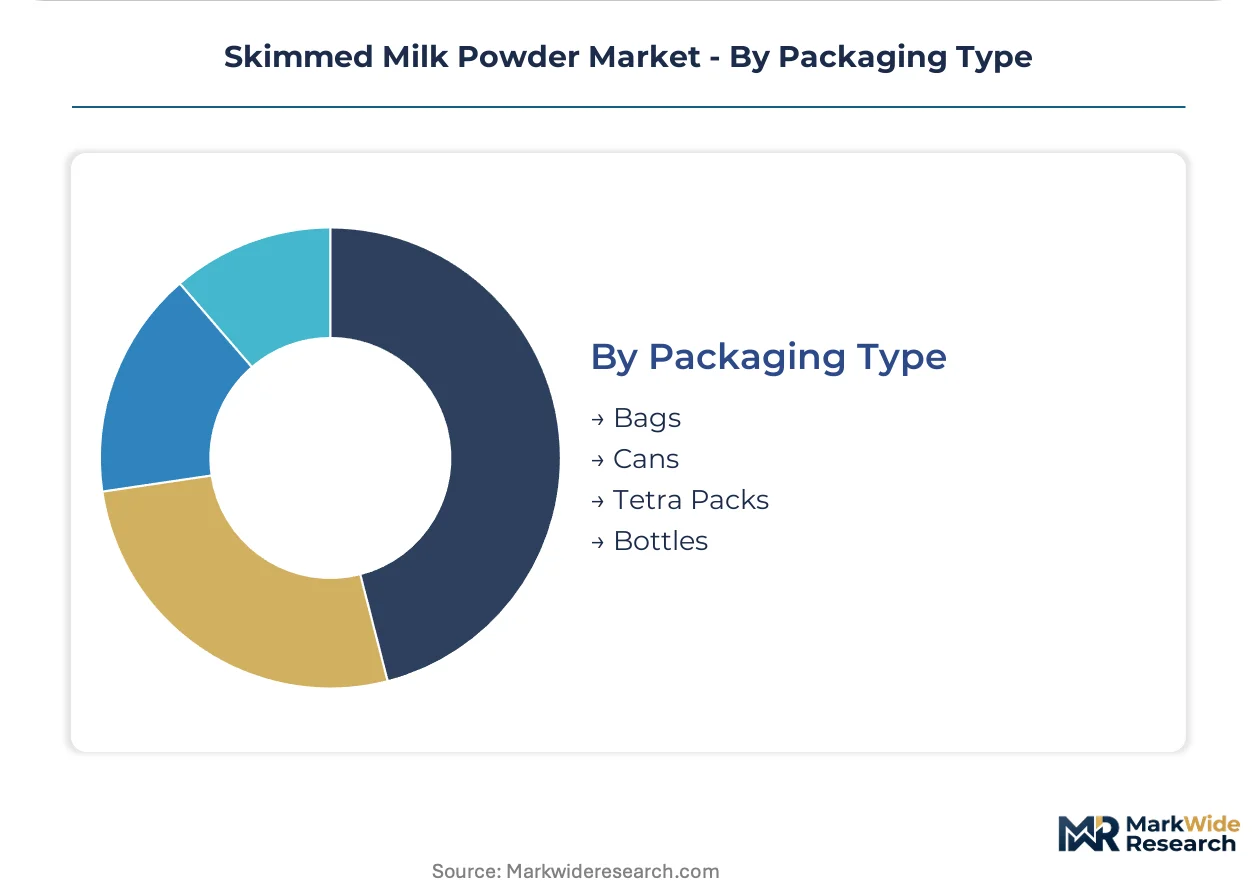
Packaging Type:
Packaging selection tracks shelf-life requirements, moisture sensitivity, and channel-specific handling economics across the value chain.
- Bags:Multi-wall paper or polyethylene bulk formats for industrial ingredient supply; dominates B2B powder shipments to food manufacturers.
- Cans:Metal containers with nitrogen flushing for premium retail grades requiring extended ambient stability.
- Tetra Packs:Aseptic carton systems for reconstituted liquid formats in emerging market retail.
- Bottles:PET or HDPE containers for instant-dissolve consumer portions in convenience channels.
Leading by shipment volume: Bags. Climbing the fastest: Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing has established Gujarat and Maharashtra as the dominant tax-incentive zones for skimmed milk powder capacity expansion, drawing multinational infant formula manufacturers to establish regional blending facilities.
India
Domestic dairy consumption and export-oriented processing capacity are accelerating demand for instant and organic powder variants. FSSAI standards govern protein content labeling and bioactive preservation claims across reconstituted dairy applications. The Anand milk cooperative cluster in Gujarat anchors backward integration into cooperative dairy networks for traceable organic supply.
New Zealand
Bulk ingredient exports to Asian infant formula manufacturers concentrate procurement through named-region multi-year offtake agreements. The country's national dairy regulator maintains Grade A equivalent standards that satisfy FDA import eligibility for cross-border shipments. Waikato dairy processing corridors host spray-drying facilities with membrane filtration pre-concentration systems.
Netherlands
German and Dutch infant formula manufacturers drive premium-tier demand for cold-water dispersible instant grades. REACH chemical safety alignment reduces technical barriers for EU-sourced powders entering Asian nutraceutical channels. FrieslandCampina's cooperative network in the northern provinces supplies documented Scope 3 emissions data under CSRD disclosure mandates.
United States
Functional food fortification and bakery applications sustain standard spray-dried grade volumes despite whole milk powder substitution pressure. FDA Grade A Pasteurized Milk Ordinance compliance requirements extend certification timelines for new market entrants. Wisconsin and California dairy belts concentrate processing infrastructure for domestic reconstituted milk systems.
Denmark
Farmer-owned governance structures and sustainability certifications command shelf-space premiums in European retail private labels. EU F-Gas Regulation compliance is forcing spray-drying equipment retrofits with lower-GWP refrigerants across Jutland processing facilities. Arla Foods amba's cooperative model provides transparent origin documentation for direct-procurement relationships with Asian buyers.
Skimmed Milk Powder Market Competitive Landscape
Top-tier vendors anchor cooperative and multinational dairy networks, while regional processors occupy mid-tier commodity supply. The market structure concentrates around backward-integrated milk pool control and sustainability certification pipelines. Three archetypes dominate: farmer-owned cooperatives with governance transparency, multinational dairy conglomerates with portfolio diversification, and specialized organic certifiers with provenance documentation. Competitive moves center on multi-year offtake agreements with named-region suppliers and spray-drying energy recovery system investments.
Within the farmer-owned cooperative archetype, Arla Foods amba and Fonterra Co-operative Group Limited exemplify governance structures that facilitate transparent origin documentation for Asian buyers. Lactalis Group occupies a position among multinational dairy conglomerates leveraging European production scale.
| Leading Market Players |
|---|
| Arla Foods amba |
| Lactalis Group |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Dairy Farmers of America |
| Nestlé S.A. |
| Royal FrieslandCampina N.V. |
| Glanbia plc |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
Membrane filtration pre-concentration adoption across European spray-drying facilities is simultaneously lowering thermal degradation losses and concentrating processing capacity among cooperative networks with capital reserves. This technology shift tightens cost economics for mid-tier operators while amplifying price-setting power for integrated milk pool controllers in New Zealand and Denmark.
Pricing Analysis
Short lead-time premiums dominate spot procurement, with Asian infant formula manufacturers paying shelf-space premiums for cold-water dispersible instant grades against standard spray-dried contract baselines. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified EU-origin powder from commodity bulk grades and retort-sterilized emergency stock. Cost compression in standard grades intensifies because whole milk powder substitution pressure from bakery formulators constrains margin recovery. Food manufacturers exhibit highest price sensitivity through volume tender processes, while nutraceutical companies absorb premiums for documented bioactive preservation.
Supply Chain Analysis
Container freight rate volatility from Oceania to Southeast Asian ports directly amplifies landed cost spreads between named-region cooperative suppliers and spot-market intermediaries. Milk pool concentration centers on New Zealand, Denmark, and the Netherlands, where backward integration into cooperative networks secures traceable organic feed-chain documentation. Raw material flows draw from pasture-based herds, energy-intensive spray-drying natural gas inputs, and lecithin coating agents for instant grades. Single-source vulnerability runs through Fonterra's dominance over Oceania bulk ingredient exports. Distribution runs through direct-procurement multi-year offtake agreements displacing traditional commodity broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying energy recovery systems are displacing legacy natural gas-intensive dehydration workflows, compressing operating margins for facilities without heat-exchanger retrofits and reshaping competitive access to EU markets under CSRD disclosure mandates.
For Market Incumbents: Anchor defensive positioning through farm-level methane abatement partnerships that preserve EU market access against carbon-border adjustment accumulation. Deepen backward integration into Gujarat and Maharashtra cooperative networks to capture India's PLI scheme incentives before multinational infant formula manufacturers consolidate regional blending capacity. Prioritize membrane filtration pre-concentration investments to preserve bioactive fraction premiums against standard-grade commoditization pressure. For New Entrants and Emerging Players: Capture white-space in organic certification pipelines serving European retail private labels with EU organic logo accreditation as provenance standards tighten fastest in this tier. Target India's functional foods segment where nutraceutical companies deepen skimmed milk powder embedding as protein carriers for mineral and vitamin fortification. Establish direct-procurement relationships with named-region Danish or New Zealand cooperative suppliers to bypass commodity broker intermediation. For Investors and Strategic Acquirers: Exit pathways concentrate in farmer-owned cooperative archetypes with transparent governance structures facilitating Asian buyer direct-procurement relationships and documented Scope 3 emissions data under CSRD mandates. Long-term viability hinges on processing facilities with completed F-Gas Regulation refrigerant retrofits and heat-exchanger energy recovery systems installed. Watch for divergence between EU sustainability disclosure enforcement and emerging market regulatory adoption as the inflection indicator for competitive access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Energy Recovery Retrofit | Heat-exchanger installations align processing economics with CSRD Scope 1 disclosure mandates from EU-domiciled dairy processors. |
| Organic Certification Pipeline Investment | EU organic logo accreditation opens premium positioning as European retail private labels tighten ingredient provenance standards. |
| Direct-Procurement Offtake Agreement | Multi-year named-region contracts with New Zealand or Danish cooperatives secure volume visibility for Asian infant formula manufacturers. |
| Membrane Filtration Pre-Concentration Adoption | German and Dutch infant formula manufacturers deploy these systems to preserve bioactive whey fractions for premium-grade output. |
| Farm-Level Methane Abatement Partnership | Documented supply-chain carbon intensities from cooperative milk suppliers preserve EU market access under accumulating CBAM compliance costs. |
Research Methodology
Document review covered EU F-Gas Regulation implementation timelines, FSSAI protein content labeling standards, and FDA Grade A Pasteurized Milk Ordinance import eligibility requirements, complemented by interviews with spray-drying facility operators, infant formula procurement leads, cooperative dairy network managers, and European retail private label category buyers. Secondary validation drew from customs trade data on dairy powder shipments, Codex Alimentarius standards documentation, and SEC filings from listed dairy processors. Bottom-up capacity assessments across Gujarat and Maharashtra processing corridors were triangulated against top-down demand estimates from nutraceutical and bakery formulation channels.
Segment-level value and volume trajectories were generated through econometric modeling across product type, application, end user, and packaging format dimensions, with additional stratification by organic certification status and cold-water dispersibility grade. CAGRs were derived from regression analysis against milk pool yield trends, energy cost inflation assumptions, and regulatory compliance cost accumulation. Key forecast inputs included PLI scheme capacity addition schedules in India and F-Gas Regulation retrofit completion timelines across EU member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon-border adjustment mechanism phase-in stringency and whole milk powder substitution elasticity in price-sensitive bakery markets. Forecasts reflect documented assumptions on cooperative milk pool yield stability and spray-dryer operator skill scarcity concentration in aging workforces. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Textured Butter Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
US Cheese Market
Dairy Products
Savory Dairy Products Market
Dairy Products
North America A2 Milk Market
Dairy Products
Skimmed Milk Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Filled Cheese Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Dairy Carton Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Cheese Shreds Market