
 Cream and Soft Cheese Market | 2026-2036
Cream and Soft Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Cream and Soft Cheese Market Analysis
Market Context with Strategic Players
Multi-pack bundling of flavored cream cheese varieties is restructuring retail shelf dynamics and pushing buyers toward larger-format purchases. The Kraft Heinz Company leverages its refrigerated logistics network to dominate North American grocery channels. Arla Foods sustains cooperative sourcing advantages across Northern European dairy belts. Groupe Lactalis specializes in regional soft cheese portfolios that anchor its position in traditional European markets.
Technical Definition and Structural Segments
Cream and soft cheese encompasses fresh, unripened dairy products with moisture content exceeding 50 percent and fat-in-dry-matter ranging from 20 to 75 percent, manufactured through acid or acid-heat coagulation without significant aging. These products serve as functional ingredients in baking, dessert preparation, and spreadable applications where texture and melt behavior determine formulation choices. Cream cheese occupies the largest margin pool among product types due to its versatility across retail and food service channels, while mascarpone generates premium pricing in dessert-focused segments. The food service distribution channel is expanding fastest as restaurants and bakeries increase prepared-item menus, though supermarkets retain volume leadership through private-label penetration.
Regulatory Frame and Forward-Looking Close
The FDA governs pasteurization requirements and labeling standards for interstate cream cheese commerce in the United States, while the EU Green Deal and EFSA frameworks enforce carbon accounting and animal welfare criteria across European production. REACH chemical safety protocols affect packaging material approvals for plastic tubs and vacuum films used in soft cheese distribution. Stakeholders must monitor evolving sustainability disclosure rules and alternative protein competition when allocating R&D budgets across fresh dairy portfolios.
Market Dynamics
The EU Green Deal is forcing dairy processors to restructure carbon accounting across their supply chains while food service operators simultaneously expand soft cheese applications into prepared meal formats. This dual pressure from regulatory compliance and demand diversification is compressing margins for conventional production models.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Member state producers are retrofitting facilities to meet Scope 3 disclosure requirements, creating competitive differentiation for early adopters in German and French retail channels.
- Food service menu expansion:Bakeries and casual dining chains are incorporating mascarpone and cream cheese into savory applications beyond traditional dessert positioning.
- Acid-heat coagulation automation:Continuous processing systems are reducing batch-to-batch variation and enabling scale-up for private-label supermarket contracts.
Market Restraints
- Feed cost volatility:Dairy farm input expenses fluctuate with grain and hay markets, compressing processor margins on standard cream cheese grades.
- Northern European supply concentration:Arla Foods and cooperative networks dominate raw milk procurement in Denmark and Sweden, limiting new entrant access to quality fluid milk.
- Plant-based substitution:Oat and almond-based spreadable alternatives are capturing shelf space in urban supermarket formats targeting flexitarian households.
Strategic Opportunities
- Italian artisan positioning:Mascarpone and ricotta producers can leverage PDO certification gaps in North American markets to command premium pricing.
- Direct-to-foodservice distribution:Refrigerated logistics investments enable bypass of traditional distributor markups for bakery and restaurant accounts.
- REACH-compliant packaging innovation:Bio-based tubs and films meeting ECHA chemical safety standards unlock retail placement in sustainability-focused EU chains.
Industry Challenges
- Microbiological certification timelines:Listeria and Salmonella testing protocols for ready-to-eat soft cheeses extend product release cycles by 48-72 hours.
- Legacy ERP integration:Batch tracking systems for moisture and fat-in-dry-matter compliance require costly upgrades to interface with modern traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream and Soft Cheese Market |
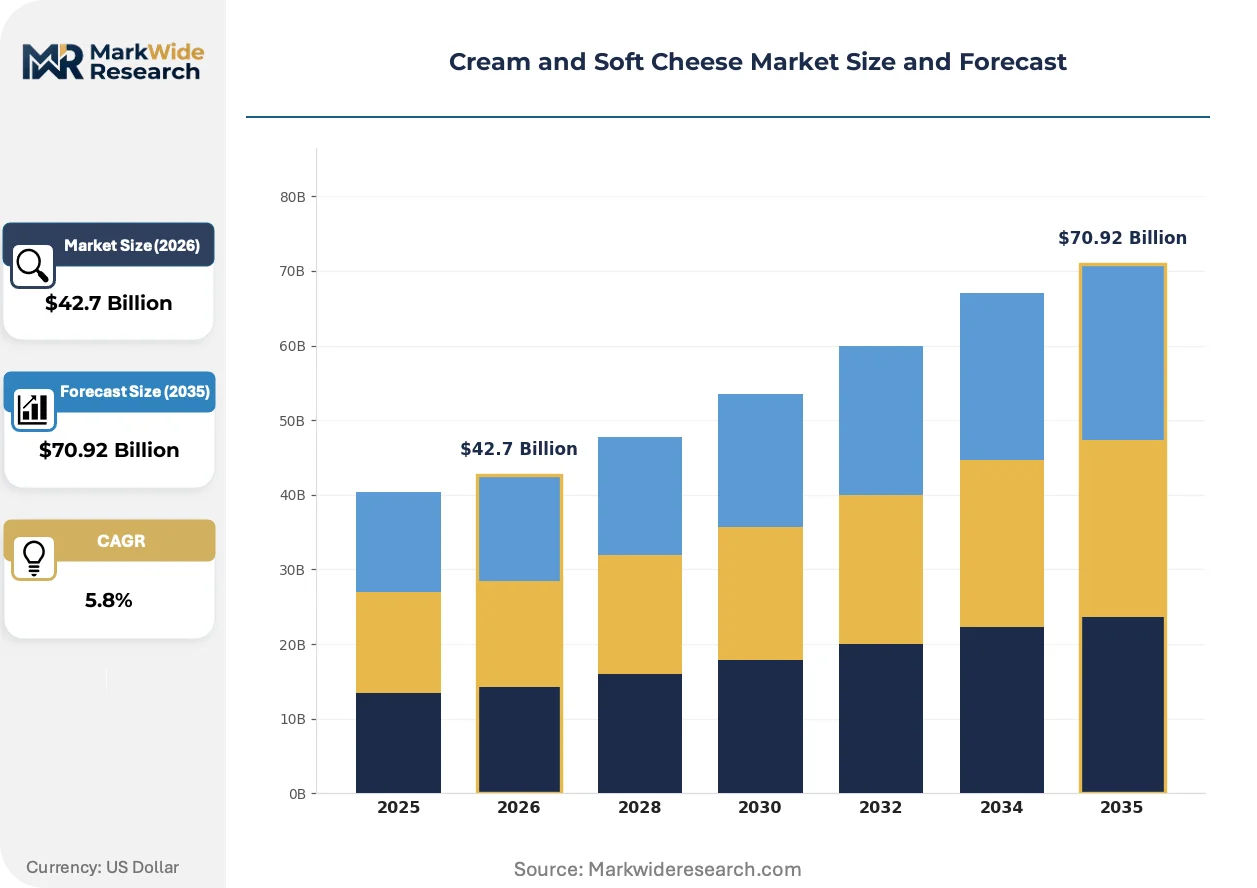
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Mascarpone, Fromage Blanc, Ricotta Packaging Type: Plastic Tub, Glass Jar, Vacuum Pack, Block Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Households, Restaurants, Bakeries, Caterers |
| Companies Covered | The Kraft Heinz Company, Organic Valley, Arla Foods, FrieslandCampina, Galbani, Fonterra Co-operative Group, Groupe Lactalis, Savencia SA, Saputo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream and Soft Cheese Market Emerging Trajectories
Processing technology and sustainability disclosure are converging to reshape how cream and soft cheese moves from dairy farm to retail shelf. The competitive edge is shifting toward carbon-transparent supply chains and functional ingredient positioning.
Precision fermentation for dairy proteins is expanding into cream cheese analog development, with biotechnology firms engineering casein and whey expressions that replicate acid-coagulation behavior. Ingredient suppliers are pitching these inputs to plant-forward brands seeking improved melt and texture performance. This capability is expanding into premium private-label negotiations with supermarket chains evaluating hybrid formulations.
EFSA animal welfare criteria under the EU Green Deal framework are mandating housing condition documentation and transport time limits for dairy herds supplying soft cheese processors. French and German regulators are enforcing these standards through farm audit requirements that affect milk eligibility for PDO-designated products. Italian producers are responding by consolidating supplier bases to reduce compliance fragmentation.
Buyer concentration among bakery chains and prepared-meal manufacturers is compressing supplier negotiation cycles from annual to quarterly terms. Food service distributors are unbundling logistics and merchandising services, forcing cream cheese processors to manage direct delivery scheduling or absorb third-party fees. This restructuring is most visible in German urban markets where bakery cooperatives centralize procurement for multi-outlet operations.
Cream and Soft Cheese Market Segmentation
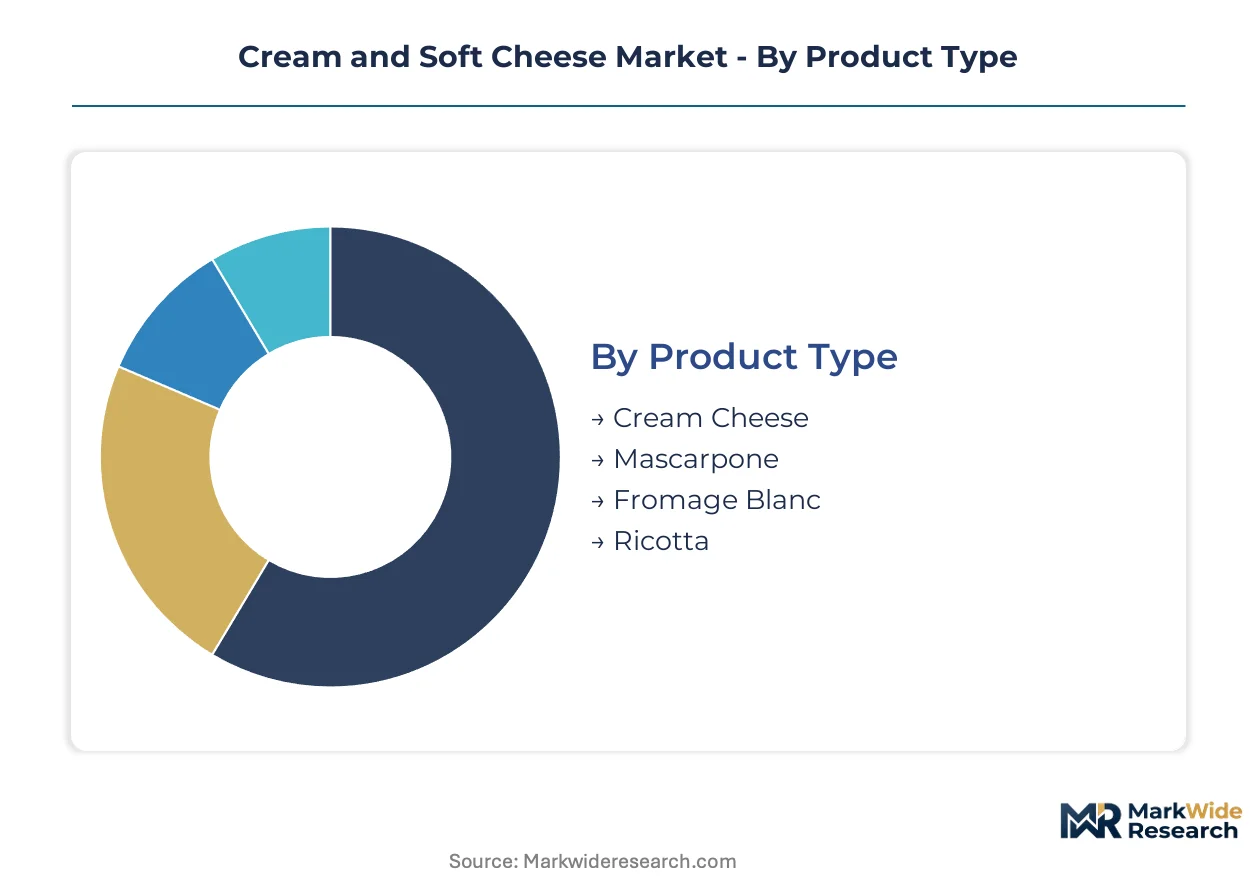
Segmentation in cream and soft cheese markets reveals how moisture content specifications and distribution economics create divergent margin structures across product formats. Understanding these divides enables processors to align production capacity with channel-specific requirements.
Product Type:
Volume concentration sits with standardized spreadable formats while premium capture belongs to Italian-origin specialties with protected designation credentials.
- Cream Cheese:Acid-coagulated fresh cheese with fat-in-dry-matter ranging from 33 to 55 percent and moisture content between 50 and 60 percent, delivering spreadable consistency for bagel applications and cheesecake formulations. Demand concentrates in North American retail channels where private-label penetration drives procurement consolidation toward multi-year supply agreements.
- Mascarpone:Double-cream soft cheese with butterfat content exceeding 60 percent, manufactured through acid-heat coagulation of heavy cream without rennet addition. Italian PDO producers command premium positioning in dessert-focused segments across German and French metropolitan markets where bakery chains centralize procurement.
- Fromage Blanc:French fresh cheese with fat content ranging from 0 to 8 percent, consumed as a dessert base or savory spread in domestic households.
- Ricotta:Whey-derived fresh cheese with granular texture, serving as pasta filling and cannoli ingredient in Italian-American food service operations.
Mature deployment sits with Cream Cheese. Newer deployment is concentrated in Mascarpone.
Packaging Type:
Shelf-life extension and sustainability disclosure requirements are reshaping material selection across retail and food service channels.
- Plastic Tub:Polypropylene containers with tamper-evident lids dominate retail cream cheese distribution, offering 45-60 day refrigerated shelf life and compatibility with high-speed filling lines. German supermarket chains are mandating post-consumer recycled content minimums under EU Green Deal packaging directives.
- Vacuum Pack:Multi-layer barrier films with oxygen transmission rates below 5 cc/m²/day preserve fresh cheese integrity for extended distribution cycles. Food service distributors in France prefer this format for bulk mascarpone delivery to bakery cooperatives.
- Glass Jar:Premium positioning vehicle for artisan ricotta and fromage blanc varieties in specialty retail.
- Block:Foil-wrapped rectangular formats serving industrial bakery and cheesecake manufacturing accounts.
Established infrastructure aligns with Plastic Tub. Sustainability-driven transition is accelerating in Vacuum Pack.
Distribution Channel:
Direct-to-operator routing is gaining share against traditional wholesale intermediation as bakery chains consolidate procurement functions.
- Food Service:Direct delivery to restaurants, bakeries, and prepared-meal manufacturers requiring temperature-controlled logistics and just-in-time scheduling. German urban markets exhibit the steepest expansion trajectory as bakery cooperatives unbundle distributor services.
- Supermarkets:Multi-format retail placement spanning deli counters, dairy cases, and private-label programs. French and Italian hypermarket chains concentrate volume through centralized purchasing agreements with cooperative processors.
- Online Retail:Subscription and same-day delivery platforms targeting urban flexitarian households with specialty cheese assortments.
- Specialty Stores:Independent cheese mongers and gourmet retailers emphasizing PDO certification and farm-specific provenance.
Volume leadership remains with Supermarkets. Margin expansion is concentrating in Food Service.
End User:
Application diversification is fragmenting demand across savory meal preparation and traditional dessert positioning.
- Restaurants:Casual dining and fast-casual chains incorporating cream cheese into savory sauces, stuffed proteins, and appetizer formats beyond conventional dessert applications. Menu innovation in French bistro segments drives mascarpone adoption for risotto enrichment.
- Bakeries:Multi-outlet operations and artisan producers utilizing soft cheeses as filling bases, frosting ingredients, and laminated dough components. Italian bakery chains standardize ricotta specifications across regional production facilities.
- Households:Retail purchasers consuming spreadable formats for breakfast and snacking occasions.
- Caterers:Event-service operators requiring bulk formats with extended holding stability for buffet presentation.
Traditional anchoring sits with Households. Application expansion is concentrating in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Northern European dairy belts while consumption concentrates in metropolitan food service corridors across Western Europe and North America. This geographic mismatch creates refrigerated logistics dependencies that shape margin structures for cream and soft cheese processors.
Germany
Bakery cooperatives in Berlin and Munich are consolidating procurement for multi-outlet operations, driving direct-to-operator distribution models. The EU Green Deal mandates Scope 3 carbon disclosure for dairy processors supplying German retail chains. Bavarian dairy clusters around Munich are retrofitting facilities to meet EFSA animal welfare audit requirements for PDO-eligible milk sourcing.
France
Hypermarket chains in Paris and Lyon centralize purchasing through cooperative processors, concentrating volume in private-label cream cheese programs. ANSM enforces microbiological certification timelines for ready-to-eat soft cheeses distributed through national retail networks. The Île-de-France region anchors dessert-focused mascarpone demand as bistro chains expand risotto and savory applications.
United States
Food service distributors in New York and Chicago are unbundling logistics services, forcing processors to manage direct delivery scheduling for bakery accounts. FDA pasteurization requirements govern interstate cream cheese commerce, extending product release cycles through pathogen testing protocols. The Northeast Corridor exhibits the steepest food service channel expansion as fast-casual chains incorporate cream cheese into savory menu formats.
Italy
PDO-designated mascarpone and ricotta producers in Lombardy and Emilia-Romagna command premium positioning in export markets. Italian regulators under the EU Green Deal framework enforce farm audit requirements affecting milk eligibility for protected designation products. Milan anchors domestic demand concentration while Verona-based processors consolidate supplier bases to reduce compliance fragmentation.
Canada
Supply management frameworks stabilize raw milk pricing for Ontario and Quebec processors manufacturing cream cheese for cross-border retail placement. Health Canada governs labeling standards for dairy products distributed through national supermarket chains. The Toronto metropolitan corridor concentrates food service demand as bakery chains centralize procurement for multi-province operations.
Cream and Soft Cheese Market Vendor Landscape
The competitive structure tilts toward cooperative networks and multinational dairy conglomerates with captive refrigerated logistics. Tiered player concentration spans global conglomerates with multi-brand portfolios, regional cooperatives controlling raw milk procurement, and artisan specialists leveraging PDO certification. Dominant competitive moves include direct-to-foodservice distribution investments and sustainability certification acquisition for EU Green Deal compliance.
Within the multinational conglomerate tier, The Kraft Heinz Company and Groupe Lactalis occupy positions defined by refrigerated supply chain scale and regional brand portfolio depth. Arla Foods exemplifies the cooperative archetype through Northern European dairy belt sourcing integration. These three anchors represent divergent structural approaches to margin defense against plant-based substitution pressure and food service buyer consolidation.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Organic Valley |
| Arla Foods |
| FrieslandCampina |
| Galbani |
| Fonterra Co-operative Group |
| Groupe Lactalis |
| Savencia SA |
| Saputo Inc. |
| Others |
Supply Flow & Price Mechanics
Bakery cooperative procurement consolidation in Germany is forcing cream cheese processors to restructure delivery scheduling and absorb logistics costs, compressing margins on standard grades while premium PDO-certified varieties retain pricing power through supply scarcity.
Pricing Analysis
Margin tightening in economy-tier cream cheese reflects private-label concentration among French and German supermarket chains. Three-tier pricing structure across premium PDO mascarpone, standard industrial cream cheese, and economy private-label spreads governs the market. Cost-down pressure accelerates as food service distributors unbundle services and processors face direct delivery requirements. Private-label buyers exhibit highest price sensitivity, while artisan bakery chains accept premiums for Italian-origin certification.
Supply Chain Analysis
EFSA animal welfare certification gating is restructuring supplier eligibility across European production networks. Raw milk procurement concentrates in Denmark, Sweden, and Northern Germany through cooperative networks. Production draws from fluid milk, heavy cream, and whey inputs, with feed cost volatility transmitting directly to processor margins. Single-source vulnerability sits with Northern European dairy belt concentration for PDO-eligible milk. Distribution runs through refrigerated logistics partnerships serving direct-to-foodservice and supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing conventional acid-coagulation methods for dairy protein production, creating capability gaps between biotechnology-advantaged processors and legacy operators dependent on farm-sourced milk.
For Market Incumbents: Anchor market position through backward integration into certified dairy herds meeting EU Green Deal animal welfare standards, while investing in precision fermentation R&D partnerships to offset plant-based substitution pressure. Cooperative processors must consolidate supplier bases to reduce compliance fragmentation across German and French audit requirements. For New Entrants and Emerging Players: Enter via direct-to-foodservice distribution models targeting bakery cooperatives in Berlin and Munich, where incumbent markups create white-space opportunity. Italian PDO certification gaps in North American markets offer premium positioning for artisan mascarpone and ricotta specialists. Leverage refrigerated logistics partnerships to bypass traditional distributor channels. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation-enabled dairy protein developers given accelerating food service demand for hybrid formulations. Long-term viability favors biotechnology firms with casein expression capabilities and established co-manufacturing relationships. Watch for inflection when major supermarket chains initiate hybrid cream cheese private-label negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Enables casein and whey protein production that replicates traditional acid-coagulation texture for hybrid formulations. |
| Direct-to-Foodservice Distribution | Bypasses traditional distributor markups for bakery cooperatives in German urban markets. |
| PDO Certification Acquisition | Unlocks premium positioning for Italian-origin mascarpone and ricotta in North American retail channels. |
| REACH-Compliant Packaging Transition | Secures retail placement in EU supermarket chains mandating post-consumer recycled content minimums. |
| Supplier Base Consolidation | Reduces EFSA animal welfare audit fragmentation for Lombardy and Emilia-Romagna processors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving dairy processing executives, food service procurement managers, refrigerated logistics operators, and cooperative sourcing directors. EFSA guidance documents, FDA pasteurization standards, and EU Green Deal implementation reports provided regulatory calibration. Bottom-up volume modeling triangulated against top-down value estimates from customs and trade databases.
Data-stream reconciliation across production capacity surveys, retail audit data, and food service distribution records enabled forecast construction across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-use application, with geographic regulatory clusters treated as distinct forecast inputs. CAGRs derived from trend extrapolation of volume and value trajectories, adjusted for feed cost volatility and plant-based substitution elasticity.
Revisions become necessary when EU Green Deal implementation timelines accelerate, precision fermentation achieves cost parity with conventional dairy proteins, or major food service distributors complete logistics unbundling. Forecasts reflect assumptions around regulatory stability and technology adoption curves. A model refresh is warranted upon material change in bakery cooperative procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheddar Cheese Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Filled Cheese Market
Dairy Products
Dairy Carton Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
India Milk Protein Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Global Butter Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Dairy Protein Market
Dairy Products
Skimmed Milk Market