
 Flavoring Agents Market | 2026-2036
Flavoring Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Flavoring Agents Market Foresight
Buyer concentration among food and beverage manufacturers is shifting as multinational processors consolidate supplier rosters while mid-sized dairy alternative and nutraceutical startups fragment procurement across specialized flavor houses. Givaudan SA leverages its integrated botanical extraction network to serve clean-label beverage clients across Europe and North America. Symrise AG anchors its position through deep R&D partnerships with German confectionery and bakery manufacturers. Kerry Group competes by extending its savory and dairy flavor capabilities into the fast-growing plant-based segment.
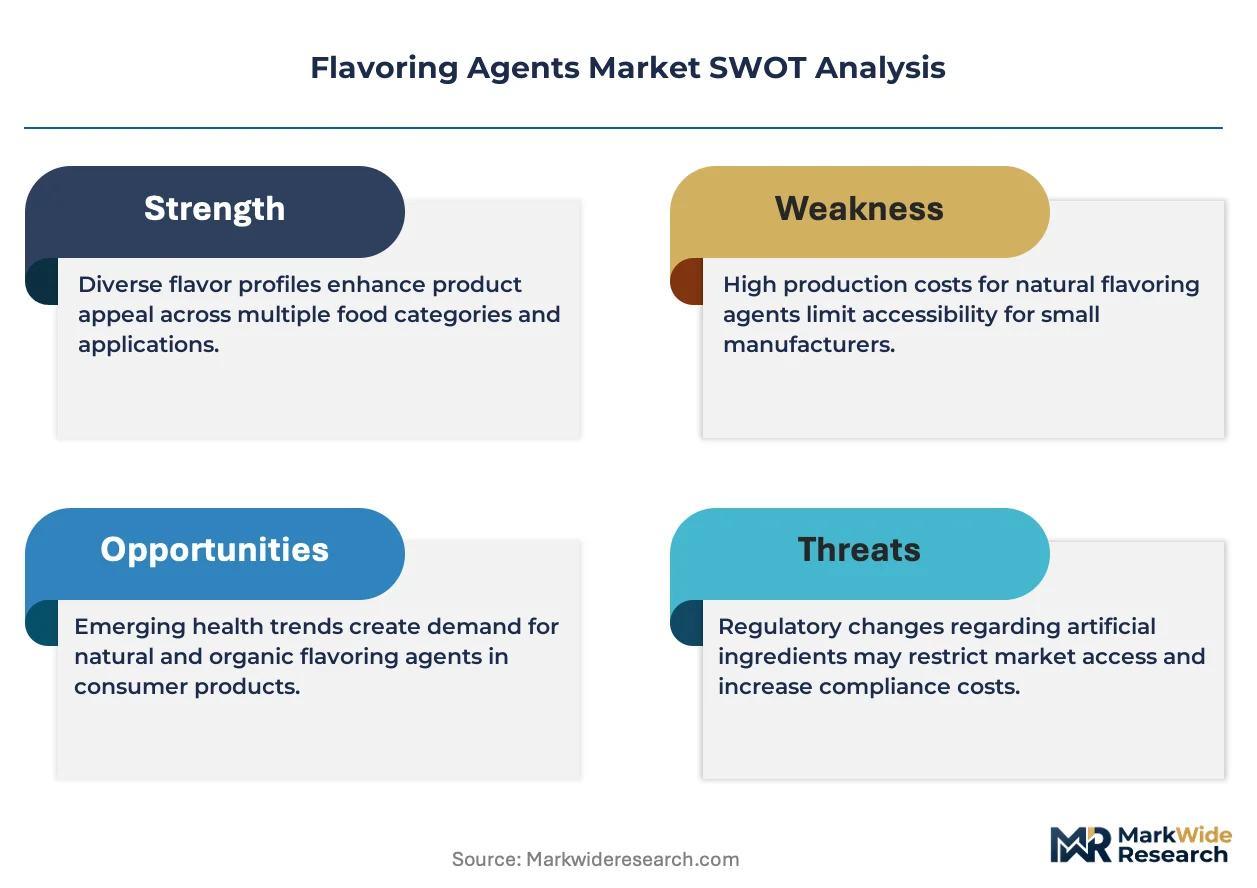
Flavoring agents comprise volatile and non-volatile chemical compounds—natural extracts, synthetic molecules, essential oils, oleoresins, and emulsified flavor systems—formulated to impart, enhance, or modify taste and aroma in finished consumer products, typically dosed at parts-per-million to low-percentage concentrations depending on application intensity and matrix stability. Natural extracts and essential oils command premium positioning as beverage and nutraceutical manufacturers reformulate away from artificial ingredients, while synthetic compounds retain cost-driven volume in confectionery and tobacco applications where heat stability and reproducibility dominate formulation requirements. Oleoresins and flavored emulsions capture expanding margin pools in bakery and dairy alternatives, where oil-in-water dispersion and lipid solubility determine performance.
The FDA's GRAS notification program and the EFSA's flavoring group evaluation system shape product development timelines and market access for both domestic and imported flavoring agents in the United States and European Union. China's SAMR and national food safety standards (GB series) impose additional testing protocols for imported flavor compounds, particularly synthetic molecules without established Chinese usage history. Stakeholders must monitor evolving regulatory divergence between jurisdictions as compliance costs and reformulation requirements increasingly determine competitive viability in cross-border supply chains.
Market Dynamics
Clean-label reformulation is forcing flavor houses to rebuild their extraction and stabilization capabilities around botanical sourcing networks rather than synthetic chemistry platforms.
Growth Catalysts
- EU Flavoring Regulation (EC) No 1334/2008:Harmonized safety assessments across member states accelerate cross-border product registration for natural extracts and essential oils.
- Plant-based dairy alternatives:Oat, almond, and pea protein beverage manufacturers require masking and flavor-matching solutions that replicate dairy mouthfeel without animal-derived ingredients.
- Biotechnology:Precision fermentation and cell-culture platforms enable cost-competitive production of rare natural molecules previously limited by agricultural supply constraints.
Market Restraints
- Vanilla and citrus raw material volatility:Climate-driven crop failures in Madagascar and Florida concentrate input cost risk among natural extract suppliers.
- Chinese import protocols:SAMR testing requirements for synthetic molecules without established GB standards create 12-18 month market access delays.
- Heat stability limitations:Natural extracts degrade at confectionery processing temperatures above 120°C, preserving synthetic compound dominance in hard candy applications.
Strategic Opportunities
- India FSSAI clean-label incentives:Domestic beverage manufacturers face consumer pressure to eliminate artificial colors and flavors, creating demand for India-sourced botanical extracts.
- Direct-to-manufacturer digital platforms:Flavor houses bypass traditional distribution intermediaries to offer sample-to-scale ordering with rapid reformulation support.
- Upcycled food waste streams:Citrus peel, coffee cherry, and apple pomace extraction transforms agricultural byproducts into cost-advantaged natural flavor precursors.
Industry Challenges
- Flavor chemist talent scarcity:Retirement of senior professionals with 30+ years of synthetic molecule expertise outpaces university program output.
- GRAS self-determination liability:FDA notification withdrawals following safety challenges expose manufacturers to retrospective litigation and reformulation costs.
- Legacy ERP integration:Mid-sized flavor houses struggle to connect batch-level traceability systems with customer EDI platforms for real-time specification exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavoring Agents Market |
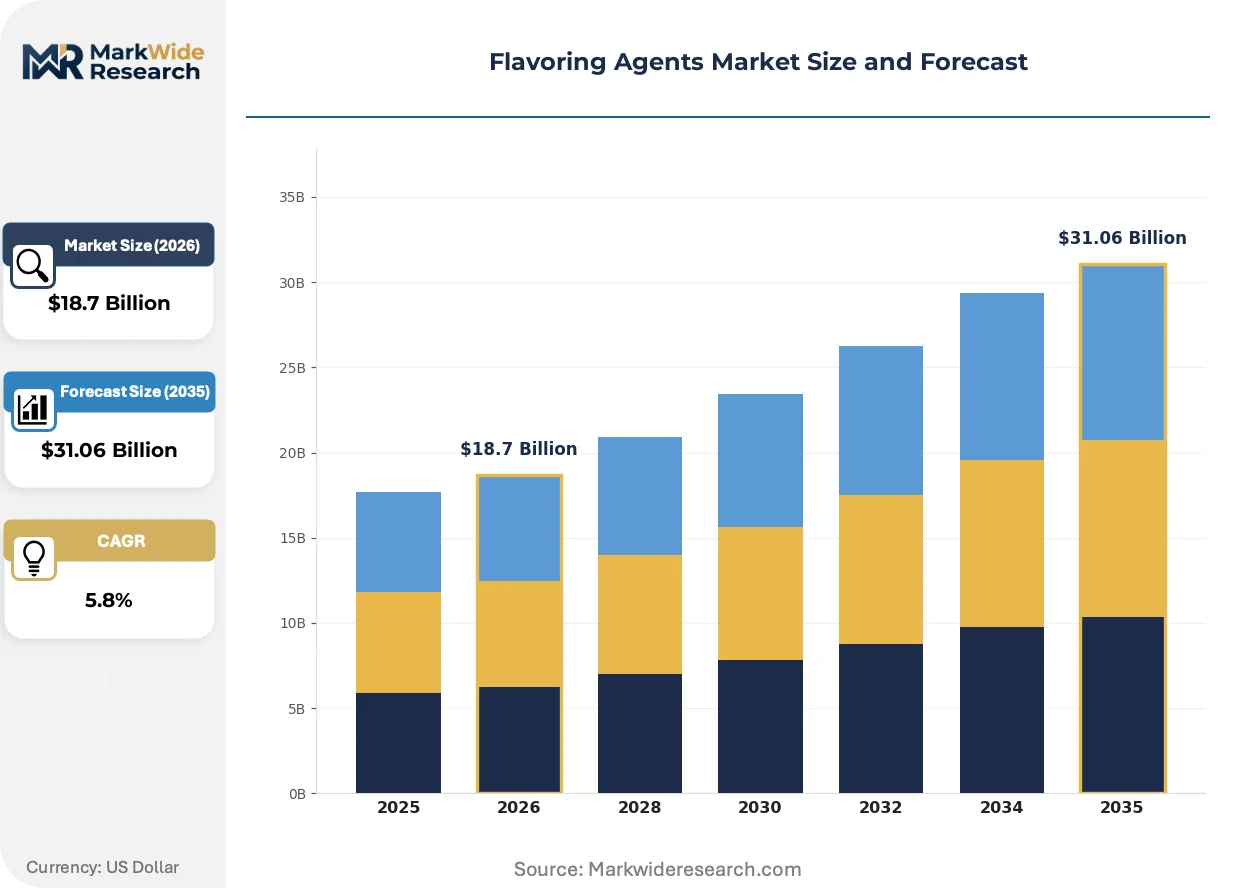
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Synthetic Compounds, Essential Oils, Oleoresins, Flavored Emulsions Application: Beverages, Confectionery, Bakery Products, Dairy Alternatives, Nutraceuticals End User: Food & Beverage Manufacturers, Personal Care Producers, Pharmaceutical Firms, Pet Food Companies, Tobacco Industry Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers, Foodservice Suppliers |
| Companies Covered | Symrise AG, Sensient Technologies Corporation, Givaudan SA, Archer-Daniels-Midland Company, Kerry Group, International Flavors & Fragrances Inc., Takasago International Corporation, Döhler GmbH, Firmenich International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavoring Agents Market Shifts & Advancements
Biotechnology platforms and extraction automation are compressing development timelines while regulatory divergence between jurisdictions forces parallel compliance investments.
Precision fermentation is rewriting the economics of rare natural molecules. Specialty chemical producers now cultivate yeast strains engineered to express vanillin, raspberry ketone, and nootkatone at commercial scale. Beverage and confectionery formulators in Germany and the United States are qualifying these bio-identical extracts for clean-label positioning. The technology is rewriting supplier power dynamics by decoupling flavor production from agricultural geography and weather risk.
EFSA's 2023 updated guidance on botanical flavoring safety assessments tightens toxicological data requirements for novel extracts. The framework demands extended 90-day rodent studies and metabolite identification that add 18-24 months to product development timelines. Small and mid-sized flavor houses serving European nutraceutical clients are consolidating safety dossiers through shared testing consortia to distribute compliance costs.
Long-term supply agreements with fixed price collars are displacing spot purchasing for high-volume natural extracts. Multinational beverage processors in China and Mexico now contract directly with Madagascar vanilla cooperatives and Indian spice extraction facilities, bypassing traditional trading houses. This procurement compression is most visible in vanilla and black pepper oleoresins, where three-year forward contracts now dominate transactions above 10 metric tons annually.
Flavoring Agents Market Segmentation
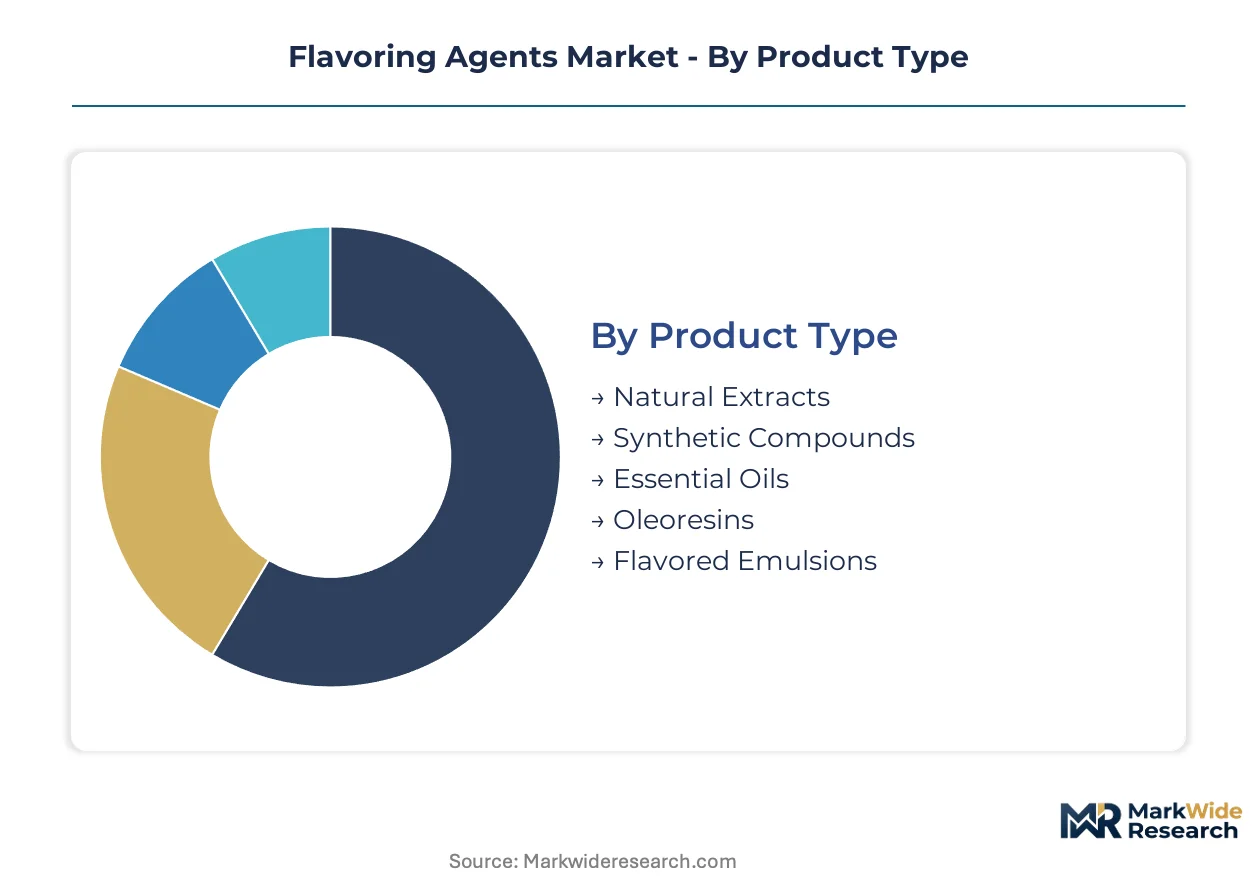
Flavoring agents traverse vastly different regulatory pathways and technical specifications depending on their chemical origin and end-use destination. Segmentation reveals how certification burdens, thermal stability requirements, and customer procurement scale fragment supplier strategies across molecular categories and distribution modes.
Product Type:
Natural extracts and essential oils require EFSA botanical safety dossiers or FDA GRAS notifications, while synthetic compounds face REACH registration in Europe and SAMR testing protocols in China.
- Natural Extracts:Botanical-derived flavor compounds including vanilla oleoresin, citrus extracts, and spice distillates. Beverage manufacturers in Germany and the United States are qualifying these for clean-label positioning as reformulation accelerates away from artificial ingredients. GRAS self-determination and EFSA novel food assessments add 18-24 months to market entry timelines.
- Synthetic Compounds:Chemically synthesized molecules such as ethyl vanillin, maltol, and benzaldehyde engineered for batch-to-batch consistency. Confectionery processors in Mexico and China favor these for heat stability above 120°C where natural alternatives degrade. REACH registration costs and Chinese GB standard harmonization create compliance barriers for new market entrants.
- Essential Oils:Steam-distilled volatile fractions from peppermint, citrus, and cinnamon.
- Oleoresins:Solvent-extracted concentrated flavor and color fractions from spices and herbs.
- Flavored Emulsions:Oil-in-water dispersed systems stabilizing lipophilic flavors for aqueous applications.
Leading the category by volume: Synthetic Compounds. Growing fastest: Natural Extracts.
Application:
Heat processing intensity and pH stability requirements separate high-margin beverage applications from commodity confectionery volumes.
- Beverages:Carbonated soft drinks, functional waters, and alcoholic formulations requiring water-soluble or emulsified flavor systems. Oat and almond milk processors in China and Germany are driving procurement of masking solutions that neutralize plant protein off-notes. Clean-label pressure from retail chains is forcing qualification of natural alternatives despite cost premiums.
- Confectionery:Hard candies, chewing gums, and chocolate coatings demanding heat-stable flavor carriers. Synthetic molecules dominate here due to thermal degradation of natural extracts during cooking stages above 120°C. Brazilian and Indian manufacturers maintain cost-driven procurement of artificial vanillin and fruit esters.
- Bakery Products:Yeast-leavened and chemically leavened goods with moderate thermal exposure.
- Dairy Alternatives:Plant-based milk, yogurt, and ice cream formulations requiring mouthfeel replication.
- Nutraceuticals:Vitamin-fortified gummies, protein powders, and functional shots with stringent stability requirements.
Dairy alternatives are expanding most quickly as plant protein processing scales. Confectionery retains the largest absolute volume.
End User:
Procurement scale and technical service intensity fragment the customer base from multinational beverage conglomerates to specialized pet food compounders.
- Food & Beverage Manufacturers:Multinational processors and mid-sized dairy alternative startups with diverging supplier roster strategies. Large accounts consolidate to integrated flavor houses offering bundled savory and sweet capabilities. Startups fragment procurement across specialized botanical extraction firms.
- Personal Care Producers:Oral care and cosmetic formulators utilizing mint and fruit flavors at sub-threshold taste levels.
- Pharmaceutical Firms:Tablet coating and liquid formulation applications with USP-grade purity requirements.
- Pet Food Companies:Palatant suppliers masking bitter active ingredients in therapeutic formulations.
- Tobacco Industry:Heat-not-burn and traditional product flavoring with distinct regulatory pathways.
Food and beverage manufacturers command the largest procurement volumes. Pharmaceutical firms are gaining share fastest on expanded pediatric and geriatric formulation pipelines.
Distribution Channel:
Order scale and reformulation service requirements determine whether flavor houses engage directly or through intermediaries.
- Direct Sales:Long-term supply agreements with fixed price collars for annual volumes above 10 metric tons. Madagascar vanilla cooperatives and Indian spice extraction facilities now contract directly with multinational beverage processors in China and Mexico, bypassing traditional trading houses.
- Online Retailers:Sample-to-scale digital platforms enabling rapid specification exchange for mid-sized customers.
- Distributors:Regional inventory stocking and technical service for fragmented small-batch buyers.
- Wholesalers:Commodity-grade synthetic molecules for cost-sensitive local processors.
- Foodservice Suppliers:Custom flavor blending for restaurant chains and institutional catering.
Direct sales dominate high-volume natural extract transactions. Online retailers are climbing fastest as digital platforms compress sample turnaround times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar's vanilla orchid belt supplies the benchmark natural extract that beverage formulators in Germany, the United States, and China price contracts against. Climate volatility in this Indian Ocean corridor concentrates procurement risk for multinational flavor houses.
United States
Carbonated soft drink and functional water manufacturers in Atlanta and Chicago drive bulk procurement of emulsified flavor systems. The FDA's GRAS notification program governs novel extract approvals, with recent withdrawals exposing manufacturers to retrospective liability. Extraction facilities in New Jersey and California process Madagascar vanilla and Indian spice oleoresins for nationwide distribution.
Germany
Confectionery and bakery clusters in Cologne and Munich anchor European demand for heat-stable synthetic molecules and natural alternatives. EFSA's 2023 botanical safety guidance extends development timelines for novel extracts. Precision fermentation startups in Bavaria are qualifying bio-identical vanillin for clean-label positioning.
China
Oat and almond milk processors in Shanghai and Beijing are scaling procurement of masking solutions for plant protein off-notes. SAMR's GB standard testing protocols impose 12-18 month delays for synthetic molecules without established usage history. Direct contracting with Madagascar cooperatives is displacing traditional trading house intermediaries.
India
Domestic beverage manufacturers in Maharashtra and Karnataka face consumer pressure to eliminate artificial colors and flavors under FSSAI clean-label incentives. Black pepper and cardamom extraction facilities in Kerala supply oleoresins to European and North American flavor houses. Citrus peel upcycling from Nagpur orange processing is emerging as a cost-advantaged natural precursor source.
Brazil
Confectionery processors in São Paulo maintain cost-driven procurement of artificial vanillin and fruit esters for hard candy applications. ANVISA's food additive regulations align partially with Mercosur standards, simplifying cross-border trade with Argentina. Coffee cherry extraction from Minas Gerais arabica cultivation is supplying natural flavor precursors to multinational beverage clients.
Flavoring Agents Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived natural molecules and direct-to-manufacturer digital platforms. The supplier base concentrates around integrated flavor houses with captive extraction networks and specialized botanical firms serving clean-label startups. Three archetypes dominate: multinational conglomerates with bundled savory-sweet capabilities, regional extraction specialists with single-origin supply contracts, and precision fermentation platforms decoupling production from agricultural geography. Competitive moves center on long-term supply agreements with fixed price collars and shared safety dossier consortia to distribute EFSA compliance costs.
Among Swiss- and German-based integrated houses, Givaudan SA, Symrise AG, and Firmenich International SA exemplify the multinational archetype with cross-continental botanical sourcing networks. These entities represent the consolidation endpoint where bundled technical service capabilities and regulatory dossier depth anchor relationships with multinational beverage and confectionery processors. Kerry Group and Archer-Daniels-Midland Company occupy positions spanning ingredient systems and flavor integration, reflecting the convergence of taste, texture, and nutrition functionality in plant-based formulation. Sensient Technologies Corporation and Takasago International Corporation sit within specialized tiers where regional extraction expertise or fermentation-derived rare molecules differentiate positioning.
| Leading Market Players |
|---|
| Symrise AG |
| Sensient Technologies Corporation |
| Givaudan SA |
| Archer-Daniels-Midland Company |
| Kerry Group |
| International Flavors & Fragrances Inc. |
| Takasago International Corporation |
| Döhler GmbH |
| Firmenich International SA |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between GRAS-notified natural extracts and commodity synthetic molecules manifests in both pricing premiums and supply chain configurations. Natural extract suppliers in Madagascar and India command forward-contract premiums with fixed price collars, while synthetic compound manufacturers in China and Germany compete on spot-market efficiency and REACH registration depth.
Pricing Analysis
Service-bundling separates integrated flavor houses offering regulatory dossier support from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with GRAS self-determination and EFSA botanical safety dossiers adding 18-24 months to premium tier qualification. Cost compression in synthetic compounds is intensifying because Chinese SAMR testing protocols delay market access for molecules without established GB standards. Mid-sized dairy alternative startups exhibit highest price sensitivity, while multinational beverage processors prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Madagascar's vanilla orchid belt, where climate-driven crop failures concentrate input cost risk among natural extract suppliers. Geographic supply concentration spans Madagascar for vanilla, India for spice oleoresins, and China for synthetic molecule manufacturing. Raw material dependencies include vanilla orchids, citrus peel from Florida and Brazil, and black pepper from Kerala. Tariff exposure runs through evolving US-China trade protocols affecting synthetic compound flows. Distribution runs through direct long-term supply agreements for volumes above 10 metric tons annually, displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are displacing agricultural extraction as the dominant production modality for rare natural molecules, compressing development timelines and decoupling supply from weather risk. This technology transition rewards early movers with captive bioreactor capacity and qualified strain libraries.
For Market Incumbents: To counter biotechnology-derived competition from precision fermentation startups, integrated flavor houses should deepen backward integration into Madagascar vanilla cooperatives and Indian spice extraction facilities while accelerating in-house bioreactor deployment for bio-identical vanillin and nootkatone production.For New Entrants and Emerging Players: Specialized botanical extraction firms serving clean-label dairy alternative startups represent the most penetrable customer segment, given multinational processors' consolidated supplier rosters. Direct-to-manufacturer digital platforms offering sample-to-scale ordering with rapid reformulation support provide the strongest go-to-market angle against established distribution networks.
For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation platforms possessing qualified bio-identical molecules and GRAS notifications, given clean-label reformulation tailwinds across beverage and confectionery sectors. Long-term viability centers on decoupling production from agricultural geography. The signal to watch is EFSA guidance tightening on botanical safety assessments, which would accelerate biotech-derived molecule adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Madagascar vanilla cooperatives now contract directly with Chinese beverage processors, bypassing trading houses. |
| Backward Integration | Captive botanical extraction networks in Kerala and New Jersey secure oleoresin supply for GRAS-qualified natural extracts. |
| Precision Fermentation Scale-Up | Commercial bioreactor deployment for vanillin production decouples supply from Madagascar climate volatility. |
| Regulatory Dossier Consortium | Shared EFSA safety testing distributes compliance costs among mid-sized flavor houses serving European nutraceutical clients. |
| Direct-to-Manufacturer Platform | Digital sample-to-scale ordering compresses turnaround times for mid-sized dairy alternative startups. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with flavor chemists, procurement leads at multinational beverage processors, regulatory affairs directors at flavor houses, and botanical extraction facility managers in Madagascar and India combined with secondary validation. Secondary sources encompassed FDA GRAS notifications, EFSA flavoring group evaluations, SAMR GB standards documentation, and FSSAI clean-label incentive frameworks. Bottom-up volume modeling and top-down value triangulation ensured cross-verification.
Segment-level granularity modeled product type splits across natural extracts, synthetic compounds, essential oils, oleoresins, and flavored emulsions; application segmentation spanning beverages, confectionery, bakery, dairy alternatives, and nutraceuticals; and end-user categories from multinational processors to specialized startups. CAGRs were derived through trend extrapolation adjusted for regulatory timeline impacts and biotechnology adoption curves. Forecast inputs included precision fermentation capacity buildouts, EFSA guidance revision schedules, and SAMR testing protocol harmonization progress across the analysis window.
Caveats apply where EFSA botanical safety assessment tightening, Chinese import protocol changes, or climate-driven vanilla crop failures could materially shift the outlook. Forecasts reflect assumptions around biotechnology scale-up timelines and regulatory divergence between jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Oryzanol Market