
 Camel Dairy Market | 2026-2036
Camel Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Camel Dairy Market Intelligence
Market Context with Strategic Players
Direct-to-consumer online channels is rewriting how camel dairy reaches buyers outside traditional Middle Eastern markets. Camelicious leverages its Dubai production base to anchor premium positioning across European specialty retailers. Desert Farms competes through USDA-certified operations that sustain American consumer trust in alternative dairy sourcing. Al Ain Farms controls extensive UAE herd networks that dominate fresh milk supply across Gulf supermarket chains.
Technical Definition and Structural Segments
Camel dairy encompasses milk extraction, processing, and derivative manufacturing from dromedary and Bactrian camels, yielding products with lower lactose, higher vitamin C, and distinct immunoglobulin profiles compared to bovine alternatives. The primary commercial purpose centers on nutritional differentiation for lactose-intolerant consumers and functional food applications requiring bioactive protein retention. Milk as a raw product category leads volume throughput, while nutraceutical applications within the application dimension capture the fastest value expansion due to insulin-like protein research and cosmeceutical formulation demand. Specialty stores within distribution channels concentrate margin pools through curated storytelling and origin verification that commands price premiums unavailable in mass retail.
Regulatory Frame and Forward-Looking Close
Gulf Standards Organization harmonization across UAE, Saudi Arabia, and Kuwait shapes camel dairy export protocols, while EFSA novel food assessments govern European market access for new entrants. Codex Alimentarius guidelines on hygienic milk production increasingly influence national regulator benchmarks from East Africa to Central Asia. Stakeholders must monitor evolving novel food classification rulings in target import jurisdictions before committing to processing capacity expansion.
Market Dynamics
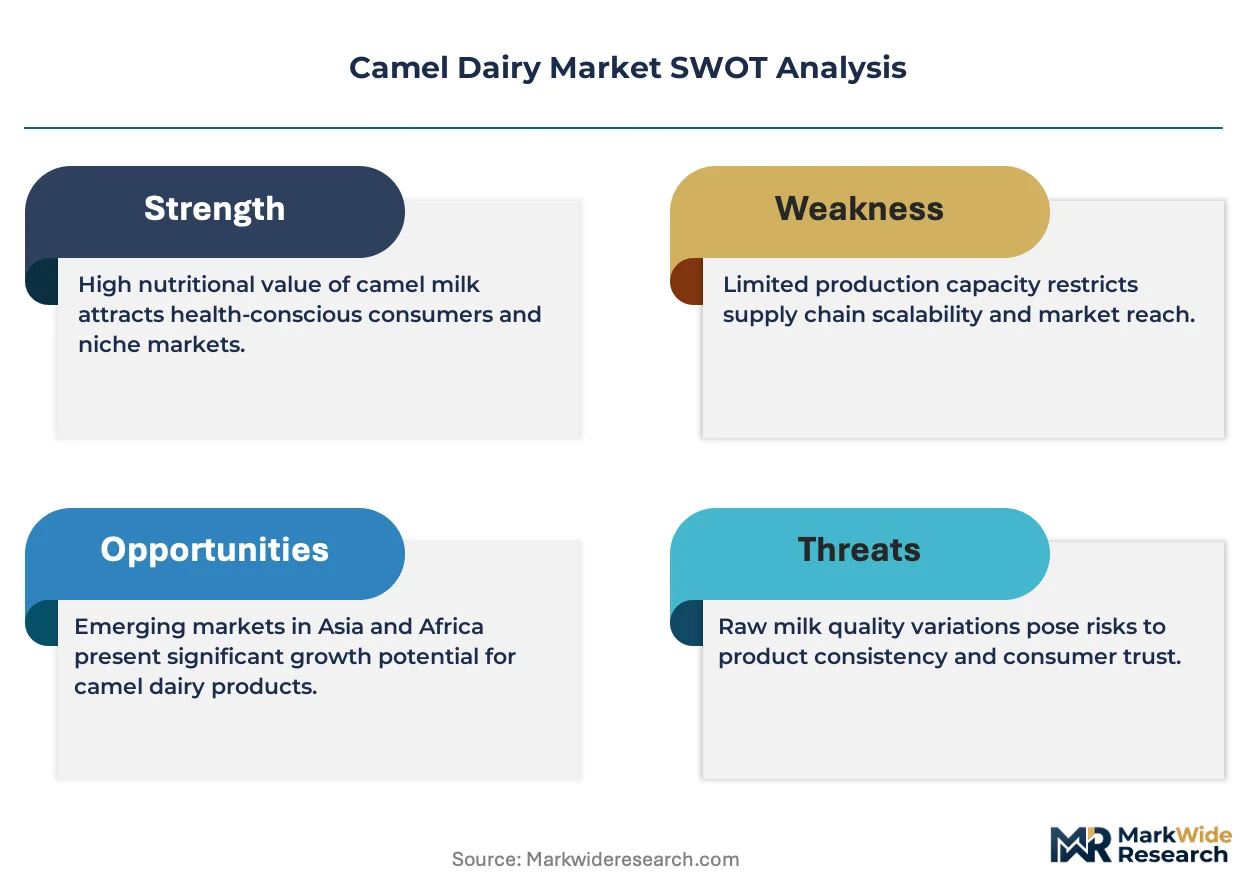
Halal certification protocols enforced by Gulf Standards Organization members are fragmenting export eligibility across camel dairy processors, forcing supply chain reconfiguration before market access.
Growth Catalysts
- Lactose-intolerant consumer migration:Rising diagnosis rates in North American and European populations pull demand toward camel milk's naturally lower lactose profile compared to bovine alternatives.
- Gulf Standards Organization harmonization:Unified halal dairy protocols across UAE, Saudi Arabia, and Kuwait reduce cross-border compliance duplication for regional processors.
- Nutraceutical formulation pipelines:Insulin-like protein research in diabetes management applications expands procurement from specialty health ingredient buyers.
Market Restraints
- Feed cost volatility:Alfalfa and date palm byproduct prices fluctuate with regional water policy changes, compressing herder margins in Saudi Arabia and UAE.
- EFSA novel food classification:European entrants face 18-24 month safety assessment timelines before commercial distribution authorization.
- Bovine dairy substitution:A2 milk and lactose-free cow milk variants capture price-sensitive consumers in Western European retail channels.
Strategic Opportunities
- Direct-to-consumer subscription channels:Freeze-dried powder formats bypass cold chain limitations and reach North American wellness consumers through curated online platforms.
- Cosmeceutical bioactive applications:Camel milk immunoglobulins and alpha-hydroxy acids attract formulation interest from premium skincare manufacturers seeking clean-label positioning.
- East African herd expansion:Somalia and Kenya pastoral cooperatives present untapped raw milk sourcing for processors seeking supply diversification outside Gulf concentration.
Industry Challenges
- Veterinary specialist scarcity:Camel-specific reproductive health and mastitis management expertise concentrates in UAE and Saudi Arabia, limiting herd quality improvement in emerging production zones.
- Cold chain infrastructure gaps:Fresh milk distribution beyond 48-hour windows requires capital-intensive refrigerated logistics investments in Central Asian and North African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camel Dairy Market |
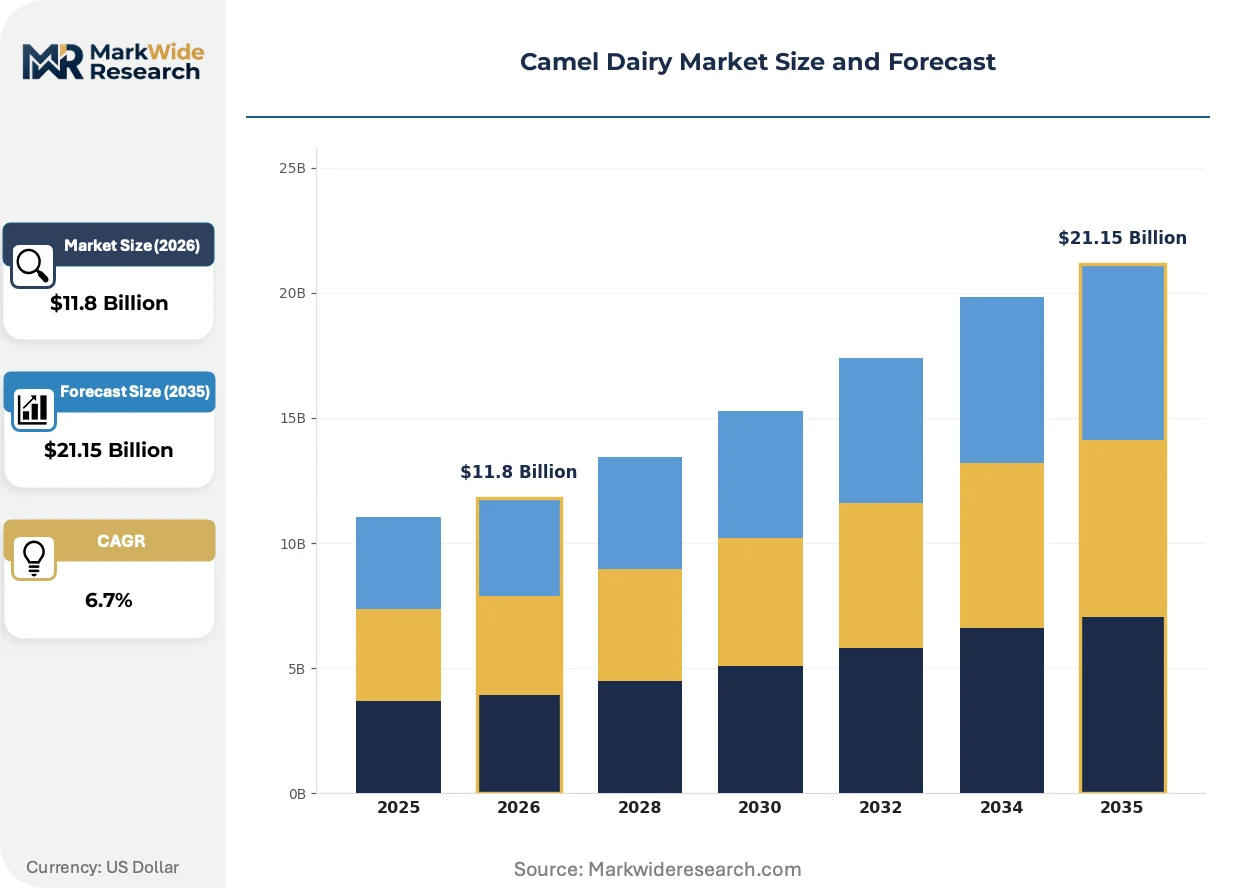
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Ice Cream End User: Households, Restaurants, Cafés, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Application: Food Processing, Nutraceuticals, Cosmetics, Pharmaceuticals |
| Companies Covered | Aadvik Foods, Al Ain Farms, Camelicious, Hump Group, Camel Dairy Smits, Desert Farms, GCMMF, Tiviski, The Camel Milk Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camel Dairy Market Strategic Shifts & Innovations
Processing technology convergence with functional food science is compressing product development cycles and opening new formulation categories previously inaccessible to camel dairy inputs.
Membrane filtration and low-temperature spray drying is hybridizing traditional camel milk preservation with bioactive protein retention standards demanded by pharmaceutical-grade nutraceutical buyers. Specialty ingredient formulators in Switzerland and Germany adopt these systems to supply cosmeceutical manufacturers requiring validated immunoglobulin stability. The technology is hybridizing commodity milk processing into precision nutrition ingredient production, elevating margin structures beyond fluid milk benchmarks.
EFSA novel food assessments are tightening evidentiary requirements for bioactive protein claims in camel milk-derived supplements entering European markets. Processors must now submit compositional stability data and toxicological profiles before commercial authorization. Nutraceutical applications face the steepest compliance burden, with several Gulf-based suppliers redirecting R&D investment toward cosmetic-grade formulations where regulatory pathways remain less protracted.
Specialty retailers are consolidating origin verification and halal certification storytelling into unified shelf positioning that commands price premiums unavailable in mass grocery. European organic chains and North American wellness boutiques now require blockchain-traceable supply documentation alongside third-party halal audit certificates. This procurement pattern shift is most visible in German and UK metropolitan markets where Muslim and non-Muslim health-conscious consumers overlap in specialty store foot traffic.
Camel Dairy Market Segmentation
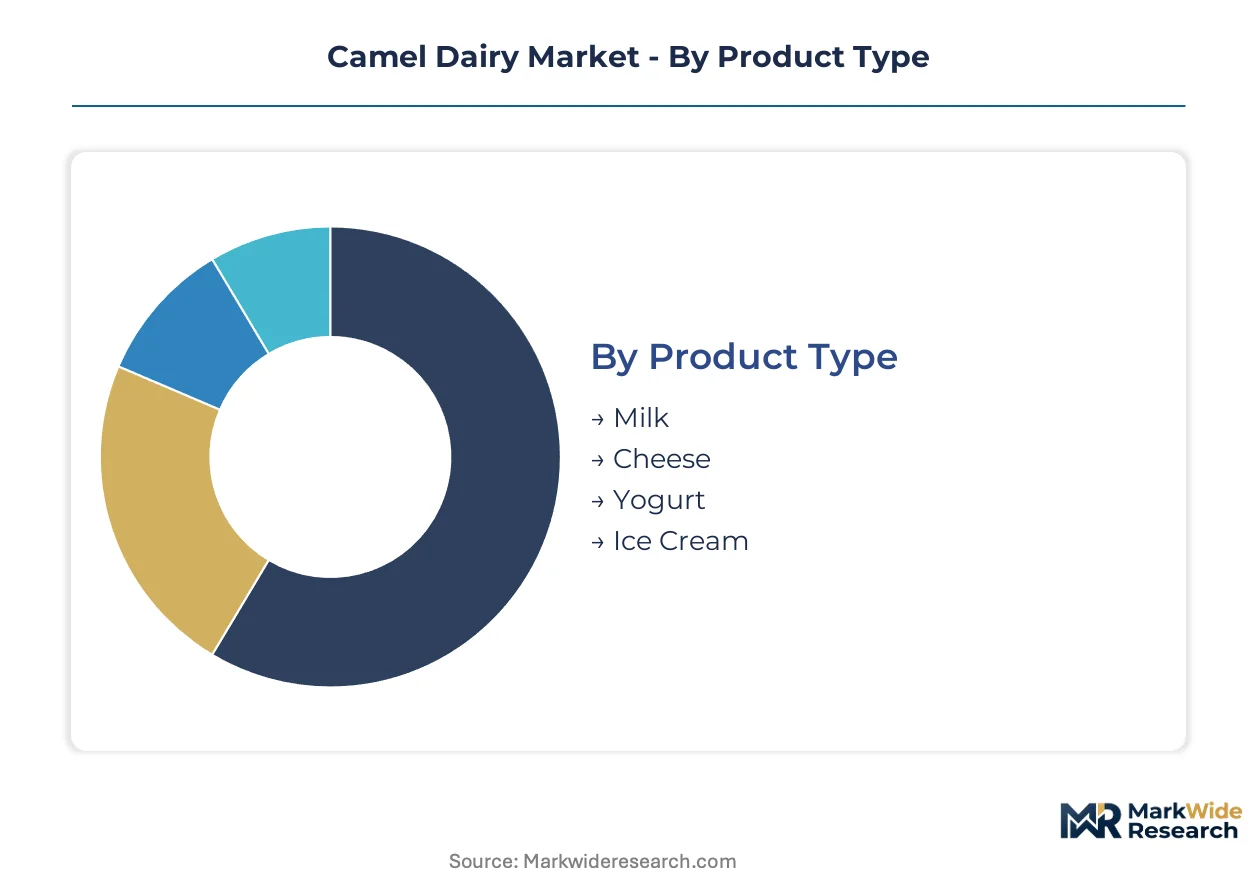
Camel dairy processors configure production lines around distinct product specifications and buyer requirements. Segment-level demand patterns determine cold chain investments, halal certification tiers, and bioactive protein retention protocols across processing facilities.
Product Type:
After-sales service intensity varies sharply across product formats, with fresh milk demanding 48-hour cold chain guarantees while powders require technical support for reconstitution protocols.
- Milk:Fresh fluid milk dominates volume throughput across Gulf supermarket chains, requiring refrigerated logistics investments and halal-certified handling from UAE and Saudi processing plants. Households in Dubai, Riyadh, and Kuwait City anchor fresh milk procurement through weekly supermarket replenishment cycles.
- Cheese:Artisanal and industrial cheese varieties command premium positioning in European specialty retailers, with EFSA novel food assessments governing export eligibility for fermented camel milk products. Swiss and German distributors prioritize blockchain-traceable origin documentation alongside third-party halal audit certificates.
- Yogurt:Probiotic fermentation formats attract Gulf health-conscious consumers through supermarket dairy aisles in Abu Dhabi and Jeddah.
- Ice Cream:Premium frozen dessert applications concentrate in UAE hotel and restaurant supply channels, requiring specialized fat content standardization.
Milk holds the largest share; momentum sits with cheese as European import protocols mature.
End User:
Cost tier stratification separates commodity bulk buyers from premium segment purchasers willing to absorb origin-verification premiums.
- Households:Direct-to-consumer subscription channels and supermarket purchases drive volume, with lactose-intolerant consumers in North America and Europe migrating toward camel milk's naturally lower lactose profile compared to bovine alternatives.
- Restaurants:Fine-dining establishments in Dubai, London, and Berlin incorporate camel dairy into halal-certified menu positioning, requiring consistent supply contracts with UAE-based processors.
- Cafés:Specialty coffee chains across Gulf Cooperation Council states experiment with camel milk flat whites and lattes, creating localized demand clusters.
- Health Stores:Nutraceutical-grade powders and supplements concentrate margin pools through curated storytelling and immunoglobulin stability validation that commands price premiums unavailable in mass retail.
Households dominate current volume; health stores are expanding most quickly through wellness consumer migration.
Distribution Channel:
Application-specific handling requirements fragment channel selection, with pharmaceutical-grade nutraceuticals bypassing retail entirely for direct B2B formulation supply.
- Online:Freeze-dried powder formats bypass cold chain limitations and reach North American wellness consumers through curated subscription platforms, with Desert Farms and similar operators leveraging USDA certification to sustain American consumer trust.
- Supermarkets:Mass retail channels in UAE and Saudi Arabia concentrate fresh milk volume through Al Ain Farms and Camelicious distribution networks dominating Gulf supermarket chains.
- Specialty Stores:European organic chains and North American wellness boutiques require blockchain-traceable supply documentation alongside third-party halal audit certificates, consolidating origin verification into unified shelf positioning.
- Direct Sales:Herder cooperative networks in Somalia and Kenya pastoral zones supply raw milk to regional processors, presenting untapped sourcing for supply diversification outside Gulf concentration.
Supermarkets retain the largest share; online channels gain share fastest through subscription model scalability.
Application:
Margin concentration aligns with bioactive protein retention standards, with pharmaceutical and cosmeceutical applications capturing value expansion unavailable in commodity food processing.
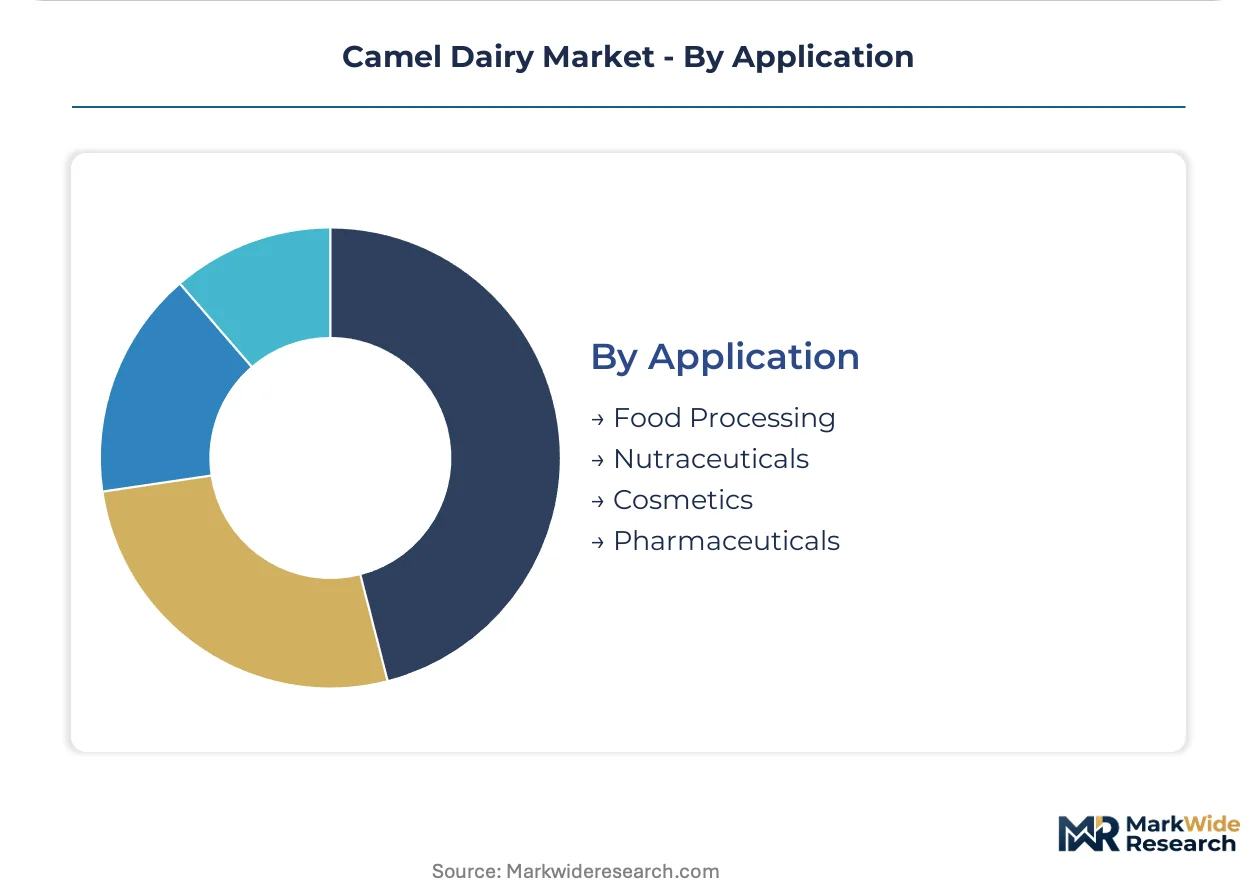
- Food Processing:Standardized milk powders and ingredients supply bakery and confectionery manufacturers across Middle Eastern and North African markets, with Codex Alimentarius guidelines on hygienic milk production influencing national regulator benchmarks.
- Nutraceuticals:Insulin-like protein research in diabetes management applications expands procurement from specialty health ingredient buyers in Switzerland and Germany, though EFSA novel food assessments impose 18-24 month safety assessment timelines before European commercial authorization.
- Cosmetics:Camel milk immunoglobulins and alpha-hydroxy acids attract formulation interest from premium skincare manufacturers in France and Germany seeking clean-label positioning, with regulatory pathways less protracted than pharmaceutical-grade supplements.
- Pharmaceuticals:Bioactive protein retention standards demanded by pharmaceutical-grade buyers require membrane filtration and low-temperature spray drying systems that hybridize commodity processing into precision nutrition ingredient production.
Food processing holds the largest share; nutraceuticals show the steepest expansion trajectory as diabetes research advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE processors command price premiums exceeding European equivalents by margins that reflect Gulf herd scarcity and halal certification overhead, while East African pastoral zones trade raw milk at fractions of those benchmarks due to infrastructure deficits.
United Arab Emirates
Dubai and Abu Dhabi anchor fresh milk consumption through supermarket chains and hotel supply channels, with household procurement concentrated in weekly replenishment cycles. MOHAP enforces strict halal dairy protocols that govern export eligibility and processing facility licensing. Al Ain Farms controls extensive herd networks across the emirates, dominating fresh milk supply through integrated production and distribution infrastructure.
Saudi Arabia
Riyadh and Jeddah metropolitan areas drive concentrated demand for probiotic yogurt and fluid milk formats through modern retail expansion. SFDA harmonizes with Gulf Standards Organization protocols to reduce cross-border compliance duplication for regional processors. The Eastern Province hosts expanding processing capacity serving domestic consumption and re-export positioning toward neighboring Gulf states.
United States
Wellness consumers in California and metropolitan New York migrate toward camel milk's lower lactose profile through direct-to-consumer subscription channels. FDA dairy safety standards apply alongside state-level raw milk regulations that fragment interstate distribution feasibility. Desert Farms leverages USDA-certified operations to sustain consumer trust in alternative dairy sourcing across specialty retail and online platforms.
Germany
Specialty retailers in Berlin and Munich consolidate blockchain-traceable origin documentation requirements alongside third-party halal audit certificates for premium positioning. EFSA novel food assessments impose extended safety evaluation timelines before commercial authorization for new entrants. Swiss and German distributors prioritize validated immunoglobulin stability data when sourcing from Gulf-based processors for nutraceutical formulation supply.
Somalia
Pastoral cooperatives in central and southern regions present untapped raw milk sourcing for processors seeking supply diversification outside Gulf concentration. The national veterinary service operates with limited camel-specific reproductive health expertise, constraining herd quality improvement. Direct sales through herder networks supply regional processors with minimal cold chain infrastructure, compressing margins through spoilage losses and quality inconsistency.
Camel Dairy Market Key Industry Players
Gulf-based integrated producers and international specialty distributors split the market between freshness-dependent domestic supply and shelf-stable export formats. The structure concentrates around three strategic archetypes: vertically integrated herd-to-retail operators controlling UAE and Saudi processing capacity, ingredient-focused formulators supplying European nutraceutical and cosmeceutical manufacturers, and direct-to-consumer brands leveraging freeze-dried formats to bypass cold chain limitations. Dominant competitive moves include backward integration into captive herd supply and geographic licensing partnerships to secure novel food authorization in restricted import jurisdictions.
Within the integrated producer tier, Al Ain Farms and Camelicious exemplify Gulf-based operators with extensive herd networks and supermarket distribution dominance across domestic markets. Desert Farms occupies a position representing the international specialty distributor archetype, leveraging certification-based positioning to reach North American wellness consumers through curated channels. These three entities anchor the competitive structure without exhaustive market coverage, as regional specialists and emerging pastoral cooperatives populate remaining volume segments.
| Leading Market Players |
|---|
| Aadvik Foods |
| Al Ain Farms |
| Camelicious |
| Hump Group |
| Camel Dairy Smits |
| Desert Farms |
| GCMMF |
| Tiviski |
| The Camel Milk Co. |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors from Dubai anchor Gulf export pricing, with refrigerated container rates compressing margins for European-bound fresh milk while freeze-dried powder formats escape cold chain premiums entirely. This logistics bifurcation concentrates pricing power among UAE processors commanding halal-certified premiums, while East African pastoral suppliers absorb spoilage losses that prevent price parity with Gulf-origin product.
Pricing Analysis
The customization-premium spread separates blockchain-traceable specialty retail formats from commodity bulk powder contracts, with halal certification tier and immunoglobulin validation grade as primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels captures subscription wellness consumers, supermarket household buyers, and industrial food processing procurement respectively. Pricing pressure stems from A2 milk and lactose-free bovine alternatives capturing price-sensitive European retail consumers. Household subscription buyers demonstrate lowest price sensitivity, while industrial food manufacturers exhibit highest elasticity to input cost fluctuations.
Supply Chain Analysis
Upstream feedstock dependencies center on alfalfa cultivation and date palm byproduct availability across UAE, Saudi Arabia, and Somalia pastoral zones. Camel-specific veterinary pharmaceuticals and refrigerated logistics equipment constitute critical component inputs. Supply chain risk concentrates in single-source vulnerability for Gulf Standards Organization-certified processing capacity. Distribution runs through integrated herd-to-retail networks dominating domestic Gulf markets, with direct-to-consumer subscription platforms bypassing traditional wholesale tiers for North American wellness consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camel dairy is approaching a platform-economics inflection where blockchain traceability infrastructure and halal certification interoperability will determine which processors capture cross-border premium positioning. Ecosystem coordination between Gulf Standards Organization members and European specialty retailers is compressing authorization timelines for compliant entrants.
For Market Incumbents: Build captive herd supply moats through backward integration into Somali and Kenyan pastoral cooperatives before competitors secure exclusive offtake agreements. Al Ain Farms and Camelicious should deepen cold chain infrastructure investments across Central Asian distribution corridors to preempt emerging entrant logistics plays. EFSA novel food classification tightening presents regulatory threat requiring dedicated Brussels-facing compliance capacity.
For New Entrants and Emerging Players: Build out cosmeceutical-grade immunoglobulin formulation supply to French and German skincare manufacturers, where regulatory pathways remain less protracted than pharmaceutical-grade supplements. East African raw milk sourcing presents the most penetrable white-space, with direct herder cooperative relationships enabling cost structures below Gulf benchmarks. Direct-to-consumer subscription platforms targeting North American lactose-intolerant consumers offer the clearest go-to-market angle bypassing established retail gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration and low-temperature spray drying equipment suppliers serving precision nutrition ingredient production. Long-term viability across the projection horizon hinges on nutraceutical pipeline maturation for diabetes management applications. Acquisition targets should demonstrate validated immunoglobulin stability data and existing Gulf Standards Organization certification. The signal to watch is EFSA novel food authorization acceleration for camel milk-derived bioactive proteins as inflection indicator for European market access normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pastoral Cooperatives | Secures raw milk supply outside Gulf concentration, enabling cost structures competitive with bovine alternatives. |
| Blockchain Traceability Implementation | Satisfies European specialty retailer procurement requirements for halal-certified origin documentation. |
| Membrane Filtration Capacity Expansion | Retains bioactive protein integrity demanded by pharmaceutical-grade nutraceutical buyers in Switzerland and Germany. |
| Cosmeceutical Formulation Partnership | Accesses premium skincare manufacturing demand in France with regulatory pathways shorter than supplement authorization. |
| Direct-to-Consumer Subscription Launch | Bypasses cold chain limitations through freeze-dried formats while capturing North American wellness consumer price premiums. |
Research Approach
Operator-level perspectives from camel dairy processing executives, Gulf supermarket category buyers, European specialty retailer procurement managers, and East African pastoral cooperative leaders anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including Gulf Standards Organization protocol documentation, EFSA novel food assessment filings, Codex Alimentarius hygienic milk production guidelines, and UAE-Saudi customs trade data. Bottom-up volume modeling from herd capacity and milk yield assumptions was triangulated with top-down demand estimation from end-use consumption patterns.
Scenario-bracketing framed the analytical approach across the analysis window, with optimistic, baseline, and conservative tracks reflecting alternative EFSA authorization timelines and Gulf herd expansion trajectories. Segmentation dimensions modeled included product format, application category, distribution channel, and regional regulatory cluster. CAGRs were derived from compounded annual growth trajectory analysis against baseline year anchor points. Industry-specific forecast inputs incorporated alfalfa price volatility indices and halal certification audit completion rates.
Stress conditions across EFSA regulatory delay extensions, Gulf feed cost inflation spikes, and bovine A2 milk competitive pricing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding novel food classification evolution and Gulf Standards Organization harmonization progress. Cross-checking against FAO dairy trade statistics and regional veterinary service capacity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Milk Powder Market
Dairy Products
Emmental Cheese Market
Dairy Products
Processed Cheese Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Textured Butter Market
Dairy Products
Paneer Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Goat Milk Products Market
Dairy Products
Fluid Milk Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
South America Yogurt Market
Dairy Products
White Cheese Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
North America Milk Powder Market
Dairy Products
Enzyme Modified Cheese Market