
 Fat-Rich Dairy Products Market | 2026-2036
Fat-Rich Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fat-Rich Dairy Products Market Analysis
Project finance tied to dairy processing infrastructure is reconfiguring competitive entry barriers across emerging markets. Fonterra Co-operative Group leverages its New Zealand farm-gate ownership model to sustain raw milk cost advantages. Lactalis Group anchors European cheese production through backward integration into regional milk pools. Danone competes in premium yogurt segments through specialized strain development and clean-label positioning.
Fat-rich dairy products encompass milk-derived goods with elevated butterfat content, typically ranging from 10% in cream to over 80% in clarified butter, produced through centrifugal separation, churning, or enzymatic coagulation processes that concentrate lipid fractions for culinary and nutritional applications. Cheese commands the largest product type margin pool due to aged varieties and protected designation premiums, while cream experiences accelerated growth through foodservice expansion in sauces and dressings. The application split reveals baked goods as the mature volume anchor, with snacks representing the fastest-growing segment as extruded and puffed formats incorporate butter and cheese powders for flavor delivery.
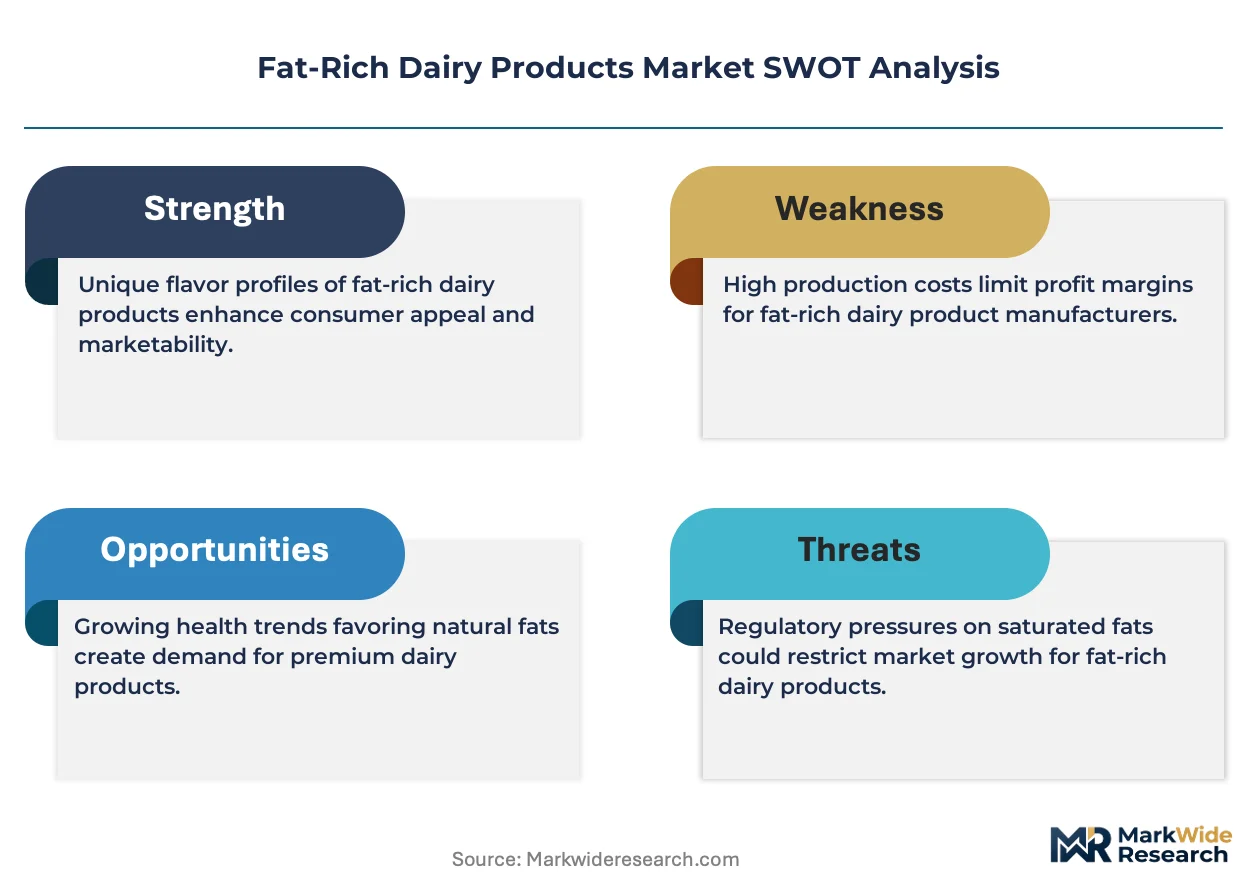
The EU Green Deal and F-Gas Regulation reshape cold-chain and processing energy standards across European dairy operations, while the FDA's Grade A Pasteurized Milk Ordinance governs interstate fluid cream safety in the United States. India's FSSAI enforces compositional standards for ghee and butter that determine market access for organized and unorganized producers alike. Stakeholders must monitor carbon border adjustment mechanisms and evolving methane accounting protocols that will redefine cost structures for export-oriented processors.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanisms are restructuring procurement economics for export-oriented processors, forcing simultaneous capital deployment into methane abatement and renewable energy integration across European supply chains.
Growth Catalysts
- Foodservice Expansion:Asia-Pacific hotel chains and quick-service restaurants are incorporating cream-based sauces and butter-enriched pastries into standardized menus, creating pull-through demand for industrial cream and clarified butter.
- Clean-Label Reformulation:REACH-compliant emulsifier alternatives are enabling butter and cream to replace synthetic stabilizers in European baked goods, satisfying EFSA-guided consumer preference shifts.
- Rural Procurement Networks:India's cooperative dairy federations aggregate smallholder milk into butter and ghee processing streams, lowering raw material acquisition costs for organized manufacturers.
Market Restraints
- Feed Cost Volatility:Soybean meal and alfalfa price swings in New Zealand and Argentina transmit directly into farm-gate milk costs, compressing processor margins without forward-contract hedging.
- Cold-Chain Energy Intensity:The EU F-Gas Regulation mandates refrigeration system retrofits that add capital intensity to cream and butter storage infrastructure.
- Plant-Based Substitution:Oat and coconut cream alternatives are capturing foodservice accounts seeking menu items compliant with flexitarian dietary frameworks.
Strategic Opportunities
- Specialized Strain Development:Precision fermentation platforms enable novel fat structures that replicate aged cheese mouthfeel without traditional aging infrastructure.
- Direct-to-Restaurant Distribution:Bypassing traditional wholesale distributors, processors are building captive delivery networks to high-volume bakery and confectionery chains.
- Carbon Credit Monetization:Methane capture installations at anaerobic digestion facilities generate compliance offsets under emerging EU and California cap-and-trade frameworks.
Industry Challenges
- Skilled Technician Scarcity:Centrifugal separator and butter churn maintenance requires mechanical expertise that dairy processing regions struggle to retain against manufacturing competition.
- Legacy System Integration:ERP upgrades for batch traceability under FDA Grade A Pasteurized Milk Ordinance conflict with decades-old production scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat-Rich Dairy Products Market |
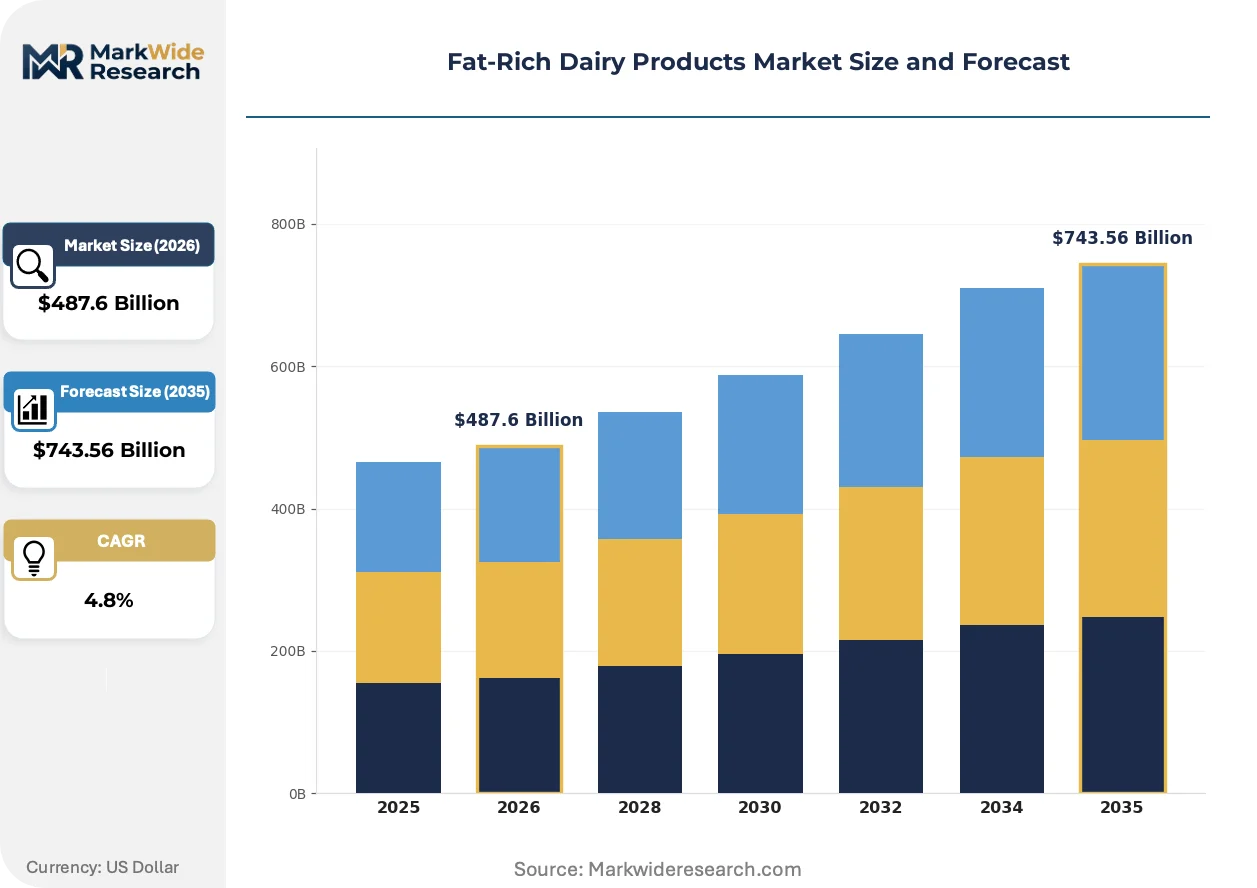
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Cream, Cheese, Yogurt Application: Baked Goods, Snacks, Sauces, Dressings End User: Households, Foodservice Providers, Manufacturers, Retailers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Arla Foods, Land O'Lakes, Nestlé, Saputo Inc., Royal FrieslandCampina, Danone, Fonterra Co-operative Group, Gujarat Cooperative Milk Marketing Federation, Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat-Rich Dairy Products Market Emerging Trajectories
Membrane filtration advances and enzymatic restructuring processes are compressing traditional aging timelines while regulatory pressure on carbon intensity accelerates energy system reinvestment across production facilities.
Precision fermentation is collapsing the traditional cheese aging value chain by producing casein and milk fat equivalents without cow agriculture. Specialty food manufacturers in the Netherlands and California are piloting these inputs for premium hard cheese analogues. The technology is collapsing capital requirements for aged product entry, enabling mid-scale players to compete on flavor complexity previously reserved for multi-year inventory holders.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is compelling cold-chain operators to install transcritical CO2 systems or ammonia-based alternatives. Dairy processors in Germany and Denmark face compressed retrofit timelines before 2030 compliance deadlines. Cream and butter storage facilities with extended holding periods absorb disproportionate capital impact due to temperature sensitivity.
Restaurant procurement teams are consolidating supplier relationships around full-category dairy portfolios rather than single-product contracts. Large bakery chains in Japan and South Korea now specify butter, cream, and cheese from unified sourcing agreements with traceability documentation. This consolidation favors processors with integrated fat-rich product lines over specialized single-category competitors.
Fat-Rich Dairy Products Market Segmentation
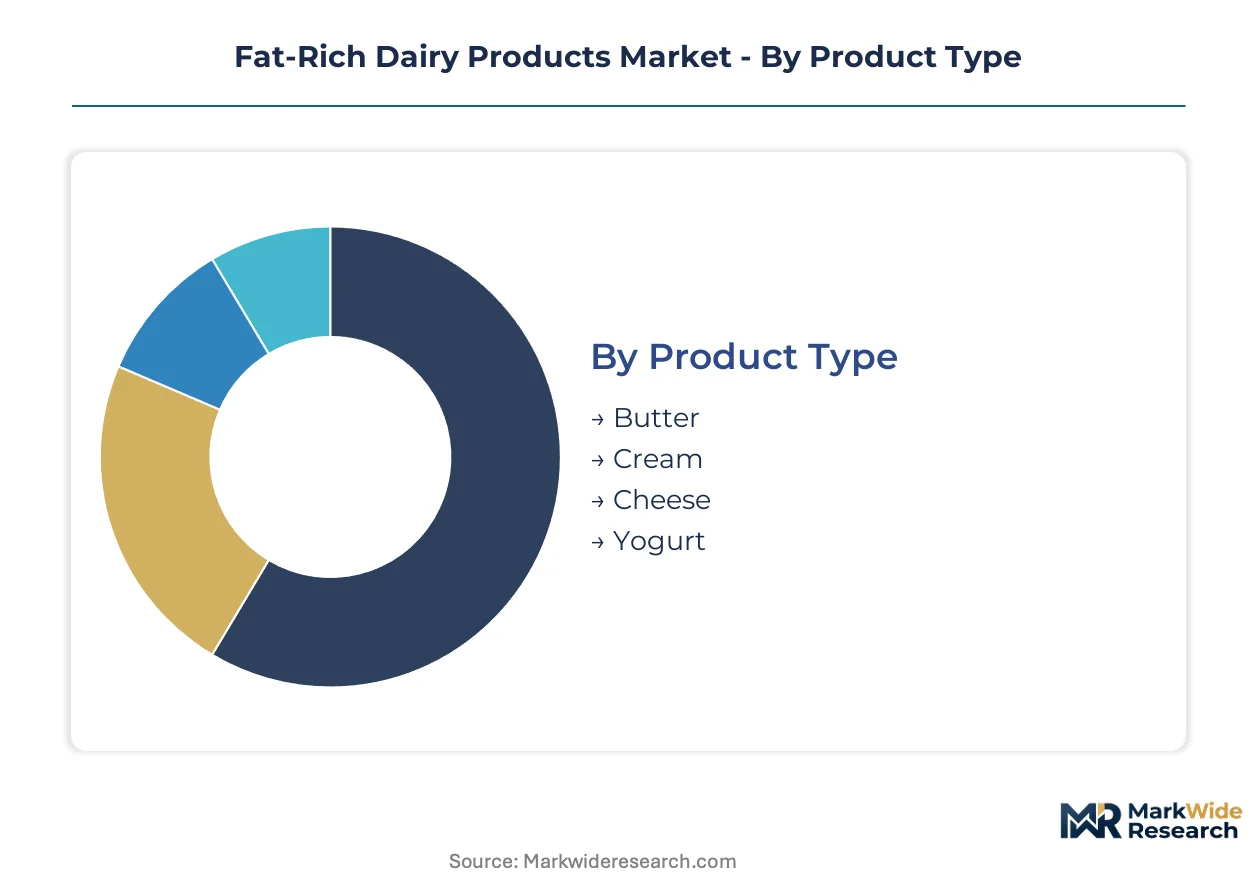
Segmentation in fat-rich dairy products reveals distinct margin profiles and service intensity requirements across product categories. Processing complexity, cold-chain demands, and end-use specifications create differentiated competitive arenas that reward specialized capabilities over commodity scale.
Product Type:
After-sales service intensity varies sharply across product categories, with aged cheese requiring inventory financing and quality monitoring that butter and cream operations rarely match.
- Cheese:Aged varieties command extended holding periods and controlled humidity storage, creating working capital intensity that favors processors with established affineur relationships. Protected designation origin premiums in France, Italy, and Spain concentrate value capture among heritage producers with documented provenance chains. Demand concentrates in European foodservice channels where menu differentiation through regional cheese boards drives procurement specifications.
- Cream:Industrial volumes serve sauce and confectionery manufacturers requiring standardized fat content and whipping stability across batch consistency. Asia-Pacific hotel chains and quick-service restaurants are incorporating cream-based preparations into standardized menus, pulling through foodservice-grade volumes from New Zealand and Australian processors with established export cold-chain networks.
- Butter:Churned fat products range from sweet cream to cultured varieties, with European traditions favoring lactic fermentation that extends production timelines.
- Yogurt:Strained and Greek-style variants concentrate protein and fat through membrane filtration, creating texture profiles distinct from set or stirred formats.
By volume, cheese leads. By growth pace, cream is ahead.
Application:
Application segmentation tracks formulation requirements that determine processor technical specifications and customer stickiness.
- Baked Goods:Laminated pastries and shortcrust formulations demand precise plasticity ranges in butter, with industrial bakeries specifying slip points and melting curves that constrain supplier qualification. European and Japanese bakery chains maintain rigid vendor approval processes that lock in multi-year supply relationships.
- Snacks:Extruded and puffed formats incorporate butter and cheese powders for flavor delivery, with powder particle size and fat encapsulation determining shelf stability and mouthfeel. Snack manufacturers in South Korea and Thailand are expanding cheese-flavored product lines, pulling through specialized spray-dried and roller-dried ingredient volumes.
- Sauces:Emulsion stability requirements in cream-based preparations dictate homogenization specifications and heat treatment protocols.
- Dressings:Viscosity control and pourability specifications vary across retail and foodservice packaging formats.
By installed base, baked goods anchor volume. By expansion trajectory, snacks are climbing fastest.
End User:
End-user categories reflect procurement sophistication and price elasticity gradients that shape go-to-market economics.
- Foodservice Providers:Restaurant groups and hotel chains specify full-category dairy portfolios with unified traceability documentation, favoring processors with integrated butter, cream, and cheese lines over single-product competitors. Procurement consolidation in Japan and South Korea has compressed supplier counts while raising documentation requirements.
- Manufacturers:Industrial buyers of cheese powders, butter fractions, and cream concentrates negotiate formula pricing tied to commodity futures, requiring processors with hedging capabilities and volume flexibility.
- Households:Retail packaging sizes and private-label penetration vary across supermarket formats.
- Retailers:Private-label development programs demand co-manufacturing relationships with dedicated production lines.
By contract value, foodservice providers dominate. By volume throughput, manufacturers process the most tonnage.
Distribution Channel:
Channel segmentation captures cold-chain infrastructure requirements and margin stacking that differ between direct and intermediated routes.
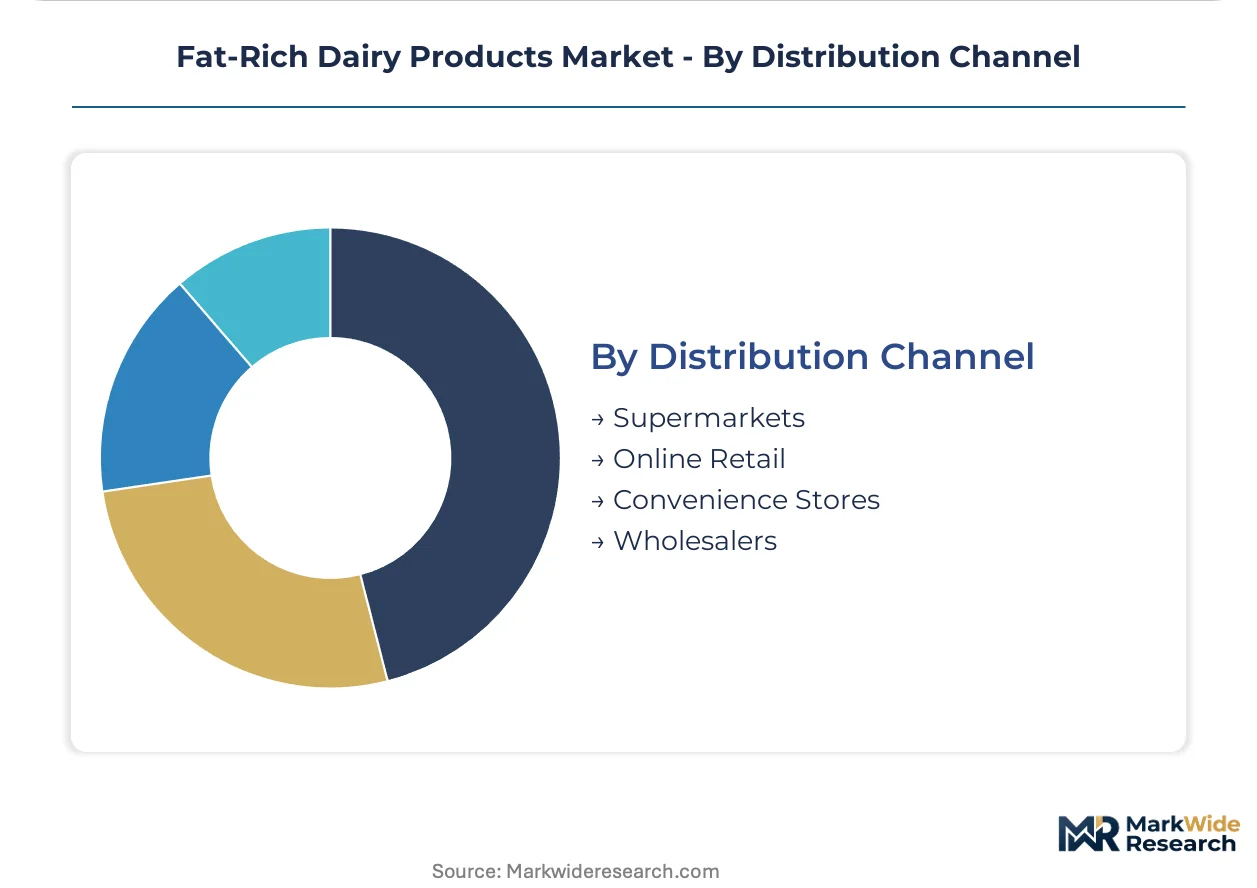
- Supermarkets:Multi-temperature distribution centers and dedicated dairy aisles create slotting fee structures that favor national brand portfolios with marketing support funds. European retailers are consolidating dairy category management around fewer suppliers with full-range capabilities.
- Online Retail:Direct-to-consumer chilled delivery requires insulated packaging and time-definite logistics that add cost but enable premium positioning and subscription models.
- Convenience Stores:Limited refrigeration space drives single-serve and extended-shelf-life product formats.
- Wholesalers:Cash-and-carry and delivered wholesale serve independent foodservice accounts with fragmented order patterns.
By revenue concentration, supermarkets lead. By channel expansion rate, online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon border adjustments are redirecting capital flows toward methane abatement infrastructure in export-oriented dairy regions. India's cooperative procurement networks and New Zealand's farm-gate ownership models represent divergent supply-side responses to tightening environmental compliance.
United States
Foodservice chains and industrial bakeries drive cream and butter demand through laminated pastry and sauce applications. FDA's Grade A Pasteurized Milk Ordinance governs interstate fluid cream safety standards. Wisconsin and California dairy clusters concentrate processing capacity for aged cheese and butter fractions serving domestic and export markets.
Germany
Transcritical CO2 refrigeration retrofits under EU F-Gas Regulation are reshaping cold-chain economics for cream storage facilities. EFSA-guided clean-label preferences accelerate butter-for-emulsifier substitution in baked goods. Bavaria and Lower Saxony host integrated dairy cooperatives with affineur networks for protected designation cheese aging.
India
Gujarat Cooperative Milk Marketing Federation and state dairy federations aggregate smallholder milk into butter and ghee processing streams. FSSAI compositional standards for ghee and butter determine organized sector market access against unorganized competitors. Anand district in Gujarat anchors cooperative processing infrastructure with rural procurement reach across western states.
New Zealand
Fonterra's farm-gate ownership model sustains raw milk cost advantages for industrial cream and cheese powder exports. Methane accounting protocols under emerging carbon border mechanisms threaten export cost structures without anaerobic digestion investment. Canterbury and Waikato regions concentrate pasture-based dairy farming with integrated processing for Asian foodservice markets.
France
Protected designation origin premiums for Comté, Roquefort, and other aged varieties concentrate value capture among heritage producers. REACH-compliant emulsifier alternatives enable butter reformulation in European bakery chains. Franche-Comté and Auvergne maintain affineur relationships and documented provenance chains for regional cheese board procurement.
Fat-Rich Dairy Products Market Vendor Landscape
On the supply side, the industry is consolidating around integrated processors with captive raw milk supply and multi-category portfolios. Tiered competitive dynamics separate heritage affineurs with protected designation holdings, scale-driven commodity processors, and cooperative federations with rural procurement networks. Dominant competitive moves include backward integration into regional milk pools and direct-to-restaurant distribution bypassing wholesale intermediaries.
Within the cooperative federation tier, Fonterra Co-operative Group and Gujarat Cooperative Milk Marketing Federation exemplify divergent geographic models—pastoral export orientation versus dense smallholder aggregation. Lactalis Group anchors European value capture through heritage brand portfolios and affineur network relationships. These three occupy positions spanning farm-gate ownership, rural procurement density, and premium aging infrastructure respectively.
| Leading Market Players |
|---|
| Arla Foods |
| Land O'Lakes |
| Nestlé |
| Saputo Inc. |
| Royal FrieslandCampina |
| Danone |
| Fonterra Co-operative Group |
| Gujarat Cooperative Milk Marketing Federation |
| Lactalis Group |
| Others |
Supply Flow & Price Mechanics
New Zealand's farm-gate ownership concentration anchors raw milk cost structures that cascade through butter and cheese powder export pricing, concentrating margin capture among processors with backward integration into pasture-based supply pools rather than spot-market dependent competitors.
Pricing Analysis
Protected designation origin certification creates the primary spread between heritage affineur-aged cheeses and commodity-grade alternatives, with Comté and Roquefort premiums reflecting documented provenance chains. Three-tier pricing structure across premium, standard, and economy levels stratifies according to aging duration and fat content specifications. Pricing pressure stems from feed cost volatility in Argentina and New Zealand transmitting into farm-gate milk costs. Industrial bakery manufacturers exhibit highest price sensitivity due to formula pricing tied to commodity futures, while foodservice procurement teams prioritize traceability documentation over unit cost.
Supply Chain Analysis
Extended payment terms from European supermarket chains compress working capital for cream and butter processors, driving supply-chain finance facility adoption among mid-tier operators. Raw material sourcing concentrates in New Zealand, India, and Germany, with Fonterra's cooperative structure and Gujarat's rural procurement networks representing divergent aggregation models. Production draws from pasture-based systems in Oceania, grain-fed operations in North America, and mixed smallholder-cooperative structures in South Asia. Single-source vulnerability persists in specialized starter culture supply for aged cheese production. Distribution runs through integrated cold-chain networks serving foodservice consolidation in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy procurement is shifting toward full-category portfolio contracts with unified traceability, creating platform-economics dynamics where processors with integrated butter, cream, and cheese lines capture disproportionate share against single-product competitors.
For Market Incumbents: Pre-empt plant-based substitution threats by accelerating precision fermentation partnerships that replicate aged cheese mouthfeel without traditional aging infrastructure. Deepen backward integration into regional milk pools to secure cost advantages against spot-market exposed rivals. Invest in anaerobic digestion capacity to monetize carbon credits under emerging EU and California cap-and-trade frameworks. For New Entrants and Emerging Players: South Asian foodservice channels present underpenetrated white-space for clarified butter and ghee derivatives targeting hotel chain menu standardization. Precision fermentation platforms offer entry into premium hard cheese segments without multi-year inventory holding requirements. Direct-to-restaurant distribution bypassing wholesale intermediaries provides differentiation against established processor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward cooperative federations with dense rural procurement networks and processors with transcritical CO2 refrigeration infrastructure already compliant with EU F-Gas Regulation deadlines. Long-term viability hinges on methane abatement capabilities and clean-label positioning aligned with EFSA-guided reformulation trends. Monitor carbon border adjustment mechanism implementation as inflection indicator for export-oriented processor cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Milk Pools | Fonterra's farm-gate ownership model secures raw milk cost advantages against spot-market competitors. |
| Precision Fermentation Platform Investment | Netherlands and California specialty manufacturers collapse capital requirements for aged cheese entry. |
| Transcritical CO2 Refrigeration Retrofit | German and Danish processors face compressed timelines under EU F-Gas Regulation phasedown mandates. |
| Direct-to-Restaurant Distribution Buildout | Japan and South Korea foodservice consolidation favors captive delivery networks over wholesale intermediaries. |
| Anaerobic Digestion Infrastructure Deployment | Methane capture installations generate compliance offsets under emerging cap-and-trade frameworks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade databases, regulatory filings, and industry association reports, combining structured interviews with dairy processing executives, cooperative federation procurement heads, foodservice chain category managers, and cold-chain logistics operators. Validation sources include Fonterra annual disclosures, EU ETS transaction records, FSSAI compositional standards, and customs export data from New Zealand and India. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Forecast inputs incorporate product type segmentation across cheese, cream, butter, and yogurt variants; application splits spanning baked goods, snacks, sauces, and dressings; end-user categories covering foodservice providers, manufacturers, and households; and distribution channel dynamics through supermarkets, online retail, and wholesale intermediaries. CAGRs derive from elasticity modeling against population growth, urbanization rates, and foodservice expansion indices across the analysis window. Industry-specific inputs include methane accounting protocol adoption timelines and carbon border adjustment mechanism implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or cooperative federation consolidation would shift outcomes. Macroeconomic deviation in feed commodity markets, regulatory acceleration in F-Gas compliance deadlines, or technological breakthroughs in plant-based fat replication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Market
Dairy Products
Canada Dairy Market
Dairy Products
Paneer Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Plain Yogurt Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Germany Dairy Market
Dairy Products
Skimmed Milk Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
China Milk Protein Market
Dairy Products
Europe Dairy Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market