
 Canada Chocolate Market | 2026-2036
Canada Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Chocolate Market Insights
Single-serve and mini-format bundling is shifting how Canadian consumers purchase chocolate, replacing traditional large-bar commitments with variety packs suited to portion control and trial. Mondelēz International Inc. leverages its global scale to dominate multiplex packaging across mass retail channels. Purdys Chocolatier anchors its competitive position through British Columbia-based manufacturing and regional brand loyalty. Mars Incorporated differentiates via seasonal assortment bundles that command premium shelf placement during holiday windows.
Canada chocolate encompasses cocoa-based confectionery products manufactured through roasting, grinding, conching, and tempering processes, typically containing cocoa mass, cocoa butter, sugar, and milk solids, formulated for direct consumption across retail and foodservice channels. Milk chocolate occupies the largest volume position due to mainstream palatability and established household penetration, while dark chocolate registers the fastest expansion as health-conscious consumers prioritize higher cocoa content and reduced sugar formulations. Specialty Stores capture concentrated margin pools through experiential retail and premium positioning, whereas Online Retail extends reach into remote provinces with limited brick-and-mortar premium access.
Health Canada governs nutritional labeling and health claims under the Food and Drugs Act, compelling manufacturers to reformulate for cleaner ingredient decks. The Canadian Food Inspection Agency enforces Safe Food for Canadians Regulations that dictate traceability and import compliance across cocoa supply chains. The Competition Act, administered by the Competition Bureau, scrutinizes environmental marketing claims including sustainable sourcing assertions. Stakeholders must monitor evolving single-use plastic packaging restrictions in Ontario and Quebec while calibrating premium positioning against private-label encroachment in conventional grocery.
Market Dynamics
Single-serve and mini-format bundling is compressing traditional large-bar purchasing patterns across Canadian retail channels. Health Canada's evolving labeling mandates under the Food and Drugs Act are forcing accelerated reformulation cycles that favor manufacturers with captive R&D infrastructure.
Growth Catalysts
- Health-Conscious Formulation:Dark chocolate segments benefit from consumer prioritization of higher cocoa content and reduced sugar. Health Canada permits cocoa percentage claims that drive shelf differentiation.
- Safe Food for Canadians Regulations:Traceability mandates strengthen brand trust among premium buyers. Compliance investments create barriers that protect established Canadian manufacturers.
- Ontario and Quebec Urban Density:Concentrated retail footprints in Toronto and Montreal enable efficient distribution of perishable premium assortments. Specialty store expansion tracks population-weighted income growth in these provinces.
Market Restraints
- Cocoa Butter Price Volatility:West African supply concentration exposes Canadian processors to weather-driven input cost swings. Hedging instruments remain underutilized among mid-tier domestic brands.
- Single-Use Plastic Restrictions:Ontario and Quebec packaging regulations force capital-intensive transitions to compostable films. Smaller regional chocolatiers lack scale to absorb compliance costs.
- Private-Label Encroachment:Conventional grocery chains are expanding house-brand premium lines that replicate artisan positioning at lower price points. Loyalty fragmentation pressures margin pools.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick exhibit lower specialty chocolate access relative to per-capita income. Direct-to-consumer shipping models can bypass sparse brick-and-mortar coverage.
- Online Retail Infrastructure:E-commerce platforms enable national reach for British Columbia and Quebec artisan brands. Cold-chain logistics investments unlock year-round shipping of temperature-sensitive products.
- Clean-Label Certification:Organic and fair-trade designations command measurable price premiums in urban Ontario markets. Third-party verification creates defensible positioning against mass-market competitors.
Industry Challenges
- Confectionery Science Talent Scarcity:Specialized expertise in tempering and conching processes is concentrating among retiring cohorts. Technical training pipelines through Canadian food science programs remain underdeveloped.
- Legacy Equipment Integration:Automated packaging lines must interface with batch-scale artisan production systems. Retrofit complexity delays capacity expansion timelines for growing regional brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Chocolate Market |
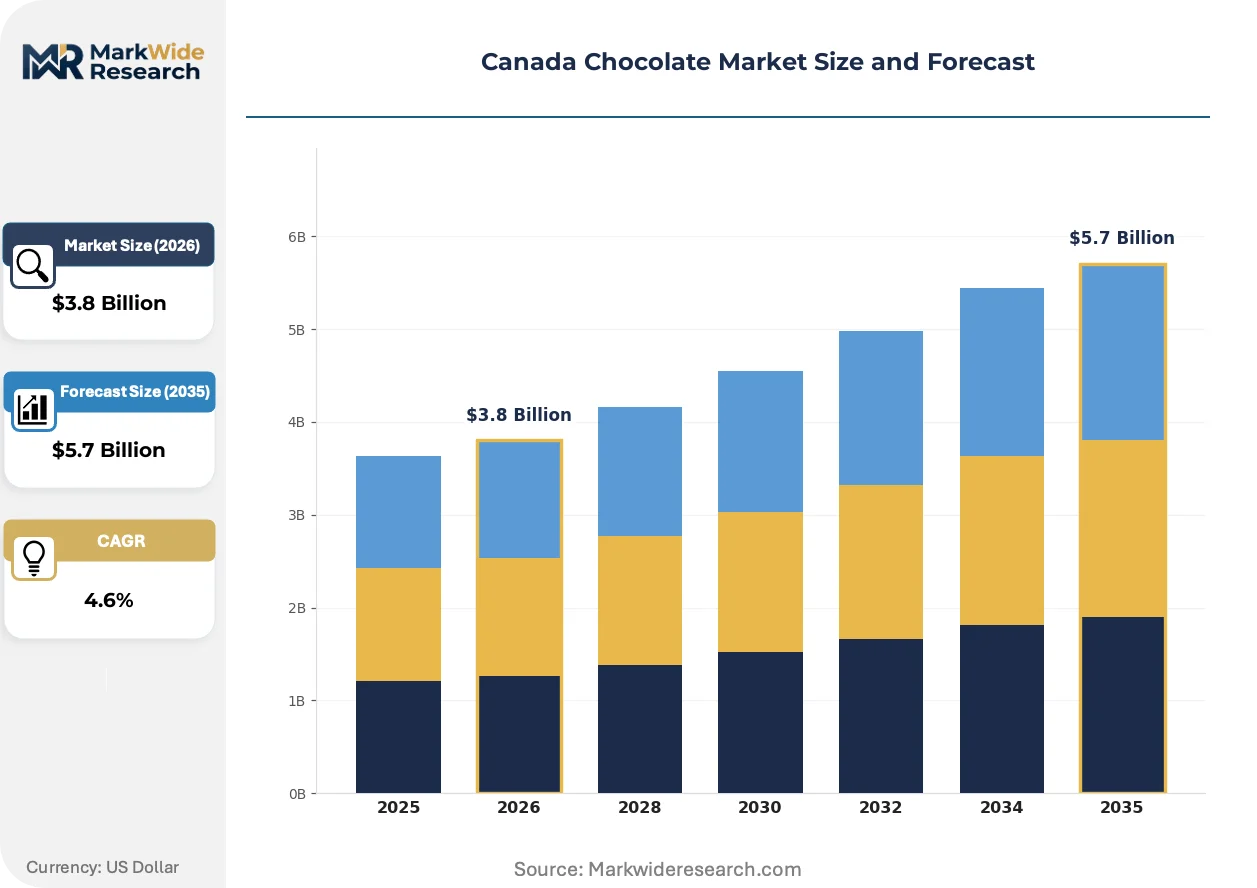
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Packaging Type: Bar, Box, Bag, Bulk Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores Customer Type: Children, Adults, Health-conscious Consumers, Gift Buyers |
| Companies Covered | Mondelēz International Inc., Chocoladefabriken Lindt & Sprüngli AG, Mars Incorporated, Ferrero International SA, The Hershey Company, Nestlé SA, Purdys Chocolatier, Roger's Chocolates, Laura Secord, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Chocolate Market Trends and Innovations
Reformulation technologies and alternative ingredient sourcing are compressing development cycles across Canadian chocolate manufacturing. Regulatory pressure on sugar content and packaging waste is simultaneously accelerating innovation investment.
Precision fermentation-derived cocoa butter alternatives are integrating into premium product lines as manufacturers seek supply security. Specialty chocolatiers in British Columbia and Quebec are piloting these ingredients to maintain mouthfeel profiles while reducing West African supply dependence. This integration is enabling shorter ingredient decks that satisfy Health Canada clean-label preferences.
Health Canada's front-of-package nutrition symbol regulations are reshaping formulation priorities across all cocoa concentration tiers. Products exceeding sugar thresholds must carry mandatory warning labels that compress retail placement options. Dark chocolate segments with elevated cocoa percentages are adapting fastest by emphasizing existing compliance advantages in marketing communications.
Subscription-based replenishment models are displacing conventional grocery replenishment among affluent urban households. Direct-to-consumer platforms in Toronto and Vancouver are capturing recurring revenue through curated assortments. This behavioral shift is most visible in Ontario, where delivery density supports economically viable cold-chain logistics for temperature-sensitive products.
Canada Chocolate Market Segmentation
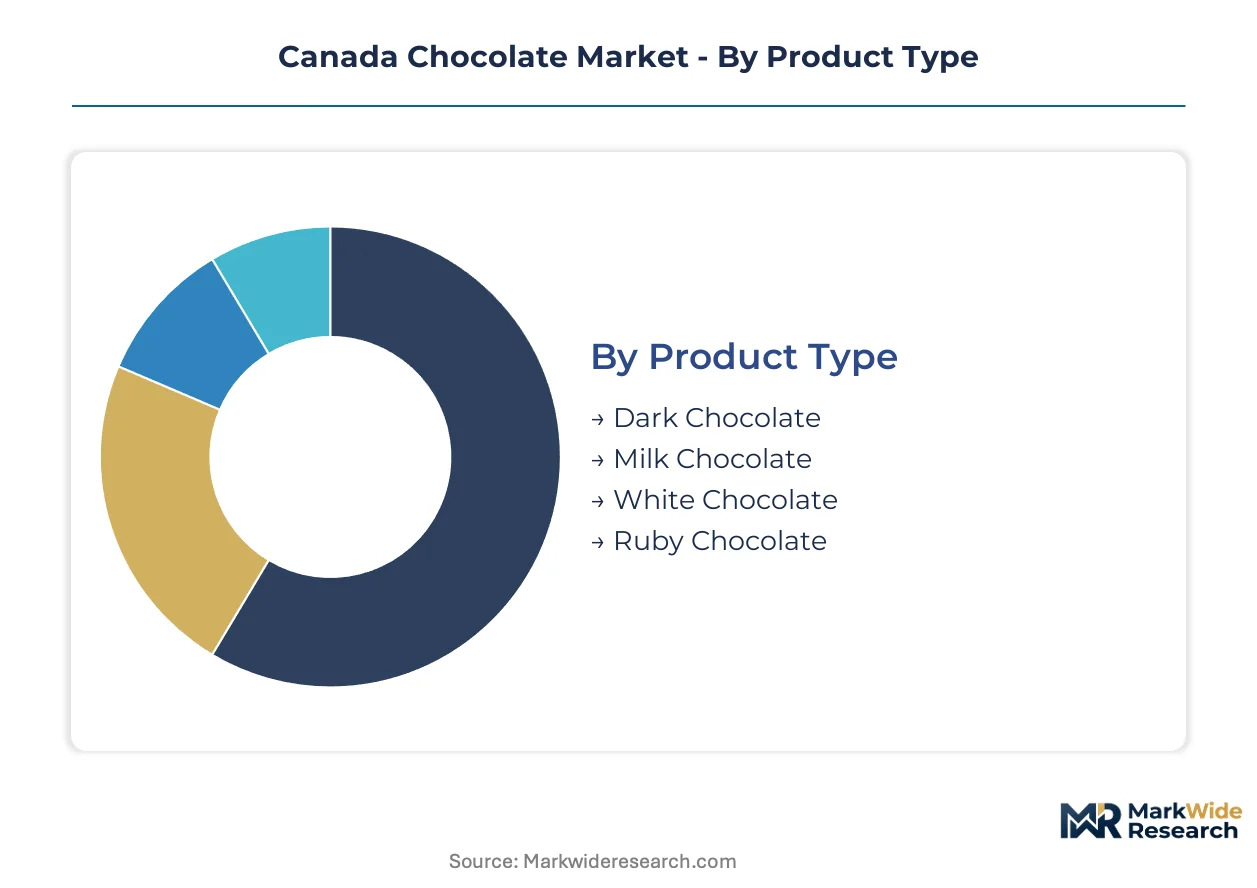
Canadian chocolate manufacturers calibrate formulation, packaging, and channel strategy against distinct consumer microsegments. Health Canada labeling mandates and provincial retail density patterns create divergent margin profiles across each axis.
Product Type:
Cocoa concentration and butterfat ratios define technical specifications, shelf positioning, and regulatory exposure across Health Canada's nutrition symbol framework.
- Dark Chocolate:Formulations with 70% or higher cocoa mass minimize sugar content and qualify for clean-label positioning. Health-conscious households in Toronto and Vancouver drive concentrated demand, with specialty retailers capturing premium margins through origin-specific sourcing claims.
- Milk Chocolate:Standard 30-40% cocoa formulations with added milk solids dominate household penetration and impulse purchase occasions. Quebec's dairy supply chain proximity gives domestic processors cost advantages in this segment.
- White Chocolate:Cocoa butter-based formulations without cocoa solids occupy niche gifting and baking applications. Seasonal demand spikes concentrate in Ontario holiday retail windows.
- Ruby Chocolate:Citric acid-processed cocoa bean varieties deliver distinctive color and fruit-forward flavor profiles. Limited production scale restricts availability to premium specialty channels in Vancouver and Montreal.
Mature deployment sits with Milk Chocolate. Newer deployment is concentrated in Dark Chocolate.
Packaging Type:
Format economics align with consumption occasion fragmentation and Ontario's single-use plastic compliance timelines.
- Bar:Traditional molded formats dominate everyday consumption and brand recognition. Convenience store distribution in Quebec and Ontario sustains volume throughput despite compressing per-unit margins.
- Box:Assortment configurations command gifting occasion premiums and seasonal shelf placement. Urban specialty retailers in Toronto and Calgary extract maximum margin through experiential unboxing presentations.
- Bag:Bite-size and mini-format configurations serve portion-control demand and trial behavior. Bulk pricing strategies in conventional grocery channels displace large-bar commitments.
- Bulk:Unwrapped or foodservice-scale formats supply bakery and hospitality channels. Direct B2B relationships with Ontario and British Columbia food manufacturers bypass retail margin structures.
Volume leadership belongs to Bar formats. Margin expansion concentrates in Box configurations.
Distribution Channel:
Channel selection determines regulatory compliance burden, cold-chain requirements, and customer data capture depth.
- Supermarkets:National banner networks provide mass-market reach and promotional scale. Loblaws and Sobeys shelf placement decisions in Ontario and Quebec dictate mainstream brand visibility.
- Specialty Stores:Curated assortments and staff expertise justify price premiums in affluent urban corridors. Vancouver's Granville Island and Toronto's Distillery District clusters concentrate independent chocolatier presence.
- Online Retail:Direct-to-consumer platforms enable national reach for temperature-sensitive products. Cold-chain logistics investments unlock year-round shipping to Atlantic Canada provinces with sparse brick-and-mortar premium access.
- Convenience Stores:Impulse-oriented formats prioritize single-serve and immediate consumption occasions. Quebec's Couche-Tard network density supports regional brand trial penetration.
Transaction volume concentrates in Supermarkets. Value per transaction climbs fastest in Online Retail.
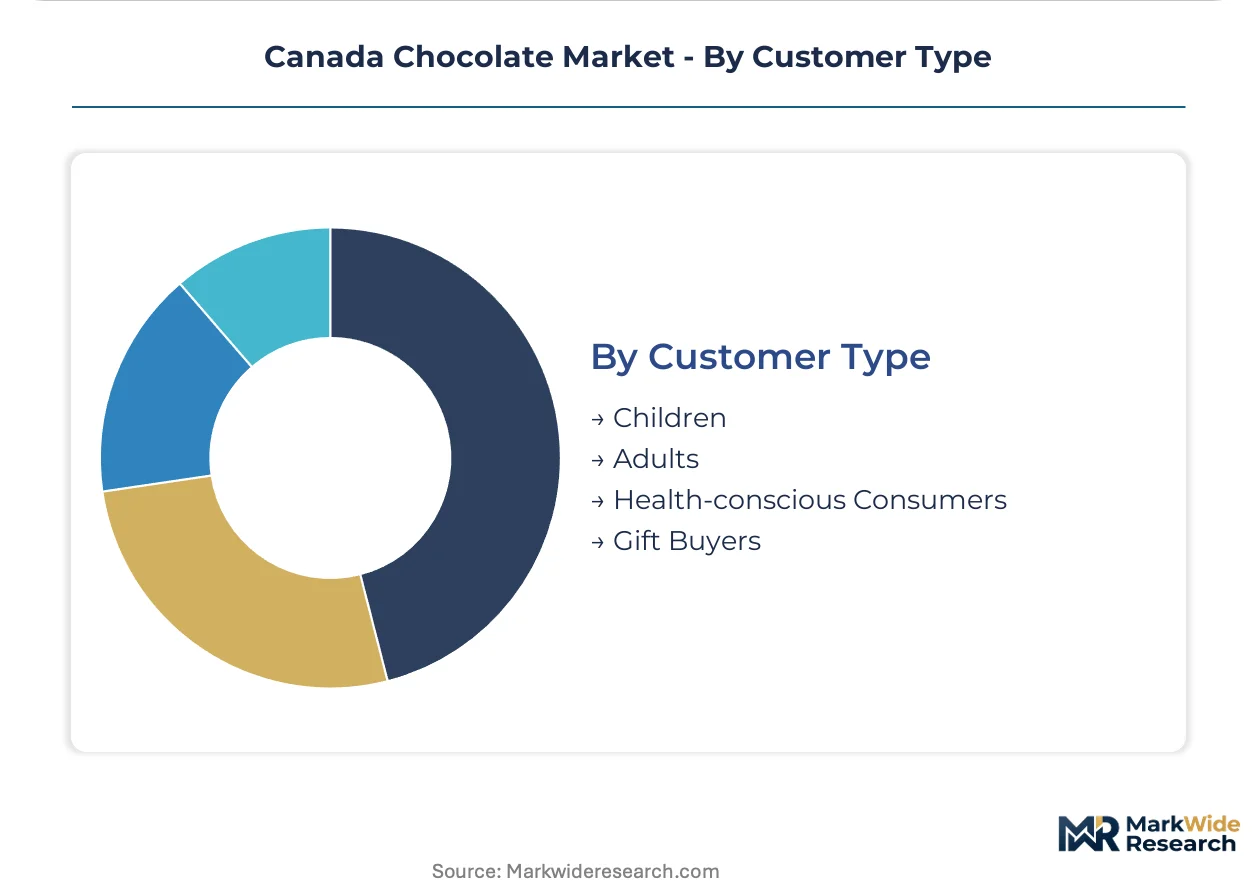
Customer Type:
Purchase motivation and price sensitivity diverge sharply across demographic and psychographic boundaries.
- Children:Sugar-forward preferences and licensed character tie-ins drive parental purchase decisions. Health Canada's front-of-package warning label regulations constrain formulation options for this segment.
- Adults:Mainstream palatability requirements sustain milk chocolate volume while enabling dark chocolate trial migration. Workplace consumption and personal indulgence occasions fragment across format sizes.
- Health-conscious Consumers:Cocoa percentage claims, organic certification, and reduced-sugar formulations command measurable price premiums. Urban Ontario markets exhibit highest per-capita spending intensity.
- Gift Buyers:Premium packaging, seasonal assortments, and brand heritage narratives justify occasion-specific spending. Holiday windows in Quebec and Ontario generate concentrated revenue spikes.
Volume foundation rests with Adults. Steepest expansion trajectory belongs to Health-conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's chocolate production concentrates in Ontario and Quebec while consumption spreads unevenly across provinces. British Columbia generates disproportionate premium demand relative to its population. Atlantic Canada remains underserved by specialty retail infrastructure.
Ontario
Toronto's dense urban corridor drives volume throughput for both mass-market and premium segments. Health Canada's front-of-package nutrition symbol regulations hit hardest here due to high retail visibility. The Greater Toronto Area hosts concentrated distribution hubs serving national grocery banners.
Quebec
Montreal anchors artisan chocolate manufacturing with proximity to dairy supply chains and European-influenced consumer preferences. The province's Couche-Tard convenience network enables impulse trial penetration unmatched elsewhere. Seasonal gifting demand spikes concentrate in Quebec's holiday retail windows.
British Columbia
Vancouver's Granville Island cluster sustains independent chocolatier presence with experiential retail formats. Direct-to-consumer shipping models from this province bypass sparse brick-and-mortar coverage in remote regions. Clean-label certification commands measurable price premiums in this market.
Alberta
Calgary's specialty retail footprint expands alongside population-weighted income growth in energy sector households. The province exhibits lower private-label penetration than Ontario, preserving margin pools for branded manufacturers. Urban corridor development tracks premium chocolate access expansion.
Atlantic Canada
Nova Scotia and New Brunswick show lower specialty chocolate access relative to per-capita income. Cold-chain logistics investments unlock year-round direct-to-consumer shipping to these provinces. Sparse retail infrastructure forces brands to rely on e-commerce platforms for market presence.
Canada Chocolate Market Competitive Landscape
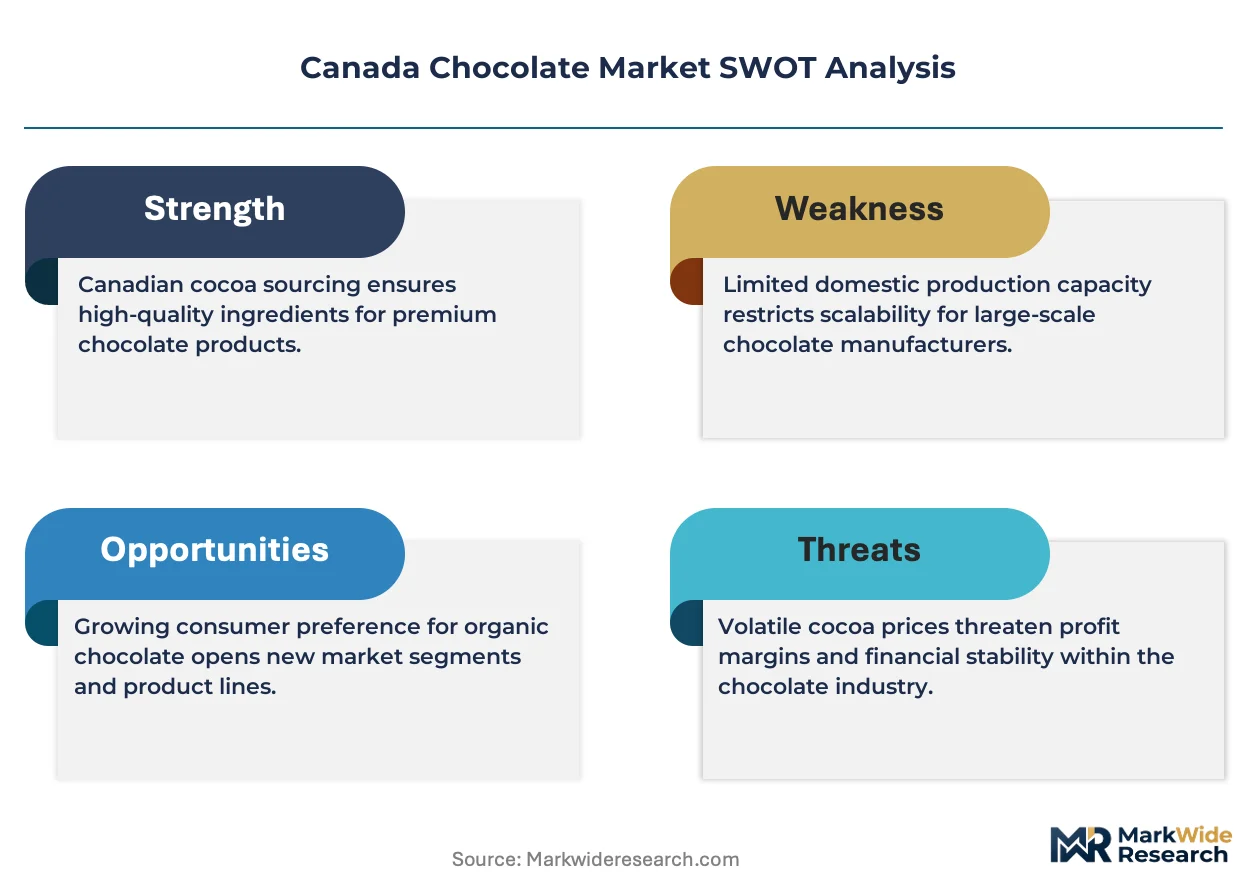
The competitive structure tilts toward multinational scale players with captive R&D infrastructure. Consolidation around mass retail shelf placement creates barriers for mid-tier domestic brands. Three archetypes dominate: global conglomerates with multiplex packaging advantages, regional heritage brands with loyalty-driven pricing power, and artisan specialists with clean-label positioning. Capacity expansion and portfolio diversification represent the primary competitive moves across tiers.
Among global-scale operators, Mondelēz International Inc. and Mars Incorporated exemplify the mass-market archetype with national distribution reach. Purdys Chocolatier represents the regional heritage position anchored in British Columbia manufacturing. These three occupy distinct competitive spaces without direct overlap in consumer targeting or channel strategy.
| Leading Market Players |
|---|
| Mondelēz International Inc. |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mars Incorporated |
| Ferrero International SA |
| The Hershey Company |
| Nestlé SA |
| Purdys Chocolatier |
| Roger's Chocolates |
| Laura Secord |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation-derived cocoa butter alternatives are compressing cost structures while redrawing supplier maps across Canadian chocolate manufacturing. These biotechnological inputs simultaneously reduce West African commodity dependence and enable cleaner ingredient decks that satisfy Health Canada labeling mandates.
Pricing Analysis
Margin tightening in premium tiers reflects cocoa butter price volatility and compostable packaging compliance costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by cocoa concentration and certification status. Cost compression accelerates in mass-market segments as private-label lines replicate artisan positioning. Health-conscious consumers in Toronto and Vancouver exhibit lowest price sensitivity, while conventional grocery shoppers in Quebec demonstrate highest elasticity.
Supply Chain Analysis
Confectionery science talent scarcity in Ontario and Quebec constrains production scaling for regional manufacturers. West African cocoa bean sourcing draws from Côte d'Ivoire, Ghana, and Nigeria, with Canadian processors anchoring secondary operations in these origins. Cocoa butter, milk solids from Quebec dairy networks, and precision fermentation alternatives constitute critical inputs. Single-source vulnerability concentrates in West African supply concentration exposed to weather-driven disruptions. Distribution runs through Loblaws and Sobeys banner networks with direct-to-consumer platforms gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's chocolate market operates as a supply-constrained environment where cocoa butter volatility and specialized talent scarcity prop pricing power for incumbent manufacturers with captive R&D infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into Quebec dairy supply chains and captive precision fermentation partnerships. Vertical control over cocoa butter alternatives mitigates West African supply disruption. Certification investment in organic and fair-trade designations creates defensible margin pools against private-label encroachment in Ontario conventional grocery. For New Entrants and Emerging Players: Precision fermentation technology platforms offer entry pathways into premium positioning without legacy commodity exposure. Atlantic Canada direct-to-consumer channels present the most penetrable geography given sparse specialty retail infrastructure. Cold-chain logistics partnerships with British Columbia artisan brands enable national reach without brick-and-mortar capital deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational confectionery conglomerates seeking clean-label capability. Long-term viability favors regional heritage brands with loyalty-driven pricing power in Quebec and British Columbia. Watch Health Canada front-of-package regulation enforcement intensity as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Butter Alternatives | Precision fermentation partnerships reduce West African supply dependence and stabilize input costs. |
| Clean-Label Certification Investment | Organic and fair-trade designations command measurable price premiums in urban Ontario markets. |
| Direct-to-Consumer Platform Launch | E-commerce unlocks year-round national reach for temperature-sensitive premium assortments. |
| Atlantic Canada Distribution Expansion | Nova Scotia and New Brunswick underpenetration creates first-mover advantage for specialty positioning. |
| Compostable Packaging Transition | Regulatory compliance in Ontario and Quebec preserves shelf access against single-use plastic restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with brand managers, category buyers at Loblaws and Sobeys, supply planners, and channel sales heads combined with Health Canada enforcement databases and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Data-stream reconciliation across multiple inputs enabled forecast construction throughout the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and customer motivation archetype. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timing and cocoa commodity cycle positioning. Cocoa butter price forecasting and precision fermentation adoption curves served as industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration, cocoa disease outbreaks in West Africa, and consumer preference shifts beyond health-conscious positioning. Forecasts reflect documented assumptions about compliance timelines and technology cost curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Dark Chocolate Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Functional Confectionery Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Cocoa and Chocolate Market
Confectionery
UK Confectionery Market
Confectionery
Chocolate Hazelnut Spread Market