
 Asia-Pacific Yogurt Market | 2026-2036
Asia-Pacific Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Yogurt Market Outlook
China's GB 19302 dairy safety standard is repositioning production requirements across the Asia-Pacific Yogurt Market. Inner Mongolia Yili Industrial Group leverages its captive dairy farming network to secure raw milk traceability. Danone anchors its premium positioning through specialized probiotic strain portfolios. Yakult Honsha dominates the drinking yogurt segment with dedicated lactobacillus cultivation expertise.
Yogurt denotes a fermented milk product containing live bacterial cultures, primarily Lactobacillus bulgaricus and Streptococcus thermophilus, with protein content typically ranging from 3.3% to 10% depending on straining processes and milk solids concentration. The product functions as both a nutritional staple and functional food载体 delivering gastrointestinal health benefits through maintained viable culture counts. Drinking yogurt commands accelerated momentum across urban Asian markets where portability aligns with commuter consumption patterns. Greek yogurt occupies the premium margin tier due to its elevated protein density and extended straining production cycle. Organic yogurt remains supply-constrained across the region, with certified dairy sourcing limiting volume scalability.
SAMR's GB standards framework and Japan's Food Sanitation Act jointly determine permissible additive regimens and labeling protocols for cultured dairy products across the region. India's FSSAI enforces progressively stricter microbiological limits on retail yogurt, elevating compliance costs for unbranded local producers. Stakeholders must monitor evolving strain-specific health claim regulations as science-backed positioning becomes the primary battleground for premium shelf space.
Market Dynamics
China's SAMR is compressing production timelines through revised GB 19302 dairy safety standards that mandate end-to-end cold-chain traceability. This regulatory pressure is forcing facility upgrades across the Asia-Pacific Yogurt Market while advantaging operators with captive dairy networks.
Growth Catalysts
- Probiotic strain innovation:Specialized lactobacillus cultivation is expanding functional positioning beyond basic nutrition. Japanese drinking yogurt formats demonstrate viable commercial pathways for gut-health claims.
- India's FSSAI microbiological limits:Tighter enforcement on retail yogurt is systematically displacing unbranded local producers. Branded manufacturers gain shelf space as compliance costs rise for informal competitors.
- Urban commuter consumption patterns:Portability requirements in Shanghai, Mumbai, and Tokyo are accelerating single-serve drinking yogurt adoption. Convenience stores and transit-adjacent retail are capturing incremental volume.
Market Restraints
- Organic milk supply scarcity:Certified dairy sourcing constraints limit organic yogurt scalability across the region. Farm conversion timelines and pasture certification create multi-year supply bottlenecks.
- Cold-chain infrastructure gaps:Last-mile refrigeration reliability in India's tier-two cities elevates spoilage risk. Temperature excursions degrade viable culture counts below label claims.
- Plant-based dairy substitution:Oat and almond fermented alternatives are capturing lactose-intolerant and vegan-adjacent consumers. Traditional dairy yogurt faces share pressure in premium urban segments.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Per capita yogurt consumption remains a fraction of Northeast Asian levels. Local dairy cooperatives offer partnership pathways for format localization.
- Senior nutrition applications:Protein-fortified and texture-modified yogurt for aging populations in Japan and South Korea opens premium positioning. MFDS functional food approval pathways support health claim substantiation.
- E-commerce subscription channels:Direct-to-home chilled delivery is bypassing traditional retail markup structures. Refrigerated logistics investments by platform operators enable recurring revenue models.
Industry Challenges
- Strain-specific health claim substantiation:Efficacy documentation requirements under Japan's Food Sanitation Act and China's SAMR demand clinical investment. Smaller producers lack resources for randomized trial execution.
- Multi-format production line complexity:Greek yogurt straining equipment, drinking yogurt homogenization systems, and cup-filling lines require distinct capital commitments. Asset utilization suffers when demand shifts between formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Yogurt Market |
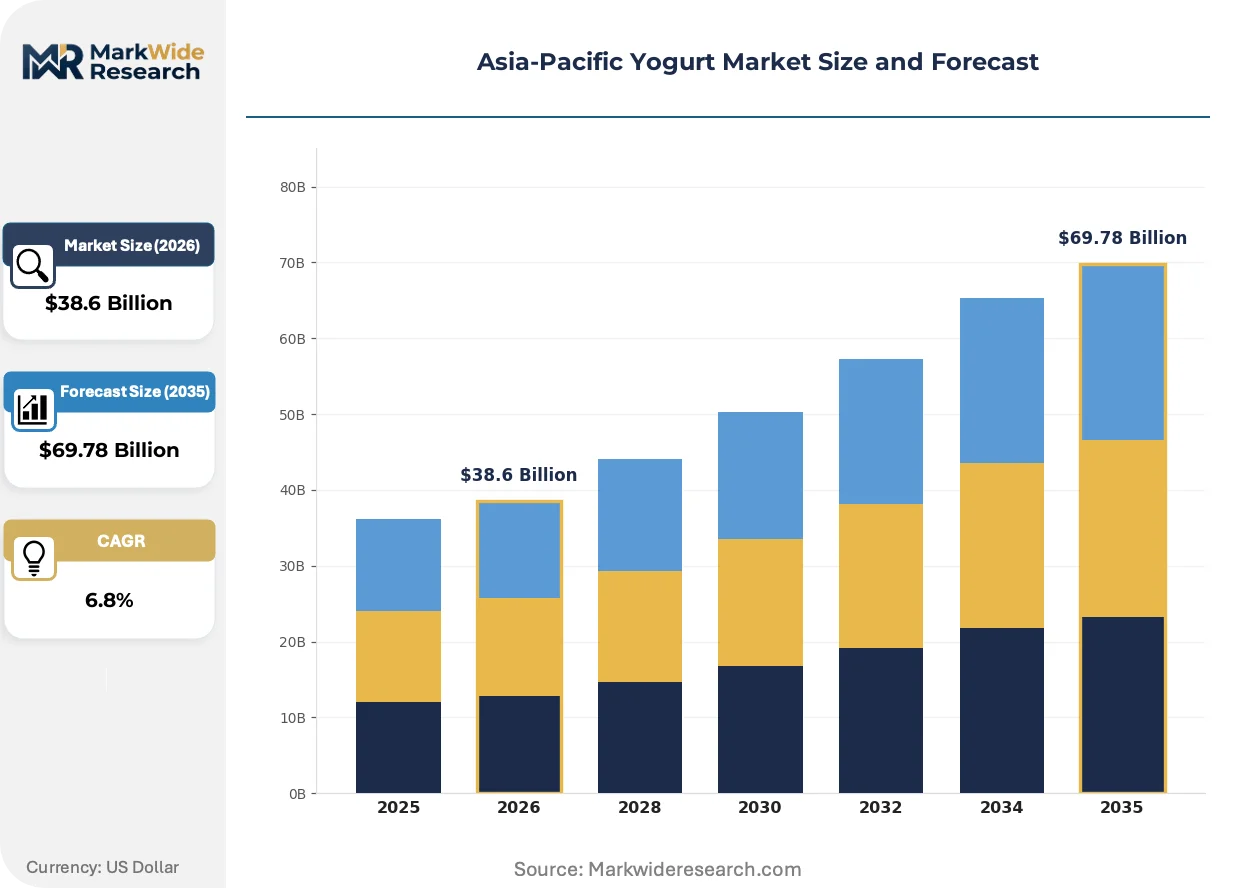
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Low-Fat Yogurt, Organic Yogurt, Drinking Yogurt Customer Type: Health-Conscious Consumers, Families, Students, Gastronomy Enthusiasts Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores Flavor Profile: Plain, Strawberry, Blueberry, Vanilla |
| Companies Covered | Inner Mongolia Yili Industrial Group, China Mengniu Dairy Company, Danone, Nestlé, Yakult Honsha, Meiji Holdings, Morinaga Milk Industry, Bright Dairy & Food, FrieslandCampina, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Yogurt Market Strategic Shifts
Active fermentation control technologies are compressing production variability while live culture stability engineering extends shelf life without cold-chain dependency. These advances are reshaping competitive economics across the Asia-Pacific Yogurt Market.
Aseptic fermentation with post-process probiotic addition is absorbing quality assurance functions previously handled by refrigerated distribution. Large-scale manufacturers in Thailand and Australia are adopting this approach to reduce cold-chain capital intensity. The technology is absorbing margin pressure from energy and logistics cost inflation while maintaining label culture counts.
China's SAMR GB standards framework is tightening additive regimens and mandating blockchain-enabled traceability for dairy inputs. Industrial consequence includes accelerated consolidation among processors lacking integrated farming operations. The drinking yogurt segment is responding fastest, with major operators deploying QR-code-linked supply chain visibility to preempt enforcement action.
Urban Chinese consumers are rotating toward functional yogurt positioned around sleep, immunity, and metabolic health rather than generic digestive benefits. E-commerce platforms and convenience store chains are displacing traditional supermarket dairy cases as primary purchase points. This behavioral shift is most visible in Shanghai and Shenzhen, where subscription-based personalized nutrition bundles now include probiotic yogurt as a core component.
Asia-Pacific Yogurt Market Segmentation
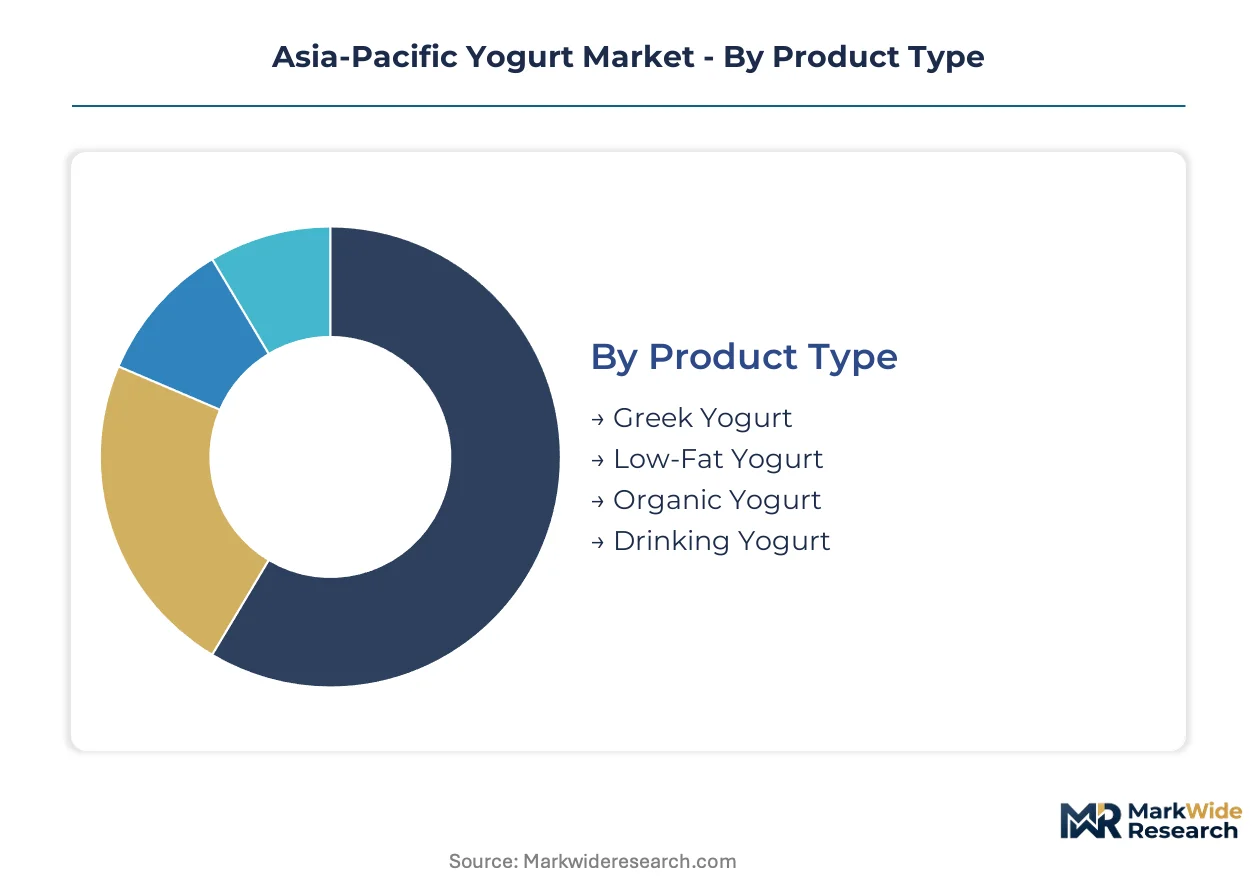
Product format differentiation determines manufacturing capital allocation and cold-chain intensity across the Asia-Pacific Yogurt Market. Consumer occasion segmentation shapes channel strategy and packaging specifications. Flavor and distribution categories reveal where premium positioning commands sustainable margin expansion.
Product Type:
Buyers in this category select based on protein density targets, texture preferences, and portability requirements rather than price alone.
- Drinking Yogurt:Liquid format with homogenized viscosity enabling single-serve bottle consumption. Commuter demand concentrates in Shanghai, Tokyo, and Mumbai transit corridors where convenience stores capture repeat purchase frequency. Portability requirements align with urban rail networks and office district retail clustering.
- Greek Yogurt:Strained preparation elevates protein content through whey separation, extending production cycles and equipment utilization. Tier-one Chinese cities and South Korean metropolitan areas concentrate demand where protein fortification justifies premium shelf positioning. Extended straining processes constrain volume scalability relative to standard formats.
- Low-Fat Yogurt:Reduced milk fat formulation targeting caloric restriction preferences across weight management consumer segments.
- Organic Yogurt:Certified dairy sourcing with pasture verification and additive restrictions limiting supply expansion.
Drinking yogurt leads volumes today; Greek yogurt is gaining share fastest.
Customer Type:
Volume concentration varies sharply by household composition and nutritional literacy levels across the region.
- Health-Conscious Consumers:Probiotic strain awareness drives purchasing decisions with explicit label scrutiny for viable culture counts. China's SAMR GB standards enforcement elevates trust in branded products with traceability documentation. Gut-health positioning and immunity claims resonate with this segment's functional food expectations.
- Families:Multi-person households prioritizing child nutrition and breakfast routine standardization. India's FSSAI microbiological limits displace unbranded alternatives in family purchase decisions.
- Students:Price-sensitive single-serve consumption with convenience store proximity determining brand selection.
- Gastronomy Enthusiasts:Premium artisanal formats and regional flavor experimentation driving specialty channel visitation.
Family purchasing dominates absolute consumption; health-conscious consumers expand per-unit spending most rapidly.
Distribution Channel:
Cold-chain reliability and last-mile temperature control separate viable from non-viable channel investments.
- Convenience Stores:Refrigerated display density in urban transit corridors and residential street corners. Japan's Food Sanitation Act compliance requirements advantage operators with standardized temperature monitoring. Single-serve impulse purchasing generates highest margin per unit.
- Online Retail:Subscription-based chilled delivery bypassing traditional retail markup with platform-operated refrigerated logistics. E-commerce penetration accelerates in Shanghai and Shenzhen where recurring delivery models stabilize household inventory.
- Supermarkets:Multi-format shelf space allocation with promotional cycling driving volume concentration.
- Specialty Stores:Curated artisanal and import positioning with educated staff enabling strain-specific health claim communication.
Supermarkets retain volume leadership; online retail climbs the fastest as platform infrastructure matures.
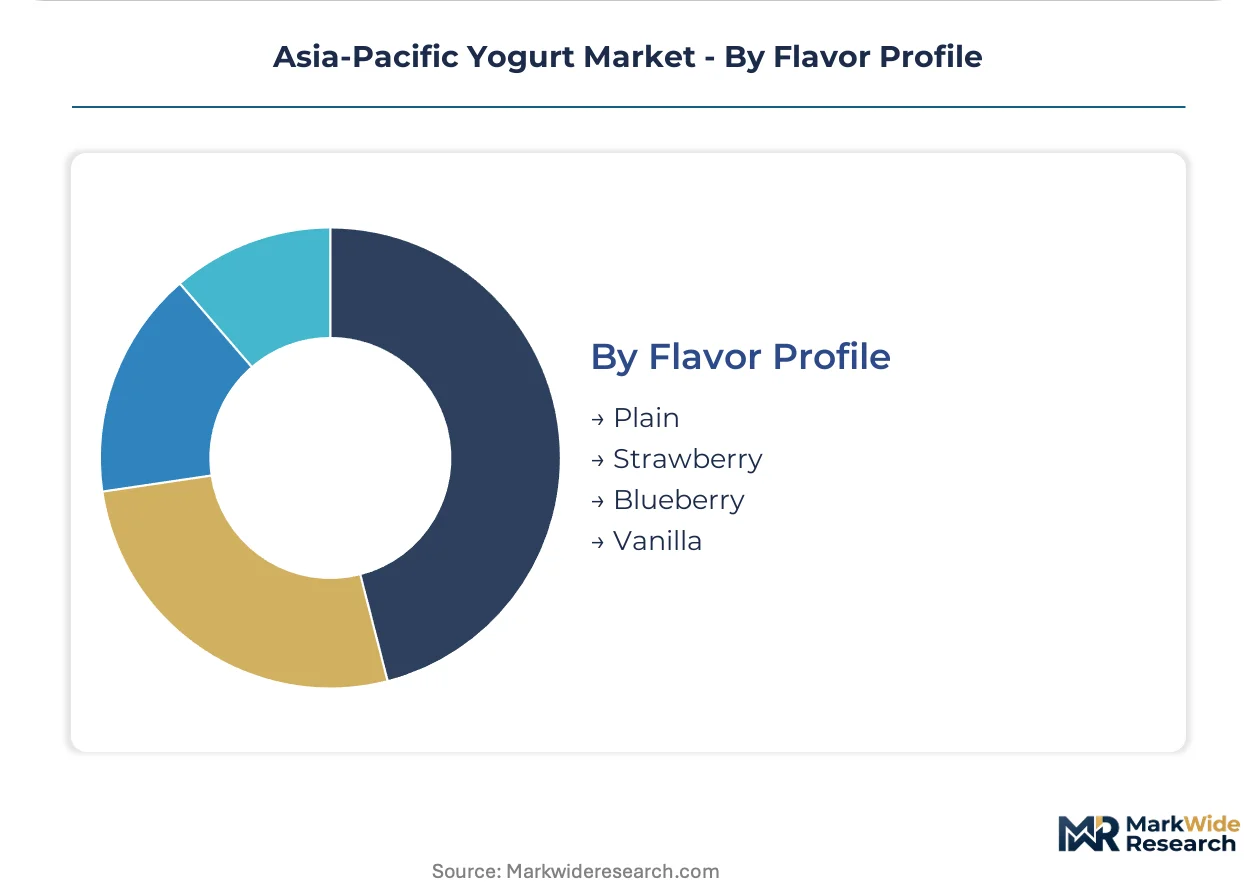
Flavor Profile:
Formulation complexity and ingredient sourcing constraints determine margin structure across taste categories.
- Plain:Unsweetened base format with live culture prominence enabling functional positioning and recipe versatility. South Korean and Japanese markets concentrate demand where plain yogurt serves as cooking ingredient and standalone consumption. Minimal additive regimens align with clean-label regulatory trajectories.
- Strawberry:Fruit preparation integration with regional sourcing from Shandong province and domestic Indian cultivation. Seasonal price volatility in fruit inputs compresses margin predictability.
- Blueberry:Premium positioning with import dependency elevating cost structure relative to domestic fruit alternatives.
- Vanilla:Universal palate acceptance with established supply chains minimizing formulation risk.
Plain yogurt anchors volume; strawberry flavor shows steepest expansion trajectory in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing talent clusters across China's northern provinces and India's Gujarat-Maharashtra corridor anchor production capacity expansion. Cold-chain engineering expertise concentrates in Japan's Kanto region and South Korea's Seoul Capital Area. These workforce distributions shape where probiotic cultivation facilities and aseptic packaging investments land.
China
Health-conscious urban consumers in Shanghai and Shenzhen drive probiotic-enriched drinking yogurt volumes. SAMR's GB 19302 dairy safety standards mandate blockchain-enabled traceability for raw milk inputs. Inner Mongolia's Hohhot cluster hosts integrated dairy farming operations securing captive milk supply for major processors.
India
FSSAI microbiological limits on retail yogurt systematically displace unbranded local producers in Mumbai and Delhi. Family purchasing dominates consumption with child nutrition positioning driving brand selection. Maharashtra's Pune-Nashik dairy belt concentrates cold-chain infrastructure investment from organized sector entrants.
Japan
MFDS functional food approval pathways support strain-specific health claims for aging population nutrition. METI-backed fermentation research programs accelerate active culture stability engineering. Tokyo-Yokohama corridor convenience store density captures commuter-driven single-serve consumption patterns.
South Korea
Seoul Capital Area demand concentrates for protein-fortified yogurt targeting senior nutrition segments. MFDS labeling protocols enforce viable culture count disclosure on packaging. Gyeonggi-do province dairy cooperatives supply raw milk to aseptic processing facilities serving premium channel distribution.
Australia
Organic yogurt demand outpaces certified dairy supply expansion across Sydney and Melbourne metropolitan markets. FSANZ additive regimens limit formulation flexibility for functional positioning. Victoria's Gippsland region hosts pasture-verified dairy farms supplying premium channel processors with export-grade milk solids.
Asia-Pacific Yogurt Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific Yogurt Market. Tier-one operators with captive dairy farming networks command traceability advantages under tightening SAMR and FSSAI compliance requirements. Three archetypes dominate: integrated dairy conglomerates with upstream farming control, multinational nutrition specialists with probiotic strain portfolios, and regional drinking yogurt specialists with fermentation expertise. Competitive moves center on aseptic processing technology licensing and cold-chain infrastructure partnerships with platform operators.
Among China-based integrated dairy conglomerates, Inner Mongolia Yili Industrial Group and China Mengniu Dairy Company exemplify the upstream-controlled archetype with captive raw milk sourcing. Japanese specialists Yakult Honsha and Meiji Holdings occupy positions within the dedicated lactobacillus cultivation tier, representing decades-long fermentation expertise. These named entities anchor industry-level commentary on where production gravity concentrates and which regulatory compliance capabilities differentiate sustainable positioning.
| Leading Market Players |
|---|
| Inner Mongolia Yili Industrial Group |
| China Mengniu Dairy Company |
| Danone |
| Nestlé |
| Yakult Honsha |
| Meiji Holdings |
| Morinaga Milk Industry |
| Bright Dairy & Food |
| FrieslandCampina |
| Others |
Value Chain & Pricing Dynamics
Greek-to-drinking yogurt price divergence separates premium protein density from commodity portability, with SAMR cold-chain mandates amplifying cost differentials across both tiers. Certified organic sourcing creates a third price ceiling where pasture verification bottlenecks sustain margin premiums despite volume constraints.
Pricing Analysis
Drinking yogurt's bundled cold-chain service model contrasts with Greek yogurt's unbundled ingredient-grade positioning. Three-tier pricing structure across premium, standard, and economy levels tracks protein density and fermentation complexity. Price differentiation rests on SAMR traceability certification and captive dairy network access. Pricing pressure stems from aseptic processing technology licensing costs. Health-conscious consumers in Shanghai and Shenzhen show lowest price sensitivity; students and tier-two city families exhibit highest elasticity.
Supply Chain Analysis
GB 19302 certification gating under SAMR restricts raw milk sourcing to blockchain-traceable cooperatives in China's Inner Mongolia and Hebei provinces. Supply draws from lactobacillus strain cultivation facilities in Japan's Kanto region and aseptic packaging engineering clusters in South Korea's Gyeonggi-do. Cold-chain infrastructure gaps in India's tier-two cities create single-source vulnerability for viable culture preservation. Distribution runs through platform-operated refrigerated logistics in Chinese e-commerce channels and convenience store density in Japanese transit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
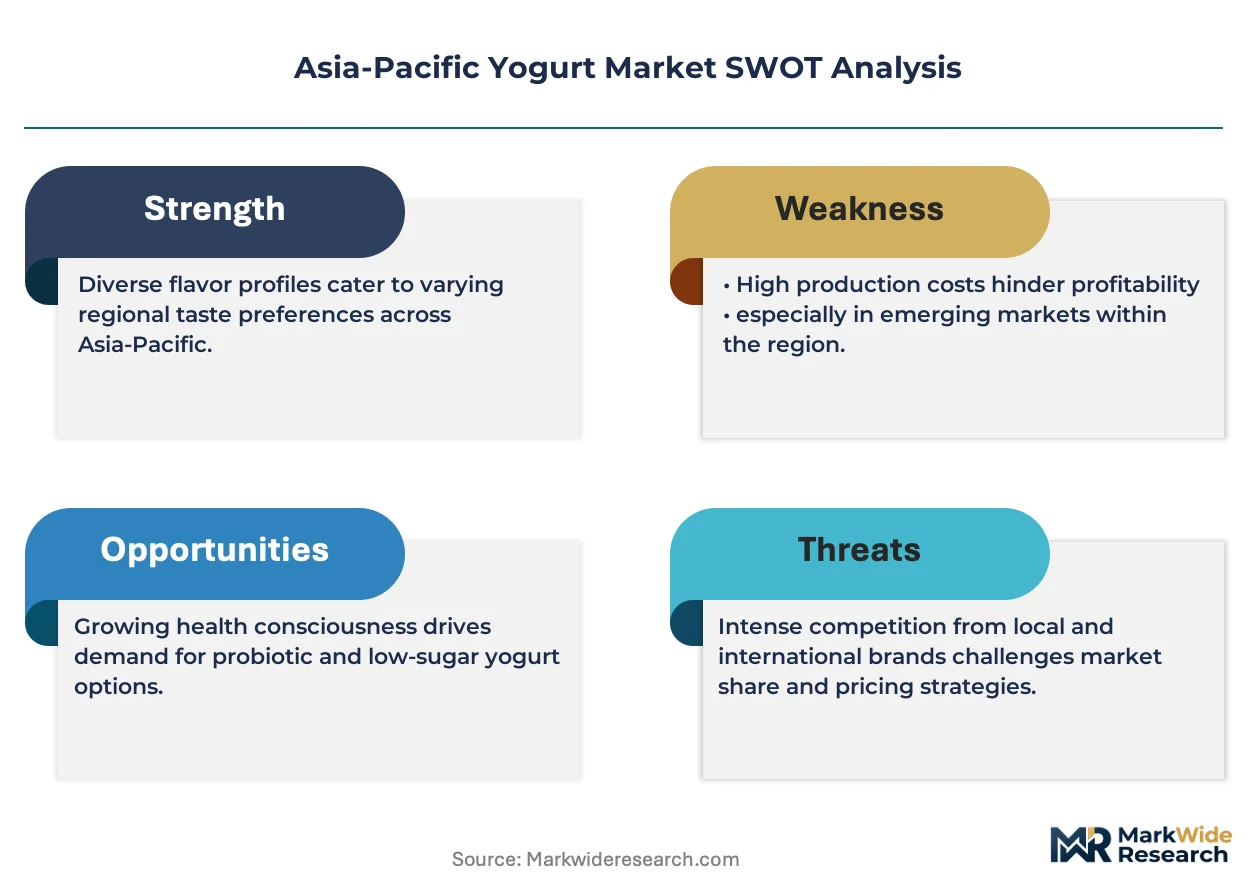
The Asia-Pacific Yogurt Market functions as a regulatory compounder where SAMR's GB 19302 cold-chain mandates are systematically consolidating production capacity around integrated operators with captive dairy networks.
For Market Incumbents: Anchor traceability advantages by deepening captive dairy control in China's northern provinces and securing exclusive aseptic processing licenses from Thai and Australian engineering clusters. Plant-based substitution threats in premium urban segments demand accelerated probiotic strain patenting to defend functional positioning against oat and almond fermented alternatives. For New Entrants and Emerging Players: FSSAI microbiological limits in India open a window for organized sector entrants to capture shelf space from displaced unbranded producers in Mumbai and Delhi family segments. Vietnam and Indonesia's underpenetrated per capita consumption levels offer white-space expansion through local dairy cooperative partnerships. Direct-to-home chilled subscription models bypass incumbent retail markups in Shanghai and Shenzhen. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR compliance costs exceed informal processor margins, creating acquisition opportunities for mid-tier operators with latent cold-chain assets. Long-term viability centers on strain-specific health claim substantiation capabilities under Japan's Food Sanitation Act and China's SAMR frameworks. Watch MFDS functional food approval velocity as inflection signal for premium senior nutrition segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Technology Licensing | Reduces cold-chain capital intensity while maintaining SAMR-compliant viable culture counts for drinking yogurt formats. |
| Captive Dairy Network Expansion | Secures blockchain-traceable raw milk supply under tightening GB 19302 standards in China's northern provinces. |
| Strain-Specific Health Claim Investment | Unlocks MFDS and SAMR approval pathways for sleep, immunity, and metabolic positioning in premium segments. |
| E-Commerce Subscription Channel Development | Bypasses traditional retail markup structures through platform-operated refrigerated logistics in urban Chinese markets. |
| Local Dairy Cooperative Partnership | Enables format localization and cost-competitive sourcing in Vietnam and Indonesia's underpenetrated consumption corridors. |
Study Parameters
Multiple input streams — dairy processor executives, cold-chain logistics operators, retail category buyers, and regulatory affairs specialists — were reconciled against SAMR enforcement documentation, FSSAI microbiological limit circulars, and MFDS functional food approval databases. Secondary validation drew from customs trade records, Nielsen retail audit data, and SEC filings of listed dairy conglomerates. Bottom-up volume modeling and top-down market sizing were cross-referenced for triangulation.
Historical consumption trajectories were cross-referenced against panel input from probiotic strain developers and aseptic packaging engineers. The analytical framework segmented across product format, customer archetype, distribution channel, and flavor profile dimensions throughout the forecast period. CAGRs were derived from elasticity modeling against urbanization rates and regulatory enforcement intensity. Forecast inputs incorporated cold-chain infrastructure investment flows and e-commerce platform refrigerated logistics expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SAMR enforcement acceleration or sustained organic dairy supply contraction. Model outputs reflect documented assumptions on strain stability technology adoption and platform subscription penetration curves. A model refresh is warranted upon material change in GB 19302 implementation timelines or MFDS functional claim approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Milk Powder Market
Dairy Products
Dairy Protein Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
A2 Milk Market
Dairy Products
White Cheese Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Latin America Cheese Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Halal Cheese Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Milk Fat Fractions Market