
 Amino Acids Market | 2026-2036
Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acids Market Intelligence
Application-specific formulation support is recalibrating the value proposition beyond bulk commodity sales. This shift favors suppliers with deep technical expertise. Ajinomoto Co., Inc. leverages its long history in fermentation science to dominate specialized pharma-grade segments. Evonik Industries AG competes on manufacturing scale and process efficiency for animal nutrition products, while Cargill, Incorporated extends its reach through a vast global distribution network for food and feed ingredients.
Amino acids are organic compounds containing both amine and carboxyl functional groups, forming the fundamental building blocks of proteins. Their industrial production relies heavily on fermentation and enzymatic processes to achieve specific molecular structures. The animal feed application, particularly for L-Lysine, constitutes the largest market segment by volume. In contrast, the nutritional supplements and pharmaceutical applications command higher margins, especially for high-purity powder and capsule forms, representing a key area for value-based competition.
Product quality and market access are governed by stringent food and feed safety regulations. The US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) enforce strict purity and labeling standards for food and supplement grades. In China, feed additive approvals from the Ministry of Agriculture and Rural Affairs are critical for market entry. Navigating these disparate regulatory frameworks while managing production costs remains the central strategic challenge for manufacturers.
Market Dynamics
The market is defined by a structural bifurcation between high-volume, cost-sensitive animal feed applications and high-margin, purity-driven pharmaceutical and nutritional segments. Advances in fermentation science are the central force enabling this divergence, allowing for both scaled commodity production and specialized, high-purity compound manufacturing.
Growth Catalysts
- Advanced Fermentation Technology:The use of engineered microbial strains and optimized bioprocesses enables more cost-effective and higher-yield production of key amino acids like L-Lysine and L-Tryptophan, expanding their accessibility for various applications.
- Animal Nutrition Optimization:The global animal feed industry leverages amino acids to formulate precise diets, which improves feed conversion ratios and reduces reliance on volatile protein sources like soybean meal, particularly in large-scale livestock operations.
- Regulatory Pressure on Antibiotics:Policies from bodies like the European Food Safety Authority (EFSA) restricting antibiotic growth promoters in livestock feed create a direct demand pull for amino acids as a primary nutritional alternative to support animal health and growth.
Market Restraints
- Raw Material Price Volatility:Production costs are directly tied to the price of agricultural feedstocks, such as corn-derived glucose or molasses. Fluctuations in these global commodity markets create significant margin pressure and price instability for amino acid manufacturers.
- Geographic Production Concentration:A substantial portion of global production capacity, especially for feed-grade amino acids, is located in China. This exposes the global supply chain to risks associated with the country's domestic policies, trade actions, and potential logistical disruptions.
- Energy-Intensive Purification:The downstream processing steps required to isolate and purify amino acids to high-purity grades are energy-intensive and require significant capital investment, acting as a barrier to entry and adding to operational costs.
Strategic Opportunities
- Plant-Based Protein Fortification:Amino acids are essential for balancing the nutritional profiles of plant-based foods, addressing deficiencies in essential amino acids like lysine or methionine. This represents a significant growth vector tied to the expanding alternative protein market.
- Bioprocess Optimization with AI:The convergence of artificial intelligence and bioprocessing allows for predictive modeling of fermentation cycles. This can optimize yields, reduce batch failures, and accelerate the development of novel production strains for specialized amino acids.
- Aquaculture Feed Development:Expanding aquaculture operations in Southeast Asia and Latin America require specialized feed formulations. Amino acids are critical for creating nutrient-dense aquafeeds that enhance growth rates and disease resistance in farmed fish and shrimp.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers face the challenge of securing and maintaining approvals across disparate regulatory systems, including the US FDA, Europe's EFSA, and China's Ministry of Agriculture and Rural Affairs, each with unique data and documentation requirements.
- Intellectual Property Protection:Safeguarding proprietary microbial strains and novel fermentation process technologies is a constant challenge. The risk of IP infringement is a significant concern, particularly for companies investing in high-value, specialized amino acid production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acids Market |
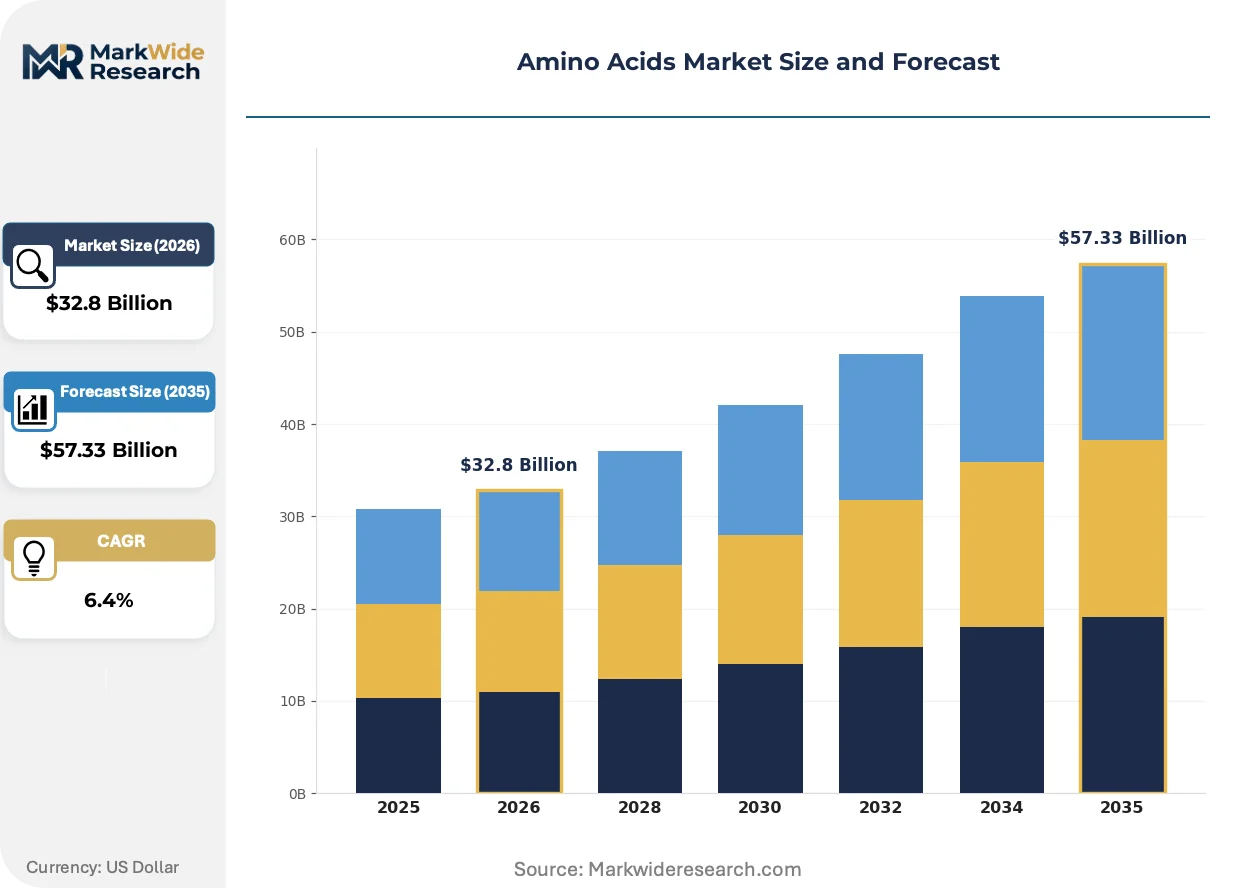
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Alanine, L-Arginine, L-Lysine, Glycine Application: Nutritional Supplements, Animal Feed, Pharmaceutical, Food & Beverage End User: Athletes, Bodybuilders, Veterinarians, Manufacturers Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Kyowa Hakko Bio Co., Ltd., Archer Daniels Midland Company, Cargill, Incorporated, CJ CheilJedang Corporation, Daesang Corporation, AMINO GmbH, Taiwan Amino Acids Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acids Market Strategic Shifts & Innovations
Advancements in bioprocessing are enabling a shift toward precision and sustainability. Fermentation science is moving beyond bulk production to create functionally specific molecules that meet demands for cleaner labels, targeted nutritional outcomes, and reduced environmental impact in end-use applications like animal feed and human nutrition.
Precision fermentation technology allows for the targeted synthesis of specific, high-purity amino acids with minimal byproducts. The nutraceutical and pharmaceutical sectors are rapidly adopting these grades for use in complex dietary supplements and as active pharmaceutical ingredients. This capability is rewriting the economics of producing rare amino acids, moving them from niche laboratory chemicals to commercially viable ingredients for specialized health applications.
The European Union's Green Deal and its Farm to Fork strategy are creating strong incentives for sustainable agricultural inputs. This policy encourages feed producers to use amino acids to lower the crude protein content in animal diets, which directly reduces nitrogen excretion and the associated environmental footprint. The swine and poultry feed segments in Europe are most affected, accelerating the reformulation of diets to align with these sustainability targets.
A shift toward application-specific formulation support is displacing traditional bulk commodity purchasing. End-users in the food and supplement sectors increasingly seek technical co-development partnerships with their suppliers rather than engaging in simple transactional procurement. This trend is most prominent in North America and Europe, where consumer demand for functionally optimized and clean-label food products drives innovation.
Amino Acids Market Segmentation
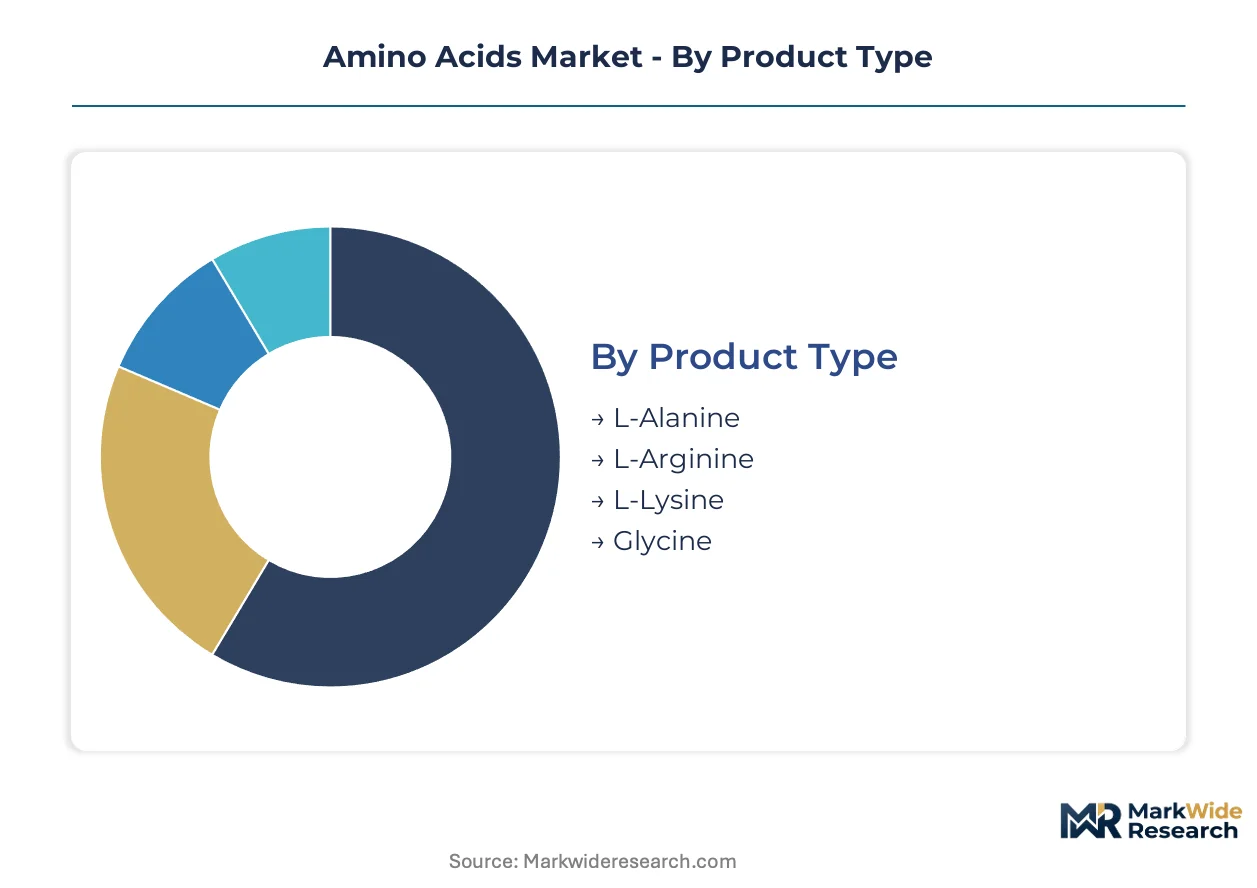
The amino acids market exhibits distinct segmentation across product types, applications, end-users, and forms, reflecting diverse functional requirements. Understanding these segments helps manufacturers tailor product offerings and optimize distribution strategies. Each segment addresses specific needs within the broader nutritional and industrial landscapes.
Product Type:
The amino acids market is differentiated by the specific molecular structure and functional properties of each compound, driving varied industrial applications.
- L-Lysine:This essential amino acid features a linear chain with a basic side group, crucial for protein synthesis and tissue repair. Demand concentrates heavily in China's animal feed sector, improving feed conversion ratios for poultry and swine.
- L-Arginine:As a semi-essential amino acid, L-Arginine plays a role in nitric oxide production, supporting cardiovascular health and immune function. Demand is significant within North American and European nutritional supplements for sports performance and wellness.
- L-Alanine:This non-essential amino acid is involved in sugar and acid metabolism, finding use in food flavorings and some pharmaceutical formulations.
- Glycine:The simplest amino acid, glycine acts as a neurotransmitter and is widely used in pharmaceuticals, food additives, and cosmetic ingredients.
L-Lysine leads on scale due to its pervasive use in animal feed; L-Arginine leads on momentum from expanding health and wellness supplement applications.
Application:
Amino acids are utilized across diverse applications, with each sector demanding specific purity levels and functional characteristics from the compounds.
- Animal Feed:This application segment uses amino acids to optimize livestock nutrition, enhancing growth rates and feed efficiency in poultry, swine, and aquaculture. Large-scale operations in Brazil and the United States drive substantial volume, reducing reliance on protein sources.
- Pharmaceutical:High-purity amino acids serve as active pharmaceutical ingredients, excipients, and building blocks for peptide synthesis in drug manufacturing. Demand in Germany and Switzerland focuses on specialized formulations for therapeutic and clinical nutrition.
- Nutritional Supplements:Amino acids fortify dietary supplements for athletes and general consumers, supporting muscle recovery, energy, and overall health.
- Food & Beverage:These compounds enhance flavor, nutritional value, and shelf-life in various food products, including infant formulas and fortified drinks.
Animal Feed applications account for the largest volume consumption, while Pharmaceutical applications command the highest purity and value.
End User:
End-user categories reflect distinct purchasing behaviors and specific requirements for amino acid formulations and technical support.
- Manufacturers:Industrial-scale producers of animal feed, pharmaceuticals, and food products are major purchasers, requiring bulk quantities and consistent supply chain reliability. This segment, particularly in Southeast Asia, seeks cost-effective solutions for large-volume inputs.
- Veterinarians:These professionals utilize amino acids in animal health formulations and dietary interventions, requiring high-quality, often pharmaceutical-grade, products for therapeutic use. European veterinary clinics drive demand for specialized amino acid blends for animals.
- Athletes:Individuals engaged in sports and fitness consume amino acid supplements to support muscle growth, recovery, and endurance performance.
- Bodybuilders:This niche group prioritizes amino acid intake for muscle protein synthesis, strength gains, and enhanced physical conditioning.
Manufacturers influence the primary market volume, while Veterinarians represent a specialized segment focused on high-value animal health solutions.
Form:
The physical form of amino acids dictates their ease of handling, solubility, and suitability for various end-product formulations.
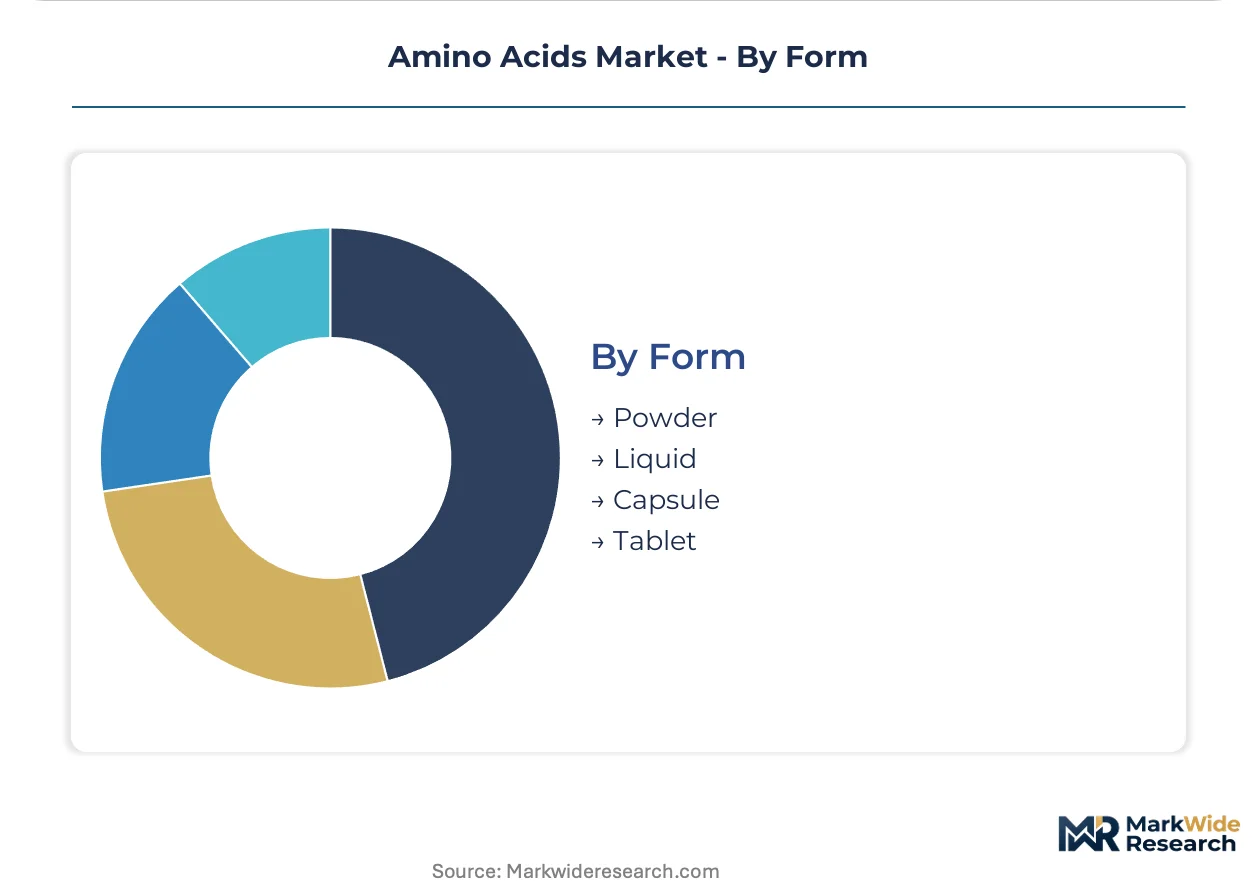
- Powder:This versatile form offers high purity and ease of incorporation into bulk animal feed, food ingredients, and nutritional supplement blends. Its cost-effectiveness and adaptability make it a staple across industrial applications in India.
- Capsule:Capsules provide precise dosing, convenience, and mask unpleasant tastes, making them popular for pharmaceutical and human nutritional supplement applications. North American and Australian consumers favor this form for daily health.
- Liquid:Liquid amino acids offer rapid absorption and are often used in specialized medical nutrition or sports drinks for quick delivery.
- Tablet:Tablets provide a stable, controlled-release dosage form, preferred for certain pharmaceutical applications and multi-ingredient dietary supplements.
Powder forms dominate industrial and bulk markets, while capsules and tablets cater to consumer convenience and precise dosing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global amino acids market sees production gravitating towards regions with favorable regulatory environments and lower operational costs. This dynamic creates a strategic arbitrage opportunity for manufacturers navigating diverse compliance landscapes. Companies often optimize their supply chains by locating high-volume production in specific geographies.
China
China drives substantial amino acid demand, primarily for its vast animal feed and food processing sectors. The Ministry of Agriculture and Rural Affairs enforces strict approvals for feed additives, impacting market entry. Shandong province concentrates significant fermentation capacity, serving as a global production hub for L-Lysine.
United States
United States demand for amino acids concentrates in nutritional supplements and specialized animal feed formulations. The US Food and Drug Administration (FDA) maintains stringent purity and labeling standards for food and supplement grades. The Midwest region leverages abundant corn resources, supporting key manufacturing facilities for fermentable sugars.
Germany
Germany represents a high-value market for pharmaceutical-grade amino acids and specialized ingredients. European Food Safety Authority (EFSA) and EMA guidelines mandate rigorous quality and safety protocols for these compounds. Bavaria's strong pharmaceutical and biotech clusters drive innovation in therapeutic and clinical nutrition formulations.
Brazil
Brazil exhibits robust demand for amino acids, particularly in its expansive animal feed and growing aquaculture sectors. ANVISA oversees regulations for food and feed additives, ensuring product safety and efficacy. São Paulo state benefits from integrated agricultural processing, providing raw materials for amino acid production.
India
India increasingly utilizes amino acids in cost-effective powder forms for industrial applications and pharmaceutical excipients. The Food Safety and Standards Authority of India (FSSAI) sets standards for food ingredients and supplements. Gujarat's chemical and pharmaceutical manufacturing hubs support local production and processing capabilities.
Amino Acids Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the amino acids market structure. The market exhibits a tiered structure, with large integrated players dominating commodity production and niche firms serving high-value segments. Strategic archetypes include global chemical conglomerates, specialized biotech firms, and regional feed ingredient suppliers. Capacity expansion and strategic partnerships remain dominant competitive moves for market participants.
At the scale-driven end, Japan-based Ajinomoto Co., Inc. exemplifies leadership in fermentation science and specialized pharma-grade segments, leveraging decades of expertise. Germany's Evonik Industries AG occupies a position of strength in animal nutrition products, leveraging its manufacturing scale and process efficiency across various regions. Cargill, Incorporated, a US-based entity, anchors its position through a vast global distribution network for food and feed ingredients, representing a broad-based market approach that spans multiple application areas from feed to human nutrition.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Kyowa Hakko Bio Co., Ltd. |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| CJ CheilJedang Corporation |
| Daesang Corporation |
| AMINO GmbH |
| Taiwan Amino Acids Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Animal feed manufacturers, a concentrated buyer archetype, drive demand for commodity-grade amino acids, influencing pricing models towards volume-based contracts. This demand concentration shapes pricing power and incentivizes large-scale production facilities in specific geographies.
Pricing Analysis
Capacity additions in China are reshaping price floors for feed-grade L-Lysine, pushing the market toward commodity spot pricing for bulk volumes. Price differentiation stems from purity levels, with pharmaceutical-grade amino acids commanding significantly higher values based on stringent FDA and EFSA certifications. Raw material price volatility, particularly for corn-derived glucose, exerts downward pressure on margins for all manufacturers. The animal feed industry exhibits the highest price sensitivity, while pharmaceutical buyers prioritize purity and consistent supply over cost.
Supply Chain Analysis
Workforce availability and lower operational costs in China and India have concentrated amino acid manufacturing capacity. The global supply chain draws from agricultural feedstocks like corn-derived glucose and molasses, primarily from the United States and Brazil. Geographic production concentration in China creates a structural supply chain risk, exposing global buyers to potential trade actions or logistical disruptions. Distribution runs through a mix of large global trading houses and specialized direct sales channels, particularly for high-ppurity pharmaceutical ingredients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amino acids market functions as a stable compounder, driven by the continuous global need for optimized animal nutrition and human health applications.
For Market Incumbents: Acquire specialized fermentation technology firms to enhance capabilities in high-purity amino acid production. This move defends against margin pressure from commodity oversupply and insulates against IP infringement risks. Invest in geographic capacity expansion within regions offering stable raw material access, such as the US Midwest, to mitigate supply chain volatility.
For New Entrants and Emerging Players: A significant price-point gap exists between bulk feed-grade and premium pharmaceutical amino acids, creating entry opportunities. Target specialized nutraceutical applications or plant-based protein fortification, which are less volume-driven but command higher margins. A go-to-market angle focused on technical co-development partnerships with food and supplement brands can secure early market share in North America and Europe.
For Investors and Strategic Acquirers: Global chemical conglomerates are the most active acquirers in this space, seeking to expand their ingredient portfolios. The market offers long-term viability due to amino acids' fundamental role in protein synthesis and diverse industrial applications. Acquisition targets should include specialized biotech firms with proprietary fermentation strains or regional manufacturers with strong regulatory compliance records. The signal to watch is the acceleration of policy shifts, like the EU Green Deal, that mandate sustainable agricultural inputs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Increases global supply of feed-grade amino acids to meet animal nutrition demand. |
| Bioprocess Optimization with AI | Enhances yield efficiency and reduces production costs for key amino acids. |
| Specialized Product Development | Captures higher margins in pharmaceutical and nutraceutical applications. |
| Strategic Partnerships with Food Manufacturers | Secures long-term demand for amino acids in plant-based protein fortification. |
| Investment in Regulatory Compliance | Ensures market access and strengthens competitive advantage in diverse regions. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to build a comprehensive market view. This involved engaging with fermentation scientists, feed formulators, pharmaceutical procurement leads, and regulatory experts across key geographies. Secondary data sources included FDA filings, EFSA reports, customs data, and company annual reports, triangulated to validate primary insights.
Historical data cross-referenced with expert panel input formed the basis of the analytical framework, projecting market trends across the analysis window. Segmentation dimensions modeled included product type, application, end-user, form, and regional regulatory clusters. Compound annual growth rates were derived from volume and value projections, with raw material price forecasts and livestock production trends serving as critical forecast inputs.
Caveats apply where geopolitical trade policies, agricultural commodity price shocks, or new bioprocessing breakthroughs could materially shift the outlook. Forecasts reflect assumptions documented through extensive research and industry consultations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
US Potassium Methylate Market