
 Artificial Muscle Fibers Market | 2026-2036
Artificial Muscle Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Muscle Fibers Market Outlook
REACH compliance is hardening material certification requirements for electroactive polymers entering European medical and automotive supply chains. Festo AG sustains applied research leadership through its Bionic Learning Network, while DuPont leverages fluoropolymer expertise to control high-performance dielectric elastomer supply. Ottobock anchors prosthetic applications through specialized distribution in rehabilitation clinics across Germany.
Artificial muscle fibers are electroactive or thermomechanical filaments that convert electrical, thermal, or chemical stimuli into controlled mechanical strain, typically achieving actuation stresses of 1-30 MPa and strains exceeding 10% in dielectric elastomer configurations. These fibers serve industrial and commercial purposes in soft robotics, biomimetic actuation, and adaptive textile systems where conventional servomotors fail on flexibility or weight constraints. Electroactive polymers currently lead product category revenue due to established manufacturing pathways, while hybrid actuation systems represent the fastest-growing technology segment as developers combine thermal responsiveness with electrical precision. Carbon nanotube yarns concentrate margin pools in defense and aerospace procurement channels where specific strength-to-weight ratios command premium positioning.
FDA device classification frameworks and EU MDR conformity assessment procedures govern market access for artificial muscle fibers deployed in implantable or patient-contacting configurations. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements further shape product development timelines for healthcare-oriented suppliers. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions, as fluorinated dielectric materials face prospective phase-down pressure that could force reformulation of high-performance electroactive polymer stacks.
Market Dynamics
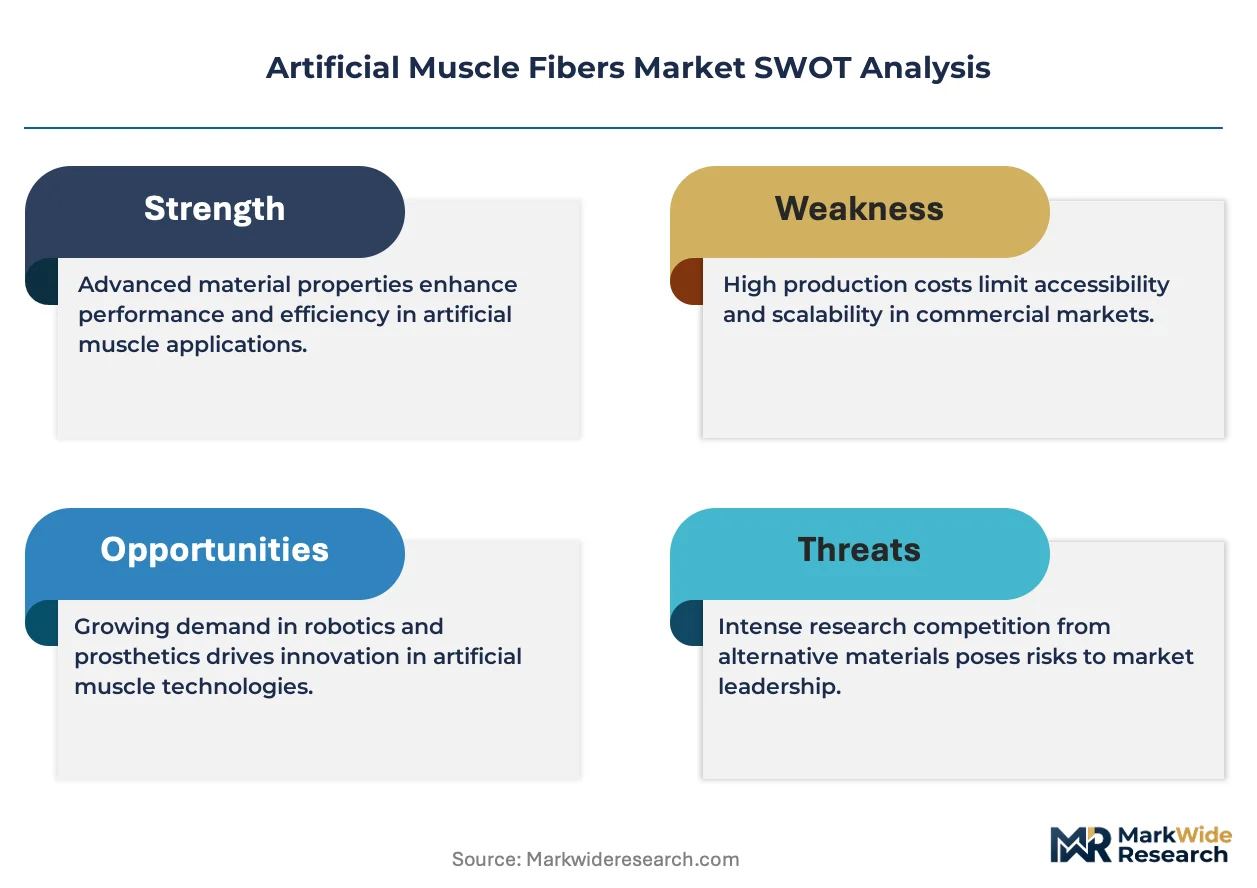
REACH compliance deadlines and evolving FDA guidance on soft robotic medical devices are compressing certification timelines while concentrating procurement among vertically integrated manufacturers with captive testing capabilities.
Growth Catalysts
- EU MDR conformity assessment:Stricter biocompatibility documentation requirements under the Medical Device Regulation are filtering out low-capability suppliers and consolidating procurement among certified fiber manufacturers serving prosthetic OEMs.
- Dielectric elastomer actuation:Advances in silicone-based elastomer processing are enabling higher strain outputs for soft robotics applications in industrial automation and adaptive textiles.
- German rehabilitation clusters:Concentrated applied research around Stuttgart and Berlin is accelerating clinical validation cycles for electroactive polymer fibers in patient-contacting devices.
Market Restraints
- Fluoropolymer feedstock volatility:EPA per- and polyfluoroalkyl substance restrictions threaten supply continuity for high-performance dielectric materials used in aerospace-grade actuators.
- Carbon nanotube supply concentration:Defense and aerospace procurement channels depend on a limited base of specialized yarn producers, creating bottleneck risk for premium fiber segments.
- Actuation stress ceilings:Electroactive polymer configurations currently max out at 30 MPa, constraining load-bearing applications in heavy industrial robotics where hydraulic systems dominate.
Strategic Opportunities
- Hybrid thermal-electrical systems:Convergence of shape-memory alloys with electroactive polymers opens precision control applications in minimally invasive surgical instruments.
- India PLI scheme alignment:Production-linked incentives for advanced materials manufacturing could attract electroactive polymer fiber assembly for domestic medical device supply chains.
- Direct-to-clinic distribution:Rehabilitation centers are bypassing traditional distributor networks to source certified fibers for custom prosthetic fabrication on-site.
Industry Challenges
- ISO 10993 testing backlog:Biocompatibility certification queues at notified bodies are extending product launch timelines by 12-18 months for implantable configurations.
- Electromechanical integration expertise:Shortage of engineers fluent in both polymer physics and control systems is constraining R&D throughput for hybrid actuation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Muscle Fibers Market |
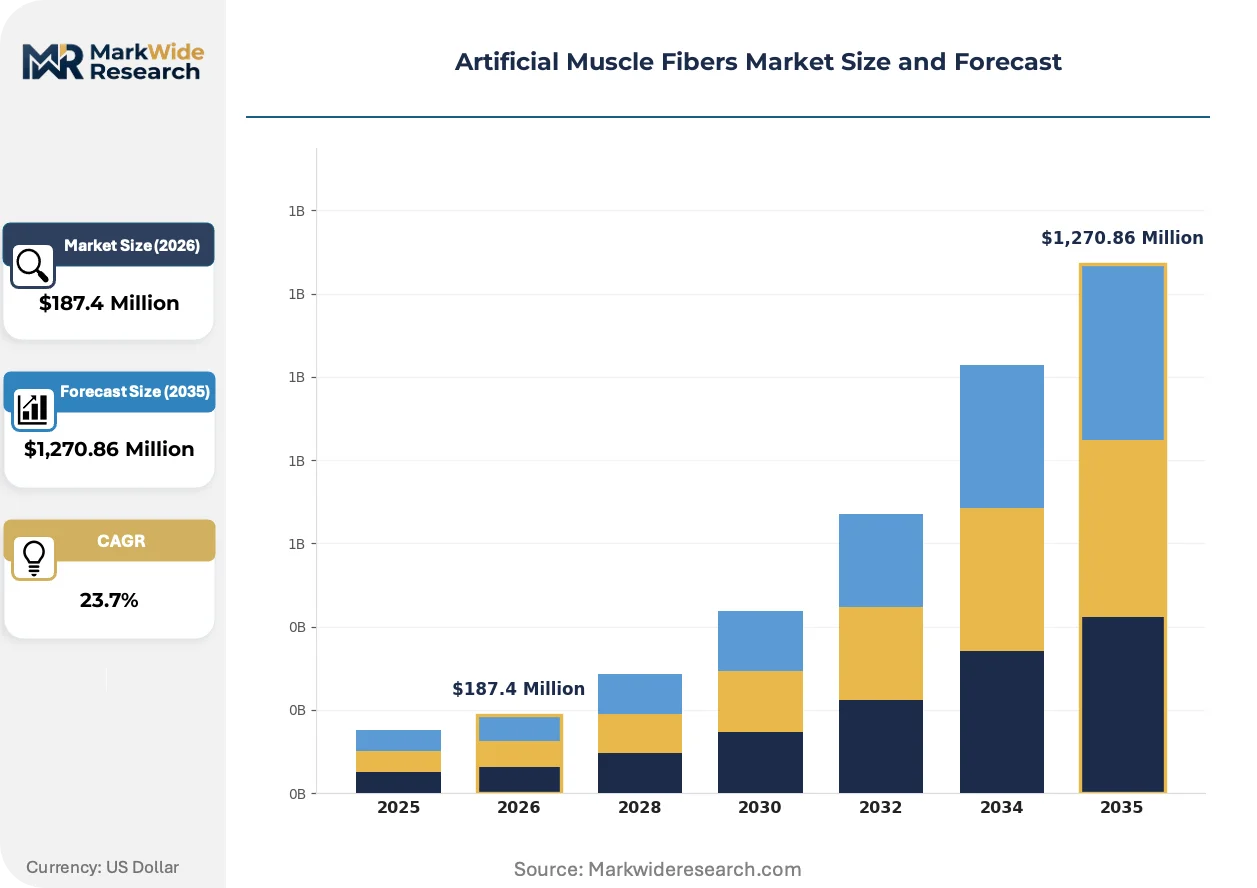
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroactive Polymers, Shape Memory Alloys, Carbon Nanotubes, Conductive Composites Technology: Thermal Actuation, Electrical Actuation, Chemical Actuation, Hybrid Systems Application: Robotics, Healthcare Devices, Wearable Technology, Automotive Systems End User: Manufacturing, Defense, Medical, Entertainment |
| Companies Covered | SRI International, Festo AG & Co. KG, Soft Robotics Inc., Parker Hannifin Corporation, Artificial Muscle Inc., Kuraray Co., Ltd., DuPont, Boston Dynamics, Ottobock SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Muscle Fibers Market Strategic Shifts
Electroactive polymer manufacturing is pivoting from batch synthesis toward continuous fiber drawing processes, compressing unit economics while opening textile-compatible form factors previously unattainable with molded actuator geometries.
Dielectric elastomer fiber bundles are expanding into wearable haptic interfaces, where fashion-tech integrators in South Korea and Japan are sampling woven actuation arrays for force-feedback garments. Sports equipment manufacturers are piloting adaptive compression textiles that modulate stiffness based on muscle activity signals. This expansion is compressing the traditional boundary between industrial robotics components and consumer-facing adaptive materials.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of fluorinated dielectric layers in electroactive polymer stacks used across European automotive and medical supply chains. Compounders with in-house toxicology testing capabilities are capturing specification authority previously held by raw material suppliers. Fiber producers serving implantable device OEMs are front-loading biocompatibility documentation to preempt downstream audit failures.
Certification-driven supplier preference is consolidating procurement among vertically integrated manufacturers with captive ISO 10993 and IEC 60601 testing infrastructure. Rehabilitation clinics and prosthetic workshops are demanding lot-traceable fiber shipments with pre-submitted regulatory dossiers, displacing spot-market purchasing of unqualified materials. This behavioral shift is most pronounced in Germany, where Ottobock's supplier qualification protocols are propagating through affiliated fabrication networks across Bavaria and North Rhine-Westphalia.
Artificial Muscle Fibers Market Segmentation
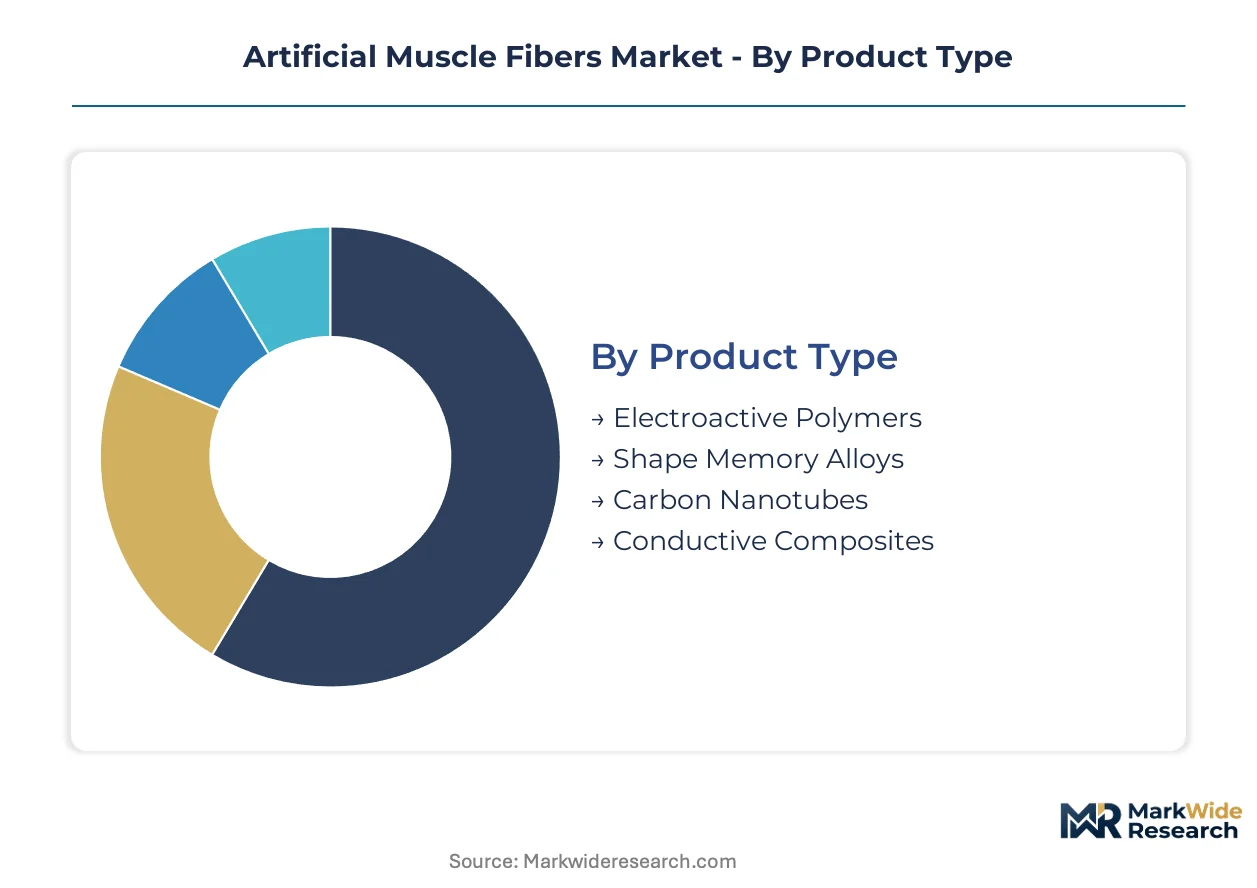
Artificial muscle fiber procurement concentrates around performance specifications that conventional actuation cannot meet. Segmentation reveals where technical differentiation commands specification authority and where commoditization pressure threatens margin pools.
Product Type:
Supply concentration in high-performance dielectric materials favors compounders with captive polymer synthesis capabilities.
- Electroactive Polymers:Dielectric elastomer and ionic polymer-metal composite configurations dominate current procurement volumes, with silicone-based formulations achieving 10-100% strain outputs. Healthcare device manufacturers in Germany source certified EAP fibers through Ottobock's supplier qualification protocols. REACH authorization requirements for persistent organic pollutants are forcing reformulation of fluorinated dielectric layers.
- Shape Memory Alloys:Nickel-titanium filaments deliver thermal actuation with force densities exceeding electroactive alternatives, concentrating demand in aerospace and minimally invasive surgical instruments. Hybrid system developers are integrating SMA cores with polymer sheaths for precision temperature control.
- Carbon Nanotubes:Defense procurement channels depend on specialized yarn producers for specific strength-to-weight ratios.
- Conductive Composites:Polymer matrices loaded with carbon black or metallic fillers serve cost-sensitive textile integration applications.
Today's leader: Electroactive Polymers. Tomorrow's challenger: Shape Memory Alloys.
Technology:
Cost tier separation between precision electrical control and simpler thermal systems is hardening across application categories.
- Electrical Actuation:Dielectric elastomer and piezoelectric configurations enable millisecond response times with closed-loop position feedback. Industrial automation integrators specify electrical actuation for robotic grippers requiring sub-millimeter positioning accuracy.
- Thermal Actuation:Joule heating of shape-memory alloys delivers high force output at lower unit cost, concentrating procurement in automotive adaptive structures and basic prosthetic joints. Response latency limits thermal systems to non-time-critical applications.
- Chemical Actuation:pH-responsive hydrogels and ion-exchange polymers serve niche microfluidic and drug-delivery applications.
- Hybrid Systems:Convergence of thermal responsiveness with electrical precision is expanding fastest in surgical instrument portfolios.
Electrical Actuation commands premium positioning. Hybrid Systems are climbing the fastest.
Application:
Volume concentration in industrial robotics is displacing early-stage consumer wearable procurement.
- Robotics:Soft robotic grippers and continuum manipulators absorb the largest fiber volumes, with collaborative automation deployments requiring compliant actuation that rigid servomotors cannot provide. Festo AG's Bionic Learning Network validates electroactive polymer configurations for industrial pick-and-place operations.
- Healthcare Devices:Prosthetic hands and rehabilitation exoskeletons demand ISO 10993-certified fibers with lot-traceable documentation. German rehabilitation clinics are bypassing distributors to source certified fibers for on-site custom fabrication.
- Wearable Technology:South Korean and Japanese fashion-tech integrators are sampling woven haptic arrays for force-feedback garments.
- Automotive Systems:Adaptive aerodynamic surfaces and active grille shutters specify thermal actuation for weight reduction.
Robotics anchors current procurement. Healthcare Devices are gaining share fastest.
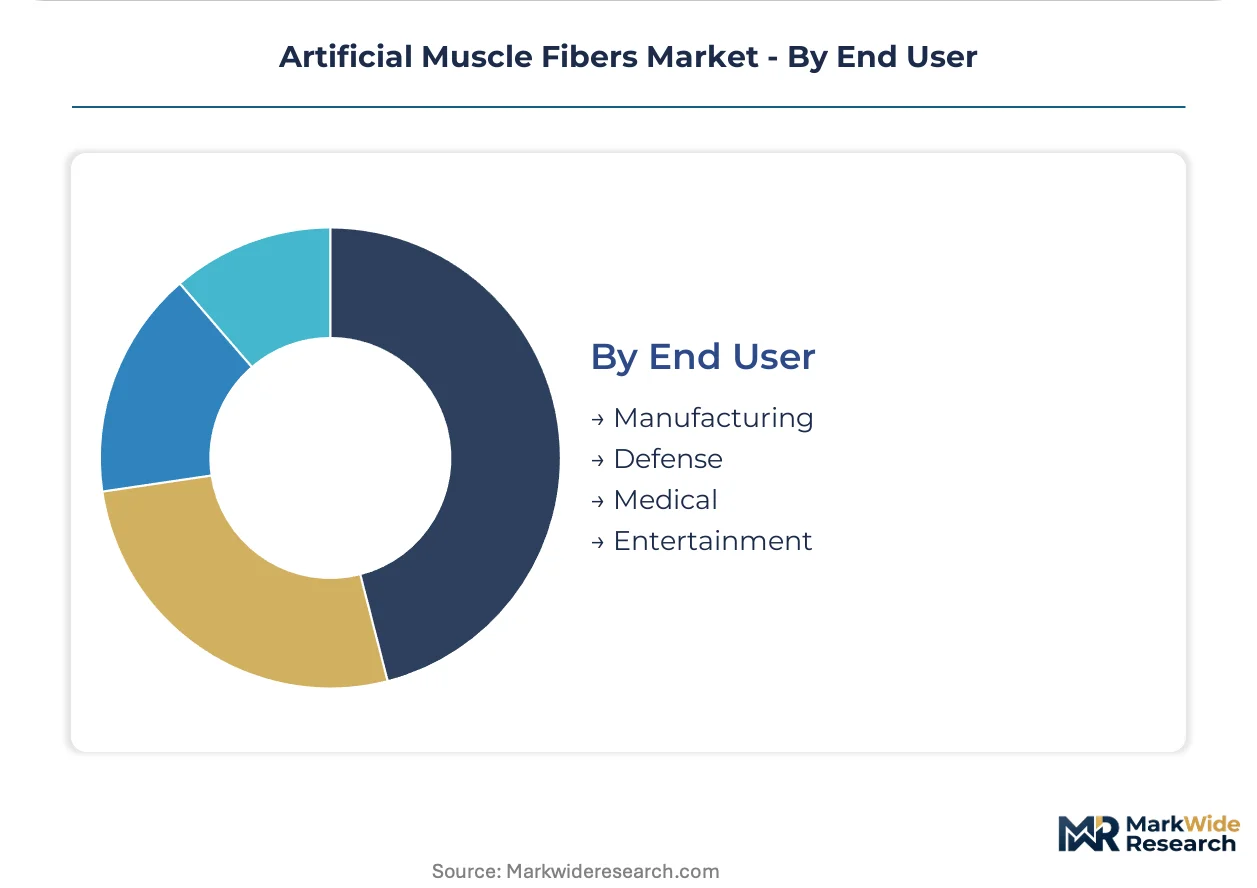
End User:
Customer type determines certification burden and payment timeline, with medical and defense procurement filtering out undercapitalized suppliers.
- Manufacturing:Industrial automation OEMs specify fibers for soft robotic end-effectors and adaptive fixturing systems. Procurement emphasizes cycle life and mean-time-between-failure metrics over biocompatibility documentation.
- Defense:Aerospace-grade carbon nanotube yarns command premium positioning through specialized procurement channels with extended qualification timelines.
- Medical:Implantable and patient-contacting configurations require FDA device classification or EU MDR conformity assessment. ISO 10993 testing backlogs at notified bodies extend product launch timelines.
- Entertainment:Theme park animatronics and motion-capture suits represent emerging demand with less stringent certification requirements.
Medical procurement concentrates margin. Defense channels represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and mechatronics engineers cluster in Germany's Stuttgart-Berlin corridor, anchoring applied research for electroactive fiber systems. Rehabilitation medicine specialists in North American and Asian markets drive clinical validation demand. Regulatory divergence between REACH-compliant European supply chains and FDA-governed US medical device pathways fragments procurement standards.
United States
Defense procurement channels absorb aerospace-grade carbon nanotube yarns through specialized qualification programs. FDA device classification frameworks govern soft robotic medical devices entering patient-contacting configurations. Boston anchors robotics R&D clusters where electroactive polymer configurations undergo industrial automation validation.
Germany
Ottobock SE & Co. KGaA's supplier qualification protocols propagate through rehabilitation fabrication networks across Bavaria and North Rhine-Westphalia. REACH authorization requirements for persistent organic pollutants force reformulation of fluorinated dielectric layers in automotive and medical supply chains. Festo AG & Co. KG's Bionic Learning Network in Stuttgart accelerates clinical validation cycles for prosthetic applications.
Japan
Fashion-tech integrators in Tokyo and Osaka sample woven haptic arrays for force-feedback garments. METI standards shape electroactive polymer certification for wearable technology exports. Kansai region compounders with in-house toxicology testing capture specification authority previously held by raw material suppliers.
South Korea
Adaptive textile manufacturers in Seoul Capital Area pilot compression garments modulating stiffness based on muscle activity signals. MFDS biocompatibility documentation requirements filter supplier qualification for medical device integration. Busan-Ulsan industrial corridors concentrate dielectric elastomer processing for export-oriented robotics OEMs.
China
Industrial automation OEMs in Yangtze River Delta specify fibers for soft robotic end-effectors requiring compliant actuation. GB standards and MIIT regulations govern electroactive polymer stack formulations for domestic medical device supply chains. Pearl River Delta compounders pivot from batch synthesis toward continuous fiber drawing processes.
Artificial Muscle Fibers Market Competitive Environment
The competitive structure tilts toward vertically integrated manufacturers with captive testing capabilities. Certification-driven supplier preference consolidates procurement among compounders controlling polymer synthesis, fiber drawing, and ISO 10993 documentation under single roofs. Three archetypes dominate: German rehabilitation-focused system integrators, Japanese materials-science conglomerates, and US defense-aerospace specialists. Capacity expansion in continuous fiber drawing and backward integration into fluoropolymer feedstock represent the dominant competitive moves.
Among Germany-based fabricators, Festo AG & Co. KG and Ottobock SE & Co. KGaA exemplify the vertically integrated rehabilitation archetype, anchoring applied research clusters with captive clinical validation infrastructure. DuPont occupies a position representing materials-science conglomerates leveraging fluoropolymer expertise for high-performance dielectric elastomer supply. These three names illustrate how geographic concentration around Stuttgart and Berlin reinforces specification authority through proximity to end-use validation cycles.
| Leading Market Players |
|---|
| SRI International |
| Festo AG & Co. KG |
| Soft Robotics Inc. |
| Parker Hannifin Corporation |
| Artificial Muscle Inc. |
| Kuraray Co., Ltd. |
| DuPont |
| Boston Dynamics |
| Ottobock SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Rehabilitation clinic procurement of lot-traceable fiber shipments with pre-submitted regulatory dossiers is forcing compounders to absorb ISO 10993 testing costs upfront, compressing margins for uncertified suppliers while concentrating pricing power among vertically integrated manufacturers with captive toxicology infrastructure.
Pricing Analysis
Bundled certification-and-material contracts dominate premium tiers, while unbundled spot-market fiber sales persist in industrial automation procurement. Three-tier pricing structure across medical-grade certified, industrial-performance, and basic textile-integration levels separates Ottobock-qualified suppliers from general robotics compounders. Pricing pressure stems from REACH-driven fluoropolymer reformulation costs passing through to dielectric elastomer stacks. Medical device OEMs exhibit lowest price sensitivity due to reimbursement-protected procurement budgets, while textile integrators in South Korea and Japan face acute cost compression.
Supply Chain Analysis
Specialized polymer chemist availability in Germany's Stuttgart-Berlin corridor and mechatronics engineer concentration in Boston and Tokyo anchor manufacturing gravity for precision electroactive fiber drawing. Fluoropolymer feedstock draws from DuPont's fluorochemical operations, carbon nanotube yarn rests on limited defense-aerospace specialized producers, and silicone elastomer compounds feed from Pearl River Delta compounders. Single-source vulnerability concentrates in aerospace-grade carbon nanotube supply. Distribution runs through direct-to-clinic channels displacing traditional distributor networks in German rehabilitation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR conformity assessment deadlines and evolving FDA guidance on soft robotic medical devices are consolidating procurement among certified suppliers. The regulatory milestone of ISO 10993 biocompatibility certification is driving demand concentration that rewards pre-qualified manufacturers.
For Market Incumbents: Anchor specification authority by deepening backward integration into fluoropolymer feedstock and expanding captive ISO 10993 testing capacity to preempt notified body backlogs. Defend against emerging South Korean fashion-tech integrators by locking rehabilitation clinic networks through direct-to-clinic distribution partnerships that bypass distributor margins. For New Entrants and Emerging Players: Entertainment animatronics manufacturers represent an underserved buyer archetype with less stringent certification requirements and faster procurement cycles than medical or defense channels. Target theme park operators and motion-capture studios in North America with conductive composite fiber bundles priced below dielectric elastomer alternatives, leveraging speed-to-contract as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap compounders possessing in-house toxicology testing capabilities and established relationships with German rehabilitation fabrication networks. Long-term viability hinges on regulatory certification moats rather than raw material cost advantages. Watch for inflection signals in India PLI scheme implementation attracting electroactive polymer fiber assembly for domestic medical device supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstock | DuPont's fluorochemical expertise secures dielectric elastomer supply continuity against EPA restrictions. |
| Captive ISO 10993 Testing Infrastructure | Ottobock's supplier qualification protocols propagate through Bavarian rehabilitation fabrication networks. |
| Continuous Fiber Drawing Process Transition | Pearl River Delta compounders compress unit economics while opening textile-compatible form factors. |
| Direct-to-Clinic Distribution Channel | German rehabilitation centers bypass traditional networks for certified fiber sourcing on-site. |
| Hybrid Thermal-Electrical System Development | Convergence of SMA cores with polymer sheaths opens minimally invasive surgical instrument applications. |
Study Parameters
Multiple input streams — primary interviews with rehabilitation clinicians, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR notified body databases, and customs trade records; and proprietary fiber shipment tracking — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across electroactive polymer, shape memory alloy, carbon nanotube, and conductive composite product categories, segmented by electrical, thermal, chemical, and hybrid actuation technologies, generated volume and value outputs across the projection horizon. CAGRs were derived from fitted growth curves incorporating prosthetic OEM procurement cycles, industrial automation adoption rates, and wearable technology pilot conversion timelines.
Inputs from notified body certification queues and EPA regulatory dockets were available through the study window; gaps in defense-aerospace carbon nanotube yarn production capacity introduce uncertainty bands around premium segment forecasts. Material deviation in fluoropolymer feedstock restrictions or ISO 10993 testing backlog resolution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Metal Fiber Felt Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Global Bicomponent Fiber Market
Fibers
Carbon Fiber Wrap Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global Concrete Fiber Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Viscose Staple Fiber Market
Fibers
Carbon Fiber Tapes Market
Fibers
High Temperature Superconducting Fibers Market