
 Fumaric Acid Market | 2026-2036
Fumaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Fumaric Acid Market Intelligence
A shift from single-source to multi-source procurement for food-grade fumaric acid is broadening supply chain resilience for food manufacturers. This transition affects major suppliers like Polynt S.p.A., which leverages its large-scale production capacity to serve diverse industrial applications including unsaturated polyester resins. Bartek Ingredients Inc. differentiates through high-purity grades for the food and beverage industry. Changmao Biochemical Engineering Co., Ltd. competes by offering a portfolio spanning both food and technical grades.
Fumaric acid is a dicarboxylic organic compound with the chemical formula C4H4O4, existing as a white crystalline solid produced via maleic anhydride isomerization or fermentation. It primarily functions as a food acidulant, a pH regulator, and a key monomer in the production of polymers. The food and beverage application constitutes a mature, high-volume segment due to its use as a non-hygroscopic acidulant in powdered mixes. Demand from the unsaturated polyester resins application is expanding rapidly, driven by construction and automotive component manufacturing.
Regulatory frameworks like the U.S. FDA's Generally Recognized as Safe (GRAS) status and the European Food Safety Authority's (EFSA) E297 designation govern its use in food products. In China, the NMPA oversees its application in pharmaceutical excipients, creating distinct compliance pathways for producers. Stakeholder success will depend on securing certifications for emerging bio-based production methods to meet corporate sustainability mandates from customers.
Market Dynamics
The transition toward bio-based production methods from renewable feedstocks is the central force shaping the fumaric acid market. This shift addresses corporate sustainability mandates from customers and creates new compliance pathways for producers seeking green certifications.
Growth Catalysts
- GRAS and E297 Status:The U.S. FDA's Generally Recognized as Safe (GRAS) status and EFSA's E297 designation secure its role as a preferred, non-hygroscopic acidulant in powdered food and beverage mixes.
- Unsaturated Polyester Resin Demand:Expanding construction and automotive manufacturing in China accelerates consumption of fumaric acid as a key monomer for unsaturated polyester resins.
- Bio-fermentation Advances:Progress in fermentation using renewable feedstocks lowers production's carbon footprint, attracting industrial and food-grade buyers with corporate sustainability mandates.
Market Restraints
- Maleic Anhydride Price Volatility:The conventional route's dependence on maleic anhydride exposes producers to crude oil price fluctuations, impacting cost stability and margins.
- Citric Acid Substitution:In liquid beverages, citric acid's higher solubility presents a substitution threat, limiting fumaric acid's use despite its cost-effectiveness as an acidulant.
- Low Water Solubility:Its characteristically low solubility in water restricts its application in clear liquid beverages, confining its primary use to powdered mixes and select industrial processes.
Strategic Opportunities
- Animal Feed Additive:Its function as a non-antibiotic growth promoter in swine and poultry feed is an emerging application, driven by regulations restricting antibiotic use.
- Southeast Asian Markets:Rising processed food consumption and industrialization in Vietnam and Indonesia offer new growth frontiers for both food-grade and technical-grade suppliers.
- Bio-based Polymers:Developing biopolymers that co-polymerize bio-based fumaric acid with bio-succinic acid opens pathways into the sustainable plastics market, displacing petrochemicals.
Industry Challenges
- Bio-based Production Validation:Securing certifications for novel bio-based production routes is a lengthy process, requiring validation to meet standards set by bodies like the USDA or for EU Ecolabel.
- Capital Investment for Scale-up:Scaling bio-fermentation facilities to compete with established petrochemical production requires significant capital expenditure, creating a high barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fumaric Acid Market |
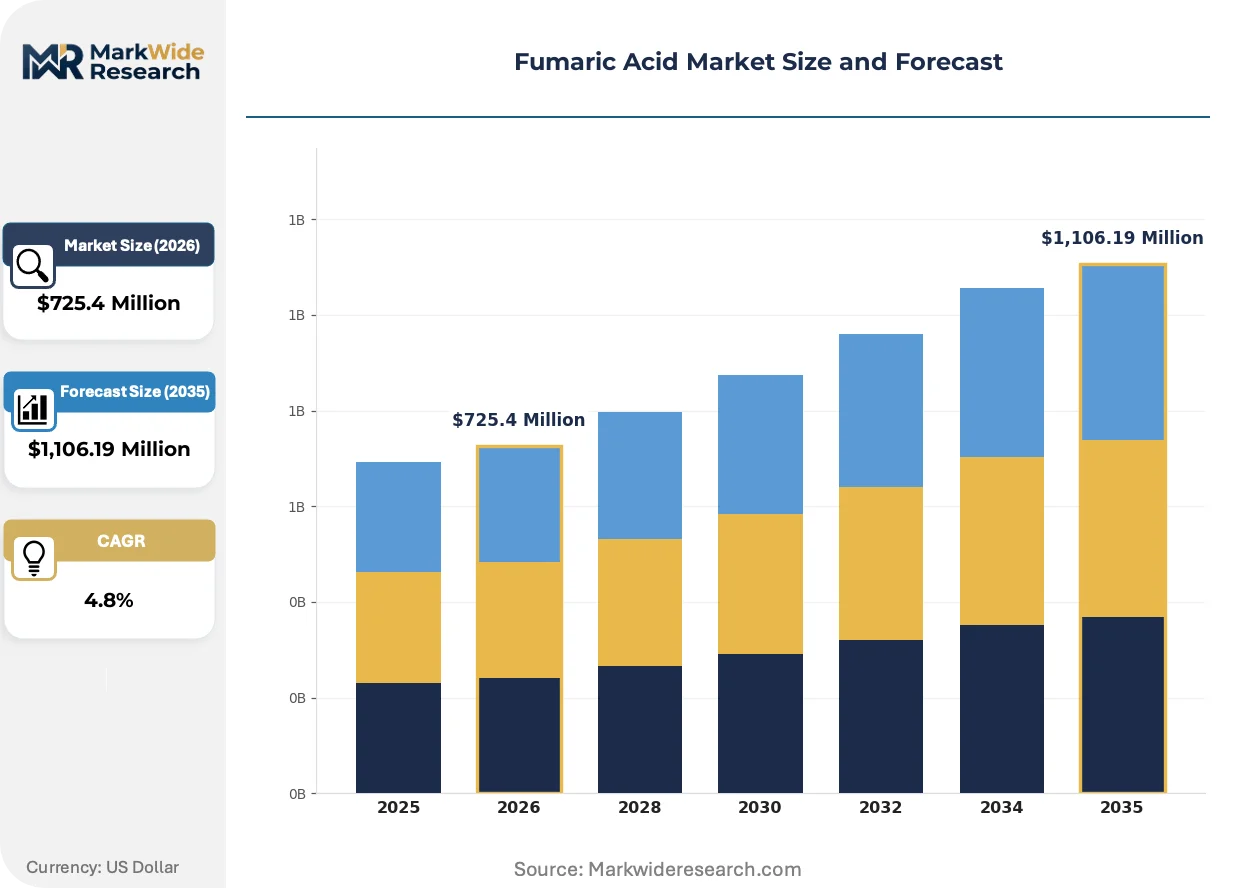
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,106.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Food & Beverage, Pharmaceuticals, Unsaturated Polyester Resins, Agriculture End User: Food Manufacturers, Pharmaceutical Companies, Chemical Producers, Agriculture Sector Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Fuso Chemical Co., Ltd., Changmao Biochemical Engineering Co., Ltd., Thirumalai Chemicals, Bartek Ingredients Inc., Polynt S.p.A., Merck KGaA, ESIM Chemicals GmbH, Nippon Shokubai Co., Ltd., Anhui Taida New Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fumaric Acid Market Strategic Shifts & Innovations
The fumaric acid market is evolving under the dual pressures of advancing bio-manufacturing technologies and stricter regulatory oversight on chemical inputs. These forces are compelling a re-evaluation of production economics and supply chain strategies across all application segments.
Continuous fermentation technology, using immobilized cell bioreactors, offers a more efficient method for producing bio-based fumaric acid. Food and beverage manufacturers are beginning to specify this production method to meet their corporate sustainability goals. This technology is integrating upstream bio-feedstock processing with downstream purification, creating a streamlined and cost-competitive production pathway compared to traditional batch fermentation.
China's "dual carbon" goals are creating regulatory incentives for chemical producers to shift away from energy-intensive processes like maleic anhydride isomerization. This policy directly favors the development and adoption of lower-carbon bio-fermentation routes for producing bulk chemicals, including fumaric acid. The unsaturated polyester resin industry, a major consumer in China, is most affected, facing pressure to source more sustainable monomers.
A notable shift is occurring where large food manufacturers now mandate supply chain transparency and proof of sustainable sourcing for ingredients like fumaric acid. This moves purchasing decisions beyond price, disrupting the traditional commodity-based procurement model and favoring suppliers with certified bio-based offerings. This trend is most pronounced in Europe and North America, where consumer-facing brands actively market their use of sustainable ingredients.
Fumaric Acid Market Segmentation
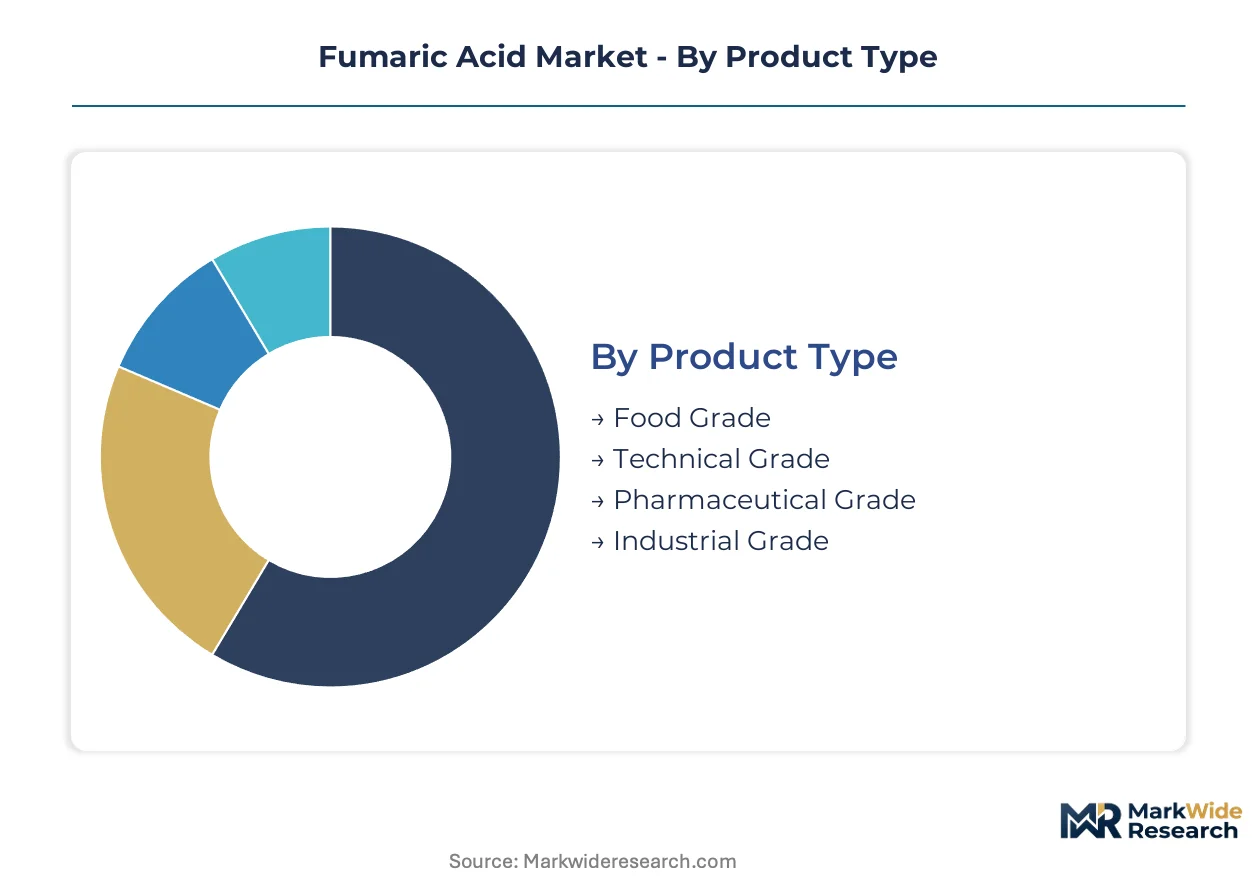
The fumaric acid market is segmented across critical dimensions reflecting its diverse industrial and food applications, each with distinct production requirements and supply chain dynamics. Understanding these segmentations reveals the varying capital intensity, regulatory hurdles, and customer specifications that shape competitive strategies. This granular view assists stakeholders in identifying high-growth niches and optimizing their operational investments.
Product Type:
Capital investment varies significantly across fumaric acid product types, with pharmaceutical grades requiring the most stringent purification and quality control infrastructure. This segment demands specialized facilities and rigorous validation processes to meet global pharmacopeia standards. Conversely, technical and industrial grades often permit more cost-effective, larger-scale production methods.
- Food Grade:This product type meets strict purity standards for human consumption, often designated as GRAS by the U.S. FDA and E297 by EFSA. Demand concentrates in the powdered food and beverage mixes sector, where its non-hygroscopic nature provides a distinct advantage over other acidulants.
- Technical Grade:Technical grade fumaric acid is produced for industrial applications where high purity is less critical but consistent chemical properties are essential. Its primary consumption occurs in the manufacturing of unsaturated polyester resins, with substantial volumes consumed by China's construction and automotive industries.
- Pharmaceutical Grade:This highly purified fumaric acid adheres to pharmacopeial specifications, serving as an excipient in drug formulations. Its application is regulated by bodies like the NMPA in China and the U.S. FDA, requiring extensive documentation and quality assurance for producers.
- Industrial Grade:Industrial grade fumaric acid finds use in various non-food and non-pharmaceutical processes, including paper sizing and animal feed.
Most installed capacity flows through Technical Grade products. Expansion is steepest in Food Grade applications.
Application:
The application segments for fumaric acid demonstrate varying demand elasticity and regulatory burdens, influencing pricing and market entry barriers. Applications in pharmaceuticals face the highest regulatory scrutiny, driving up production costs and limiting the number of qualified suppliers. Conversely, agriculture and industrial uses often prioritize cost-effectiveness and bulk supply.
- Food & Beverage:Fumaric acid functions as an acidulant and pH regulator in this mature, high-volume segment, particularly in powdered drinks, desserts, and confectionery. Its non-hygroscopic property makes it a preferred choice for dry mix formulations, ensuring product stability and shelf life.
- Unsaturated Polyester Resins:This application leverages fumaric acid as a key monomer, imparting rigidity and heat resistance to polymers used in composites. Construction materials and automotive components manufacturing, particularly in China, are significant drivers for this segment.
- Pharmaceuticals:Fumaric acid serves as an excipient, tablet disintegrant, or acidulant in various pharmaceutical formulations. Its use is strictly governed by national drug regulatory bodies, such as the U.S. FDA and China's NMPA, demanding high-purity and consistent quality.
- Agriculture:In agriculture, fumaric acid is increasingly used as a non-antibiotic growth promoter in animal feed, driven by global regulations restricting antibiotic use in livestock.
The Food & Beverage application accounts for the largest volume. The Unsaturated Polyester Resins segment is expanding most quickly.
End User:
The end-user landscape for fumaric acid is characterized by diverse procurement strategies, ranging from large-scale bulk purchasing by chemical producers to specialized sourcing by pharmaceutical companies. Food manufacturers are increasingly adopting multi-source procurement to enhance supply chain resilience, moving beyond single-supplier dependencies. Pharmaceutical companies prioritize long-term supply agreements with certified vendors.
- Food Manufacturers:These entities utilize fumaric acid primarily as an acidulant in a wide array of processed foods and beverages. Their purchasing decisions are influenced by ingredient cost, regulatory compliance, and the supplier's ability to meet corporate sustainability mandates.
- Chemical Producers:Chemical producers consume fumaric acid as a monomer for the synthesis of unsaturated polyester resins and other polymers. Their demand is directly tied to the performance of the construction and automotive sectors, especially in industrial hubs like China.
- Pharmaceutical Companies:These companies incorporate pharmaceutical-grade fumaric acid into their drug formulations, requiring suppliers to meet stringent quality, purity, and regulatory standards. Compliance with NMPA or U.S. FDA guidelines is paramount for these buyers.
- Agriculture Sector:The agriculture sector uses fumaric acid as a feed additive to promote growth and improve feed efficiency in livestock.
Food Manufacturers represent the largest purchasing volume. The Agriculture Sector is showing the greatest acceleration in demand.
Distribution Channel:
The distribution channels for fumaric acid reflect the product's varied end-user requirements and regional market structures. Direct sales often cater to large industrial buyers needing consistent bulk supply, while distributors serve smaller enterprises or provide specialized logistics for geographically dispersed customers. Online retail is emerging for niche applications or smaller volume purchases, particularly in regions with developed e-commerce infrastructure.
- Direct Sales:This channel involves direct transactions between fumaric acid producers and large-volume industrial end-users, such as major chemical producers or food manufacturers. It facilitates customized supply agreements and technical support.
- Distributors:Distributors play a crucial role in reaching smaller and medium-sized enterprises, managing inventory, and providing regional logistics. They serve as intermediaries, consolidating orders and offering diverse product portfolios.
- Wholesale:The wholesale channel involves bulk sales to other businesses, which then re-sell the product to various end-users. This channel is common for technical and industrial grades of fumaric acid.
- Online Retail:Online platforms are increasingly used for procuring smaller quantities of fumaric acid, particularly for research purposes or specialized applications.
Direct Sales channel the majority of fumaric acid volume. The Online Retail channel is demonstrating the most significant growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fumaric acid market experiences production shifts influenced by varying regulatory compliance costs and environmental policies across regions. Producers often seek locations offering more favorable operational frameworks or robust demand for specific applications. This dynamic creates opportunities for countries aligning with sustainable manufacturing practices and expanding end-use sectors.
China
Demand for fumaric acid in China primarily comes from its expansive unsaturated polyester resin manufacturing and construction sectors. The nation's "dual carbon" goals encourage a shift towards bio-fermentation routes for chemical production. Industrial hubs like the Yangtze River Delta are seeing investment in sustainable monomer sourcing for automotive components.
United States
Food-grade fumaric acid consumption remains strong in the United States, particularly for powdered mixes and beverages. The U.S. FDA's GRAS status ensures its continued use in a wide range of food products. Bio-based production facilities are emerging in states with strong agricultural feedstock supplies, attracting food manufacturers.
Germany
Germany's chemical industry drives demand for fumaric acid in polymer synthesis and specialty applications. EU Ecolabel certifications and REACH regulations influence sourcing decisions for sustainable chemical inputs. The Rhine-Ruhr region observes a growing preference for bio-based monomers to meet corporate sustainability mandates.
India
India's processed food market and developing pharmaceutical sector are boosting fumaric acid consumption. The FSSAI regulates food additives, while CDSCO oversees pharmaceutical excipients, creating distinct compliance pathways. Maharashtra's industrial zones are expanding production capacity to cater to rising domestic demand.
Vietnam
Rising processed food consumption and industrialization in Vietnam offer new growth frontiers for technical and food-grade fumaric acid. The country's food safety regulations are evolving to align with international standards for ingredient purity. Ho Chi Minh City's food processing industry is adopting fumaric acid in new product formulations.
Fumaric Acid Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue bio-based production methods and specialized high-purity grades for niche markets. The fumaric acid market exhibits a tiered structure, with distinct players serving commodity industrial applications versus specialized pharmaceutical and food segments. Strategic archetypes include large-scale chemical manufacturers focused on bulk supply, specialized food ingredient suppliers emphasizing purity, and innovative bio-fermentation developers targeting sustainability mandates. Capacity expansion and portfolio diversification represent dominant competitive moves among market participants seeking to capture new growth areas.
Within the specialized food ingredient tier, Bartek Ingredients Inc. differentiates through high-purity grades specifically tailored for the demanding food and beverage industry. Polynt S.p.A. occupies a position as a large-scale chemical manufacturer, leveraging extensive production capacity to serve diverse industrial applications including unsaturated polyester resins and other polymer formulations. Changmao Biochemical Engineering Co., Ltd. exemplifies a producer offering a comprehensive portfolio spanning both food and technical grades, effectively balancing commodity and specialty market demands across its operations.
| Leading Market Players |
|---|
| Fuso Chemical Co., Ltd. |
| Changmao Biochemical Engineering Co., Ltd. |
| Thirumalai Chemicals |
| Bartek Ingredients Inc. |
| Polynt S.p.A. |
| Merck KGaA |
| ESIM Chemicals GmbH |
| Nippon Shokubai Co., Ltd. |
| Anhui Taida New Material Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Corporate sustainability mandates from food manufacturers are compelling fumaric acid suppliers to invest in bio-based production, influencing cost structures and market pricing. This shift prioritizes certified green offerings over traditional commodity procurement.
Pricing Analysis
Maleic anhydride price volatility directly impacts fumaric acid production costs, leading to fluctuating commodity spot pricing. Long-term contract-based offtake agreements mitigate some of this risk for large buyers. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade and specific certifications like GRAS or NMPA approval. Significant capital investment for bio-based facilities creates upward pricing pressure, while technical grade buyers remain highly price-sensitive, balancing against pharmaceutical and high-purity food-grade segments that prioritize quality over cost.
Supply Chain Analysis
Securing certifications for bio-based production routes acts as a critical gating factor for fumaric acid suppliers to access sustainability-driven markets. Supply concentration is notable in China for technical grades, while the United States and Germany are expanding bio-based production capabilities. The industry draws from maleic anhydride for conventional output and renewable feedstocks for emerging bio-fermentation methods. Single-source vulnerability to maleic anhydride price fluctuations presents a structural risk. Distribution runs through direct sales for large chemical producers and distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fumaric acid market presents a geographic-arbitrage opportunity, driven by China's "dual carbon" goals accelerating the shift to lower-carbon bio-fermentation routes. This regulatory differential creates distinct cost structures and market access advantages across regions.
For Market Incumbents: To counter the threat of maleic anhydride price volatility, incumbents must diversify feedstock sourcing and invest in bio-fermentation R&D. Capacity expansion in bio-based production facilities, especially in regions with strong agricultural feedstock supplies, strengthens supply chain resilience. Targeting certifications like USDA Organic or EU Ecolabel provides a competitive lever against emerging bio-based entrants.
For New Entrants and Emerging Players: Online retail platforms offer a direct channel to penetrate niche segments for specialized high-purity fumaric acid. Targeting the rapidly accelerating agriculture sector with non-antibiotic growth promoters in Southeast Asian markets presents a white-space opportunity. Focusing on bio-based polymers, co-polymerizing bio-based fumaric acid with bio-succinic acid, provides a sustainable go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists possessing validated bio-based production routes. The long-term viability of fumaric acid hinges on its continued integration into sustainable plastics and animal feed applications over the next decade. Acquisition targets should prioritize firms with advanced fermentation technology and established green certifications. A signal to watch is the increasing number of corporate sustainability mandates requiring certified bio-based ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Shifting to bio-fermentation reduces carbon footprint, meeting corporate sustainability goals of food and beverage manufacturers. |
| Capacity Expansion | Scaling bio-fermentation facilities addresses growing demand from the unsaturated polyester resin industry in China. |
| Long-term Supply Agreement | Securing renewable feedstock supplies mitigates maleic anhydride price volatility for producers. |
| Portfolio Diversification | Expanding into animal feed additives leverages new regulations restricting antibiotic use in livestock. |
| Strategic Partnership | Collaborating with bio-succinic acid producers opens pathways into the sustainable plastics market. |
Research Approach
Coverage spans China, the United States, and Germany, with primary inputs from plant managers, procurement leads at food manufacturers, and R&D directors in polymer synthesis. This primary research is validated against secondary data, including customs/trade data, chemical industry reports, and regulatory filings from the FDA and EFSA. A rigorous bottom-up and top-down triangulation approach ensures data accuracy. This methodology synthesizes insights from diverse industry participants.
The rate-of-change decomposition framework projects market evolution across the analysis window by segmenting key growth drivers and restraints. The model incorporates grade tier, end-use industry, regional production hub, and application as core dimensions. Compound annual growth rates are derived from historical trends and projected future demand shifts. Industry-specific forecast inputs include projected construction and automotive manufacturing growth in China and bio-fermentation scale-up timelines.
The model assumes a particular technology adoption path; alternative pathways for bio-fermentation scale-up would alter the outlook. Forecasts reflect current regulatory incentives and raw material availability. A model refresh is warranted upon material change in global energy policy or trade dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Citrate Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Paraben Market