
 Urea Formaldehyde Market | 2026-2036
Urea Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Urea Formaldehyde Market Intelligence
China is reconfiguring regional supply dynamics through expanded urea formaldehyde resin capacity serving domestic particleboard and MDF producers. Hexion leverages backward integration into methanol and formaldehyde feedstocks to secure margin control across North American adhesive markets. BASF SE anchors European supply through specialized resin formulations meeting stringent indoor air quality protocols. Georgia-Pacific Chemicals dominates southern United States manufacturing corridors with integrated forest-products-to-resin operations.
Urea formaldehyde denotes a thermosetting amino resin synthesized from urea and formaldehyde condensation, typically cured under acidic conditions at temperatures between 100°C and 140°C to form irreversible methylene and methylene-ether crosslinks. The resin functions primarily as a cost-effective binder in wood composite panels, offering high tensile strength, rapid cure rates, and water solubility prior to polymerization. Adhesives command the largest volume share within product type segmentation due to irreplaceable bonding performance in particleboard and plywood lamination. Construction applications are outpacing furniture demand in absolute growth terms as engineered wood products penetrate mid-rise residential framing across temperate climate zones. Resin formulations with reduced free formaldehyde content capture expanding margin pools as certified low-emission grades achieve specification lock-in from European and North American building codes.
EPA Toxic Substances Control Act provisions and California Air Resources Board ATCM Phase 2 standards enforce formaldehyde emission caps on composite wood products sold in United States markets. REACH registration requirements and ECHA classification of formaldehyde as a Category 1B carcinogen impose reformulation obligations on European resin manufacturers. China's MEE ambient air quality standards and GB standards for indoor decorating materials create parallel compliance pathways across major production geographies. Stakeholders must monitor divergence between regional emission thresholds and certify supply chains against the most restrictive jurisdiction in their export footprint.
Market Dynamics
China's tightening MEE emissions standards are compressing formulation margins while simultaneously redirecting procurement toward low-emission resin variants, forcing manufacturers to absorb reformulation costs or surrender market access.
Growth Catalysts
- Engineered lumber penetration:Wood panel manufacturers in Vietnam and Indonesia are expanding particleboard capacity for export markets, pulling formaldehyde-based resin volumes upward.
- India PLI scheme:Furniture manufacturing clusters under the Production Linked Incentive program are consolidating demand for cost-competitive binding resins.
- Low-emission certification:California Air Resources Board ATCM Phase 2 standards are creating specification lock-in for certified resin grades across North American building material supply chains.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings in the United States and Middle East are transmitting directly into formaldehyde production economics.
- Substitution by phenol-formaldehyde:Exterior-grade plywood manufacturers are migrating toward phenolic resins where moisture resistance requirements exceed urea-formaldehyde performance thresholds.
- REACH registration burden:ECHA classification of formaldehyde as Category 1B carcinogen is imposing compliance costs that squeeze mid-tier European resin producers.
Strategic Opportunities
- Cross-laminated timber expansion:Mid-rise residential framing in Germany and Austria is opening specification pathways for specialized low-emission adhesive formulations.
- Digital procurement platforms:B2B chemical marketplaces are disintermediating traditional distributor networks for standard-grade resin volumes in Southeast Asia.
- EU Green Deal alignment:Renovation wave mandates for energy-efficient building retrofits are amplifying demand for engineered insulation panels bound with formaldehyde resins.
Industry Challenges
- Emissions testing protocol fragmentation:Divergent chamber test methods between EPA, CARB, and Chinese GB standards are forcing manufacturers to maintain multiple certification inventories.
- Specialized formulation chemist scarcity:Expertise in acid-catalyzed condensation chemistry and cure-rate optimization is concentrating among aging technical workforces in Western Europe and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urea Formaldehyde Market |
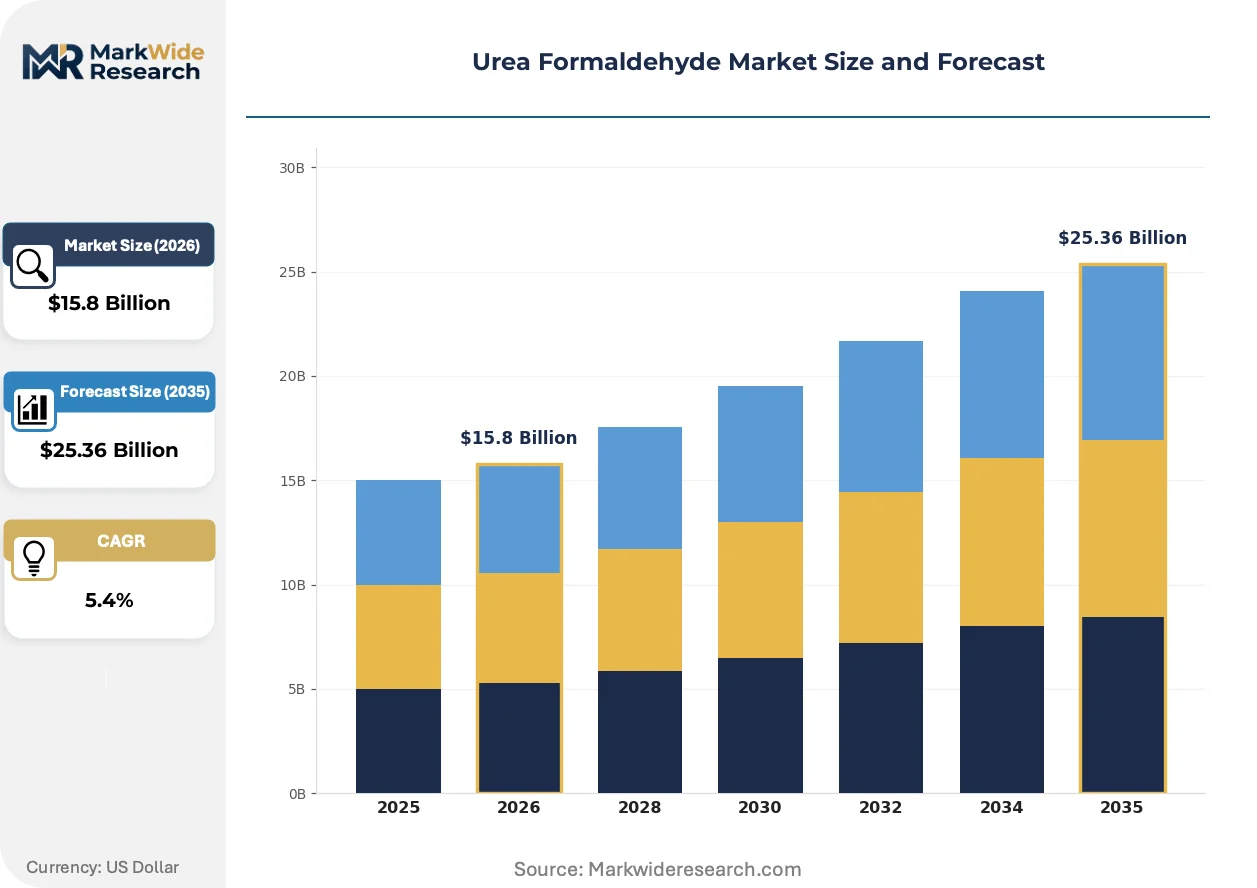
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Adhesives, Coatings, Laminates Application: Furniture, Construction, Automotive, Textiles End User: Manufacturers, Distributors, Retailers, Contractors Distribution Channel: Online, Offline, B2B, B2C |
| Companies Covered | Metadynea, Ashland, Hexion, ARCL Organics Ltd., Kronoplus Limited, BASF SE, Hexza Corporation Berhad, SABIC, Georgia-Pacific Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urea Formaldehyde Market Strategic Shifts & Innovations
Formulation science is converging with air quality regulation to compress the viable product portfolio toward ultra-low emission grades, while digital tools are restructuring how resin specifications reach downstream buyers.
Melamine-urea-formaldehyde copolymer technology is hybridizing with traditional UF chemistry to deliver intermediate emission performance at cost points below pure MUF systems. Furniture-grade plywood manufacturers in Poland and Turkey are adopting these hybrid binders to bridge the gap between commodity UF and premium phenolic resins. The hybridization is compressing the addressable market for standard-grade urea formaldehyde in interior applications where moisture exposure remains moderate.
REACH registration requirements and ECHA hazard classification updates are forcing systematic reformulation across European resin production. Manufacturers serving the German and French construction sectors are retiring legacy high-emission product lines ahead of regulatory deadlines. The specialized resin segment is absorbing the compliance burden through dedicated low-emission product families priced at formulation premiums.
Buyer concentration among large-scale particleboard producers is compressing procurement cycles and demanding integrated technical service relationships. Former distributor-dependent purchasing in Eastern Europe and Brazil is consolidating toward direct manufacturer contracts with volume commitments and embedded formulation support. The shift is most visible in Brazil's Central-West region where industrial wood processing clusters are negotiating multi-year resin supply agreements.
Urea Formaldehyde Market Segmentation
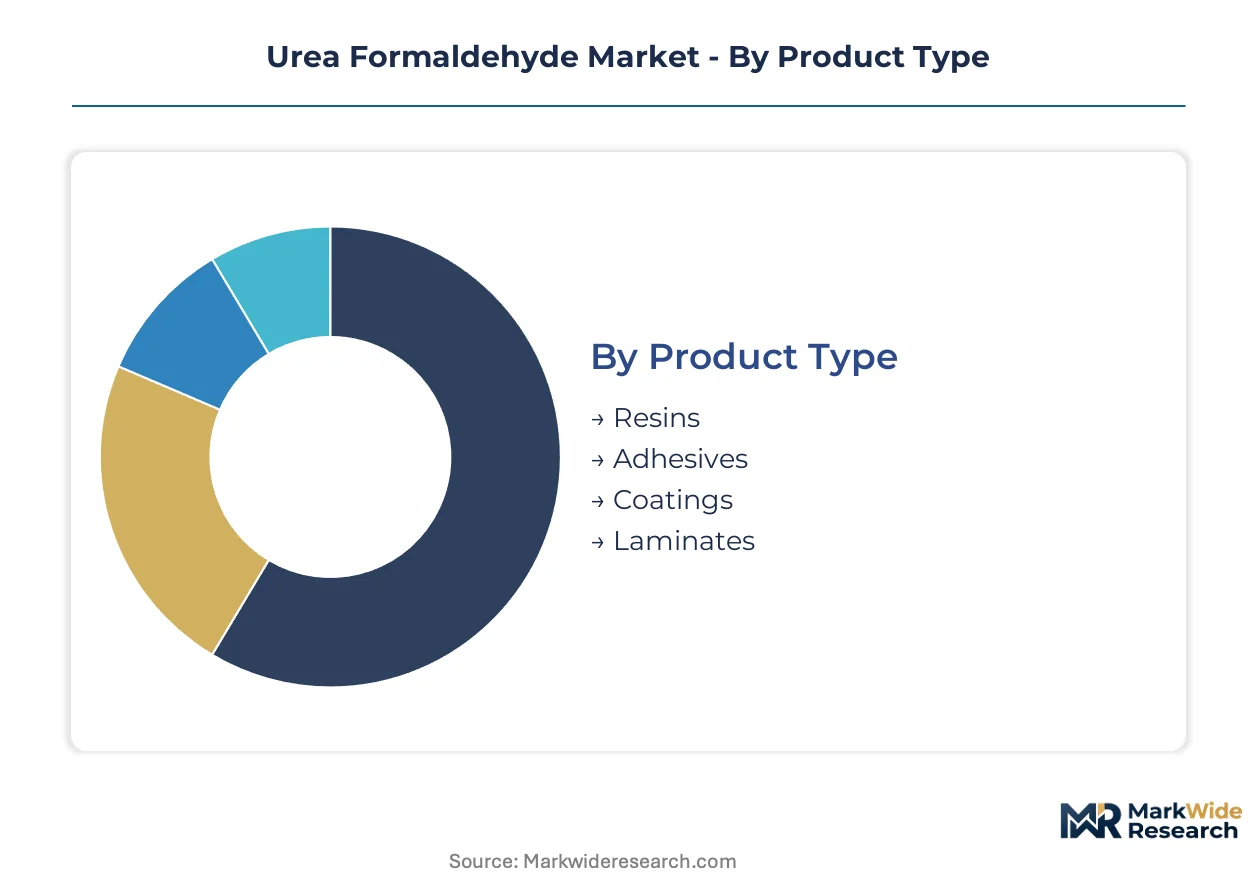
Segmentation in the urea formaldehyde market reveals how formulation chemistry, application requirements, and procurement patterns create distinct commercial battlegrounds. Each dimension exposes different margin structures and technical service intensities that manufacturers must navigate.
Product Type:
After-sales service intensity varies sharply across product categories, with resins demanding embedded technical support for cure-rate optimization while coatings require color-matching and application training.
- Resins:Thermosetting amino polymers synthesized through urea-formaldehyde condensation, cured under acidic conditions between 100°C and 140°C to form irreversible methylene crosslinks. Demand concentrates among Chinese and Vietnamese particleboard producers expanding engineered lumber capacity for export markets, with procurement teams requiring on-site formulation adjustment support during production line commissioning.
- Adhesives:Water-soluble binding systems delivering high tensile strength and rapid cure rates prior to polymerization. European furniture manufacturers in Poland and Turkey are driving specification shifts toward hybrid melamine-urea-formaldehyde systems that bridge emission performance between commodity grades and premium phenolic alternatives.
- Coatings:Surface finishing layers providing hardness and chemical resistance for decorative applications. Industrial wood processors in Brazil's Central-West region negotiate multi-year supply agreements bundling coating systems with technical service contracts.
- Laminates:Decorative surface materials bonded to substrates using formaldehyde-based resins. Indian PLI scheme beneficiaries in furniture manufacturing clusters source laminates through consolidated procurement channels with embedded quality certification.
Resins hold the largest share; momentum sits with adhesives as hybrid formulations gain specification traction.
Application:
Cost tier differentiation separates commodity interior applications from premium exterior-grade specifications, with performance requirements dictating formulation chemistry and pricing power.
- Furniture:Interior wood component binding for case goods, cabinetry, and upholstered frames. German and Austrian cross-laminated timber producers are opening specification pathways for specialized low-emission adhesive formulations in mid-rise residential applications.
- Construction:Structural engineered wood products including particleboard, MDF, and plywood for framing and sheathing. China's tightening MEE emissions standards are compressing margins while redirecting procurement toward certified low-emission resin variants for building material compliance.
- Automotive:Interior trim components, headliners, and acoustic insulation bound with formaldehyde resins. Manufacturers serving this segment face REACH registration burdens from ECHA carcinogen classification that squeeze mid-tier European producers.
- Textiles:Fabric finishing agents providing crease resistance and dimensional stability. This application commands formulation premiums due to specialized cure chemistry and textile mill technical requirements.
Construction applications hold the largest share; furniture represents the fastest-growing trajectory as PLI scheme clusters consolidate demand.
End User:
Customer type determines contract structure, with large-scale manufacturers demanding integrated technical relationships while distributors carry inventory risk for smaller accounts.
- Manufacturers:Integrated wood processors operating captive particleboard, MDF, or plywood production lines. Hexion leverages backward integration into methanol and formaldehyde feedstocks to secure margin control across North American adhesive markets serving this customer class.
- Distributors:Intermediary networks stocking standard-grade resins for smaller wood processors. B2B chemical marketplaces are disintermediating traditional distributor networks for commodity volumes in Southeast Asia.
- Retailers:Point-of-sale channels serving hobbyist and small contractor segments. Procurement cycles here remain fragmented with limited technical service requirements.
- Contractors:Installation and finishing professionals requiring just-in-time adhesive delivery. This segment shows emerging digital procurement adoption for project-based resin purchasing.
Manufacturers hold the largest share; momentum sits with distributors as digital platforms restructure channel economics.
Distribution Channel:
Supply concentration dictates channel strategy, with B2B direct relationships dominating volume flows while online platforms capture standard-grade spot purchasing.
- Online:Digital procurement platforms enabling price discovery and specification comparison for commodity resin grades. Southeast Asian wood panel manufacturers are piloting marketplace purchasing for non-critical adhesive volumes.
- Offline:Traditional field sales relationships with embedded technical service for complex formulation requirements. European low-emission certification demands sustain offline channel importance for compliance documentation.
- B2B:Direct manufacturer-to-processor contracts with volume commitments and formulation support. Brazil's industrial wood processing clusters exemplify this channel's consolidation trend.
- B2C:Retail packaging for small-volume professional and consumer applications. This channel captures minimal share in industrial urea formaldehyde markets.
B2B channels hold the largest share; online platforms are expanding most quickly as procurement digitization penetrates Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emissions standards in China are compressing formulation margins while redirecting procurement toward certified low-emission variants. Wood panel manufacturers across four major economies face divergent regulatory pressures that reshape competitive positioning.
China
Particleboard and MDF producers in Shandong and Guangdong provinces are expanding engineered lumber capacity for domestic construction. MEE ambient air quality standards enforce formaldehyde emission caps that force reformulation toward low-emission resin grades. The Yangtze River Delta wood processing cluster is absorbing compliance costs through integrated technical service relationships with resin suppliers.
United States
Engineered wood products are penetrating mid-rise residential framing across temperate climate zones, pulling adhesive volumes upward. EPA Toxic Substances Control Act provisions and California Air Resources Board ATCM Phase 2 standards create specification lock-in for certified resin grades. Southern manufacturing corridors in Georgia and Louisiana sustain integrated forest-products-to-resin operations.
Germany
Cross-laminated timber expansion in mid-rise residential applications is opening specification pathways for specialized low-emission adhesive formulations. REACH registration requirements and ECHA classification of formaldehyde as Category 1B carcinogen impose systematic reformulation obligations. Bavarian and Baden-Württemberg construction material producers are retiring legacy high-emission product lines ahead of regulatory deadlines.
India
Furniture manufacturing clusters under the PLI scheme are consolidating demand for cost-competitive binding resins. BIS standards for indoor decorating materials create parallel compliance pathways alongside international certification requirements. Gujarat and Maharashtra industrial zones are negotiating multi-year resin supply agreements with embedded technical support.
Brazil
Industrial wood processing clusters in the Central-West region are expanding particleboard capacity for export markets. ANVISA regulations and international buyer certification requirements drive procurement toward low-emission variants. São Paulo and Paraná manufacturers are piloting digital procurement platforms for standard-grade resin volumes.
Urea Formaldehyde Market Key Industry Players
Vertically integrated chemical conglomerates and specialized resin formulators split the market into distinct capability tiers. Consolidation pressures concentrate volume share among feedstock-integrated players while mid-tier specialists defend position through formulation chemistry expertise. Three archetypes dominate: methanol-backward-integrated multinationals, regional formulation specialists, and forest-products-integrated producers. Capacity expansion in Asia-Pacific and strategic partnerships for low-emission certification dominate competitive moves.
Among feedstock-integrated players, Hexion and BASF SE exemplify the multinational archetype with upstream control over methanol and formaldehyde supply chains. Georgia-Pacific Chemicals anchors the forest-products-integrated segment through captive resin operations serving southern United States manufacturing corridors. These three occupy positions that concentrate technical resources and certification capabilities, leaving mid-tier European and Asian specialists to compete on formulation agility and regional service intensity.
| Leading Market Players |
|---|
| Metadynea |
| Ashland |
| Hexion |
| ARCL Organics Ltd. |
| Kronoplus Limited |
| BASF SE |
| Hexza Corporation Berhad |
| SABIC |
| Georgia-Pacific Chemicals |
| Others |
Cost & Logistics Intelligence
Overcapacity signals from Shandong and Guangdong resin plants are compressing spot pricing power while simultaneously forcing suppliers to absorb reformulation costs for MEE-compliant low-emission grades, tightening margins across both standard and certified product tiers.
Pricing Analysis
Price spreads between Chinese export-grade resins and European low-emission certified formulations reflect certification premiums and logistics differentials. Three-tier pricing structure across premium low-emission, standard industrial, and economy spot grades dominates procurement contracts. Price differentiation centers on CARB Phase 2 and MEE certification levels versus commodity specifications. Cost compression in standard-grade segments is intensifying because Vietnamese and Indonesian particleboard producers are consolidating volumes through multi-year direct agreements.
Supply Chain Analysis
Export-control regimes on formaldehyde production technology from German and Japanese equipment suppliers limit capacity expansion capabilities in emerging production zones. Supply concentrates in China, Germany, and the United States as integrated producers with captive methanol-to-resin operations. Feedstock dependencies on natural gas-priced methanol and urea ammonia sources create margin volatility. Single-source vulnerability sits with specialized acid-catalyzed condensation catalyst suppliers concentrated in Western Europe. Distribution runs through direct B2B manufacturer contracts for volume accounts, with digital platforms capturing spot procurement in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for cure-rate optimization and formulation support are expanding faster than base resin volumes as particleboard producers demand embedded commissioning assistance.
For Market Incumbents: Build certification moats around CARB Phase 2 and MEE-compliant product families to lock out mid-tier competitors facing REACH registration burdens. Deepen backward integration into methanol feedstocks to secure margin control against natural gas price volatility. Consolidate technical service teams in Vietnam and Indonesia to capture particleboard expansion demand. For New Entrants and Emerging Players: Build out digital procurement platforms targeting Southeast Asian spot markets where traditional distributor networks remain fragmented. White-space exists in hybrid melamine-urea-formaldehyde formulations for Polish and Turkish furniture plywood manufacturers seeking intermediate emission performance. Go-to-market through embedded formulation partnerships with PLI scheme clusters in Gujarat and Maharashtra. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across specialty low-emission resin segments as formulation chemistry expertise concentrates among aging technical workforces. Long-term viability favors acquiring regional specialists with captive certification capabilities and established technical service relationships. Watch for divergence between EPA, CARB, and Chinese GB emission testing protocols as inflection indicator forcing duplicate certification inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstocks | Hexion and BASF SE anchor margin control through captive formaldehyde supply. |
| Low-Emission Certification Investment | MEE and CARB Phase 2 compliance creates specification lock-in for premium grades. |
| Digital Procurement Platform Launch | B2B marketplaces disintermediate distributor networks in Southeast Asian spot markets. |
| Technical Service Team Expansion | On-site cure-rate optimization supports particleboard line commissioning in Vietnam. |
| Hybrid MUF Formulation Development | Melamine-urea-formaldehyde bridges commodity UF and phenolic resin performance tiers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with resin plant managers, particleboard procurement leads, furniture manufacturing technical directors, and distribution channel partners. Secondary validation drew from customs trade data, ACC and Cefic industry reports, EPA and ECHA regulatory filings, and SEC 10-K disclosures from feedstock-integrated producers. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and regional production hubs.
Calibration anchored forward projections to historical capacity utilization patterns and regulatory implementation timelines without year-specific assumptions. Segmentation dimensions spanned product chemistry grades, end-use applications across construction and furniture, customer type contract structures, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves incorporating engineered lumber penetration rates and emission standard enforcement intensity.
Stress conditions across methanol feedstock price bands, MEE enforcement strictness, and phenolic resin substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory harmonization and capacity expansion timelines. Material shifts in Chinese dual carbon policy implementation or REACH hazard classification updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Paraben Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Serine Market