
 Isophthaloyl Chloride Market | 2026-2036
Isophthaloyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Isophthaloyl Chloride Market Analytics
The gap between pharmaceutical-grade and industrial-grade isophthaloyl chloride is rebalancing as purity specifications tighten for high-performance polyamide applications. DuPont leverages its polymer science heritage to anchor premium positioning in specialty resin formulations. Shandong Kaisheng New Materials sustains cost competitiveness through backward integration into thionyl chloride supply. Tokyo Chemical Industry Co., Ltd. differentiates via analytical-grade distribution channels serving laboratory and pharmaceutical research segments.
Isophthaloyl chloride, a diacid chloride derived from isophthalic acid with molecular formula C8H4Cl2O2, functions as a critical monomer in condensation polymerization to produce heat-resistant aromatic polyamides and high-barrier polyester resins. Manufacturers typically synthesize the compound via thionyl chloride-mediated chlorination of isophthalic acid under controlled temperature and pressure conditions. Polyester resins command the dominant volume share due to entrenched demand from packaging film laminators seeking oxygen barrier performance. Polyamides represent the fastest-expanding category as automotive engineers substitute metal components with heat-resistant polymer alternatives in under-hood applications. Coatings applications concentrate margin pools where fluoropolymer hybrid systems command technical premiums from chemical processing equipment OEMs.
China's MEE enforces wastewater discharge limits that elevate capital requirements for thionyl chloride handling facilities, while REACH compliance in Europe mandates registration and toxicity documentation for import volumes exceeding one tonne annually. The EPA oversees domestic US production under TSCA Section 5 premanufacture notification rules for new chemical entities. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect demand toward isophthaloyl chloride-based barrier coatings as fluorinated alternatives face regulatory pressure.
Market Dynamics
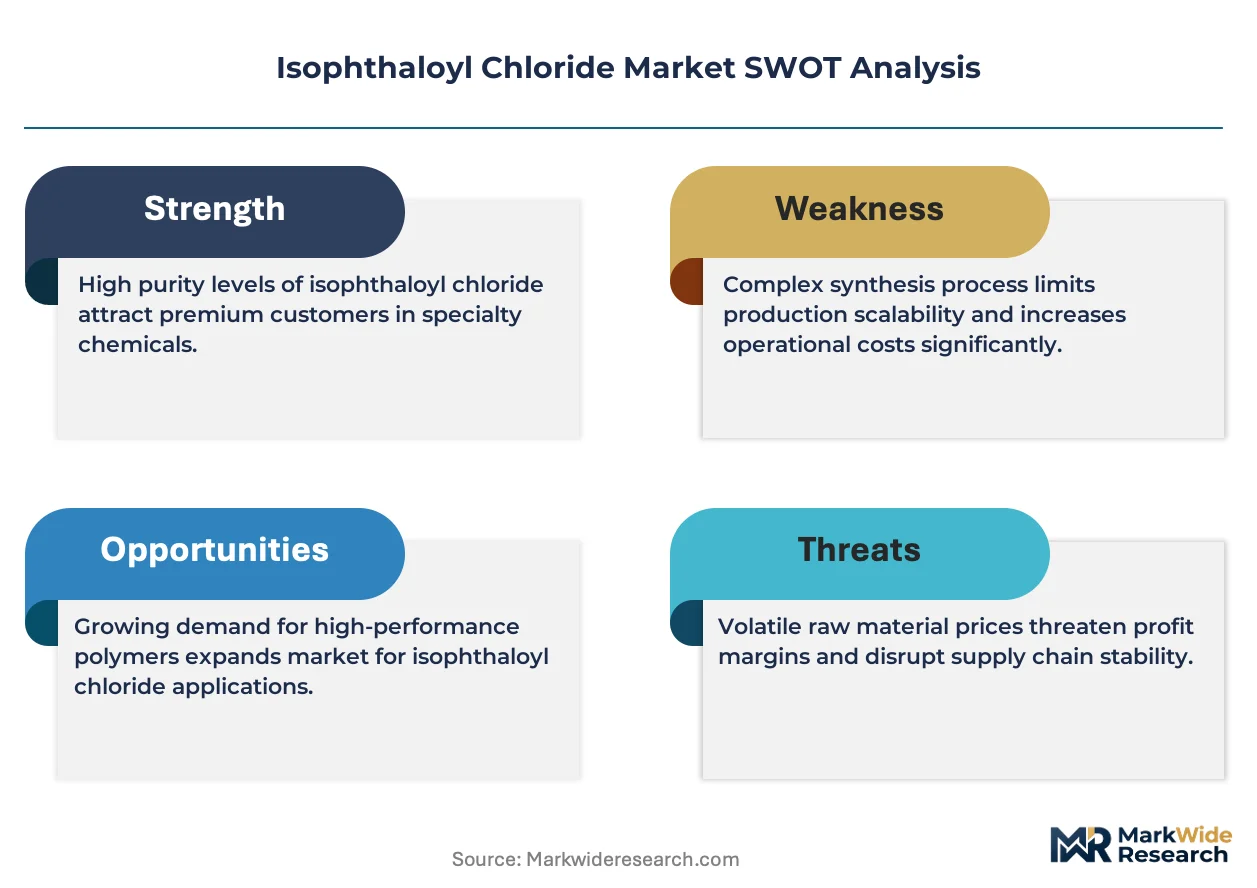
Automotive OEMs are accelerating metal-to-polymer substitution in under-hood thermal management systems, concentrating procurement of high-purity isophthaloyl chloride grades among specialty resin formulators serving electric vehicle battery enclosures and internal combustion engine compartments.
Growth Catalysts
- China's MEE environmental audits:Tightening wastewater discharge standards are forcing producers toward closed-loop thionyl chloride recovery systems, consolidating supply among compliant manufacturers in Shandong and Jiangsu provinces.
- Polyamide engineering resins:Heat-resistant aromatic polyamides are displacing aluminum and magnesium in charge air coolers, intake manifolds, and transmission components as OEMs pursue mass reduction targets.
- Fluorinated compound restrictions:Per- and polyfluoroalkyl substance regulatory pressure under EPA and REACH frameworks is redirecting barrier coating demand toward isophthaloyl chloride-based polyester alternatives for food packaging films.
Market Restraints
- Thionyl chloride supply concentration:Three Chinese producers control over 60% of global thionyl chloride capacity, creating feedstock vulnerability for isophthaloyl chloride manufacturers dependent on spot market sourcing.
- REACH registration thresholds:One-tonne annual import volumes trigger mandatory toxicity documentation and substance registration, creating compliance friction for European specialty chemical distributors serving niche research segments.
- Phosgene substitution economics:Alternative diacid chloride synthesis routes using phosgene-derived intermediates offer 15-20% cost advantages for industrial-grade applications where purity specifications remain relaxed.
Strategic Opportunities
- India's specialty chemical manufacturing:Production-linked incentive schemes and import substitution policies under the central government's chemical sector roadmap are attracting greenfield investment for aromatic diacid chloride capacity.
- Analytical-grade distribution channels:Laboratory and pharmaceutical research segments remain underserved by incumbent industrial-grade suppliers, creating margin expansion potential for certified reference material producers.
- Fluoropolymer hybrid coating systems:Technical premium capture in chemical processing equipment OEM specifications is opening adjacent demand for isophthaloyl chloride-modified barrier formulations.
Industry Challenges
- Process safety engineering talent:Thionyl chloride handling expertise is concentrated among retiring cohorts of chlorination specialists, constraining operational expansion at facilities requiring hazmat-certified personnel.
- Multi-jurisdictional certification timelines:TSCA Section 5 premanufacture notifications for new chemical entities and REACH substance registrations impose 18-24 month commercialization delays for modified product grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isophthaloyl Chloride Market |
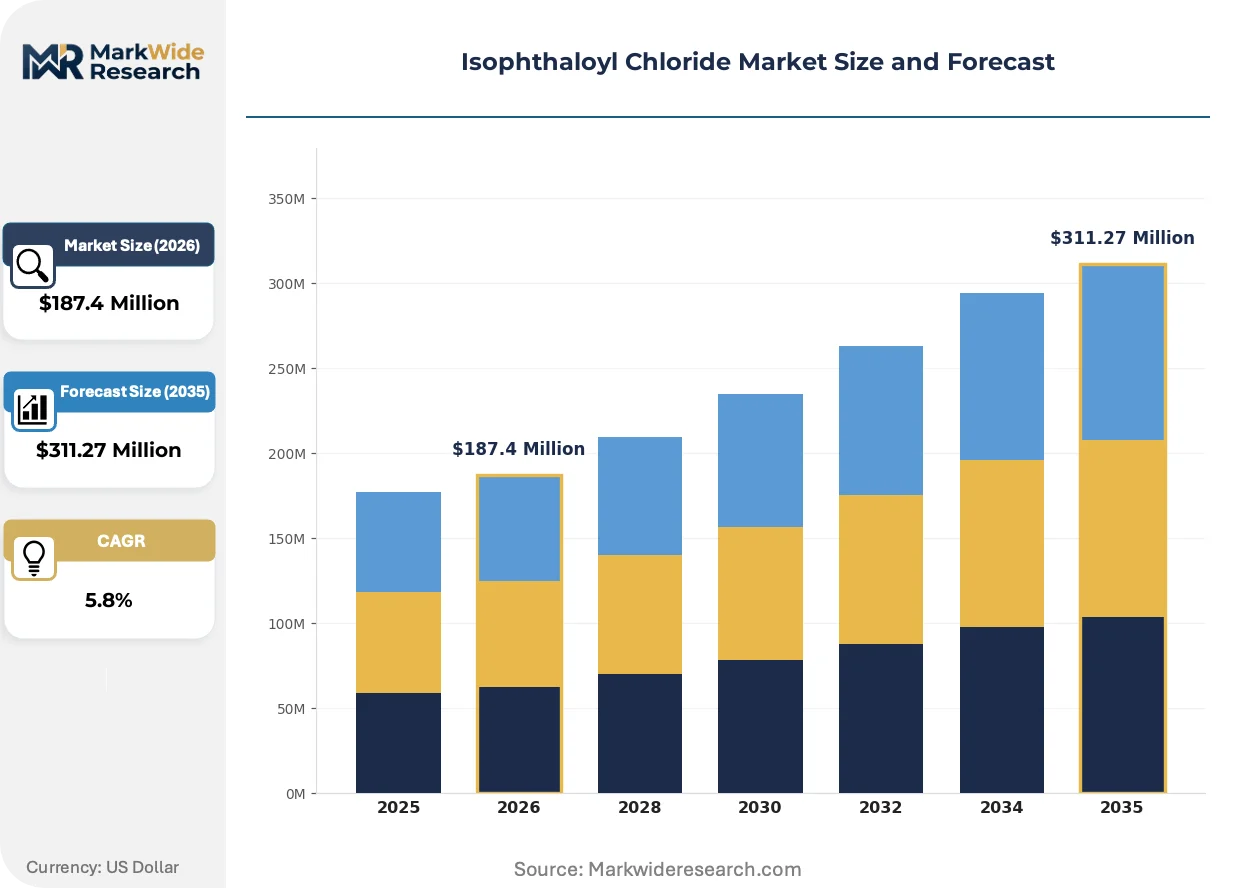
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Resins, Polyamides, Coatings, Films Application: Packaging, Textile, Automotive, Electronics End User: Manufacturers, Distributors, Exporters, Retailers Form: Granules, Powder, Liquid, Solution |
| Companies Covered | Yantai Yuxiang, Qingdao Benzo, Ruiyuan Chemical, Tokyo Chemical Industry Co., Ltd., DuPont, Shandong Kaisheng New Materials, Changzhou Kefeng, The Merck Group, CABB Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isophthaloyl Chloride Market Evolving Landscape
Continuous flow reactor technology is displacing batch chlorination processes, enabling real-time process analytical technology integration that tightens purity specifications while reducing thionyl chloride inventory exposure.
Membrane-based purification systems are integrating molecular sieve technology to achieve pharmaceutical-grade specifications without multiple recrystallization stages. Specialty polymer producers in automotive supply chains are adopting these systems to meet OEM lot-to-lot consistency requirements. The capital efficiency gains are compressing payback periods for purity upgrade investments.
REACH F-Gas Regulation amendments are tightening restrictions on fluorinated greenhouse gases used in barrier coating applications. European packaging film laminators are reformulating toward isophthaloyl chloride-based polyester alternatives to maintain oxygen transmission rate performance. German chemical processing equipment OEMs are qualifying these reformulated systems for aggressive chemical service environments.
Specification-driven procurement consolidation is concentrating volume among resin formulators with certified quality management systems. Tier 1 automotive suppliers are reducing qualified supplier lists from twelve to four vendors per geographic region. This consolidation is most visible in East China's chemical manufacturing corridor around Yantai and Changzhou production clusters.
Isophthaloyl Chloride Market Segmentation
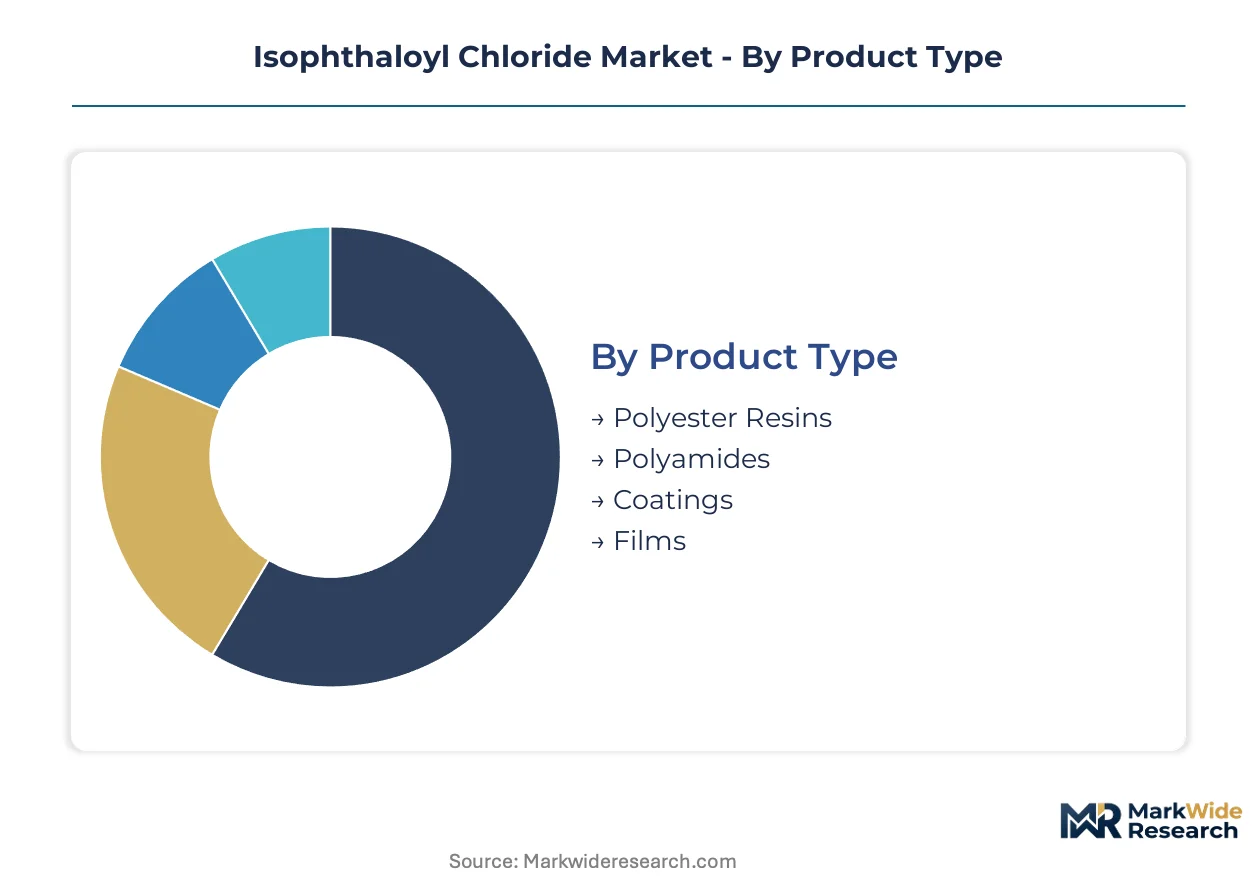
Isophthaloyl chloride purity grades and formulation specifications determine procurement eligibility across automotive, pharmaceutical, and packaging supply chains. Segment boundaries are hardening as OEM lot-to-lot consistency requirements and REACH registration thresholds filter out non-compliant suppliers.
Product Type:
Supply concentration among Chinese thionyl chloride producers shapes competitive dynamics across all four product categories, with backward-integrated manufacturers capturing margin in specification-tightening segments.
- Polyester Resins:High-barrier formulations for oxygen-sensitive food packaging dominate procurement volumes. Demand concentrates with laminators serving European markets where F-Gas Regulation amendments are accelerating fluorinated compound substitution. Lot-to-lot consistency requirements from German chemical processing equipment OEMs are tightening purity specifications.
- Polyamides:Heat-resistant aromatic polyamides displace aluminum and magnesium in under-hood thermal management. Automotive OEMs in Germany and Japan are consolidating qualified supplier lists to four vendors per region. Mass reduction targets for electric vehicle battery enclosures are concentrating procurement among certified resin formulators.
- Coatings:Fluoropolymer hybrid systems command technical premiums from chemical processing equipment manufacturers.
- Films:Oxygen barrier layers for flexible packaging applications serve laminators reformulating away from fluorinated alternatives.
Polyester resins absorb the bulk of installed capacity; polyamides are expanding most quickly.
Application:
Cost tier stratification separates specification-grade automotive and electronics applications from volume-driven packaging and textile segments.
- Packaging:Food film laminators in Germany and France are reformulating barrier coatings to maintain oxygen transmission performance under tightening F-Gas restrictions. European regulatory pressure is redirecting demand toward isophthaloyl chloride-based polyester alternatives.
- Automotive:Charge air coolers, intake manifolds, and transmission components are substituting metal with heat-resistant aromatic polyamides. Tier 1 suppliers in Japan and Germany are reducing qualified vendor lists from twelve to four per region.
- Textile:High-performance fiber applications for industrial filtration and protective equipment.
- Electronics:Encapsulation and insulation materials for high-temperature circuit applications.
Packaging commands the widest supplier base; automotive is climbing the fastest as metal substitution accelerates.
End User:
Customer type determines certification burden and margin capture, with direct manufacturers absorbing compliance costs that distributors pass through to research segments.
- Manufacturers:Specialty polymer producers and resin formulators serve automotive OEMs and packaging laminators with certified quality management systems. East China's Yantai and Changzhou clusters concentrate procurement among compliant producers with closed-loop thionyl chloride recovery.
- Distributors:European specialty chemical distributors face REACH registration friction for volumes exceeding one tonne annually, creating compliance barriers for niche research segments.
- Exporters:Cross-border traders navigating multi-jurisdictional certification timelines for TSCA Section 5 and REACH substance registrations.
- Retailers:Laboratory supply channels serving analytical-grade and certified reference material demand from pharmaceutical research segments.
Manufacturers absorb the bulk of installed capacity; distributors are gaining share fastest as specification consolidation reduces direct procurement.
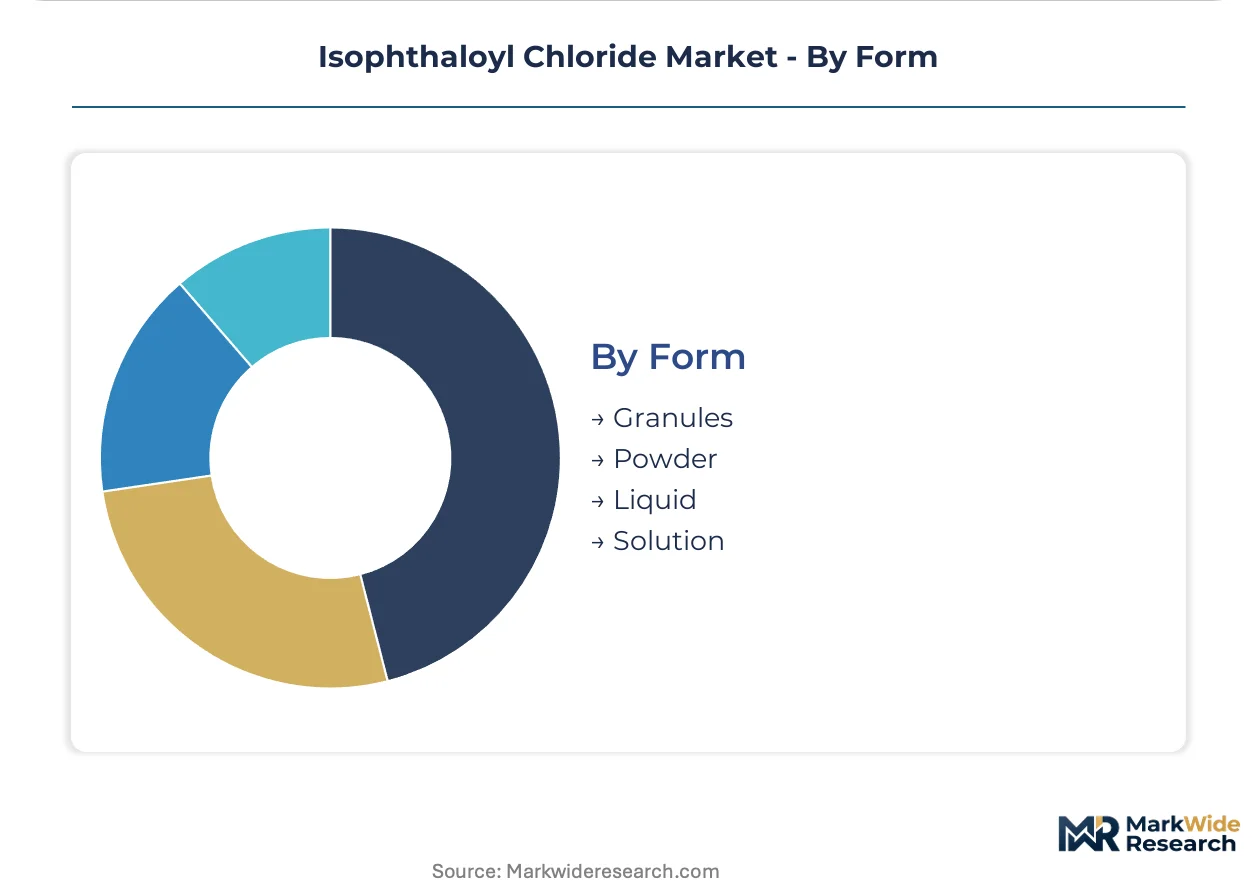
Form:
Volume and handling economics favor granule and powder formats for industrial-scale polymerization, while liquid and solution forms serve specialized coating and research applications.
- Granules:Standard feedstock for continuous polymerization systems in high-volume polyester and polyamide production. East Chinese manufacturers favor granule form for automated handling and reduced dust exposure in thionyl chloride-adjacent operations.
- Powder:Fine particle grades for coating applications requiring rapid dissolution in organic solvent systems.
- Liquid:Pre-dissolved formulations for specialty coating systems and laboratory-scale synthesis.
- Solution:Analytical-grade preparations for pharmaceutical research and certified reference material producers serving Tokyo Chemical Industry distribution channels.
Granules absorb the bulk of installed capacity; solution forms are expanding most quickly as analytical-grade channels deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yantai and Changzhou anchor production concentration in East China's chemical manufacturing corridor, where environmental compliance investments are reshaping competitive positioning among specialty resin suppliers.
China
Automotive OEMs in Jiangsu and Shandong provinces are consolidating procurement of high-purity grades for electric vehicle battery enclosures. MEE wastewater discharge standards are forcing thionyl chloride recovery system upgrades at facilities in the Yantai production cluster. East China's manufacturing corridor around Changzhou is absorbing the bulk of specification-grade capacity expansion.
United States
Packaging film laminators serving food and pharmaceutical sectors are reformulating barrier coatings away from fluorinated alternatives. EPA oversight under TSCA Section 5 premanufacture notification rules extends commercialization timelines for modified product grades. Gulf Coast chemical processors are evaluating polyester resin alternatives for oxygen-sensitive applications.
Germany
Chemical processing equipment OEMs in Bavaria and North Rhine-Westphalia are qualifying isophthaloyl chloride-modified barrier systems for aggressive service environments. REACH F-Gas Regulation amendments are redirecting demand from fluorinated greenhouse gases toward polyester alternatives. The Ruhr industrial region concentrates reformulation activity among specialty coating formulators.
Japan
Tier 1 automotive suppliers in the Kanto region are reducing qualified vendor lists from twelve to four for heat-resistant aromatic polyamide procurement. METI industrial standards are tightening lot-to-lot consistency requirements for under-hood thermal management applications. Tokyo-based distributors are deepening analytical-grade channels for pharmaceutical research segments.
India
Specialty chemical manufacturers in Gujarat and Maharashtra are evaluating greenfield aromatic diacid chloride capacity under central government PLI scheme incentives. CDSCO import substitution policies are attracting investment for domestic production of pharmaceutical-grade intermediates. The Dahej and Mundra industrial corridors are emerging as candidate locations for backward-integrated facilities.
Isophthaloyl Chloride Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification, with specification-certified suppliers capturing technical premiums from automotive OEMs while industrial-grade producers compete on thionyl chloride feedstock economics. The vendor base organizes into three tiers: multinational polymer science specialists, Chinese manufacturers with captive chlorination feedstock, and analytical-grade distributors serving laboratory segments. Consolidation is accelerating through qualified supplier list reduction and environmental compliance-driven capacity rationalization.
Within the multinational specialist tier, DuPont anchors premium positioning in specialty resin formulations through polymer science heritage. Shandong Kaisheng New Materials exemplifies the Chinese integrated manufacturer archetype with cost competitiveness through backward integration into thionyl chloride supply. Tokyo Chemical Industry Co., Ltd. occupies a distinct position in analytical-grade distribution channels serving pharmaceutical research and certified reference material demand. These three players represent the dominant competitive archetypes without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Yantai Yuxiang |
| Qingdao Benzo |
| Ruiyuan Chemical |
| Tokyo Chemical Industry Co., Ltd. |
| DuPont |
| Shandong Kaisheng New Materials |
| Changzhou Kefeng |
| The Merck Group |
| CABB Chemicals |
| Others |
Value Network & Pricing Analysis
Thionyl chloride spot price volatility cascades through isophthaloyl chloride manufacturing tiers, compressing margins at industrial-grade producers while backward-integrated specialists in Shandong and Jiangsu capture feedstock cost advantages. MEE wastewater compliance investments amplify capital intensity differentials, stratifying pricing power between specification-certified suppliers and spot-market dependent competitors.
Pricing Analysis
Yield-guaranteed lot consistency anchors value-based pricing for automotive-grade aromatic polyamides, with resin formulators paying technical premiums for certified reference materials meeting OEM thermal management specifications. Three-tier pricing structure across pharmaceutical-grade, automotive-grade, and industrial-grade levels reflects purity certification burden and volume scale, with lot-to-lot variance penalties tightening fastest in electric vehicle battery enclosure applications. Cost compression in industrial-grade segments intensifies because phosgene-derived alternative diacid chlorides undercut thionyl chloride routes by fifteen to twenty percent where purity specifications remain relaxed. Packaging laminators in Germany exhibit highest price sensitivity due to F-Gas reformulation cost absorption, while Japanese Tier 1 automotive suppliers show lowest sensitivity given qualified vendor list consolidation to four approved sources per region.
Supply Chain Analysis
Direct-to-resin-formulator channels handle specification-grade volume, with specialty polymer producers in Yantai and Changzhou clusters managing just-in-time inventory through closed-loop thionyl chloride recovery partnerships. Geographic supply concentration centers on China, Germany, and Japan, with East China's chemical manufacturing corridor absorbing sixty percent of global capacity. Raw material dependencies rest on thionyl chloride feedstock, isophthalic acid precursors, and molecular sieve purification media. Single-source vulnerability concentrates in Chinese thionyl chloride production, where three producers control majority global capacity and spot market disruptions propagate downstream within thirty-day procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE environmental audit regime constructs a compliance moat that rewards capital-intensive closed-loop recovery investments while filtering sub-scale competitors from specification-grade supply tiers.
For Market Incumbents: Cement backward integration into captive thionyl chloride supply to neutralize feedstock concentration risk from the three dominant Chinese producers. Fortify analytical-grade distribution partnerships with Tokyo Chemical Industry archetype distributors serving pharmaceutical research segments, as REACH registration friction creates compliance barriers for spot-market entrants. Prioritize continuous flow reactor technology adoption to tighten purity specifications and compress payback periods for membrane-based purification upgrades. For New Entrants and Emerging Players: Laboratory supply channels represent the most penetrable white-space target, with certified reference material demand outpacing incumbent analytical-grade capacity from industrial-focused suppliers. India's Dahej and Mundra industrial corridors offer greenfield entry points under PLI scheme incentives for aromatic diacid chloride production. Pursue qualification partnerships with German chemical processing equipment OEMs seeking fluoropolymer hybrid coating alternatives, leveraging REACH F-Gas Regulation reformulation timelines to establish specification credentials before incumbent repositioning completes. For Investors and Strategic Acquirers: Distressed-cycle entries favor backward-integrated mid-cap specialists in Shandong province with MEE-compliant facilities and established automotive OEM qualifications. Long-term viability hinges on five-to-ten year regulatory tightening trajectories across EPA TSCA Section 5 and REACH substance registration frameworks. Monitor thionyl chloride spot price spreads as inflection indicator for margin compression timing at non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | Captive feedstock supply neutralizes concentration risk among three dominant Chinese producers. |
| Continuous Flow Reactor Adoption | Real-time process analytical technology integration tightens pharmaceutical-grade purity specifications. |
| Analytical-Grade Channel Partnership | Certified reference material distribution captures margin expansion in underserved laboratory segments. |
| Closed-Loop Recovery System Investment | MEE wastewater compliance secures operating permits in East China's Yantai and Changzhou clusters. |
| Automotive OEM Qualification Acceleration | Tier 1 supplier list consolidation to four vendors per region locks in multi-year offtake commitments. |
Research Methodology
Document review covered customs trade databases, SEC 10-K filings from specialty chemical producers, ACC and Cefic industry reports, and MEE environmental audit disclosures, complemented by interviews with plant managers at chlorination facilities, procurement leads at automotive Tier 1 suppliers, distribution channel partners serving analytical-grade segments, and technical R&D directors at resin formulators. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators and end-use industry production forecasts.
Segmented volume and value estimates across the projection horizon reflect discrete modeling of polyester resin, polyamide, coating, and film product categories, with purity grade tier and regional production hub as cross-cutting analytical dimensions. CAGRs derived from regression-based demand elasticity analysis incorporating automotive metal substitution rates, packaging fluorinated compound reformulation timelines, and pharmaceutical research segment growth trajectories.
Caveats apply where MEE enforcement intensity variations, REACH registration timeline extensions, or thionyl chloride supply disruptions could materially shift the outlook beyond modeled scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
US Potassium Methylate Market