
 Transfluthrin Market | 2026-2036
Transfluthrin Market Size, Share, and Industry Trends Forecast 2026-2036
Transfluthrin Market Analytics
Household insecticide demand is realigning the Transfluthrin market as urban pest control intensifies across tropical and subtropical zones. Bayer AG leverages its pyrethroid synthesis heritage to sustain supply security for aerosol and liquid concentrates. Sumitomo Chemical anchors Asian manufacturing capacity through integrated intermediate production. Godrej Consumer Products dominates Indian distribution through dense retail and direct-to-home channels.
Transfluthrin is a synthetic pyrethroid insecticide characterized by high vapor pressure and rapid knockdown activity against mosquitoes, flies, and cockroaches at low concentrations. Manufacturers synthesize it via cyclopropanation of tetrafluorobenzyl alcohol derivatives, yielding a compound optimized for vaporizing formulations such as mosquito mats, liquid vaporizers, and heated devices. Household insecticides represent the largest application segment, with aerosol formats commanding premium shelf positioning in supermarkets and online retail. Agricultural pesticide applications are expanding fastest among smallholder-intensive regions, though margin pools remain thinner due to commodity pricing pressure on generic actives. The emulsion product type occupies a niche in professional pest control services, where dilutable concentrates support perimeter spraying protocols.
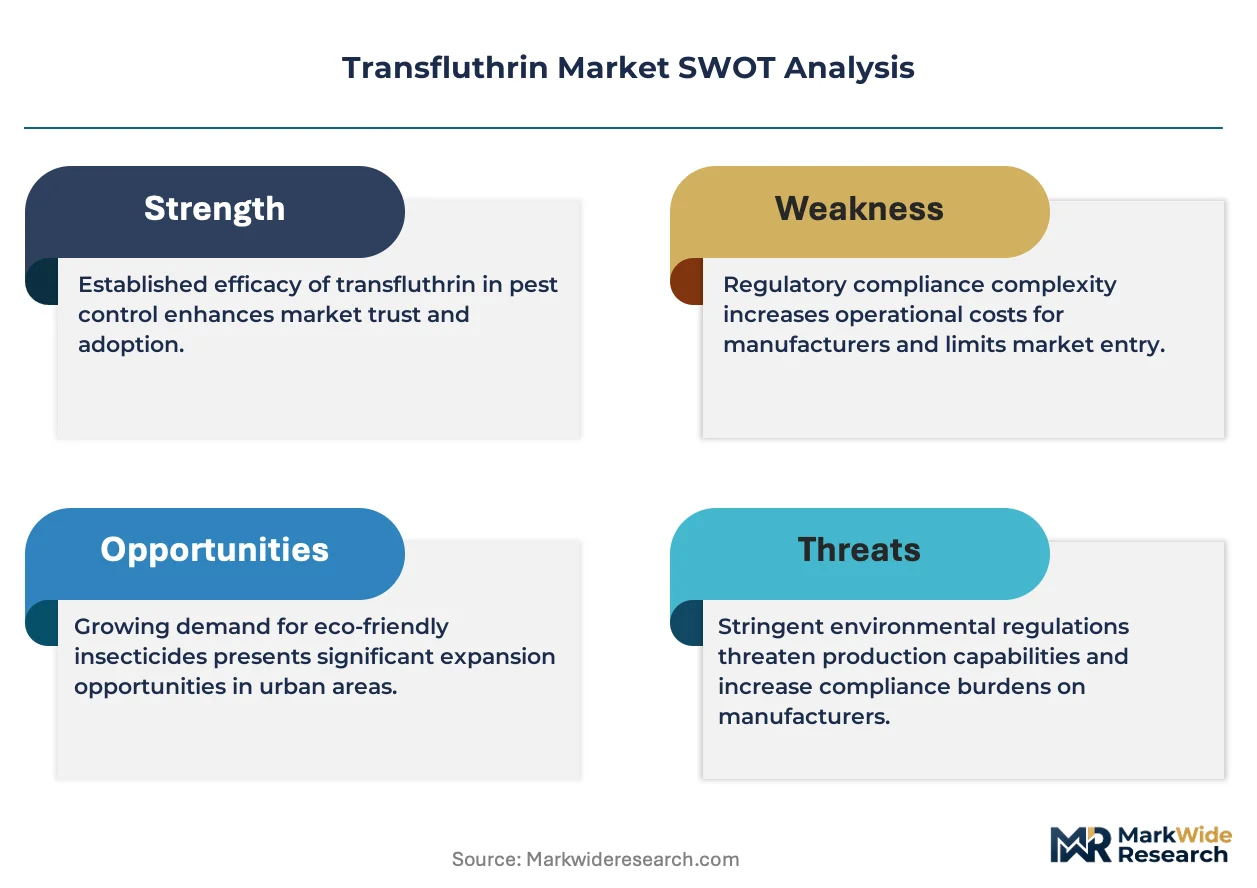
EPA registration requirements govern product efficacy claims and residue tolerance in the United States, while REACH restricts hazardous substance thresholds across European supply chains. India's Central Insecticides Board mandates BIS certification for domestic manufacture and import, creating compliance barriers for unregistered foreign suppliers. Stakeholders must monitor evolving pyrethroid resistance patterns and regulatory reclassification risks that could restrict vaporizer use in confined spaces.
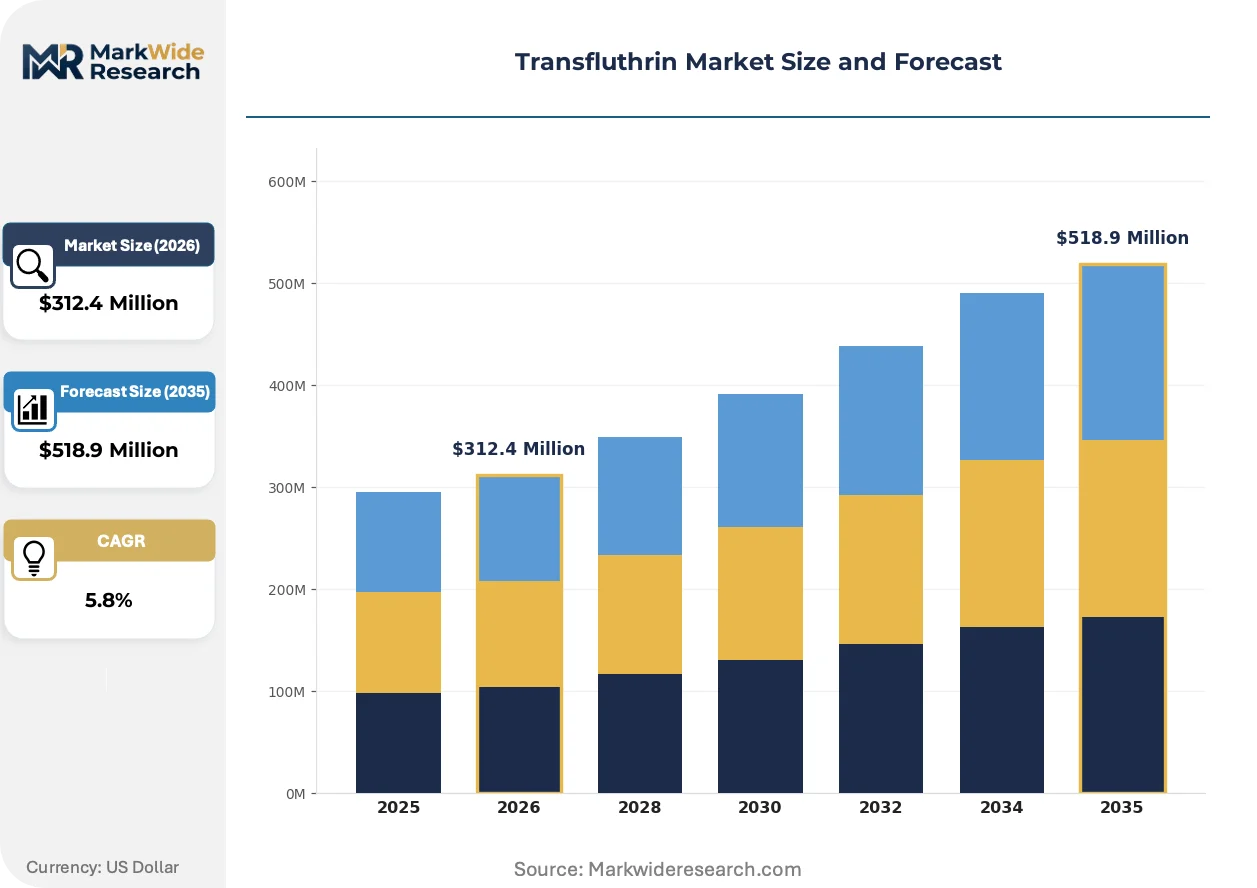
Market Dynamics
Household insecticide procurement is concentrating around low-dose vaporizer formulations as urban vector control programs in tropical megacities expand year-round deployment schedules. REACH compliance deadlines and EPA residue tolerance reviews are compressing formulation flexibility for legacy aerosol products.
Growth Catalysts
- REACH substance restrictions:European formulators are accelerating transitions to Transfluthrin-based vaporizers ahead of 2026 hazard classification reviews, creating pull for high-purity active ingredient supply.
- India PLI scheme for agrochemicals:Domestic manufacturing incentives are expanding integrated pyrethroid synthesis capacity, reducing import dependence for mosquito mat and coil producers.
- Heated device technology:Ceramic wick and PTC heating element advances are enabling lower-concentration formulations that extend active ingredient efficiency per unit.
Market Restraints
- Tetrafluorobenzyl alcohol feedstock volatility:Fluorochemical intermediate prices fluctuate with refrigerant industry demand cycles, compressing margin predictability for pyrethroid manufacturers.
- Chinese intermediate concentration:Cyclopropanation catalyst supply and chiral resolution capacity cluster in Jiangsu and Zhejiang provinces, creating single-geography exposure for global formulators.
- Pyrethroid resistance accumulation:Anopheles and Aedes mosquito populations in Southeast Asian field sites exhibit documented knockdown resistance mutations, threatening efficacy claims in WHO prequalification pathways.
Strategic Opportunities
- Brazil ANVISA re-registration:Pending reviews for household insecticide actives create entry windows for Transfluthrin-based formulations in Latin America's largest vector control market.
- Agricultural extension services:Smallholder rice cultivation in the Mekong Delta represents underpenetrated demand for granular and wettable powder applications against rice stem borers.
- E-commerce direct fulfillment:Platform-owned logistics networks in Indian tier-2 cities are enabling vaporizer refill subscription models that bypass traditional distributor markups.
Industry Challenges
- Chiral synthesis expertise scarcity:Stereoselective cyclopropanation requires specialized organometallic chemistry talent that concentrates in legacy agrochemical R&D hubs.
- BIS certification timelines:India's Central Insecticides Board technical committee review periods for new source registrations extend 18-24 months, delaying market entry for alternative suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfluthrin Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Granule, Emulsion Application: Household Insecticides, Agricultural Pesticides, Public Health Insecticides, Industrial Insecticides End User: Households, Agricultural Sector, Pest Control Services, Industrial Facilities Distribution Channel: Online Retail, Specialty Stores, Supermarkets, wholesalers |
| Companies Covered | Bayer AG, Sumitomo Chemical Co., Ltd., Syngenta AG, BASF SE, Godrej Consumer Products Limited, SC Johnson & Son, Inc., Jiangsu Yangnong Chemical Group Co., Ltd., Tagros Chemicals India Pvt. Ltd., Meghmani Organics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfluthrin Market Evolving Landscape
Formulation chemistry and delivery hardware are converging to reduce active ingredient loading rates while maintaining knockdown speed. This shift is compressing the addressable volume per household but expanding unit economics for precision-engineered devices.
Polymer-encapsulated Transfluthrin microcapsules are extending release duration in residual spraying applications. Vector control programs in sub-Saharan African trial sites are adopting these formulations for indoor residual spraying protocols. The technology is decentralizing application authority from centralized spray teams to household-level deployment models.
EPA's updated pyrethroid cumulative risk assessment framework is tightening residential exposure assumptions for vaporizer products. Formulators are redesigning emission profiles and reducing daily exposure duration estimates in submission packages. Aerosol segment manufacturers face the steepest reformulation costs to meet revised hazard quotients for child inhalation scenarios.
Urban pest control services are unbundling preventive maintenance contracts from acute treatment calls. Property management firms in Indian metropolitan clusters are negotiating annual vaporizer supply agreements with direct-to-facility logistics. This restructuring concentrates procurement authority with facilities managers rather than distributed retail purchasing decisions.
Transfluthrin Market Segmentation
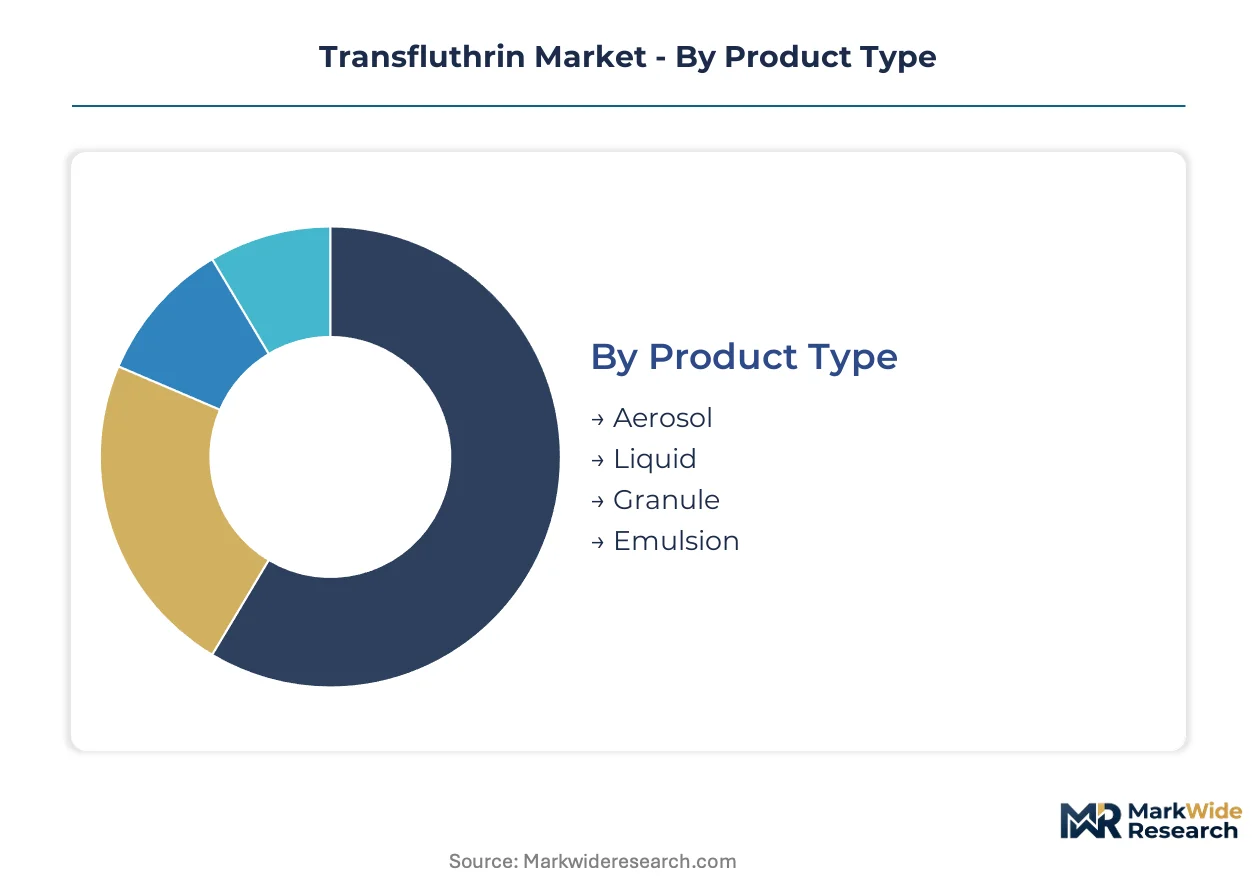
Transfluthrin formulations diverge sharply across delivery mechanisms, with hardware compatibility and emission profiles dictating procurement specifications. Each segment carries distinct margin structures and regulatory exposure, requiring formulators to align R&D investment with channel-specific performance thresholds.
Product Type:
Upgrade cycles in heating element technology and propellant chemistry are redrawing the competitive map across delivery formats, as ceramic wick vaporizers displace legacy pressurized systems.
- Aerosol:Pressurized hydrocarbon or compressed gas formulations deliver immediate knockdown in enclosed spaces. Demand concentrates in Brazilian and Mexican retail channels where supermarket shelf placement commands premium positioning fees from multinational formulators.
- Liquid:Concentrated refills for electric vaporizers with ceramic wick or PTC heating elements. Indian household penetration drives volume, with Godrej Consumer Products and domestic competitors expanding direct-to-home subscription logistics in tier-2 cities.
- Granule:Slow-release matrix formulations for perimeter and agricultural applications. Rice cultivation zones in Vietnam and Thailand represent concentrated uptake for stem borer control programs.
- Emulsion:Dilutable concentrates for professional spray equipment. Pest control services in US metropolitan markets specify these formulations for integrated vector management contracts.
Aerosol sits at the top of the volume ranking, with Liquid climbing the fastest.
Application:
Cost tier stratification separates premium vaporizer systems from commodity agricultural actives, with household formulations capturing margin pools unavailable to field crop applications.
- Household Insecticides:Vaporizing mats, liquid refills, and heated devices dominate residential mosquito control. EPA cumulative risk assessments and REACH hazard classification reviews are compressing allowable emission rates, forcing reformulation investments.
- Agricultural Pesticides:Granular and wettable powder applications target rice stem borers and storage pests. Mekong Delta smallholders and Indian state extension services drive procurement, though generic pricing pressure thins manufacturer margins.
- Public Health Insecticides:WHO prequalification pathways govern indoor residual spraying and space treatment protocols. Polymer-encapsulated microcapsule formulations are extending residual efficacy in sub-Saharan African trial sites.
- Industrial Insecticides:Perimeter treatments for food processing and warehousing facilities. FSMA compliance requirements in US facilities mandate documented pest control protocols that specify pyrethroid residual barriers.
Household Insecticides holds the revenue concentration advantage, with Public Health Insecticides gaining share fastest through donor-funded vector control programs.
End User:
Customer type determines specification authority, with facilities managers and procurement officers displacing individual retail purchasing decisions in commercial segments.
- Households:Individual consumers purchasing through retail or e-commerce channels. Indian platform-owned logistics networks enable subscription refill models that bypass traditional distributor markups.
- Agricultural Sector:Smallholder cooperatives and state extension services specify bulk formulations. India's PLI scheme for agrochemicals is expanding domestic pyrethroid synthesis capacity to serve this demand.
- Pest Control Services:Contract operators managing preventive maintenance for property management firms. Annual supply agreements with direct-to-facility delivery are restructuring procurement authority in Indian metropolitan clusters.
- Industrial Facilities:Food processing plants, pharmaceutical manufacturing, and warehousing operations with documented HACCP or GMP compliance requirements. Third-party audit standards dictate residual spray documentation.
Pest Control Services is expanding most quickly as preventive maintenance contracts unbundle from acute treatment calls.
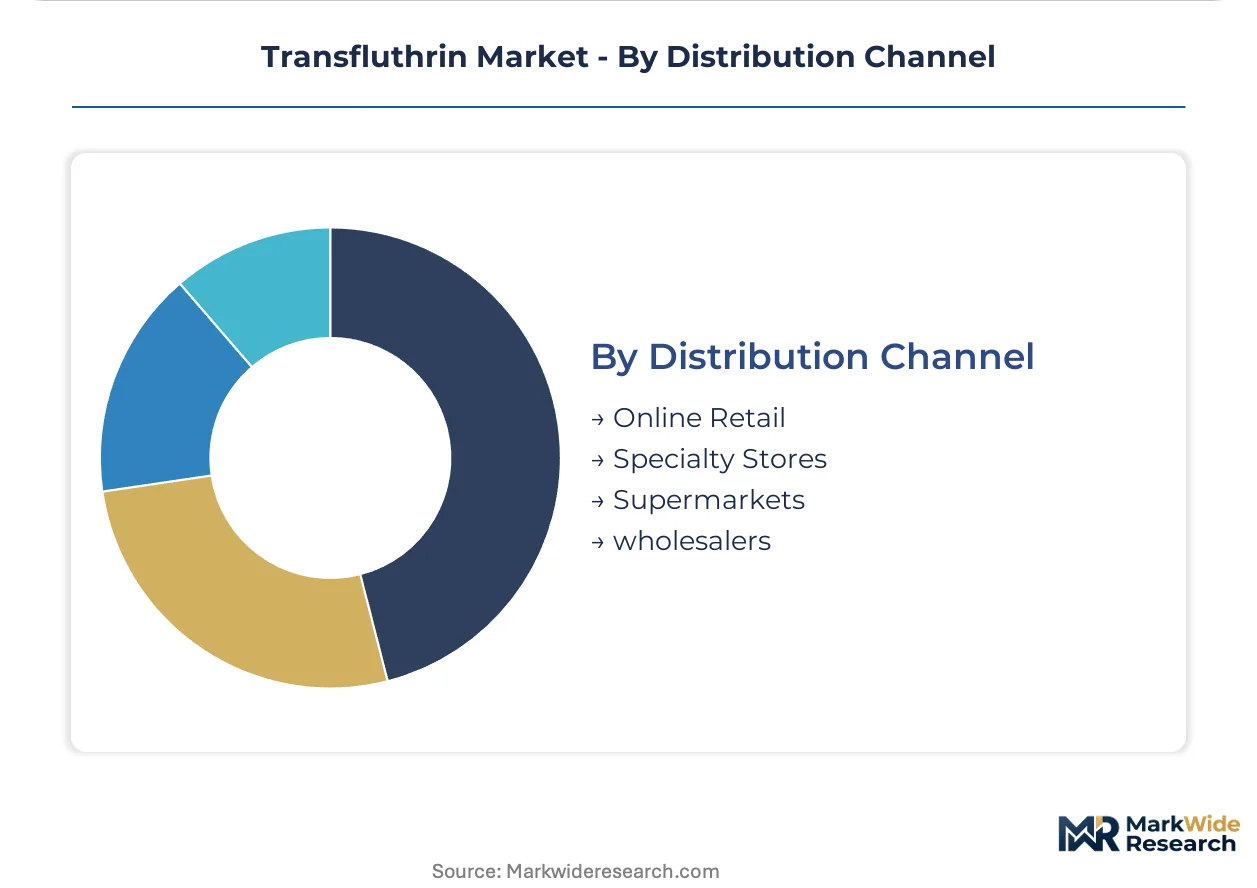
Distribution Channel:
Geographic reach and margin capture diverge across channel structures, with e-commerce platforms extracting logistics efficiencies unavailable to brick-and-mortar retail.
- Online Retail:Platform-direct sales and third-party marketplace listings. Indian tier-2 city penetration through platform-owned logistics is enabling subscription models for vaporizer refills.
- Specialty Stores:Agricultural input dealers and pest control equipment suppliers. Technical advisory relationships support specification of emulsion concentrates for professional applicators.
- Supermarkets:Mass retail placement for aerosol and vaporizer starter kits. Brazilian and Mexican retail chains command slotting fees that favor multinational formulators with marketing budgets.
- Wholesalers:Regional distributors serving rural agricultural markets and independent pest control operators. Inventory financing terms determine competitive positioning in working-capital-constrained segments.
Supermarkets maintain the volume lead, with Online Retail climbing fastest through subscription logistics innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting pyrethroid synthesis capacity toward jurisdictions with streamlined chemical registration pathways and lower compliance overhead. Manufacturers are relocating cyclopropanation operations to exploit these cost-of-compliance gaps.
China
Jiangsu and Zhejiang provinces concentrate cyclopropanation catalyst supply and chiral resolution capacity for tetrafluorobenzyl alcohol derivatives. MEE enforcement of dual carbon goals is tightening emissions standards at fluorochemical intermediate plants. Yangtze River Delta chemical parks are consolidating pyrethroid API production to meet stricter wastewater discharge protocols.
India
Godrej Consumer Products and domestic formulators are expanding vaporizer and coil portfolios to serve household demand in tier-2 cities. The PLI scheme for agrochemicals is incentivizing integrated pyrethroid synthesis capacity to reduce import dependence. Gujarat and Maharashtra host the bulk of BIS-certified manufacturing facilities for mosquito mat production.
United States
EPA cumulative risk assessments for pyrethroids are tightening residential exposure assumptions for vaporizer products. Aerosol segment manufacturers face reformulation costs to meet revised hazard quotients for child inhalation scenarios. Texas and Louisiana chemical corridors supply fluorochemical intermediates subject to FERC-regulated energy pricing volatility.
Brazil
ANVISA re-registration reviews for household insecticide actives are creating entry windows for Transfluthrin-based formulations in Latin America's largest vector control market. São Paulo and Rio de Janeiro metropolitan clusters drive supermarket shelf placement competition for aerosol products. Brazilian retail chains command slotting fees that favor multinational formulators with marketing budgets.
Germany
Bayer AG leverages pyrethroid synthesis heritage to sustain supply security for European aerosol and liquid concentrate markets. ECHA REACH hazard classification reviews are compressing allowable emission rates for legacy formulations. North Rhine-Westphalia's chemical industry cluster hosts specialized organometallic chemistry talent for stereoselective cyclopropanation processes.
Transfluthrin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with household formulations consolidating around consumer-facing portfolios while agricultural applications fragment among generic suppliers. The vendor base separates into three tiers: multinational agrochemical conglomerates with integrated pyrethroid synthesis, regional formulators serving domestic registration pathways, and toll manufacturers supplying unbranded active ingredient. Two dominant competitive moves are reshaping positioning: backward integration into tetrafluorobenzyl alcohol intermediates to secure margin predictability, and geographic expansion through ANVISA and BIS registration filings to capture re-registration windows.
Among German and Japanese chemical conglomerates, Bayer AG and Sumitomo Chemical Co., Ltd. exemplify the integrated synthesis archetype with captive pyrethroid production chains. Godrej Consumer Products Limited occupies a distinct position as a domestic Indian formulator leveraging dense retail distribution and direct-to-home subscription logistics. Jiangsu Yangnong Chemical Group Co., Ltd. represents the Chinese intermediate-specialist tier concentrated in Yangtze River Delta chemical parks.
| Leading Market Players |
|---|
| Bayer AG |
| Sumitomo Chemical Co., Ltd. |
| Syngenta AG |
| BASF SE |
| Godrej Consumer Products Limited |
| SC Johnson & Son, Inc. |
| Jiangsu Yangnong Chemical Group Co., Ltd. |
| Tagros Chemicals India Pvt. Ltd. |
| Meghmani Organics Limited |
| Others |
Value Network & Pricing Analysis
Captive synthesis of tetrafluorobenzyl alcohol intermediates anchors both supply security and margin control for integrated pyrethroid manufacturers. Godrej Consumer Products and Bayer AG leverage backward integration into fluorochemical feedstocks to buffer pricing volatility from refrigerant industry demand cycles, while toll-dependent formulators absorb cost compression in spot intermediate markets.
Pricing Analysis
Distributor markups in Indian tier-2 cities compress as platform-owned logistics enable direct-to-home subscription models for vaporizer refills. Three-tier pricing structure across premium ceramic-wick systems, standard heated devices, and economy coil formats separates specification tiers by heating element technology and BIS certification grade. Pricing pressure stems from generic agricultural actives flooding Mekong Delta procurement tenders, where smallholder cooperatives prioritize unit cost over residual efficacy. Household insecticide buyers show lowest price sensitivity, accepting premium positioning for EPA-registered vaporizer systems with documented child-safety emission profiles.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Zhejiang provinces, where cyclopropanation catalyst production and chiral resolution capacity concentrate for tetrafluorobenzyl alcohol derivatives. Raw material dependencies span fluorochemical intermediates from Chinese refrigerant plants, organometallic catalysts from German specialty chemical suppliers, and ceramic wick substrates from Japanese precision ceramics manufacturers. Supply chain risk centers on MEE enforcement of dual carbon goals tightening emissions standards at Yangtze River Delta chemical parks. Distribution runs through Godrej's dense Indian retail network, Bayer's European aerosol channel partnerships, and Sumitomo's Asian technical-grade bulk shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transfluthrin market reads as a late-cycle quality story, with urban vector control programs shifting procurement specifications toward WHO-prequalified polymer-encapsulated microcapsule formulations that command residual efficacy premiums.
For Market Incumbents: Cement supply security through captive tetrafluorobenzyl alcohol synthesis capacity in Gujarat or Maharashtra chemical corridors, insulating margin structures from Chinese intermediate volatility. Deepen BIS certification moats by accelerating 18-24 month technical committee review timelines for alternative supplier registrations, defending against unregistered import competition. Prioritize ceramic wick vaporizer R&D to meet EPA's tightened child inhalation hazard quotients, converting reformulation compliance costs into specification advantages.
For New Entrants and Emerging Players: Begin with ANVISA re-registration windows for household insecticide actives in Brazil, where São Paulo supermarket chains seek alternatives to incumbent aerosol suppliers. Target Mekong Delta agricultural extension services with wettable powder formulations for rice stem borer control, exploiting underpenetrated demand outside donor-funded public health programs. Pursue platform-direct fulfillment partnerships with Indian e-commerce logistics networks, bypassing traditional distributor markups through subscription refill models in tier-2 cities.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Indian formulators with BIS-certified manufacturing and established distributor relationships because domestic PLI scheme incentives are compressing import dependence for pyrethroid actives. Long-term viability hinges on acquisition targets with demonstrated REACH compliance capabilities ahead of 2026 hazard classification reviews. Watch for pyrethroid resistance mutation documentation in Southeast Asian Anopheles field populations as the signal indicating potential WHO prequalification pathway disruptions that would revalue residual efficacy claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Intermediates | Captive tetrafluorobenzyl alcohol production buffers margin predictability against refrigerant industry demand cycles. |
| BIS Certification Acceleration | Expedited Central Insecticides Board registrations block unregistered foreign suppliers from Indian mosquito mat markets. |
| Ceramic Wick Vaporizer R&D Investment | PTC heating element advances enable lower-concentration formulations meeting EPA child inhalation hazard thresholds. |
| ANVISA Registration Filing | Pending re-registration reviews create entry windows for Transfluthrin-based formulations in Brazilian retail channels. |
| Polymer-Encapsulated Microcapsule Development | Extended-release formulations qualify for WHO prequalification pathways in sub-Saharan African vector control programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Yangtze River Delta pyrethroid API facilities, procurement leads at Indian household insecticide formulators, distribution channel partners in Brazilian supermarket networks, and technical R&D directors at German organometallic chemistry hubs. Secondary validation drew from customs and trade data, SEC 10-K filings of listed agrochemical conglomerates, BIS certification registries, and ANVISA re-registration dockets. Bottom-up volume estimates from formulation-grade consumption patterns were triangulated against top-down pyrethroid active ingredient production capacity assessments.
Historical reference periods anchored the projection horizon to documented cyclopropanation capacity expansions, REACH compliance transition timelines, and EPA cumulative risk assessment revision cycles. Segmentation dimensions modeled include product type (aerosol, liquid, granule, emulsion), application (household, agricultural, public health, industrial), and regional production hub (Jiangsu-Zhejiang corridor, Gujarat-Maharashtra cluster, North Rhine-Westphalia specialty chemicals). CAGRs were derived from elasticity-adjusted demand curves incorporating urbanization rates in tropical megacities and smallholder rice cultivation intensity in the Mekong Delta. Forecast inputs integrated ceramic wick technology adoption curves and pyrethroid resistance mutation surveillance data from WHO field sites.
Several conditions sit outside the modeled scope, including unscheduled regulatory reclassification of pyrethroids under REACH hazard categories, abrupt MEE enforcement actions shuttering Chinese fluorochemical intermediate plants, and emergence of CRISPR-based vector control technologies displacing chemical insecticide demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Functional Polymer Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Asia-Pacific Amino Acids Market