
 Global Peptide Synthesis Market | 2026-2036
Global Peptide Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peptide Synthesis Market Foresight
Multi-sourced contract manufacturing is repositioning how biopharmaceutical firms access peptide production capacity. Bachem Holding AG anchors European supply through large-scale GMP facilities in Switzerland. Thermo Fisher Scientific Inc. extends its position via integrated reagent-to-service workflows across North America and Asia. GenScript Biotech Corporation competes on custom synthesis turnaround times for research-grade peptides.
Peptide synthesis encompasses the chemical or biological assembly of amino acid chains into defined sequences, typically ranging from two to one hundred residues, using carbodiimide coupling reagents and protecting group strategies to control regioselectivity. The process serves drug discovery and therapeutic manufacturing where precise sequence fidelity determines biological activity and immunogenicity profiles. Solid phase synthesis retains dominance in clinical-scale production due to purification efficiency and automation compatibility, while recombinant DNA technology captures margin pools for longer peptides exceeding fifty residues where chemical yields degrade. Modified peptides represent the fastest-expanding product category as pharmaceutical developers pursue enhanced stability and receptor selectivity through non-natural amino acid incorporation.
FDA peptide drug guidance and EMA GMP Annex 1 revisions are tightening purity specifications and endotoxin thresholds for therapeutic-grade materials. China's NMPA alignment with ICH Q7 guidelines is reshaping export qualification requirements for domestic manufacturers. REACH chemical registration in Europe adds compliance layers for novel coupling reagents and resin chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply qualification delays.
Market Dynamics
Accelerated FDA and EMA approval pathways for peptide therapeutics are compressing development timelines and forcing manufacturers to scale GMP capacity faster than traditional chemical synthesis infrastructure permits.
Growth Catalysts
- Metabolic Disease Pipelines:Biopharmaceutical developers are expanding GLP-1 receptor agonist programs for diabetes and obesity management, creating sustained demand for large-scale peptide production capacity.
- REACH Chemical Registration:European compliance requirements for novel coupling reagents are driving investment in greener chemistries that reduce solvent waste and purification steps.
- Swiss CDMO Clusters:Concentrated GMP infrastructure around Basel and Visp is attracting multi-sourced manufacturing contracts from firms seeking geographic risk diversification.
Market Restraints
- Amino Acid Derivative Costs:Non-natural amino acid prices fluctuate with petroleum feedstock volatility, squeezing margins on modified peptide programs.
- Single-Source Resin Supply:Controlled-pore glass and polystyrene resin production concentrates among three European specialty chemical suppliers, creating bottleneck vulnerability.
- Chemical Yield Degradation:Solid-phase synthesis efficiency drops precipitously beyond fifty residues, limiting addressable market scope for longer therapeutic peptides.
Strategic Opportunities
- China NMPA Alignment:Domestic manufacturers upgrading to ICH Q7 standards can capture export qualification contracts previously held by European CDMOs.
- Continuous Flow Synthesis:Microreactor technology convergence with real-time analytical monitoring is enabling just-in-time production for personalized peptide vaccines.
- Research-Grade Turnaround:Academic institutions and biotech startups are migrating to platform-as-a-service models that bypass capital-intensive in-house synthesis investments.
Industry Challenges
- Peptide Chemist Scarcity:Universities have reduced specialized training programs in solid-phase synthesis methods, constraining technical workforce availability for GMP facilities.
- Endotoxin Validation Timelines:FDA purity specification tightening requires extended qualification batches that delay product release and tie up manufacturing suites.
- Legacy ERP Integration:Batch record systems designed for small-molecule pharmaceuticals require expensive customization to handle peptide-specific protecting group tracking and resin loading calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peptide Synthesis Market |
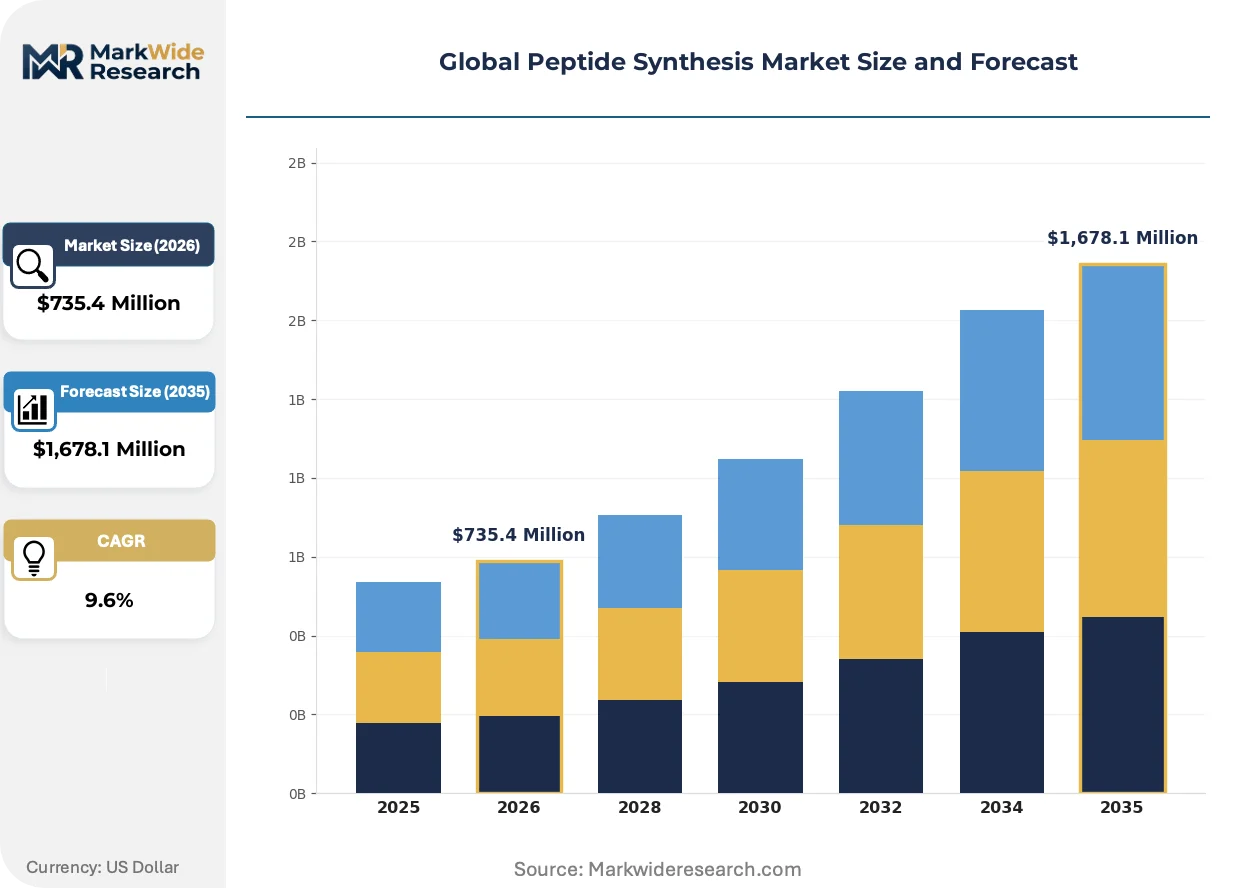
| Market Size in 2026 | $735.4 Million |
| Market Size in 2035 | $1,678.1 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Peptides, Modified Peptides, Large Peptides, Custom Peptides, Labelled Peptides Technology: Solid Phase Synthesis, Liquid Phase Synthesis, Recombinant DNA Technology, Microwave Assisted Synthesis, Automated Synthesizers Application: Drug Discovery, Diagnostics, Vaccine Development, Agriculture, Cosmetic Formulations End User: Biopharmaceutical Companies, Research Laboratories, Contract Research Organizations, Academic Institutes |
| Companies Covered | PolyPeptide Group AG, AmbioPharm Inc., Thermo Fisher Scientific Inc., BioDuro LLC, Kaneka Corporation, Merck KGaA, GenScript Biotech Corporation, CEM Corporation, Bachem Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peptide Synthesis Market Shifts & Advancements
Automation, regulatory harmonization, and procurement centralization are converging to transform how peptide synthesis capacity is accessed and monetized across the value chain.
Integrated robotic workstations are automating solid-phase synthesis workflows from resin loading through cleavage and crude purification. Mid-sized biopharmaceutical firms are adopting these platforms to reduce reliance on external CDMOs for clinical-stage material. The technology is automating batch reproducibility and freeing chemists for method development rather than repetitive manual operations.
EMA GMP Annex 1 revisions are mandating closed-system processing for sterile peptide formulations. European manufacturers are retrofitting isolator technology into existing suites at capital costs exceeding traditional cleanroom upgrades. Parenteral peptide developers face the steepest compliance burden, with many relocating fill-finish operations to Switzerland where Swissmedic interprets containment requirements more predictably.
Consolidated procurement functions at large pharmaceutical houses are unbundling synthesis from analytical characterization services. Biopharmaceutical procurement teams now source crude peptide production, purification, and QC testing from separate qualified vendors rather than single-source CDMO packages. This fragmentation is most advanced in the United States, where preferred provider networks compete on individual service line pricing rather than bundled contracts.
Global Peptide Synthesis Market Segmentation
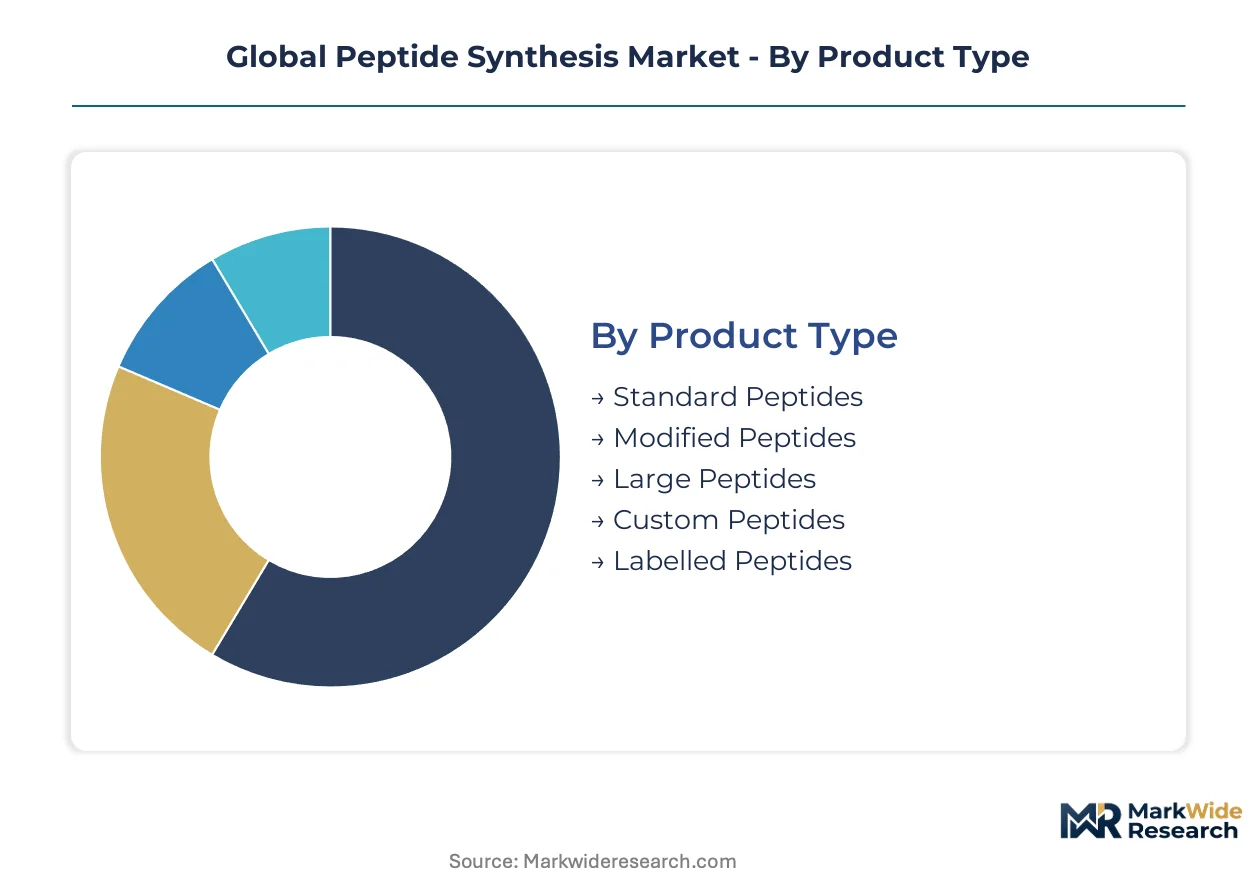
Peptide synthesis market segmentation reflects divergent buyer priorities across therapeutic development stages. Product type selection determines regulatory pathway complexity and manufacturing scale requirements. Technology choices separate research-grade speed from commercial-grade compliance.
Product Type:
Buyers in this category differentiate by stability requirements and amino acid modification complexity.
- Modified Peptides:Incorporation of non-natural amino acids, cyclization, and PEGylation extends half-life and receptor selectivity for metabolic and oncology therapeutics. FDA accelerated approval pathways for GLP-1 programs are concentrating demand in the United States and Switzerland where CDMOs possess specialized modification expertise.
- Standard Peptides:Unmodified sequences up to thirty residues serve as research tools and diagnostic antigens with fastest turnaround times. Academic institutes in China and Germany are driving volume procurement through platform-as-a-service contracts that bypass capital-intensive in-house synthesis investments.
- Large Peptides:Sequences exceeding fifty residues where solid-phase yields degrade, requiring hybrid chemical-recombinant approaches.
- Custom Peptides:Project-specific sequences with variable batch sizes for exploratory research programs.
- Labelled Peptides:Fluorescent or isotopic tags for imaging and quantitative assays in diagnostic development.
Standard peptides lead volumes today; modified peptides are gaining share fastest.
Technology:
Technology selection tracks production scale and residue count thresholds.
- Solid Phase Synthesis:Stepwise amino acid addition on insoluble resin supports dominates clinical-scale manufacturing through automation compatibility and purification efficiency. EMA GMP Annex 1 closed-system mandates are driving European manufacturers toward isolator-retrofitted solid-phase suites at capital costs exceeding traditional cleanroom upgrades.
- Recombinant DNA Technology:Microbial expression systems capture longer peptides where chemical synthesis efficiency collapses. Chinese manufacturers upgrading to ICH Q7 standards are expanding recombinant capacity to capture export qualification contracts previously held by European CDMOs.
- Liquid Phase Synthesis:Solution-phase coupling for specialized applications requiring homogeneous reaction conditions.
- Microwave Assisted Synthesis:Accelerated coupling kinetics for research-grade rapid prototyping.
- Automated Synthesizers:Integrated robotic workstations reducing manual intervention in mid-scale production.
Solid phase synthesis retains the largest installed base; recombinant DNA technology is expanding most quickly.
Application:
Application mix correlates with funding concentration and regulatory scrutiny intensity.
- Drug Discovery:High-throughput peptide libraries and lead optimization campaigns consume the largest synthesis volumes. Biopharmaceutical companies in the United States are unbundling crude production from analytical services, sourcing each from separate qualified vendors rather than single-source CDMO packages.
- Vaccine Development:Personalized neoantigen peptides and synthetic epitope vaccines are emerging as fastest-expanding demand pockets. Continuous flow microreactor convergence with real-time monitoring is enabling just-in-time production for individualized cancer vaccines.
- Diagnostics:Antigen peptides and capture reagents for immunoassay development.
- Agriculture:Biopesticide peptides and plant signaling molecules for crop protection.
- Cosmetic Formulations:Topical signal peptides for anti-aging and skin barrier applications.
Drug discovery commands the largest current spend; vaccine development shows the steepest expansion trajectory.
End User:
End user segmentation captures organizational scale and outsourcing maturity differences.
- Biopharmaceutical Companies:Integrated developers with multi-sourced manufacturing strategies and dedicated procurement functions. Swiss CDMO clusters around Basel and Visp are attracting geographic risk-diversification contracts from firms seeking regulatory predictability through Swissmedic interpretation of containment requirements.
- Contract Research Organizations:Specialized service providers managing synthesis outsourcing for sponsor firms. CROs in China are capturing research-grade turnaround contracts through accelerated custom synthesis platforms.
- Research Laboratories:Biotechnology and pharmaceutical internal discovery groups with capital constraints.
- Academic Institutes:University and government research facilities with grant-funded peptide requirements.
Biopharmaceutical companies dominate procurement value; contract research organizations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss CDMO clusters around Basel and Visp anchor global peptide synthesis capacity through concentrated GMP infrastructure and regulatory predictability under Swissmedic oversight.
United States
GLP-1 receptor agonist pipelines for diabetes and obesity management drive sustained demand for large-scale peptide production. FDA accelerated approval pathways compress development timelines and force faster GMP scale-up. Greater Boston and San Diego biotech corridors host specialized modification expertise for metabolic therapeutics.
Switzerland
Multi-sourced manufacturing contracts from risk-diversifying biopharmaceutical firms concentrate around Basel and Visp. Swissmedic interprets EMA GMP Annex 1 containment requirements with regulatory predictability that attracts parenteral peptide developers. The country's specialty chemical suppliers control critical resin and coupling reagent production.
China
Domestic manufacturers upgrading to ICH Q7 standards capture export qualification contracts previously held by European CDMOs. NMPA alignment with international guidelines reshapes qualification requirements for therapeutic-grade materials. Yangtze River Delta research-grade synthesis platforms compete on custom turnaround times for academic and startup demand.
Germany
REACH chemical registration requirements for novel coupling reagents drive investment in greener chemistries reducing solvent waste. EMA GMP Annex 1 closed-system mandates force capital-intensive isolator retrofits into existing manufacturing suites. Baden-Württemberg and North Rhine-Westphalia host precision automation equipment suppliers serving European solid-phase synthesis infrastructure.
India
Contract research organizations capture research-grade peptide turnaround contracts through accelerated custom synthesis platforms. CDSCO regulatory harmonization with ICH standards opens pathways for domestic manufacturers to serve export markets. Maharashtra and Gujarat chemical manufacturing belts supply amino acid derivatives and specialty reagents to global CDMO networks.
Global Peptide Synthesis Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory access. The vendor base separates into tiered service providers differentiated by GMP certification depth and therapeutic specialization. Three archetypes dominate: integrated life science conglomerates with reagent-to-service workflows, pure-play CDMOs with geographic risk-diversification strategies, and research-grade specialists competing on synthesis turnaround velocity. Capacity expansion and strategic unbundling of synthesis from analytical services represent the dominant competitive moves reshaping procurement relationships.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. exemplifies reagent-to-service workflow consolidation across North America and Asia. Bachem Holding AG anchors European supply through large-scale GMP concentration in Swiss industrial corridors. GenScript Biotech Corporation occupies a position within the research-grade specialist archetype, competing on custom synthesis platform velocity for exploratory programs.
| Leading Market Players |
|---|
| PolyPeptide Group AG |
| AmbioPharm Inc. |
| Thermo Fisher Scientific Inc. |
| BioDuro LLC |
| Kaneka Corporation |
| Merck KGaA |
| GenScript Biotech Corporation |
| CEM Corporation |
| Bachem Holding AG |
| Others |
Supply & Pricing Matrix
GLP-1 receptor agonist procurement consolidation by biopharmaceutical majors is forcing CDMOs to absorb amino acid derivative volatility while maintaining fixed-price contract structures for multi-year manufacturing agreements.
Pricing Analysis
Non-natural amino acid cost pass-through from petroleum-linked feedstocks dominates contract renegotiation cycles between peptide developers and European specialty chemical suppliers. Pricing stratifies across GMP-certified commercial, research-grade, and exploratory tiers, with FDA-validated batches commanding substantial premiums over preclinical material. Cost compression in standard peptide segments is intensifying because Chinese manufacturers are capturing research-grade contracts through accelerated turnaround platforms. Academic institutes exhibit highest price sensitivity, while Swiss CDMO clusters serving parenteral peptide developers demonstrate lowest elasticity due to regulatory predictability premiums.
Supply Chain Analysis
China's NMPA ICH Q7 alignment is reshaping domestic-content qualification rules for export-bound therapeutic-grade peptides, compelling European CDMOs to establish joint-venture manufacturing within Chinese industrial zones. Controlled-pore glass and polystyrene resin production concentrates in Switzerland, Germany, and the United States, while amino acid derivative synthesis feeds from Indian and Chinese chemical manufacturing belts. Single-source resin vulnerability creates acute bottleneck exposure during demand surges for GLP-1 programs. Distribution runs through qualified supplier networks that unbundle synthesis, purification, and analytical services rather than traditional bundled CDMO packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in peptide synthesis rests on automation-driven cost reduction in solid-phase production and premium-tier capture in modified peptide modification expertise.
For Market Incumbents: Cement GMP capacity concentration in Swiss industrial corridors where Swissmedic regulatory predictability attracts parenteral peptide developers seeking geographic risk diversification. Lock in multi-year amino acid derivative supply agreements with European specialty chemical suppliers to insulate against petroleum feedstock volatility. Threat of Chinese manufacturers upgrading to ICH Q7 standards demands accelerated isolator retrofit investments ahead of EMA GMP Annex 1 closed-system mandates. For New Entrants and Emerging Players: Contract research organizations in the Yangtze River Delta represent the most penetrable channel partner type for research-grade synthesis platforms targeting academic and startup demand with sub-two-week turnaround velocities. White-space opportunity concentrates in personalized neoantigen peptide production where continuous flow microreactor technology enables just-in-time manufacturing for individualized cancer vaccines. Pursue platform-as-a-service positioning that eliminates capital-intensive in-house synthesis investments for grant-funded research laboratories. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play CDMOs possessing isolator-retrofitted solid-phase suites and established Swissmedic regulatory relationships. Long-term viability hinges on five-to-ten-year GLP-1 receptor agonist pipeline durability and metabolic disease therapeutic expansion beyond diabetes into obesity management. Acquisition target archetype: mid-scale European manufacturers with EMA GMP Annex 1 compliance completion and underutilized recombinant DNA capacity for longer peptide sequences. Watch for NMPA export qualification contract migration from European to Chinese manufacturers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Retrofit Investment | EMA GMP Annex 1 compliance secures parenteral peptide manufacturing access in European markets. |
| Continuous Flow Microreactor Deployment | Real-time analytical monitoring enables just-in-time production for personalized cancer vaccines. |
| ICH Q7 Standard Upgrade | NMPA alignment opens export qualification contracts previously held by Swiss and German CDMOs. |
| Multi-Sourced Manufacturing Contracting | Geographic risk diversification through Basel and Visp clusters reduces regulatory concentration exposure. |
| Automated Synthesizer Integration | Robotic workstations reduce manual intervention and free chemists for method development activities. |
Research Methodology
Direct dialogue with peptide development executives, CDMO procurement directors, regulatory affairs specialists, and academic principal investigators grounded qualitative insights in operational reality. Secondary validation drew from FDA peptide drug guidance documents, EMA GMP Annex 1 revision drafts, NMPA ICH Q7 implementation notices, and Swissmedic containment interpretation guidelines. Bottom-up capacity modeling across solid-phase and recombinant DNA technology platforms triangulated against top-down therapeutic pipeline analysis.
Bottom-up segmentation analysis tracked modified, standard, and large peptide categories across drug discovery, vaccine development, and diagnostic applications. Modeled dimensions spanned product type stability requirements, technology residue count thresholds, and end-user outsourcing maturity. CAGRs were derived from capacity expansion announcements, regulatory approval pathway velocities, and therapeutic pipeline progression rates across the analysis window. Forecast inputs incorporated GLP-1 program scale-up timelines and EMA closed-system mandate compliance capital requirements.
Revisions become necessary when FDA purity specification tightening accelerates beyond current endotoxin validation timelines, when Chinese ICH Q7 qualification achieves faster-than-anticipated European contract capture, or when petroleum feedstock volatility disrupts amino acid derivative supply contracts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Paraben Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
2-Propylheptanol Market