
 Paraformaldehyde Market | 2026-2036
Paraformaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Paraformaldehyde Market Analysis
Maintenance-linked technical service contracts is shifting how paraformaldehyde suppliers capture value beyond commodity sales. Celanese Corporation leverages its integrated acetyls chain to anchor methanol-to-formaldehyde economics across North American and European sites. MITSUBISHI GAS CHEMICAL COMPANY, INC. dominates high-purity grades for electronics and pharmaceutical applications through proprietary polymerization control. Ercros S.A. specializes in Southern European supply, operating chlor-alkali and derivatives complexes that sustain captive formaldehyde consumption.
Paraformaldehyde is a polymeric condensate of formaldehyde, typically containing 91–98% formaldehyde by weight with a degree of polymerization between 8 and 100 units, manufactured by vacuum evaporation and spray-drying of concentrated aqueous formaldehyde solutions. It serves as a solid, transportable source of formaldehyde for resin synthesis, chemical derivatization, and biological preservation where liquid formalin presents handling constraints. Granule and powder grades command structural priority in resin production applications, where controlled dissolution rates determine downstream reactivity and cure performance. Pharmaceutical and agrochemical end-user channels represent the fastest-expanding demand pools, driven by active ingredient synthesis and crop protection formulation requirements that specify low-metal, low-methanol specifications.
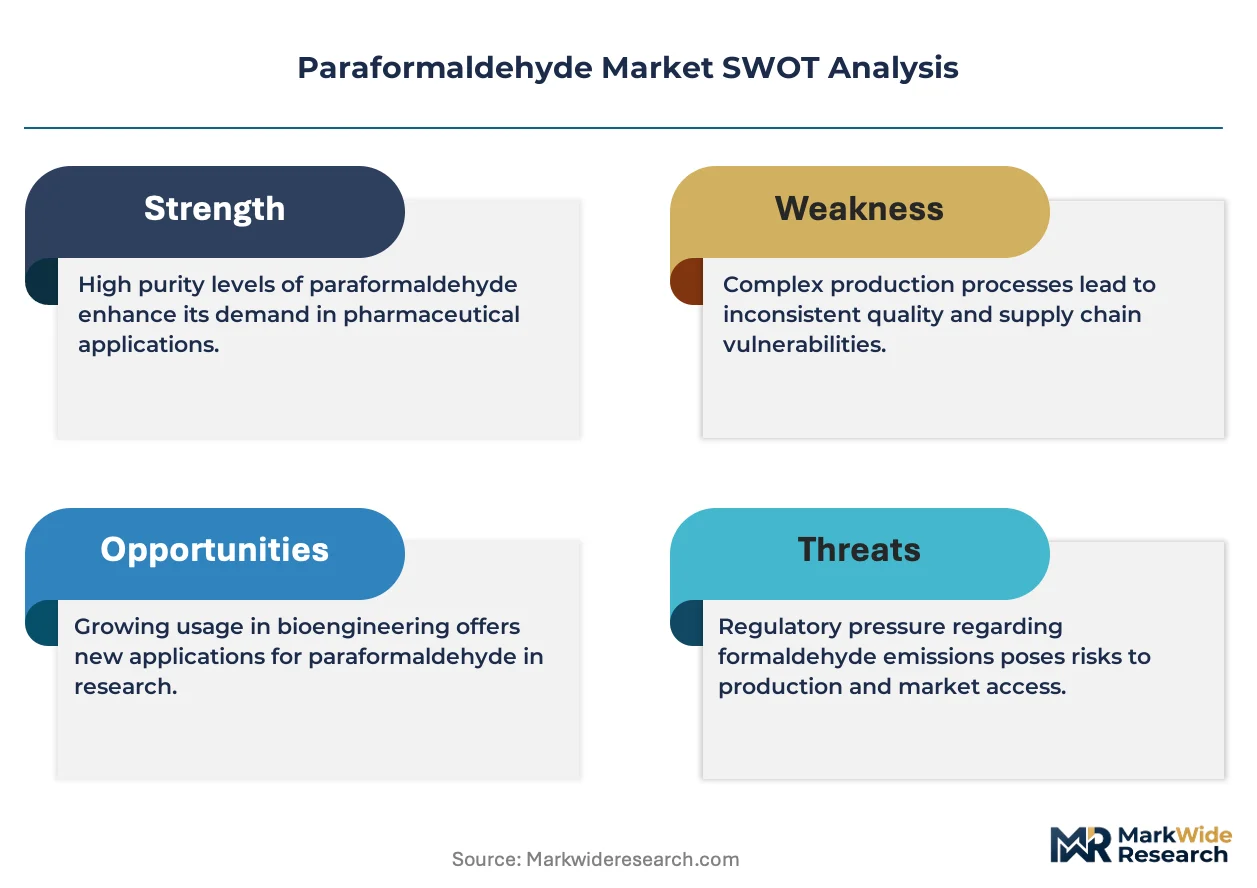
EPA formaldehyde emission standards for composite wood products and EU REACH restrictions on formaldehyde classification are reshaping product specifications and market access conditions for paraformaldehyde suppliers. China's MEE enforcement of GB standards on atmospheric formaldehyde limits is accelerating capital allocation toward low-emission process technologies. Stakeholders must monitor regulatory divergence between jurisdictions to determine where formulation-grade versus industrial-grade capacity investments align with emerging compliance thresholds.
Market Dynamics
China's MEE enforcement of GB atmospheric formaldehyde limits is compressing legacy capacity while redirecting investment toward low-emission polymerization technologies. This regulatory pressure is the dominant structural force reshaping competitive economics and geographic production allocation across the paraformaldehyde value chain.
Growth Catalysts
- Construction resin demand:Formaldehyde-based thermoset consumption in composite wood and automotive interiors is pulling volume through downstream derivative channels. Building codes in Germany and Japan specify phenolic resin content for fire-rated applications.
- REACH reclassification protocols:EU ECHA guidance on formaldehyde hazard communication is accelerating formulation-grade substitution toward controlled-release paraformaldehyde grades in adhesive applications.
- Agrochemical synthesis expansion:Crop protection active ingredient manufacturers in India and Brazil specify low-metal paraformaldehyde for glyphosate and triazole intermediate production.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings in North American and Middle Eastern methanol corridors transmit directly to formaldehyde cost structures.
- Supply concentration in East China:Shanghai-Ningbo chemical cluster dominance creates single-point vulnerability for global resin-grade availability.
- Aqueous formaldehyde substitution:Liquid formalin retains cost advantage in bulk resin applications where transport economics favor pipeline delivery.
Strategic Opportunities
- Southeast Asian capacity greenfield:Vietnam and Indonesia offer tariff-advantaged export platforms serving ASEAN composite wood manufacturing growth.
- Pharmaceutical-grade specification expansion:Low-methanol, low-acetaldehyde grades for parenteral excipient synthesis command 40-60% price premiums over industrial grades.
- EU Green Deal chemical transition:Biomass-derived methanol feedstock certification is creating preferential sourcing status for formaldehyde producers with mass-balance chain-of-custody documentation.
Industry Challenges
- Polymerization control engineering scarcity:Vacuum evaporation and spray-drying process optimization requires specialized chemical engineering talent concentrated in legacy formaldehyde production regions.
- Multi-jurisdiction emission compliance:Simultaneous EPA, REACH, and GB standard adherence demands parallel quality management system investments without harmonized testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraformaldehyde Market |
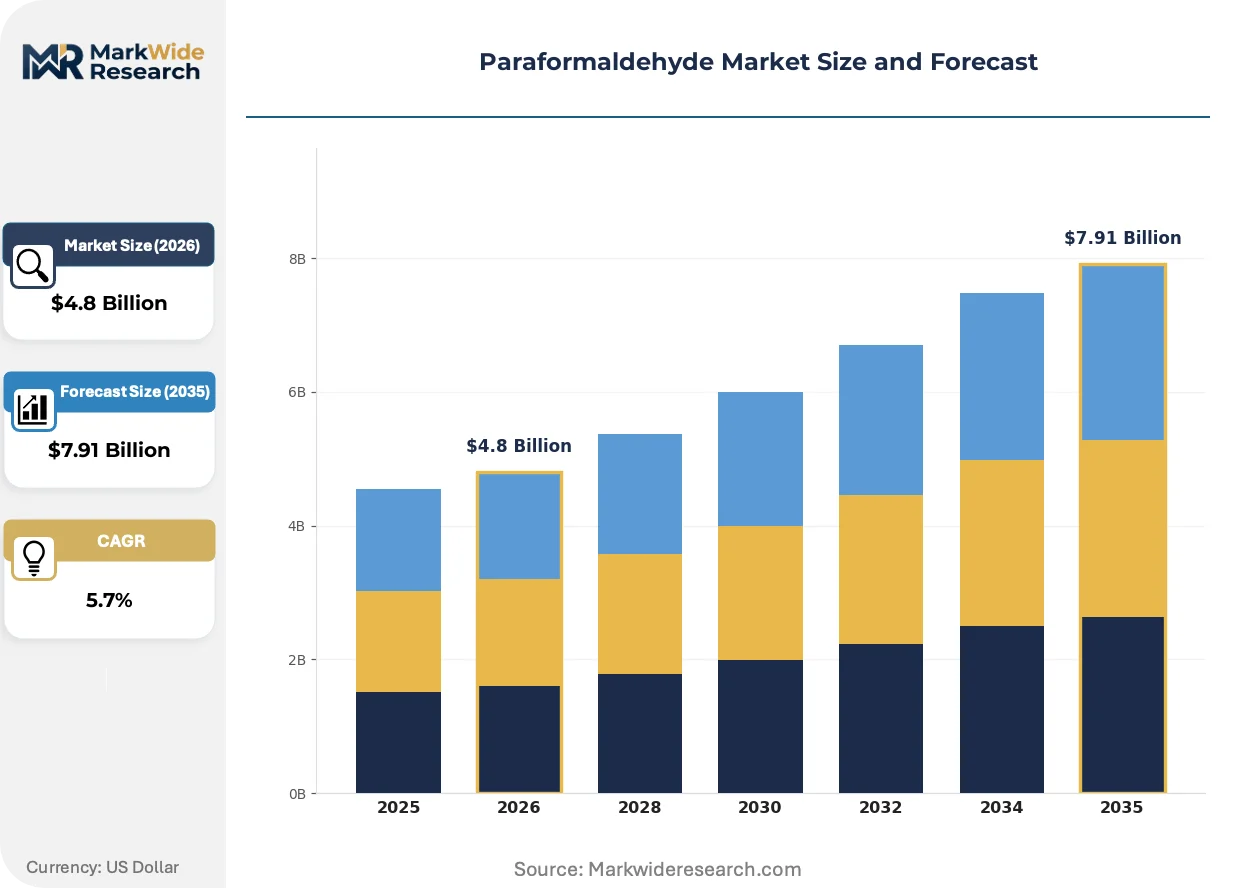
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Solution, Crystals Application: Resin Production, Laboratory Use, Fixative, Chemical Intermediates End User: Pharmaceuticals, Agrochemicals, Plastics, Biotechnology Packaging Type: Bags, Drums, Totes, Containers |
| Companies Covered | LCY Chemical Corp., MITSUBISHI GAS CHEMICAL COMPANY, INC., Ercros S.A., Changzhou Koye Chemical Co., Ltd., Nantong Jiangtian Chemical Co., Ltd., Celanese Corporation, Honeywell International Inc., Ekta International, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraformaldehyde Market Emerging Trajectories
Continuous polymerization reactor designs are compressing batch cycle times while improving molecular weight distribution control. These process intensification advances are reshaping capital efficiency thresholds and product consistency benchmarks across pharmaceutical and electronics-grade segments.
Membrane-based formaldehyde recovery systems are overtaking traditional vacuum distillation in new capacity installations. Pharmaceutical manufacturers in Switzerland and South Korea specify membrane-processed material for active ingredient synthesis due to superior methanol residual control. This technology compression is eroding the cost advantage of legacy Chinese batch producers in high-specification segments.
EPA formaldehyde emission standards for composite wood products are tightening test chamber protocols and deconstructing grandfathered certification pathways. Panel manufacturers in the US Southeast are reformulating toward paraformaldehyde-derived resins with lower free formaldehyde content to meet CARB ATCM and TSCA Title VI alignment requirements. This regulatory compression is accelerating substitution away from urea-formaldehyde toward phenol-formaldehyde and melamine-formaldehyde systems.
Resin compounders are consolidating procurement around annual framework contracts with dissolution-rate performance guarantees. Tier-1 automotive suppliers in Germany and Japan now specify cure kinetics parameters rather than basic purity metrics, shifting supplier qualification toward application-technical service capabilities. This specification evolution is visible most acutely in lightweight structural composite programs where batch-to-batch reactivity consistency determines manufacturing yield.
Paraformaldehyde Market Segmentation
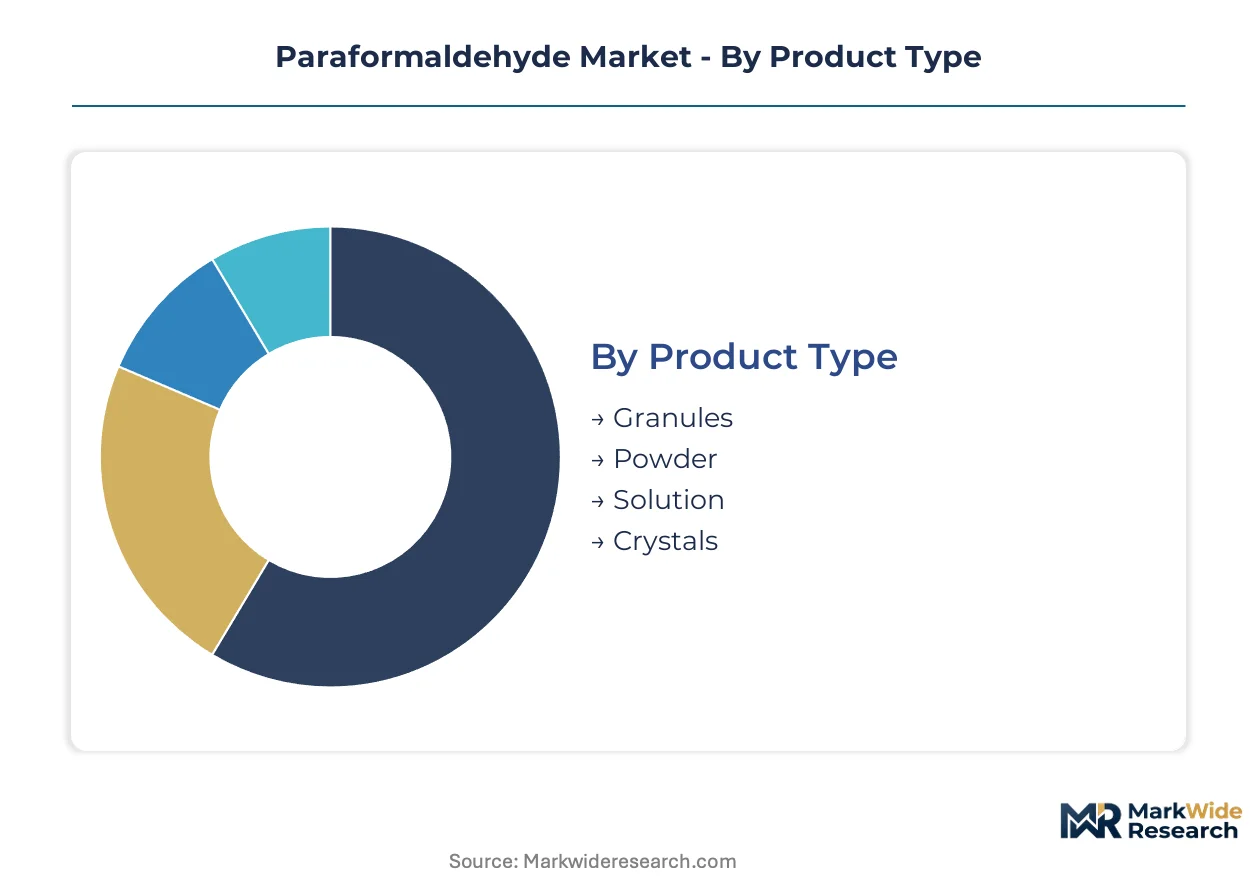
Paraformaldehyde specifications diverge sharply across end-use channels, with resin producers prioritizing dissolution kinetics while pharmaceutical buyers enforce tight methanol and metal limits. Segmentation discipline separates commodity-grade volume from premium-margin specialty positions.
Product Type:
Customization intensity spans controlled-release engineering for thermoset cure rates versus standardized bulk grades for general chemical synthesis.
- Granules:Spherical agglomerates with 91–95% formaldehyde content and engineered porosity for predictable dissolution profiles. Demand concentrates in German and Japanese automotive panel manufacturing where phenolic resin cure consistency determines lightweight composite yield.
- Powder:Fine particulate grades with higher surface area and faster rehydration kinetics. Chinese construction resin compounders in the Shanghai-Ningbo cluster specify powder grades for urea-formaldehyde adhesive production under tightening MEE emission enforcement.
- Solution:Pre-dispersed aqueous concentrates eliminating on-site dissolution equipment. Chemical intermediate manufacturers in India favor solution formats for continuous glyphosate synthesis processes.
- Crystals:High-purity monoclinic forms with minimal acetaldehyde carryover. Swiss and South Korean pharmaceutical API producers specify crystalline grades for parenteral excipient applications.
Leading the category by volume: Granules. Expanding most quickly: Crystals.
Application:
Volume concentration tracks construction sector formaldehyde thermoset consumption against precision-driven laboratory and preservation segments.
- Resin Production:Dominant consumption channel for phenol-formaldehyde, urea-formaldehyde, and melamine-formaldehyde thermoset synthesis. US Southeast panel manufacturers reformulate toward paraformaldehyde-derived resins to meet EPA TSCA Title VI and CARB ATCM alignment requirements for composite wood certification.
- Laboratory Use:Analytical-grade specifications for molecular biology and histology protocols. European research institutions specify low-metal, low-methanol grades under ECHA REACH hazard communication guidance.
- Fixative:Tissue preservation applications in pathology and embalming requiring controlled formaldehyde release. Brazilian and Mexican mortuary supply chains drive Latin American demand for standardized powder grades.
- Chemical Intermediates:Feedstock for pentaerythritol, hexamine, and trimethylolpropane synthesis. Indian agrochemical intermediate producers specify low-acetaldehyde grades for triazole fungicide manufacturing.
Highest volume share: Resin Production. Steepest expansion trajectory: Chemical Intermediates.
End User:
Margin structure inverts between price-sensitive agricultural chemical procurement and specification-captive pharmaceutical qualification.
- Pharmaceuticals:Parenteral drug formulation and active ingredient synthesis demanding GMP-compliant, low-impurity grades. Swissmedic and MFDS regulatory filings require comprehensive residual solvent documentation.
- Agrochemicals:Crop protection manufacturing with volume-scaled procurement and functional purity thresholds. Brazilian glyphosate and Indian triazole intermediate producers anchor regional demand concentration.
- Plastics:Thermoset molding compounds and composite matrix resins. German automotive Tier-1 suppliers specify cure kinetic parameters rather than basic purity metrics.
- Biotechnology:Cell culture and bioprocessing applications requiring endotoxin-controlled grades. South Korean CDMOs drive specification evolution for biologic manufacturing support.
Dominant by procurement volume: Agrochemicals. Gaining share fastest: Pharmaceuticals.
Packaging Type:
Logistics economics separate bulk industrial formats from contamination-controlled pharmaceutical configurations.
- Bags:Multi-wall paper or polyethylene configurations for 25–50 kg industrial distribution. Chinese resin compounders favor bagged granules for manual handling in smaller batch operations.
- Drums:Steel or fiber drums with liner systems for moisture protection. Standard format for European chemical intermediate producers requiring palletized unit loads.
- Totes:Intermediate bulk containers for high-volume automated handling. US and German phenolic resin manufacturers specify totes for continuous production line integration.
- Containers:Specialized formats including inert atmosphere purging for pharmaceutical and electronics grades. Swiss and Japanese high-purity distributors employ stainless steel containers with nitrogen blanketing.
Leading format by shipment volume: Drums. Climbing fastest: Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global paraformaldehyde output, yet consumption spreads across resin compounders in Germany, pharmaceutical formulators in Switzerland, and agrochemical intermediates producers in India. This geographic disconnect between production concentration and demand dispersion shapes trade flows and regulatory compliance investments.
China
Construction resin manufacturers in the Shanghai-Ningbo chemical cluster consume powder grades for urea-formaldehyde adhesive production. MEE enforcement of GB atmospheric formaldehyde limits is shuttering legacy batch capacity and redirecting investment toward low-emission polymerization technologies. East China chemical parks around Ningbo now require membrane-based formaldehyde recovery systems for new plant approvals.
Germany
Automotive Tier-1 suppliers specify phenolic resin cure kinetics for lightweight structural composites in electric vehicle programs. ECHA REACH reclassification protocols on formaldehyde hazard communication accelerate formulation-grade substitution toward controlled-release paraformaldehyde grades. Industrial concentration in North Rhine-Westphalia and Baden-Württemberg sustains demand for granule grades with engineered dissolution profiles.
United States
Panel manufacturers in the Southeast reformulate toward paraformaldehyde-derived resins to meet EPA TSCA Title VI and CARB ATCM alignment requirements for composite wood certification. EPA formaldehyde emission standards for composite wood products are tightening test chamber protocols and deconstructing grandfathered certification pathways. Texas and Louisiana host methanol-to-formaldehyde integrated complexes supplying regional resin compounders.
India
Agrochemical intermediate producers in Gujarat and Maharashtra specify low-metal paraformaldehyde for glyphosate and triazole fungicide manufacturing. CDSCO quality standards for pharmaceutical-grade imports enforce residual solvent documentation that favors certified low-methanol grades. Chemical synthesis clusters around Ahmedabad and Mumbai drive procurement volume for continuous process feedstock.
Switzerland
Pharmaceutical API manufacturers specify crystalline grades with minimal acetaldehyde carryover for parenteral excipient applications. Swissmedic regulatory filings require comprehensive residual solvent documentation that screens out standard industrial grades. Basel-area pharmaceutical chemistry operations anchor European demand for high-purity monoclinic crystal formats.
Paraformaldehyde Market Vendor Landscape
Top-tier vendors anchor integrated methanol-formaldehyde-paraformaldehyde chains, while mid-scale specialists occupy specification-captive niches. The market exhibits tiered concentration with three to four multinational chemical conglomerates commanding resin-grade volume and regional specialists capturing pharmaceutical and electronics-grade premiums. Strategic archetypes include backward-integrated petrochemical majors, chlor-alkali complex operators with captive formaldehyde consumption, and purity-focused fine chemical distributors. Dominant competitive moves center on membrane technology licensing for emission compliance and annual framework contracts with dissolution-rate performance guarantees.
Among integrated chemical producers, Celanese Corporation and MITSUBISHI GAS CHEMICAL COMPANY, INC. represent scale-driven archetypes with multinational production footprints, while Ercros S.A. exemplifies the regional complex operator model with Southern European supply concentration. These three entities occupy positions across distinct competitive tiers without overlapping strategic positioning.
| Leading Market Players |
|---|
| LCY Chemical Corp. |
| MITSUBISHI GAS CHEMICAL COMPANY, INC. |
| Ercros S.A. |
| Changzhou Koye Chemical Co., Ltd. |
| Nantong Jiangtian Chemical Co., Ltd. |
| Celanese Corporation |
| Honeywell International Inc. |
| Ekta International |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps across East China's chemical clusters anchor spot-market liquidity while state-backed petrochemical majors enforce contract discipline through methanol-formaldehyde integration. This ownership bifurcation concentrates pricing power among backward-integrated producers in Ningbo and Shanghai while fragmenting procurement leverage for resin compounders dependent on bagged powder grades.
Pricing Analysis
Margin tightening in pharmaceutical-grade crystals reflects membrane-processed material premiums and Swissmedic residual-solvent documentation requirements. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical grades from industrial resin grades and bulk chemical feedstock tiers. Price differentiation traces to methanol feedstock volatility in Middle Eastern corridors and MEE emission-compliance capital recovery in East China. Agrochemical intermediate buyers in Gujarat and Maharashtra exhibit highest price sensitivity, while Swiss parenteral excipient manufacturers accept substantial premiums for acetaldehyde-controlled crystalline specifications.
Supply Chain Analysis
Methanol supply rests on natural gas pricing in Qatar, Trinidad, and the US Gulf Coast, with formaldehyde conversion economics tethered to regional energy differentials. Paraformaldehyde output concentrates in China, Germany, and the United States, with vacuum evaporation and spray-drying capacity clustering around Shanghai-Ningbo, North Rhine-Westphalia, and Texas-Louisiana chemical corridors. Single-source vulnerability pervades East China's dominance in resin-grade powder production, where MEE enforcement is shuttering legacy batch capacity faster than membrane-technology replacements achieve commissioning. Distribution runs through drum and tote palletized unit loads for European and North American chemical intermediate producers, with nitrogen-blanketed stainless steel containers serving Swiss and Japanese pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE emission enforcement is compressing legacy capacity faster than replacement investments achieve regulatory approval, forcing sub-scale batch producers toward distressed exit or acquisition.
For Market Incumbents: Cement membrane-technology licensing advantages through exclusive regional distribution agreements with pharmaceutical-grade buyers in Basel and Seoul. Prioritize backward integration into methanol-formaldehyde economics across Texas and Louisiana sites to neutralize feedstock volatility transmission. Defend against aqueous formaldehyde substitution in bulk resin applications by embedding dissolution-rate performance guarantees into annual framework contracts with German automotive Tier-1 suppliers. For New Entrants and Emerging Players: The 40-60% price-point gap between pharmaceutical-grade crystals and industrial powder grades opens white-space entry for mid-purity agrochemical specifications in Vietnam and Indonesia. Target ASEAN composite wood manufacturing growth with tariff-advantaged greenfield capacity serving resin compounders in Ho Chi Minh City and Jakarta. Pursue EU Green Deal chemical transition certification with mass-balance chain-of-custody documentation to capture preferential sourcing status among sustainability-mandated European buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane-technology-equipped mid-caps in East China facing MEE compliance deadlines without capital access. Long-term viability centers on pharmaceutical-grade specification expansion where regulatory documentation barriers sustain margin premiums. Watch MEE approval velocity for new plant commissioning as inflection indicator for supply-side discipline restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Pharmaceutical manufacturers in Switzerland specify membrane-processed material for superior methanol residual control. |
| Backward Integration | Celanese leverages integrated acetyls chains to anchor methanol-to-formaldehyde economics across North American sites. |
| Green Manufacturing Transition | EU Green Deal biomass-derived methanol certification creates preferential sourcing for mass-balance documented producers. |
| Long-term Supply Agreement | German automotive Tier-1 suppliers consolidate procurement around annual framework contracts with cure kinetic guarantees. |
| Capacity Expansion | Vietnam and Indonesia offer tariff-advantaged export platforms serving ASEAN composite wood manufacturing growth. |
Methodological Framework
Independent corroboration across plant managers at formaldehyde derivative facilities, procurement leads at downstream resin compounders, and distribution channel partners in Shanghai-Ningbo underwrites the qualitative findings. Primary interviews with technical R&D directors at pharmaceutical API manufacturers and agrochemical intermediate producers combined with secondary validation from customs trade data, Cefic sector reports, and SEC 10-K disclosures from integrated chemical producers. Bottom-up capacity assessments and top-down consumption estimates triangulate volume figures across the analysis window.
Rate-of-change decomposition separates volume growth from price realization across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derive from segmented demand modeling incorporating construction sector formaldehyde thermoset consumption, pharmaceutical-grade specification expansion, and MEE-driven supply-side restructuring. Forecast inputs include methanol feedstock corridor pricing differentials, membrane technology adoption curves, and REACH reclassification protocol implementation timelines.
Underlying measurement precision varies by segment; pharmaceutical-grade crystals and granules carry tighter precision than commodity powder grades due to documented regulatory filings. Forecasts reflect assumptions on MEE enforcement consistency, EU Green Deal certification adoption rates, and membrane technology capital cost trajectories. A small set of triggers—including MEE approval velocity, German automotive lightweight composite program ramp rates, and Swissmedic documentation requirement revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Amino Acids Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Lauric Acid Market