
 Trimer Acid Market | 2026-2036
Trimer Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Trimer Acid Market Outlook
Petroleum-derived dimer acid is realigning toward renewable oleochemical precursors in trimer acid production, compressing carbon intensity metrics across supply chains. Croda International leverages backward integration into tropical oil feedstocks to secure cost-advantaged raw material flows. Kraton Corporation anchors its position through specialized hydrogenation capabilities that yield premium-grade trimer acid for polyamide hot-melt adhesives. Emery Oleochemicals competes on manufacturing scale, operating integrated oleochemical complexes that convert palm and palm kernel oils into tailored trimer acid specifications.
Trimer acid comprises a C54 tribasic acid synthesized via thermal oligomerization of unsaturated fatty acids, typically yielding products with acid values between 170-190 mg KOH/g and viscosities suited for polyamide resin synthesis. The substance functions primarily as a building block for non-reactive polyamide resins, corrosion inhibitors, and oilfield chemicals where thermal stability and flexibility govern performance. Liquid trimer acid dominates formulation flexibility in adhesive and coating applications, while bio-based trimer acid represents the fastest-expanding category as OEM sustainability mandates intensify procurement screening for renewable content. Modified trimer acid variants command margin premiums through customized functionality for epoxy curing agents and alkyd resin modifications.
EPA regulations under the Toxic Substances Control Act constrain manufacturing emissions from oleochemical thermal processing, while REACH registration requirements in Europe mandate full substance characterization for trimer acid imports above one tonne annually. OSHA process safety management standards govern reactor operations at US-based production facilities, influencing capital deployment decisions for capacity expansions. Stakeholders must monitor evolving biofuel tax credit structures and renewable chemical designation criteria, as these policy levers will determine relative economics between petroleum-derived and plant-based trimer acid pathways.
Market Dynamics
REACH registration mandates in Europe and EPA emissions controls in the United States are compressing manufacturing flexibility while accelerating capital flows toward bio-based oleochemical pathways. These regulatory pressures are restructuring procurement screening criteria across polyamide resin supply chains.
Growth Catalysts
- OEM Sustainability Mandates:Automotive and electronics manufacturers now enforce renewable content thresholds in adhesive specifications, pulling bio-based trimer acid into qualified supplier lists.
- REACH Compliance Deadlines:European substance characterization requirements above one tonne annually are filtering out unregistered imports, consolidating volume with compliant domestic and import suppliers.
- Specialty Chemical Cluster Expansion:Germany's Rhine-Main and Ruhr industrial corridors are scaling formulation R&D infrastructure for high-performance coatings and synthetic lubricants.
Market Restraints
- Tropical Oil Price Volatility:Palm and palm kernel oil feedstock costs fluctuate with Malaysian and Indonesian export duties, compressing margin predictability for integrated producers.
- Hydrogenation Capacity Concentration:Premium-grade trimer acid production requires specialized reactor infrastructure concentrated among a limited set of North American and European operators.
- Petroleum-Derived Dimer Acid Substitution:Lower-cost synthetic alternatives retain cost advantage in price-sensitive industrial adhesive segments where renewable content carries no procurement premium.
Strategic Opportunities
- India Industrial Adhesive Expansion:BIS certification pathways and PLI scheme incentives for domestic chemical manufacturing are opening qualified supplier positions for bio-based feedstock producers.
- Epoxy Curing Agent Applications:Modified trimer acid variants with customized functionality are penetrating aerospace and wind turbine composite manufacturing specifications.
- EU Green Deal Procurement Rules:Public tender environmental criteria are mandating renewable content in infrastructure coating projects across Germany, France, and the Netherlands.
Industry Challenges
- Reactor Safety Certification Timelines:OSHA process safety management compliance for thermal oligomerization expansion projects extends capital deployment cycles by 18-24 months.
- Feedstock Traceability Documentation:RSPO and ISCC certification requirements for palm-derived inputs are adding audit complexity and supplier qualification overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimer Acid Market |
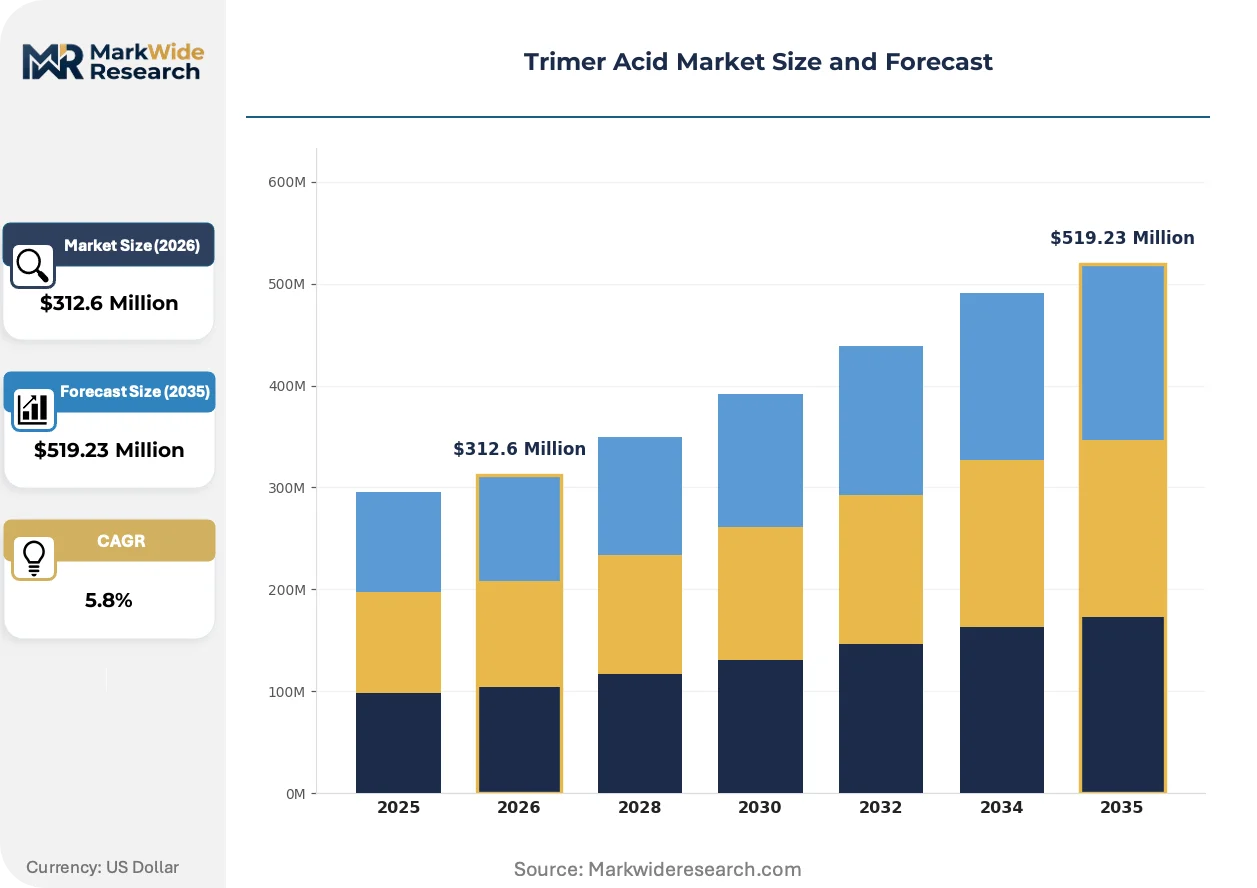
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Trimer Acid, Solid Trimer Acid, Modified Trimer Acid, Bio-based Trimer Acid Application: Adhesives, Coatings, Lubricants, Surfactants End Use Industry: Automotive, Construction, Pharmaceuticals, Chemicals Form: Pastes, Powders, Granules, Solutions |
| Companies Covered | Croda International, Kraton Corporation, Oleon NV, Florachem, Ingevity Corporation, Emery Oleochemicals, Harima Chemicals Group, WestRock Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimer Acid Market Strategic Shifts
Thermal oligomerization process intensification and downstream hydrogenation specialization are compressing unit economics while fragmenting competitive advantage between scale operators and functionality customizers.
Continuous-flow reactor technology is unifying temperature control precision with throughput scalability in trimer acid synthesis. Polyamide hot-melt adhesive manufacturers are adopting these systems at pilot scale in Germany and the United States. This convergence is unifying carbon intensity reduction targets with capital efficiency metrics, enabling smaller batch producers to meet OEM sustainability audits without integrated oleochemical complex investments.
EPA Toxic Substances Control Act enforcement is tightening emissions monitoring for thermal processing facilities above threshold throughput volumes. The industrial consequence is accelerating scrubber and thermal oxidizer retrofits at legacy production sites. Corrosion inhibitor and oilfield chemical segments are responding by consolidating procurement with operators holding verified EPA compliance histories.
Formulation laboratories are bundling technical service with resin specification development, displacing pure product sales in adhesive and coating channels. Automotive Tier 1 suppliers are the primary adopters, demanding application-specific viscosity and acid value tailoring. This service integration is most visible in Germany's specialty chemical clusters, where proximity to OEM technical centers enables rapid iteration cycles.
Trimer Acid Market Segmentation
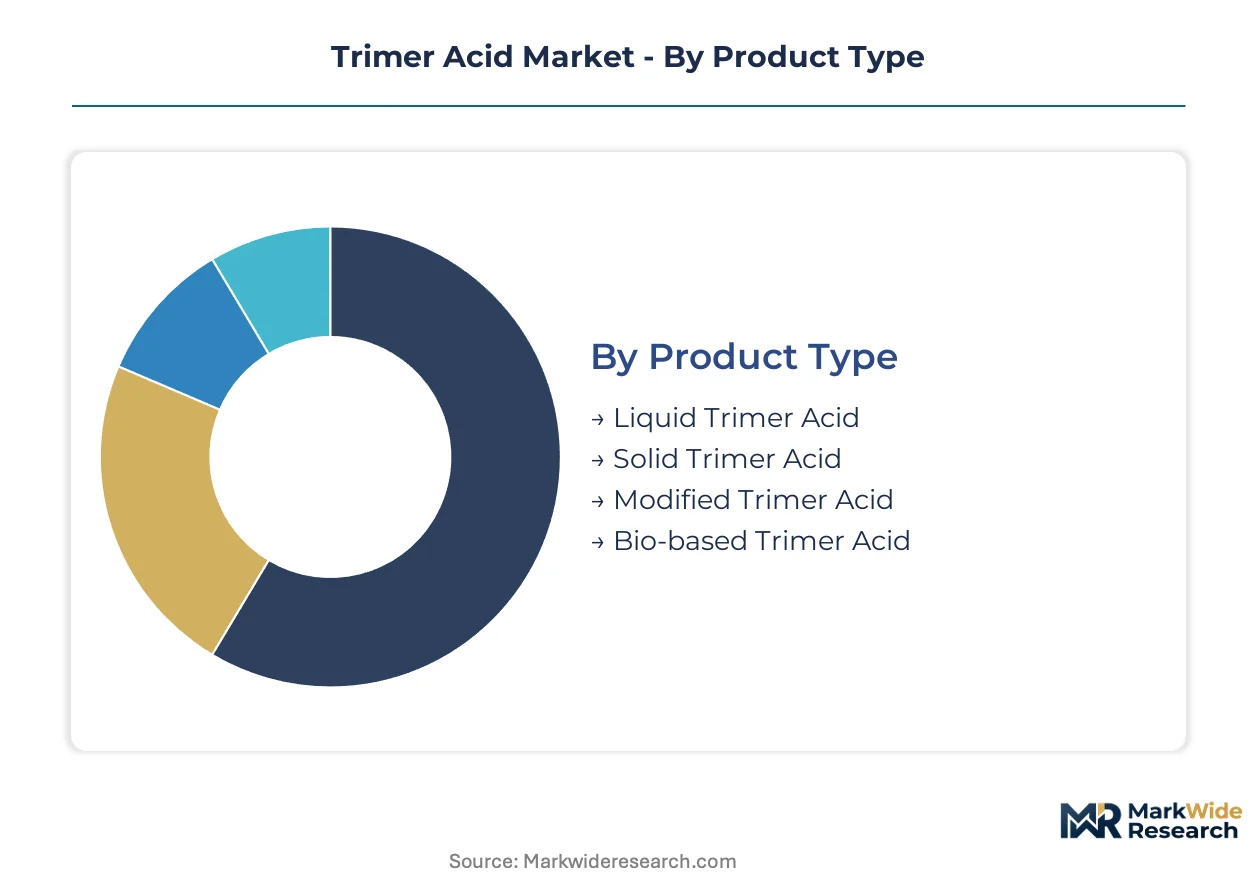
Trimer acid procurement decisions hinge on certification burdens that vary sharply across product grades and end-use specifications. REACH registration thresholds, bio-based content verification, and application-specific performance standards fragment supplier qualification pathways.
Product Type:
REACH substance characterization above one tonne annually applies universally, yet RSPO and ISCC certification burdens concentrate disproportionately on bio-based grades while modified variants face epoxy curing agent specification audits.
- Liquid Trimer Acid:Standard C54 tribasic acid with acid values between 170-190 mg KOH/g and optimized viscosity profiles for polyamide resin synthesis. Demand concentrates in Germany's Rhine-Main specialty chemical corridor where adhesive formulators require batch-to-batch consistency for automotive hot-melt specifications.
- Bio-based Trimer Acid:Synthesized from palm and palm kernel oil feedstocks through thermal oligomerization of unsaturated fatty acids. OEM sustainability mandates in automotive and electronics procurement are pulling this grade into qualified supplier lists fastest.
- Solid Trimer Acid:Hydrogenated variants with enhanced thermal stability for powder coating applications.
- Modified Trimer Acid:Functionality-customized specifications for epoxy curing agents and alkyd resin modifications commanding margin premiums.
Leading the category by volume: Liquid Trimer Acid. Growing fastest: Bio-based Trimer Acid.
Application:
Cost tier stratification separates premium specification adhesives from commodity lubricant additives, with coatings occupying the intermediate margin band.
- Adhesives:Polyamide hot-melt formulations dominate consumption, with automotive Tier 1 suppliers in Germany demanding application-specific viscosity tailoring. Continuous-flow reactor adoption at pilot scale is unifying carbon intensity targets with capital efficiency metrics for adhesive-grade producers.
- Coatings:Corrosion inhibitor and oilfield chemical segments are consolidating procurement with operators holding verified EPA compliance histories. EU Green Deal procurement rules are mandating renewable content in infrastructure coating projects.
- Lubricants:Synthetic lubricant R&D infrastructure scaling in Germany's Ruhr corridor drives formulation innovation.
- Surfactants:Niche applications in industrial cleaning and personal care formulations.
Highest margin capture: Adhesives. Steepest volume expansion: Coatings.
End Use Industry:
Customer type fragmentation pits OEM direct procurement against distributor-mediated sales, with automotive and construction representing opposing qualification timelines.
- Automotive:OEM sustainability mandates enforce renewable content thresholds in adhesive specifications, compressing supplier lists to bio-capable producers. Tier 1 technical centers in Germany enable rapid formulation iteration cycles.
- Construction:Price-sensitive industrial adhesive segments where petroleum-derived dimer acid substitution retains cost advantage.
- Pharmaceuticals:Stringent purity requirements limit qualified supplier pools.
- Chemicals:Intermediate demand from corrosion inhibitor and oilfield chemical manufacturers.
Deepest supplier consolidation: Automotive. Longest sales cycles: Pharmaceuticals.
Form:
Supply concentration in hydrogenation capacity favors pastes and solutions, while powder processing requires specialized micronization infrastructure.
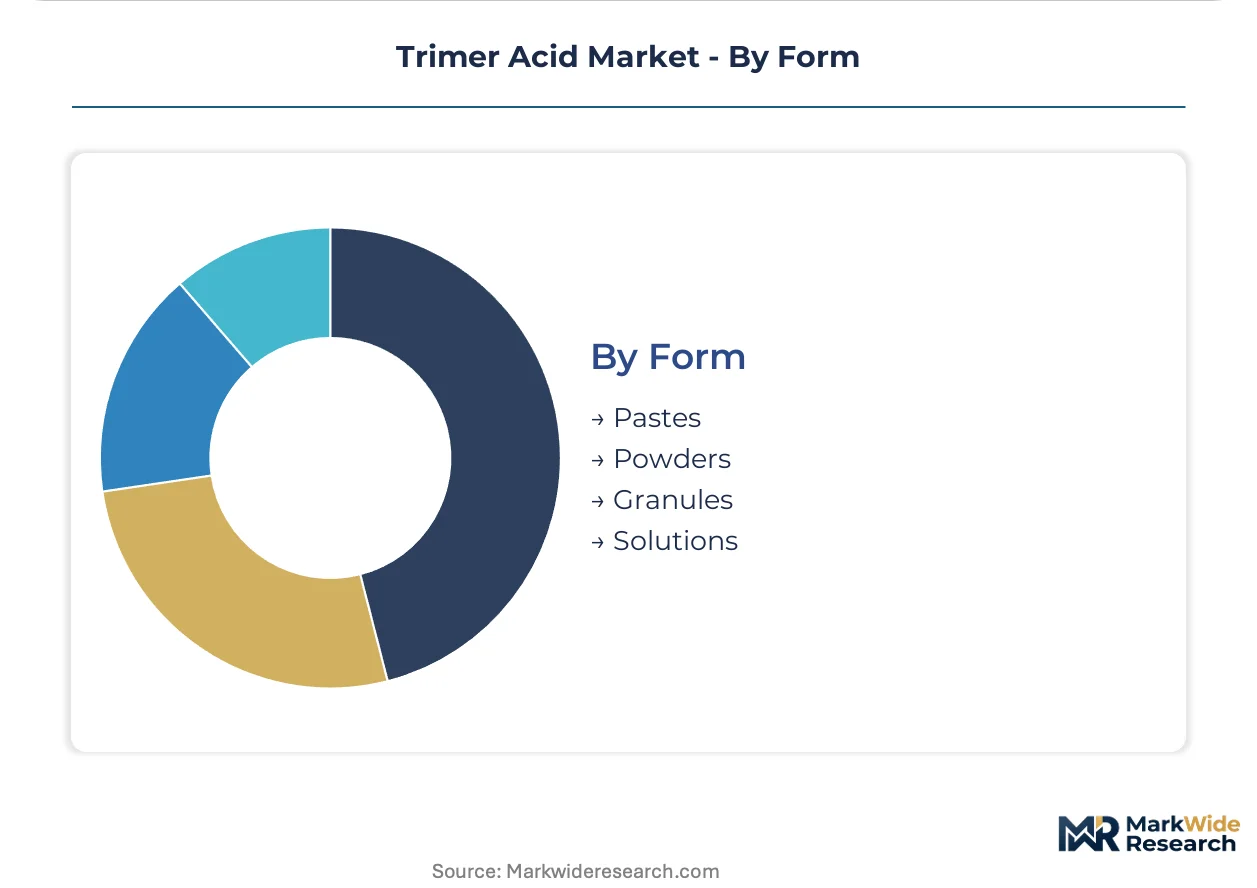
- Pastes:Semi-solid formulations for direct adhesive compounding.
- Solutions:Solvent-dispersed grades for coating application systems.
- Powders:Micronized specifications for powder coating and dry blend applications.
- Granules:Intermediate processing form for downstream hydrogenation.
Widest application flexibility: Solutions. Tightest processing requirements: Powders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical clusters in Germany concentrate the highest formulation innovation intensity for trimer acid applications, while procurement screening for renewable content is tightening fastest across automotive supply chains in the United States and China.
Germany
Polyamide hot-melt adhesive specifications from automotive Tier 1 suppliers are concentrating demand in the Rhine-Main and Ruhr corridors. REACH substance characterization mandates above one tonne annually filter unregistered imports, consolidating volume with compliant domestic producers. BASF SE and specialty chemical formulators in Ludwigshafen and Leverkusen are scaling R&D infrastructure for high-performance coatings.
United States
EPA Toxic Substances Control Act enforcement is tightening emissions monitoring for thermal oligomerization facilities above threshold volumes. OSHA process safety management standards extend capital deployment cycles for reactor expansions by 18-24 months. Kraton Corporation anchors hydrogenation capabilities in the Gulf Coast region for premium-grade trimer acid production.
China
Dual carbon goals and MIIT industrial policy are accelerating oleochemical complex investments for bio-based feedstock processing. GB standards for chemical manufacturing emissions are compressing flexibility at legacy thermal processing sites. Zhejiang and Jiangsu province chemical parks are integrating palm oil derivative processing with downstream polyamide resin synthesis.
India
BIS certification pathways and PLI scheme incentives for domestic chemical manufacturing are opening qualified supplier positions for bio-based feedstock producers. DGFT import regulations on oleochemical derivatives are shifting procurement toward local thermal oligomerization capacity. Maharashtra and Gujarat industrial corridors are scaling adhesive formulation infrastructure for construction and automotive applications.
Japan
METI industrial decarbonization targets are pulling renewable content thresholds into electronics and automotive adhesive specifications. JIS standards for chemical substance characterization align with REACH-equivalent documentation burdens for imported trimer acid above volume thresholds. Osaka-based chemical traders are consolidating procurement with RSPO-certified palm derivative suppliers.
Trimer Acid Market Competitive Environment
Capacity expansion dominates the current landscape as integrated oleochemical producers retrofit thermal oligomerization lines for bio-based feedstock processing. The vendor base stratifies between scale-driven tropical oil processors and hydrogenation specialists commanding premium-grade positions. Three archetypes define competitive positioning: backward-integrated palm oil processors, specialized hydrogenation technology holders, and formulation-integrated resin suppliers. M&A activity concentrates on securing RSPO-certified feedstock traceability, while strategic partnerships between adhesive formulators and oleochemical producers are displacing spot-market procurement.
Among European-based integrated producers, Croda International exemplifies the backward-integrated archetype through captive tropical oil sourcing, while Oleon NV occupies a position within the scale-driven processing tier. Kraton Corporation represents the hydrogenation specialization vector, anchoring premium-grade production capabilities for polyamide hot-melt specifications. These three entities collectively illustrate how competitive advantage fragments between feedstock control, process technology, and downstream formulation integration.
| Leading Market Players |
|---|
| Croda International |
| Kraton Corporation |
| Oleon NV |
| Florachem |
| Ingevity Corporation |
| Emery Oleochemicals |
| Harima Chemicals Group |
| WestRock Company |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Malaysian palm oil futures and Indonesian export duty schedules cascade through integrated oleochemical complexes into three distinct pricing tiers for trimer acid procurement. Feedstock cost volatility compresses margin predictability for bio-based grades while hydrogenation specialists capture premium positioning through technical specification control.
Pricing Analysis
Volume-mass commodity spot contracts anchor the economy tier for construction adhesive applications where petroleum-derived dimer acid substitutes retain cost advantage. Premium-grade specifications for automotive hot-melt polyamides command substantial markups through REACH registration and RSPO certification bundling. Cost compression in standard liquid grades is intensifying as tropical oil price swings transmit directly into formulation costs. Construction sector buyers exhibit highest price sensitivity, while automotive Tier 1 suppliers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore coordinate hub-and-spoke flows from integrated oleochemical complexes to downstream adhesive formulators. Manufacturing concentrates in Malaysia, Indonesia, and Germany where thermal oligomerization capacity clusters near palm derivative processing infrastructure. Raw material flows draw from crude palm oil, palm kernel oil, and tall oil fatty acid streams. Single-source vulnerability concentrates around Malaysian export duty policy shifts. Distribution runs through chemical distributor networks with direct OEM relationships for premium grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trimer acid supply chains are consolidating as REACH registration burdens and hydrogenation capacity scarcity force sub-scale operators toward exit. Regulatory compliance costs function as the primary consolidation mechanism.
For Market Incumbents: Anchor hydrogenation specialization through reactor safety certification investments that extend EPA compliance histories. Secure RSPO-certified feedstock traceability via backward integration into tropical oil sourcing or long-term offtake agreements with Malaysian and Indonesian processors. Capacity expansion in India's Maharashtra and Gujarat corridors captures PLI scheme incentives while building qualified supplier positions for emerging automotive adhesive demand. For New Entrants and Emerging Players: Launch via continuous-flow reactor technology partnerships that bypass integrated oleochemical complex capital requirements. Target India's BIS certification pathways where domestic thermal oligomerization capacity remains underdeveloped relative to downstream adhesive formulation growth. Penetrate epoxy curing agent applications for aerospace and wind turbine composites where modified trimer acid functionality commands margin premiums with limited incumbent specialization. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydrogenation-specialized mid-cap producers in Germany and the United States where OSHA compliance timelines have stalled expansion projects. Long-term viability hinges on bio-based pathway economics converging with petroleum-derived alternatives. Watch for EU Green Deal procurement rule enforcement intensity as the inflection signal for renewable content premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Croda International's tropical oil sourcing secures cost-advantaged raw material flows against Malaysian export volatility. |
| Hydrogenation Capacity Expansion | Kraton Corporation's specialized reactor infrastructure yields premium-grade specifications for automotive hot-melt adhesives. |
| Continuous-Flow Reactor Adoption | German pilot-scale installations unify carbon intensity targets with capital efficiency for smaller batch producers. |
| RSPO Certification Investment | Emery Oleochemicals' integrated complexes convert certified palm oils into tailored specifications with full traceability documentation. |
| Formulation Technical Service Integration | BASF SE's Ludwigshafen laboratories bundle resin specification development with product supply for Tier 1 automotive suppliers. |
Study Parameters
Independent corroboration across customs trade databases, SEC chemical sector filings, and European oleochemical association reports underwrites the qualitative findings in this study. Primary interviews with plant managers at integrated oleochemical complexes, procurement leads at automotive Tier 1 adhesive formulators, distribution channel partners in specialty chemical corridors, and technical R&D directors for polyamide resin applications were combined with secondary validation from ECHA REACH registration databases, Malaysian Palm Oil Board export statistics, and EPA Toxic Substances Control Act enforcement records. Bottom-up volume triangulation against top-down value estimates was applied across all segmentation dimensions.
Comparable historical reference periods anchored the projection horizon to observed capacity utilization, feedstock cost transmission patterns, and regulatory implementation timelines. The analytical framework modeled product grade tiers, end-use industry applications, and regional production hub configurations throughout the forecast period. CAGRs were derived from segment-level demand elasticity analysis and supply-side capacity expansion schedules. Forecast inputs incorporated REACH registration compliance rates, tropical oil price volatility indices, and OEM renewable content mandate adoption curves.
Feedstock price regime shifts, regulatory enforcement intensity variations, and hydrogenation capacity addition delays are the dominant revision risks to the projections presented. Forecasts reflect documented assumptions regarding bio-based pathway cost convergence and certification burden trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Serine Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Citrate Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Global Sodium Lignosulfonate Market