
 Sodium Lauroyl Glutamate Market | 2026-2036
Sodium Lauroyl Glutamate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Lauroyl Glutamate Market Insights
Clean-label cosmetic brands is bifurcating demand away from conventional petrochemical surfactants toward plant-derived alternatives. Ajinomoto Co., Inc. leverages its fermentation expertise to anchor supply of amino acid-based surfactants for premium skincare lines. BASF SE competes through integrated oleochemical networks that sustain cost advantages across European and Asian production hubs. Galaxy Surfactants Ltd. specializes in surfactant exports to emerging cosmetic manufacturers in South Asia and the Middle East.
Sodium lauroyl glutamate is an anionic surfactant synthesized from L-glutamic acid and lauric acid, typically exhibiting a pH range of 5.0-7.0 in aqueous solution and functioning as a mild cleansing agent with low irritation potential for skin and eye contact. Its primary commercial purpose centers on replacing sulfate-based surfactants in personal care formulations where dermatological tolerance and biodegradability are specified. Powdered grades command premium positioning within cosmetics applications due to extended shelf stability and precise dosing control in dry-blend manufacturing. Liquid formulations dominate pharmaceutical and food additive applications where rapid dispersion into aqueous systems is required. Surfactant formulations lead volume consumption across end users, while emulsifier applications in natural cosmetics represent the fastest-expanding margin pool.
REACH registration through ECHA governs surfactant purity and ecotoxicology profiles for European market access, while FDA cosmetic ingredient regulations under the Modernization of Cosmetics Regulation Act establish traceability requirements for U.S. distribution. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols that shape export qualification timelines. Stakeholders must monitor evolving biobased content certification schemes and regional allergen labeling mandates to preserve formulation flexibility across jurisdictions.
Market Dynamics
Clean-label cosmetic procurement is bifurcating demand away from petrochemical surfactants toward amino acid-derived alternatives, with sulfate-free formulation mandates from major personal care brands reshaping supplier qualification criteria.
Growth Catalysts
- REACH compliance thresholds:ECHA registration requirements for surfactant purity and ecotoxicology profiles are accelerating substitution of conventional sulfates in European cosmetic formulations.
- China's domestic surfactant scaling:NMPA-aligned producers are expanding fermentation-derived output for both local consumption and export qualification to ASEAN markets.
- Fermentation process optimization:Biocatalytic production routes for L-glutamic acid precursors are reducing input costs and improving batch consistency for cosmetic-grade material.
Market Restraints
- Lauric acid price volatility:Crude palm kernel oil and coconut oil feedstock fluctuations compress margin stability for producers without backward integration into oleochemical supply.
- Chinese supply concentration:Domestic fermentation capacity for amino acid surfactants clusters in coastal provinces, creating geographic exposure to regional energy and logistics disruptions.
- Performance limitations in hard water:Calcium and magnesium ion sensitivity reduces foam stability compared to sulfate alternatives, restricting application in certain rinse-off formulations.
Strategic Opportunities
- India's emerging cosmetic manufacturing:CDSCO-aligned domestic brands are qualifying new surfactant suppliers for sulfate-free skincare lines targeting middle-class consumers.
- Pharmaceutical-grade emulsifier demand:Injectable and topical drug delivery systems specify ultra-pure amino acid surfactants with documented endotoxin profiles.
- EU Green Deal biobased mandates:Certification schemes for renewable carbon content create preferential procurement channels for fermentation-derived versus petrochemical alternatives.
Industry Challenges
- Multi-jurisdiction dossier compilation:Concurrent REACH, FDA MoCRA, and NMPA registration timelines strain regulatory affairs capacity at mid-scale producers.
- Biocatalyst scale-up expertise:Fermentation process engineers with amino acid surfactant specialization remain concentrated at established Japanese and European producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Lauroyl Glutamate Market |
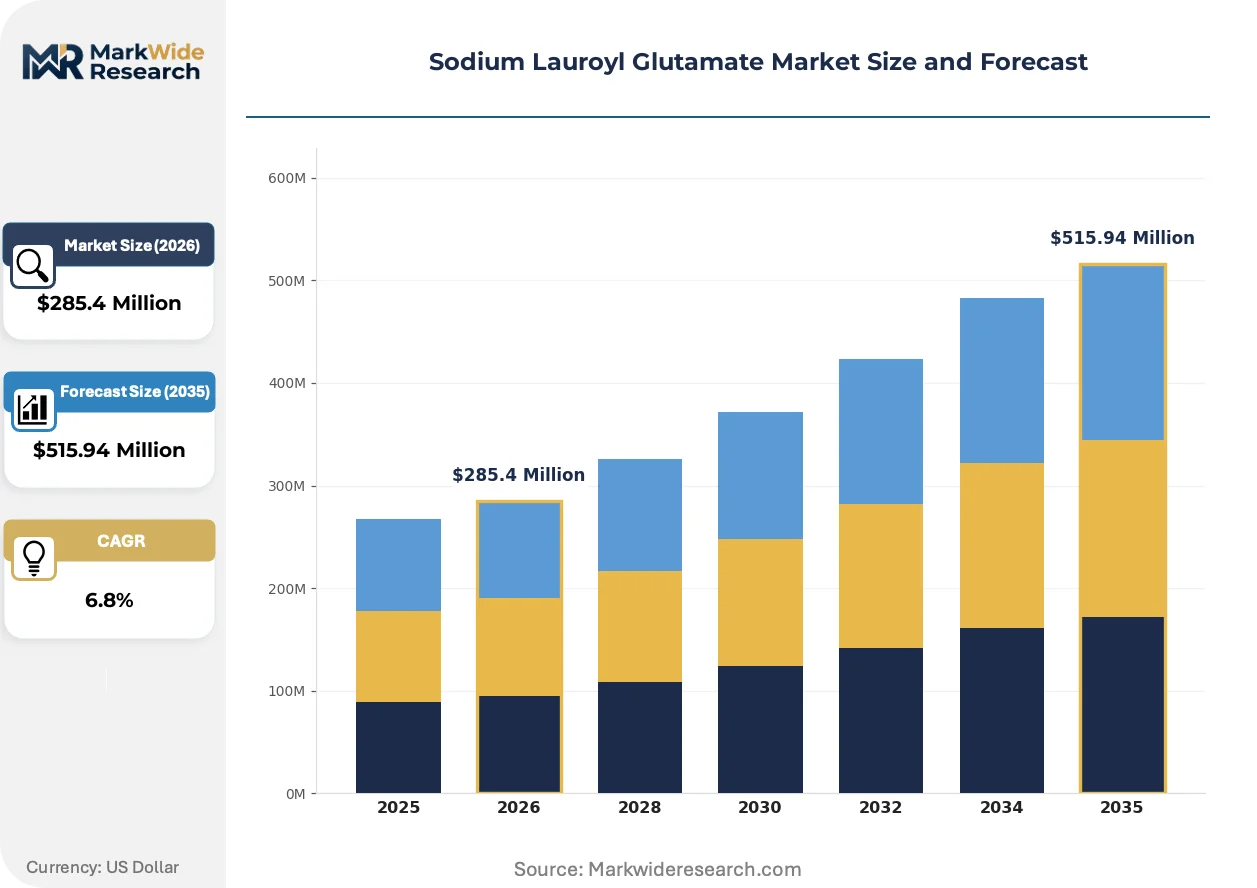
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Powdered, Liquid, Granules Application: Cosmetics, Food Additive, Pharmaceuticals, Personal Care Formulation: Emulsifiers, Surfactants, Stabilizers, Thickening Agents End User: Cosmetic Manufacturers, Food Producers, Pharmaceutical Companies, Private Label Brands |
| Companies Covered | BASF SE, Croda International, Evonik Industries, Symrise, Ajinomoto Co., Inc., Clariant, Stepan Company, Lubrizol, Galaxy Surfactants Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Lauroyl Glutamate Market Trends and Innovations
Enzymatic synthesis routes and biobased certification schemes are redefining competitive positioning, while procurement models evolve toward direct supplier partnerships that bypass traditional distributor networks.
Continuous enzymatic transesterification for sodium lauroyl glutamate production is decomposing batch-reactor economics that have dominated amino acid surfactant manufacturing for decades. Premium skincare brands in South Korea and Japan are qualifying output from these systems for 2025 formulation cycles. The technology is decomposing capital barriers that previously constrained entry by specialized fermentation houses.
REACH registration dossier requirements for chronic aquatic toxicity and biodegradability endpoints are extending qualification timelines for new surfactant suppliers seeking European market access. ECHA's 2024 updated guidance on UVCB substance identification creates additional analytical burden for plant-derived feedstock variants. Cosmetic formulators with established supplier relationships are locking in multi-year contracts to preempt supply uncertainty.
Direct procurement contracts between surfactant producers and finished goods manufacturers are displacing regional distributor networks that historically managed inventory and technical service. Large personal care conglomerates in Germany and France are establishing supplier development programs with fermentation specialists. This channel compression is most visible in premium skincare segments where formulation IP protection and supply traceability carry priority over transactional purchasing efficiency.
Sodium Lauroyl Glutamate Market Segmentation
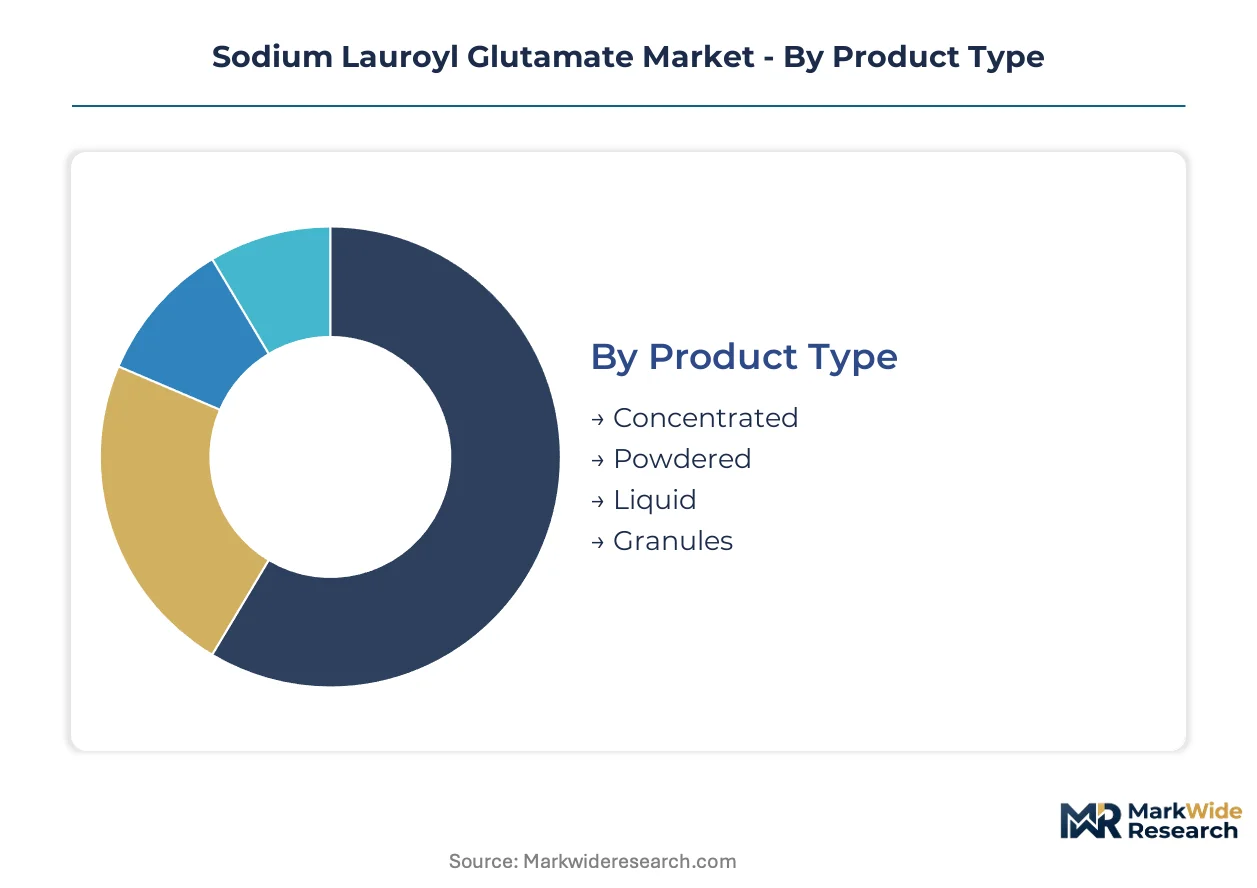
Segmentation in the sodium lauroyl glutamate market reveals how margin pools concentrate in premium-grade formats and sulfate-free cosmetic applications. Manufacturers optimize production configurations around formulation flexibility, regulatory compliance burdens, and end-user technical service requirements.
Product Type:
Powdered grades capture the widest margin expansion as cosmetic brands prioritize shelf stability and precise dry-blend dosing control.
- Concentrated:High-active-content solutions reduce shipping volumes for large-scale cosmetic manufacturers. Demand clusters with multinational personal care conglomerates in Germany and France seeking to minimize inbound logistics costs.
- Powdered:Extended shelf stability and precise dosing control command premium positioning in premium skincare manufacturing. South Korean and Japanese brands are qualifying powdered grades for 2025 formulation cycles.
- Liquid:Rapid dispersion into aqueous systems dominates pharmaceutical and food additive procurement.
- Granules:Intermediate handling characteristics serve regional compounders lacking sophisticated powder handling infrastructure.
The dominant share belongs to Powdered, while Concentrated is closing the gap fastest through logistics optimization contracts.
Application:
Volume concentration tracks sulfate-free formulation mandates from major personal care brands.
- Cosmetics:Sulfate-free skincare and color cosmetics specify amino acid surfactants for dermatological tolerance. REACH registration dossiers for chronic aquatic toxicity extend qualification timelines for new European suppliers.
- Personal Care:Shampoo and body wash formulations leverage mild cleansing profiles with low eye irritation potential. China's NMPA-aligned producers are scaling fermentation-derived output for ASEAN export qualification.
- Food Additive:Emulsifier applications in processed foods require FSSAI or FDA food-grade certification.
- Pharmaceuticals:Injectable and topical drug delivery systems demand ultra-pure grades with documented endotoxin profiles.
Cosmetics holds the dominant position, though Pharmaceuticals is climbing the fastest on purity premium capture.
Formulation:
Functional role determines pricing tier and technical service intensity.
- Surfactants:Primary cleansing function in rinse-off formulations generates the largest volume consumption. Calcium and magnesium ion sensitivity restricts application in certain hard-water formulations.
- Emulsifiers:Natural cosmetics applications represent the steepest expansion trajectory for margin pool growth. EU Green Deal biobased certification schemes create preferential procurement channels.
- Stabilizers:Formulation integrity maintenance commands mid-tier pricing in multi-phase cosmetic systems.
- Thickening Agents:Rheology modification serves secondary functional roles with lower active loading requirements.
Surfactants maintains dominant share, while Emulsifiers is gaining share fastest on natural cosmetics qualification.
End User:
Procurement sophistication separates direct technical partnerships from transactional purchasing.
- Cosmetic Manufacturers:Direct supplier development programs with fermentation specialists are displacing regional distributor networks. Large German and French conglomerates prioritize formulation IP protection and supply traceability.
- Private Label Brands:Cost-competitive sourcing through distributor channels dominates mass-market positioning.
- Food Producers:FSSAI and FDA compliance documentation requirements shape supplier qualification timelines.
- Pharmaceutical Companies:CDSCO-aligned domestic brands in India are qualifying new suppliers for sulfate-free lines.
Cosmetic Manufacturers command the dominant share, while Pharmaceutical Companies is expanding most quickly on purity specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetic brands in South Korea and Japan are driving amino acid surfactant procurement for sulfate-free skincare lines. Chinese fermentation houses are scaling output for both domestic NMPA compliance and ASEAN export qualification. European REACH dossier requirements are extending supplier timelines for chronic aquatic toxicity documentation.
China
Domestic surfactant producers in Jiangsu and Zhejiang provinces are expanding fermentation-derived capacity for local cosmetic manufacturers. NMPA-aligned GB standards for cosmetic raw materials impose additional testing protocols that shape export qualification timelines to Southeast Asian markets. The Yangtze River Delta cluster anchors both production scale and technical service capabilities for amino acid surfactant supply.
South Korea
Seoul-based skincare conglomerates are qualifying powdered-grade sodium lauroyl glutamate for 2025 formulation cycles targeting dermatological tolerance. MFDS cosmetic ingredient regulations establish traceability requirements that favor established supplier relationships over transactional sourcing. The Gyeonggi-do province concentration of contract manufacturers is driving direct procurement partnerships with fermentation specialists.
Germany
Personal care conglomerates in Hamburg and Düsseldorf are locking in multi-year surfactant contracts to preempt REACH registration uncertainty. ECHA's 2024 updated guidance on UVCB substance identification creates additional analytical burden for plant-derived feedstock variants. The North Rhine-Westphalia chemical corridor sustains integrated oleochemical networks that support cost advantages in amino acid surfactant production.
United States
Clean-label cosmetic brands are expanding procurement of amino acid-derived surfactants following FDA MoCRA implementation. The Modernization of Cosmetics Regulation Act establishes traceability requirements that reshape supplier qualification criteria for domestic distribution. New Jersey and California formulation hubs are prioritizing supply relationships with documented endotoxin profiles for premium skincare applications.
India
CDSCO-aligned domestic brands in Maharashtra and Gujarat are qualifying new surfactant suppliers for sulfate-free lines targeting middle-class consumers. FSSAI food-grade certification requirements shape supplier timelines for emulsifier applications in processed foods. The Mumbai-Pune industrial corridor is emerging as a procurement destination for fermentation-derived surfactants serving both cosmetic and pharmaceutical end users.
Sodium Lauroyl Glutamate Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with fermentation expertise and specialized surfactant houses. Market structure concentrates around three strategic archetypes: integrated oleochemical majors leveraging backward feedstock control, Japanese fermentation specialists with amino acid process heritage, and regional surfactant exporters serving emerging cosmetic manufacturers. Dominant competitive moves include direct supplier development programs bypassing distributor networks and enzymatic synthesis licensing to decompose batch-reactor capital barriers.
Within the fermentation-specialist tier, Ajinomoto Co., Inc. and BASF SE exemplify contrasting strategic positions. Ajinomoto anchors amino acid surfactant supply through biocatalytic production heritage. BASF occupies a position supported by integrated European and Asian oleochemical networks. Galaxy Surfactants Ltd. represents the regional-export archetype, with Mumbai-based operations serving South Asian and Middle Eastern cosmetic manufacturers. These three entities collectively illustrate the competitive vectors of process technology, feedstock integration, and geographic specialization.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Evonik Industries |
| Symrise |
| Ajinomoto Co., Inc. |
| Clariant |
| Stepan Company |
| Lubrizol |
| Galaxy Surfactants Ltd. |
| Others |
Pricing and Supply Chain Analysis
REACH registration dossiers for chronic aquatic toxicity and biodegradability endpoints simultaneously gate European market access and stratify supplier pricing tiers, with ECHA-compliant producers commanding substantial premiums over non-registered alternatives while buyers absorb extended qualification timelines as embedded cost.
Pricing Analysis
Cost-plus contracts indexed to lauric acid feedstock benchmarks dominate procurement between fermentation specialists and multinational personal care conglomerates. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade certification levels reflects purity testing burdens and endotoxin documentation requirements. Pricing pressure stems from Chinese domestic producers scaling NMPA-aligned capacity for ASEAN export qualification. Mass-market private label brands exhibit highest price sensitivity, while pharmaceutical companies tolerate premium capture for documented batch consistency.
Supply Chain Analysis
China anchors fermentation-derived amino acid surfactant production through Jiangsu and Zhejiang coastal clusters serving both domestic NMPA compliance and export markets. South Korean and Japanese fermentation houses supply premium powdered grades to Seoul-based skincare conglomerates. German integrated oleochemical networks in North Rhine-Westphalia sustain European cost competitiveness. Lauric acid feedstock draws from Malaysian and Indonesian palm kernel oil estates, with coconut oil alternatives from Philippine suppliers. Single-source vulnerability concentrates in coastal China's energy grid exposure. Distribution runs through direct supplier development programs displacing regional distributor networks for premium cosmetic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from feedstock volatility cyclicality, with lauric acid price normalization following palm oil sector stabilization enabling margin restoration for backward-integrated producers.
For Market Incumbents: Consolidate fermentation capacity in Yangtze River Delta clusters to preempt NMPA-aligned Chinese competitors from capturing ASEAN export share. Deepen backward integration into oleochemical feedstock through Malaysian palm kernel oil offtake agreements to insulate margin stability from lauric acid spot volatility. Lock in multi-year direct procurement contracts with German and French personal care conglomerates before REACH dossier renewal cycles extend competitor qualification timelines. For New Entrants and Emerging Players: Lead with enzymatic synthesis technology licensing to bypass capital-intensive batch-reactor barriers that have constrained fermentation house entry. Target India's CDSCO-aligned domestic brands in Maharashtra and Gujarat for sulfate-free skincare line qualification, where incumbent supplier relationships remain underdeveloped. Penetrate through technical partnership models offering formulation IP protection and supply traceability documentation that large conglomerates prioritize over transactional purchasing efficiency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous enzymatic production routes as process technology licensing decomposes historic barriers to scale. Five-to-ten year viability favors acquisition of mid-scale fermentation specialists with existing REACH registration dossiers and established supplier development programs with premium cosmetic manufacturers. Monitor ECHA guidance updates on UVCB substance identification as inflection signal for regulatory compliance cost acceleration that would favor incumbent scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstock | Captive lauric acid supply from Malaysian estates insulates margin stability from palm kernel oil volatility. |
| Continuous Enzymatic Synthesis Scale-Up | Biocatalytic production routes reduce capital barriers and improve batch consistency for cosmetic-grade material. |
| Multi-Jurisdiction Dossier Registration | Concurrent REACH, FDA MoCRA, and NMPA compliance preserves formulation flexibility across premium export markets. |
| Direct Supplier Development Programs | Bypassing distributor networks secures long-term offtake with German and French personal care conglomerates. |
| Pharmaceutical-Grade Purity Certification | Documented endotoxin profiles unlock injectable and topical drug delivery system specifications at premium pricing tiers. |
Research Methodology
A spread of perspectives from fermentation process engineers, cosmetic formulation chemists, procurement leads at multinational personal care conglomerates, and regulatory affairs specialists at ECHA-registered producers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of diversified chemical conglomerates, and NMPA cosmetic raw material registration databases. Bottom-up capacity assessments triangulated against top-down demand modeling from sulfate-free formulation mandates.
Segmentation dimensions modeled include product type format, application end-use, functional formulation role, and geographic production hub across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating lauric acid feedstock price scenarios and regulatory compliance cost burdens. Industry-specific forecast inputs encompassed enzymatic synthesis technology adoption curves and CDSCO-aligned domestic brand procurement timelines in India.
Forecasts assume regulatory continuity in REACH, FDA MoCRA, and NMPA regimes; material policy shifts would require re-modeling. Specific risks include ECHA guidance updates on UVCB substance identification, Chinese energy grid disruptions affecting coastal fermentation capacity, and palm kernel oil price volatility from Southeast Asian weather events. Recalibration cycles align with material shifts in biobased certification scheme adoption and enzymatic synthesis technology licensing activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Paraben Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Ortho-Phthalaldehyde Market