
 Calcium Citrate Malate Market | 2026-2036
Calcium Citrate Malate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Citrate Malate Market Outlook
Calcium carbonate is shifting toward calcium citrate malate in premium supplement lines due to superior gastric tolerability and absorption kinetics at lower gastric pH. Jungbunzlauer Suisse AG leverages its Swiss fermentation heritage to dominate pharmaceutical-grade supply chains. Gadot Biochemical Industries anchors Mediterranean production with integrated citric acid sourcing. Dr. Paul Lohmann GmbH KG differentiates through custom mineral premix capabilities for European nutraceutical brands.
Calcium citrate malate is a calcium salt formed from citric acid and malic acid, typically yielding 20-25% elemental calcium with enhanced solubility in both acidic and neutral pH environments; manufacturers produce it via controlled aqueous reaction followed by spray drying or crystallization for tableting and encapsulation. The compound serves primarily as a bioavailable calcium source in dietary supplements and pharmaceutical antacids where gastric sensitivity limits carbonate tolerance. Powder formulations lead production volumes due to bulk ingredient demand from contract manufacturers, while tablet and capsule segments capture higher margin pools in direct-to-consumer channels. Bone health applications anchor the application mix, though cardiovascular support and muscle function categories are gaining traction in sports nutrition portfolios.
US FDA cGMP regulations for dietary supplements and EFSA health claim evaluations in Europe collectively elevate purity and substantiation thresholds for calcium citrate malate suppliers seeking multi-jurisdiction market access. India's FSSAI fortification standards and China's GB food additive specifications further fragment compliance requirements for global manufacturers. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study expectations as clinical evidence standards tighten across major consuming markets.
Market Dynamics
The transition from calcium carbonate to calcium citrate malate in premium supplement lines is restructuring formulation priorities across pharmaceutical and nutraceutical supply chains, as gastric tolerability and absorption kinetics at lower pH become decisive selection criteria.
Growth Catalysts
- Aging demographics in the United States:The expanding population over 65 drives sustained offtake for bone health supplements, with fortified food consumption reinforcing daily intake habits.
- FDA cGMP regulations:Elevated purity and documentation standards for dietary supplements are filtering out subscale suppliers and consolidating demand among qualified manufacturers.
- Spray drying technology:Advanced crystallization methods are enabling consistent particle size distribution for direct compression tableting, reducing downstream processing costs.
Market Restraints
- Citric acid price volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, compressing margins for integrated producers.
- Swiss production concentration:Pharmaceutical-grade supply chains cluster around Jungbunzlauer's fermentation heritage, creating geographic single-point vulnerability.
- Calcium carbonate substitution:Lower-cost mineral forms retain dominant share in economy supplement tiers, limiting CCM penetration in price-sensitive segments.
Strategic Opportunities
- Sports nutrition expansion:Cardiovascular support and muscle function claims are opening new application categories beyond traditional bone health positioning.
- India FSSAI fortification standards:Mandatory micronutrient enrichment in staple foods creates institutional demand for bioavailable calcium salts.
- Direct-to-consumer encapsulation:E-commerce channels are capturing higher-margin finished dose sales, bypassing traditional contract manufacturing relationships.
Industry Challenges
- Multi-jurisdiction pharmacopeial alignment:Reconciling USP, EP, and JP monograph specifications extends certification timelines for global suppliers.
- Bioequivalence study requirements:Tightening clinical evidence standards across major consuming markets demand expanded R&D investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Citrate Malate Market |
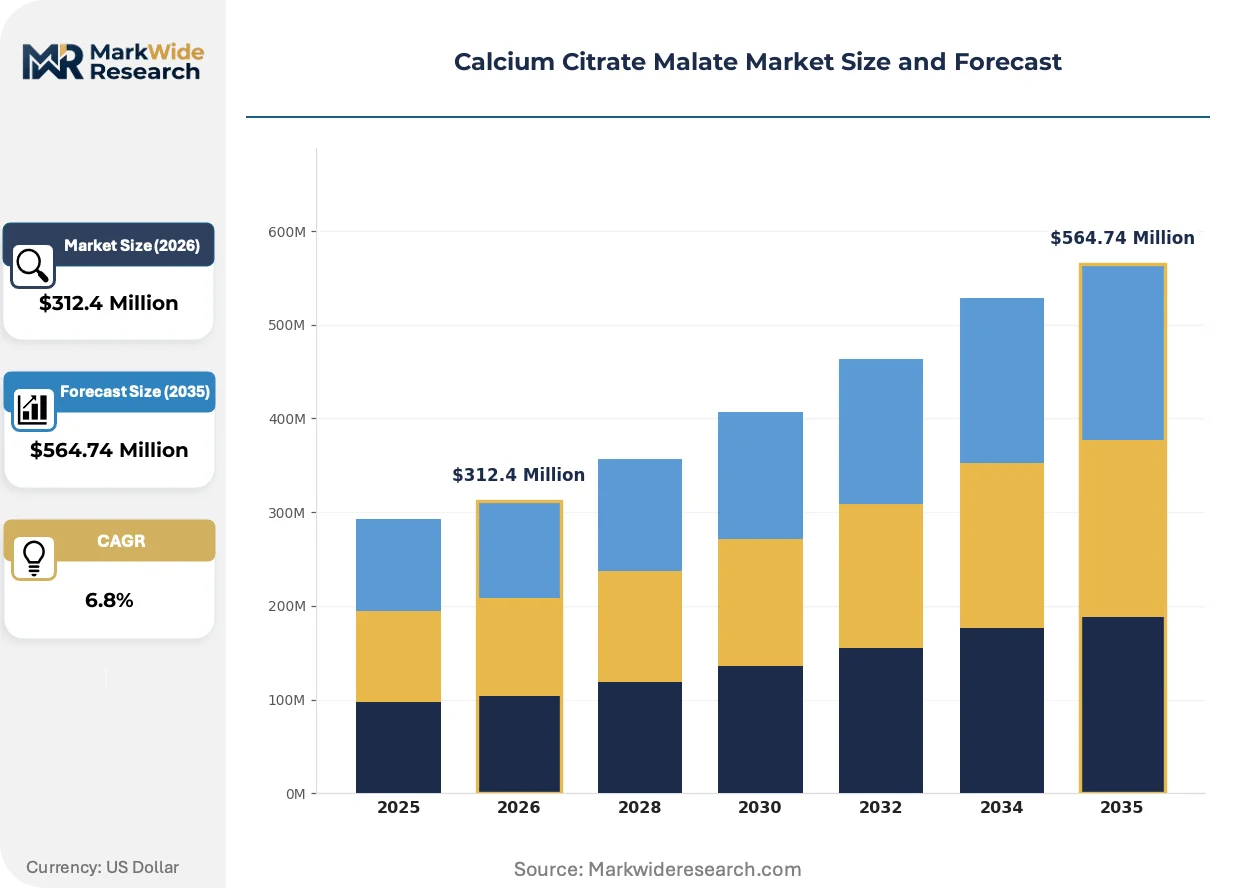
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Capsule, Liquid End User: Pharmaceuticals, Dietary Supplements, Food & Beverages, Nutraceuticals Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets Application: Bone Health, Muscle Function, Digestive Health, Cardiovascular Support |
| Companies Covered | Jungbunzlauer Suisse AG, Gadot Biochemical Industries, Dr. Paul Lohmann GmbH KG, Sucroal SA, Jost Chemical, Global Calcium, Tate & Lyle, American Elements, Nikunj Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Citrate Malate Market Strategic Shifts
Continuous processing technologies are displacing batch manufacturing in mineral salt production, while regulatory convergence around bioavailability substantiation is reshaping competitive qualification barriers.
Controlled-release matrix formulations incorporating calcium citrate malate are electrifying sports nutrition portfolios, enabling sustained mineral delivery during endurance activities. Marathon training communities and masters athletes are adopting these products at accelerating rates. The technology is electrifying premium positioning strategies, compressing the addressable market for immediate-release carbonate alternatives.
EFSA health claim evaluations are tightening evidentiary thresholds for bone maintenance assertions, requiring randomized controlled trial data rather than mechanistic plausibility arguments. European nutraceutical brands now face reformulation costs or label restriction risks. The directive most affects chewable and effervescent delivery formats targeting senior consumers.
Contract manufacturers are consolidating ingredient procurement around qualified supplier lists, reducing approved vendor counts from dozens to single-digit rosters. Direct material sourcing relationships are replacing distributor intermediation in large-scale supplement operations. This concentration is most visible in United States dietary supplement production, where cGMP audit costs favor scaled partnerships.
Calcium Citrate Malate Market Segmentation
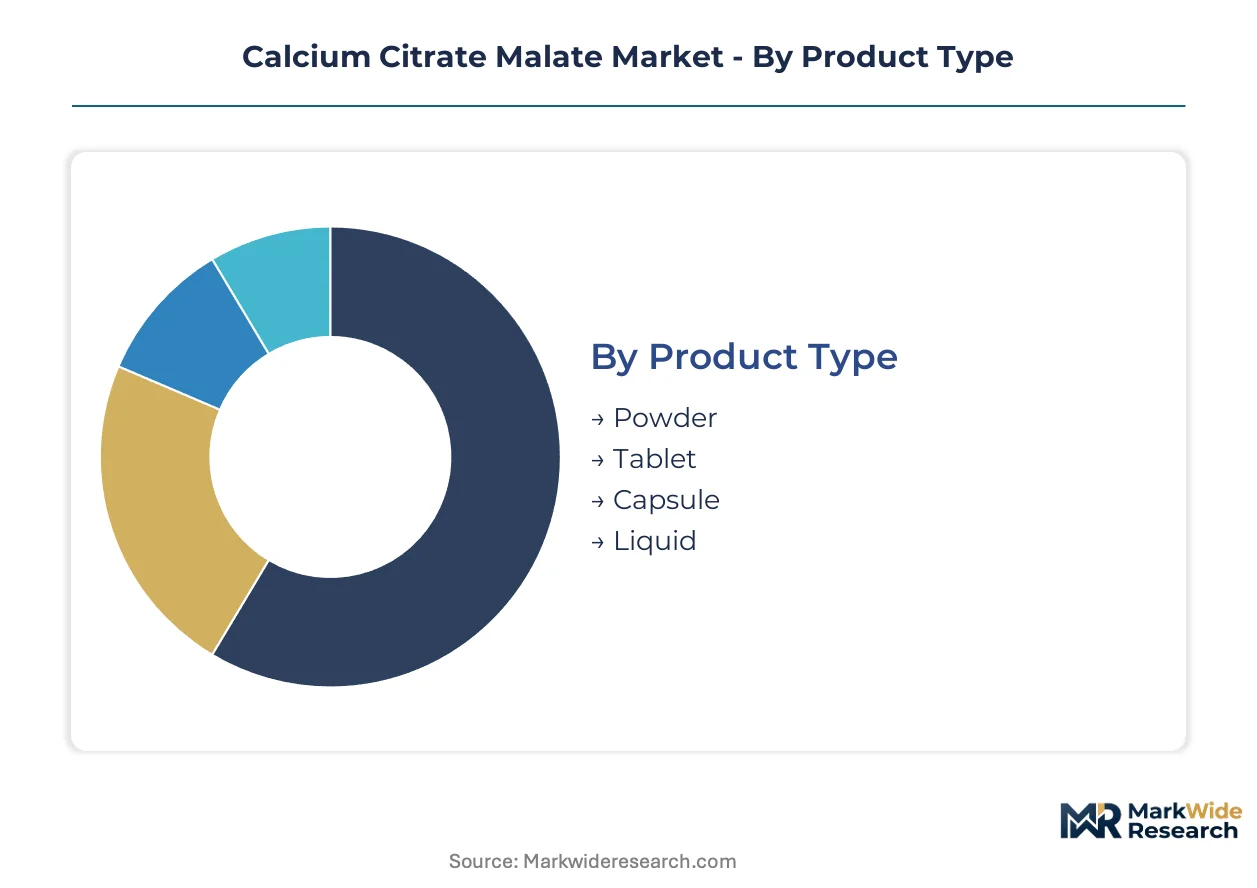
Calcium citrate malate markets fragment across formulation formats, end-use specifications, and channel economics. Each dimension carries distinct margin profiles, regulatory obligations, and customer acquisition dynamics that reshape supplier priorities.
Product Type:
Standardization dominates bulk powder supply while tablets and capsules demand customization for compression characteristics and disintegration profiles.
- Powder:Bulk ingredient form serves contract manufacturers and food fortification programs with 20-25% elemental calcium content. Demand concentrates in United States dietary supplement production where cGMP documentation requirements favor qualified suppliers with consistent particle size distribution. Spray drying technology investments separate pharmaceutical-grade from technical-grade supply tiers.
- Tablet:Direct compression formulations require precise granulometry and flow properties. United States direct-to-consumer brands drive specification tightening as cGMP audit costs push procurement toward single-digit approved vendor rosters. Controlled-release matrix technologies are opening sports nutrition applications.
- Capsule:Encapsulation suits acid-sensitive consumers seeking gastric tolerability. E-commerce channels capture higher-margin finished dose sales.
- Liquid:Pediatric and geriatric compliance applications favor this format. Pharmacy dispensing networks anchor distribution.
Most installed capacity flows through Powder. Expansion is steepest in Tablet.
End User:
Cost tier separation distinguishes pharmaceutical validation requirements from nutraceutical speed-to-market priorities.
- Pharmaceuticals:USP and EP monograph compliance mandates extensive documentation and stability testing. Swissmedic and FDA cGMP standards filter out subscale suppliers, consolidating demand around fermentation heritage manufacturers with integrated citric acid sourcing.
- Dietary Supplements:Rapid formulation iteration and label claim flexibility characterize this segment. United States aging demographics and fortified food consumption drive sustained offtake. EFSA health claim evaluations in Europe are tightening evidentiary thresholds for bone maintenance assertions.
- Food & Beverages:India FSSAI fortification standards create institutional demand for bioavailable calcium salts in staple food enrichment. GB standards in China govern food additive specifications.
- Nutraceuticals:Positioning between pharma and supplements requires balanced substantiation and agility. European brands face reformulation costs from tightened clinical evidence standards.
Volume concentrates in Pharmaceuticals. Margin expansion is fastest in Dietary Supplements.
Distribution Channel:
Channel selection determines customer relationship economics and working capital intensity.
- Online Retail:Direct-to-consumer encapsulation bypasses traditional contract manufacturing relationships. United States e-commerce penetration in supplements enables premium positioning and subscription revenue models.
- Specialty Stores:Curated assortment and staff consultation support premium tier placement. Sports nutrition and endurance athlete targeting concentrates here.
- Pharmacies:Professional recommendation channel suits geriatric and pediatric liquid formulations. Pharmacist counseling reinforces compliance and repeat purchase.
- Supermarkets:Mass market penetration for fortified foods and economy supplement tiers. Price competition with calcium carbonate alternatives limits CCM share.
Procurement consolidation favors Online Retail. Specialty Stores command highest unit economics.
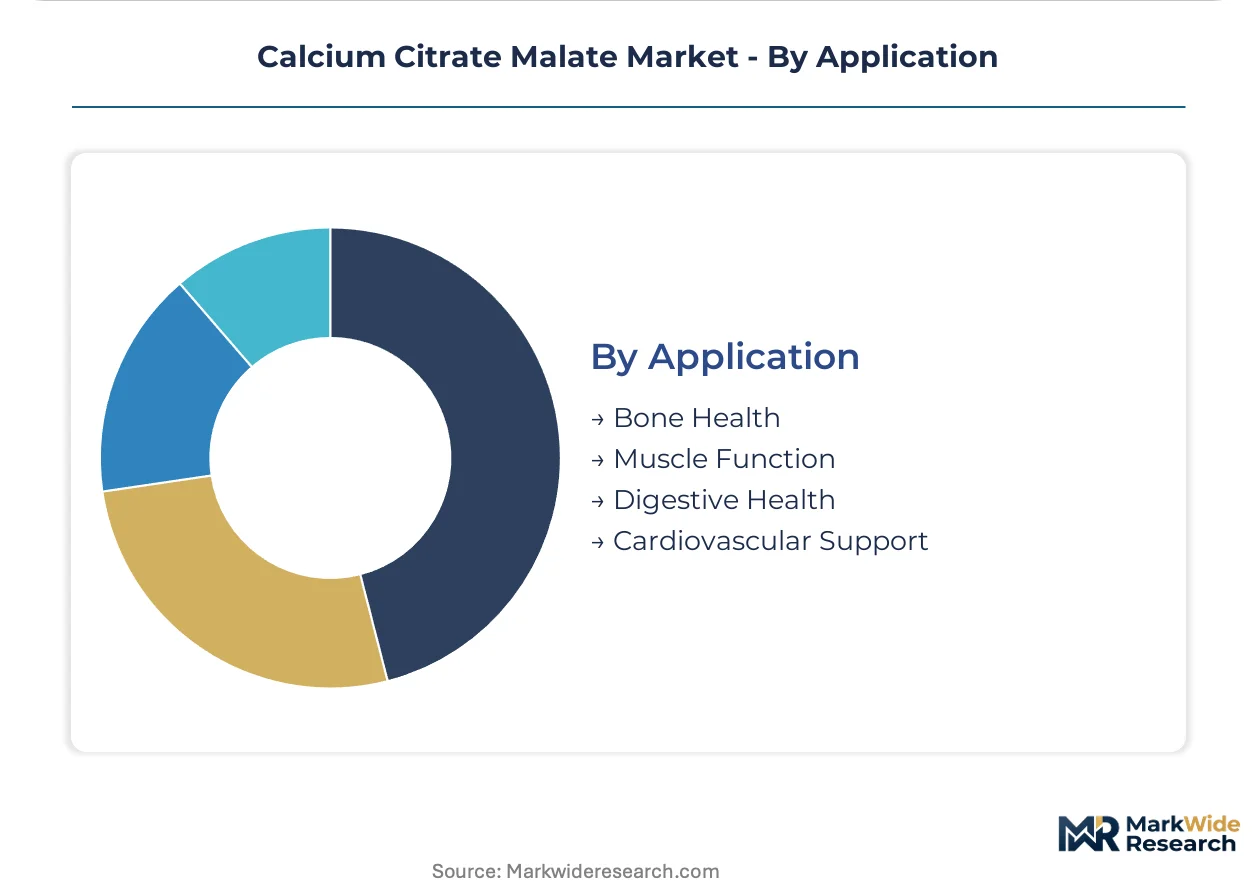
Application:
Maturity gradient separates established bone health positioning from emerging functional claims.
- Bone Health:Traditional anchor application with extensive clinical validation. United States population over 65 sustains baseline demand across all formulation formats.
- Muscle Function:Emerging sports nutrition category with controlled-release matrix enabling sustained mineral delivery. Marathon training communities and masters athletes are adopting these products.
- Digestive Health:Gastric tolerability advantage over carbonate drives substitution in sensitive populations. Antacid formulations leverage CCM solubility across pH ranges.
- Cardiovascular Support:Novel positioning requiring expanded bioequivalence study investment. Tightening clinical evidence standards across major consuming markets elevate R&D barriers.
Revenue concentration remains in Bone Health. Category development is most active in Muscle Function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jungbunzlauer's Swiss fermentation heritage anchors pharmaceutical-grade supply chains, while Mediterranean citric acid sourcing clusters around Gadot's integrated operations. Demand concentrates where aging populations and fortified food programs intersect with strict cGMP enforcement.
United States
The population over 65 sustains bone health supplement offtake, with fortified food consumption reinforcing daily intake habits. FDA cGMP regulations for dietary supplements filter out subscale suppliers and consolidate procurement around qualified manufacturers. New Jersey and California host contract manufacturing clusters where approved vendor rosters have compressed from dozens to single-digit counts.
Germany
Custom mineral premix capabilities serve European nutraceutical brands seeking formulation agility. EFSA health claim evaluations tighten evidentiary thresholds for bone maintenance assertions, forcing reformulation investments. The North Rhine-Westphalia region concentrates pharmaceutical-grade mineral salt production with integrated citric acid supply chains.
India
FSSAI fortification standards create institutional demand for bioavailable calcium salts in staple food enrichment programs. Mandatory micronutrient policies expand addressable volume beyond traditional supplement channels. Maharashtra and Gujarat house integrated fermentation and mineral processing facilities serving domestic and export markets.
China
GB food additive specifications govern calcium citrate malate incorporation into fortified foods and beverages. Dual carbon goals pressure fermentation feedstock sourcing decisions across citric acid supply chains. Shandong Province clusters citric acid production with downstream mineral salt manufacturing.
Switzerland
Swissmedic standards enforce pharmaceutical-grade purity thresholds that exceed general nutraceutical requirements. Basel and Zurich anchor fermentation heritage capabilities with multi-jurisdiction pharmacopeial certification. Jungbunzlauer's integrated operations supply qualified manufacturers across European and North American markets.
Calcium Citrate Malate Market Competitive Environment
Global majors compete with regional champions across certification tiers and supply chain integration levels. The vendor base stratifies between fermentation heritage operators with captive citric acid supply and mineral salt specialists dependent on merchant feedstock markets. Three archetypes dominate: integrated fermentation-to-mineral producers, custom premix formulators, and regional contract manufacturers. Capacity expansion and pharmacopeial certification investments constitute the primary competitive vectors as multi-jurisdiction compliance costs rise.
Within the integrated production tier, Jungbunzlauer Suisse AG represents Swiss fermentation heritage with pharmaceutical-grade supply chain dominance. Gadot Biochemical Industries anchors Mediterranean operations with geographic proximity to citric acid feedstock sources. Dr. Paul Lohmann GmbH KG occupies a position as a custom mineral premix specialist serving European nutraceutical formulation requirements.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Gadot Biochemical Industries |
| Dr. Paul Lohmann GmbH KG |
| Sucroal SA |
| Jost Chemical |
| Global Calcium |
| Tate & Lyle |
| American Elements |
| Nikunj Chemicals |
| Others |
Value Chain & Pricing Dynamics
Captive citric acid sourcing through fermentation heritage operations anchors both supply security and pricing power for pharmaceutical-grade calcium citrate malate, insulating integrated producers from agricultural commodity volatility while compressing margins for merchant-feedstock-dependent competitors.
Pricing Analysis
Fermentation feedstock costs pass through directly to mineral salt pricing, with citric acid price volatility compressing margins most acutely for non-integrated suppliers. Pricing stratifies across pharmaceutical-grade, nutraceutical-grade, and technical-grade tiers, with USP and EP certification premiums widening as FDA cGMP audit costs filter out subscale competitors. Cost compression in economy supplement tiers is intensifying because calcium carbonate alternatives retain dominant share in price-sensitive segments. Contract manufacturers exhibit highest price sensitivity due to procurement consolidation around single-digit approved vendor rosters, while direct-to-consumer brands absorb premium positioning costs.
Supply Chain Analysis
India FSSAI fortification standards and China's GB food additive specifications are reshaping sourcing patterns toward domestic-content compliance for institutional food programs. Supply concentrates in Switzerland, Germany, and India, with Swissmedic-certified fermentation heritage operations drawing from captive citric acid streams. Raw material dependencies rest on agricultural feedstocks for fermentation, malic acid merchant markets, and calcium carbonate sourcing. Single-source vulnerability clusters around Jungbunzlauer's Swiss production dominance for pharmaceutical-grade supply. Distribution runs through qualified supplier lists to contract manufacturers, with direct material sourcing replacing distributor intermediation at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
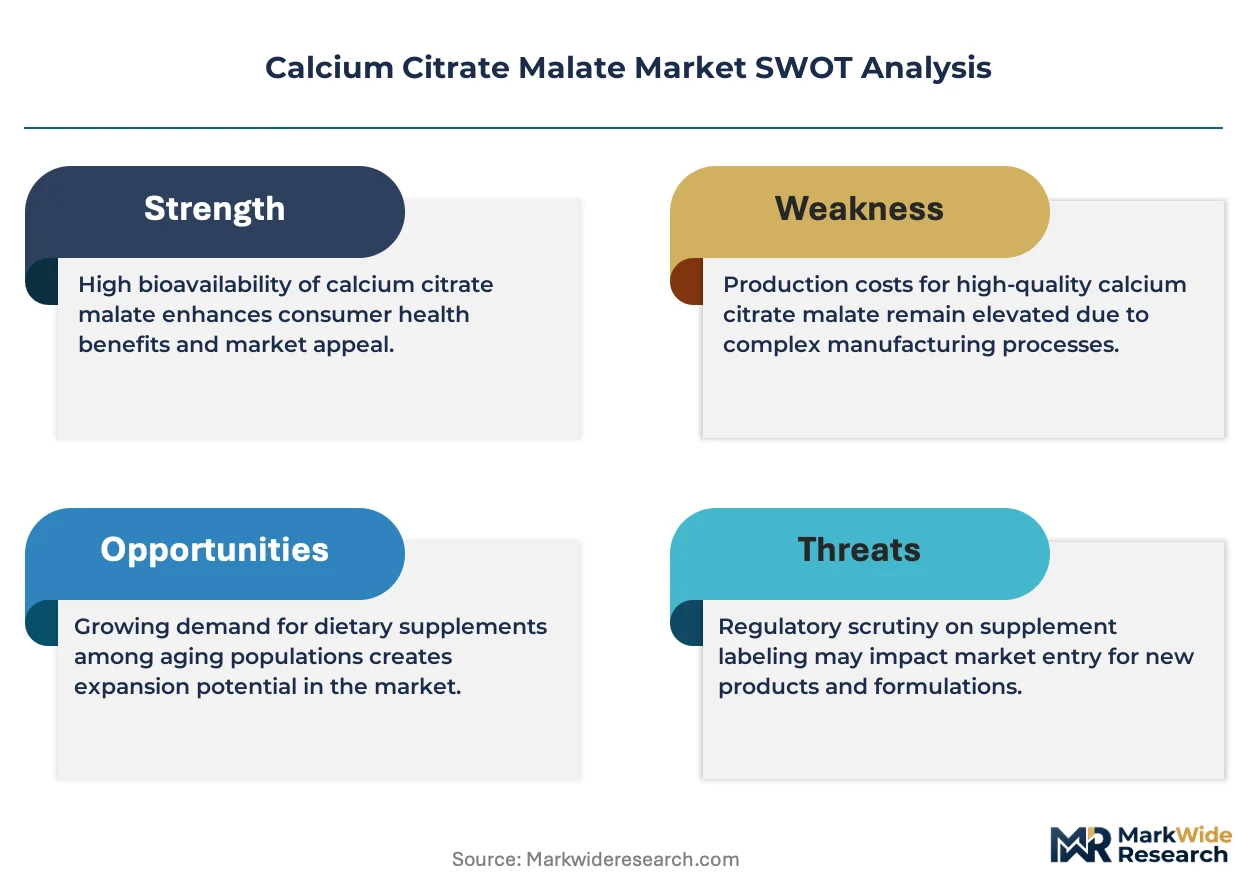
Calcium citrate malate represents a late-cycle quality story as aging demographics and tightening pharmacopeial standards drive substitution away from carbonate alternatives toward premium bioavailable forms.
For Market Incumbents: Anchor pharmaceutical-grade positioning through Swissmedic and FDA cGMP certification investments that exploit the geographic single-point vulnerability of concentrated fermentation heritage supply. Defend against calcium carbonate substitution in economy tiers by locking long-term offtake agreements with contract manufacturers whose approved vendor rosters have compressed to single-digit counts. Prioritize backward integration into citric acid fermentation to neutralize agricultural commodity price volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer encapsulation channels that bypass traditional contract manufacturing relationships and capture higher-margin finished dose sales. Target India's FSSAI-mandated staple food fortification programs as the most penetrable institutional volume opportunity, where bioavailable calcium salts face limited qualified supplier competition. Pursue white-space positioning in sports nutrition controlled-release matrices for endurance athletes, where clinical evidence requirements remain less stringent than EFSA-regulated bone health claims. For Investors and Strategic Acquirers: Roll-up economics work for custom mineral premix specialists because European nutraceutical brands face reformulation costs from tightened EFSA evidentiary thresholds that favor agile formulation partners. The five-to-ten-year viability window hinges on pharmacopeial convergence around bioavailability substantiation standards. Monitor bioequivalence study requirement announcements across major consuming markets as the inflection signal for R&D investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Fermentation | Captive feedstock supply neutralizes agricultural commodity price volatility for mineral salt producers. |
| Pharmacopeial Certification Investment | USP and EP monograph compliance filters subscale competitors and consolidates procurement around qualified suppliers. |
| Controlled-Release Matrix Development | Sustained mineral delivery technology opens sports nutrition applications beyond traditional bone health positioning. |
| Direct-to-Consumer Channel Launch | E-commerce encapsulation bypasses contract manufacturing relationships and captures premium finished dose margins. |
| India FSSAI Fortification Compliance | Mandatory micronutrient enrichment in staple foods creates institutional demand for bioavailable calcium salts. |
Study Parameters
Bottom-up dietary supplement and pharmaceutical demand modeling reconciled against top-down citric acid and mineral salt production tracking forms the analytical core of this study. Primary interviews with formulation scientists at nutraceutical brands, procurement leads at contract manufacturers, regulatory affairs directors, and technical sales managers at fermentation heritage suppliers combined with secondary validation from FDA cGMP inspection databases, EFSA health claim evaluation registers, FSSAI fortification compliance notices, and USP monograph revision records. Triangulation across these sources ensures demand-side consumption patterns align with supply-side capacity and certification constraints.
Input-output matrices linking fermentation feedstock availability to mineral salt production capacity, certification tier distribution, and end-use segment absorption rates structure the projection framework. Segmentation dimensions span formulation format, grade tier, end-use specification, and regional regulatory cluster. CAGRs derive from trend extrapolation of aging demographic supplementation rates, fortified food program expansion, and pharmacopeial standard tightening across the analysis window. Industry-specific forecast inputs include citric acid price volatility indices and cGMP audit cost trajectories.
Several conditions sit outside the modeled scope, including unforeseen regulatory monograph revisions, abrupt shifts in agricultural commodity cycles affecting fermentation economics, and disruptive calcium delivery technologies that could displace citrate malate bioavailability advantages. Forecasts reflect documented assumptions about pharmacopeial convergence timelines and institutional fortification program continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Paraben Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Global Sodium Lignosulfonate Market