
 Pharmaceutical Grade Amino Acid Market | 2026-2036
Pharmaceutical Grade Amino Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Grade Amino Acid Market Insights
Specialty distributor networks for pharmaceutical grade amino acids is fragmenting as direct API procurement channels gain ground among large formulation houses. Ajinomoto Co., Inc. leverages its integrated fermentation infrastructure to command supply security for L-glutamine and L-leucine grades. Merck KGaA anchors European demand through its high-purity Emprove-qualified portfolio, while CJ CheilJedang Corp. competes aggressively on lysine-family derivatives via scaled bioreactor operations in South Korea.
Pharmaceutical grade amino acids are defined as compendial-quality nitrogenous organic compounds meeting pharmacopeial monograph specifications for identity, purity, and microbial limits, typically manufactured via microbial fermentation or enzymatic synthesis with residual solvent controls below ICH Q3C thresholds. These molecules serve as essential building blocks in parenteral nutrition solutions, cell culture media, and active pharmaceutical ingredient synthesis. L-glutamine dominates volume flows into clinical nutrition and bioprocessing applications where thermal instability drives demand for stabilized dipeptide forms. Pharmaceutical formulations command premium pricing due to endotoxin and heavy metal testing burdens, while nutraceuticals sustain broader volume through dietary supplement manufacturer procurement of powdered L-taurine and L-valine.
FDA enforces Current Good Manufacturing Practice under 21 CFR Parts 210-211 for amino acid API production, while EMA's Active Substance Master File procedures govern European market access through centralized quality reviews. China's NMPA mandates registration testing under the Chemical Drug Registration Classification system for imported amino acid raw materials. Stakeholders must monitor divergence between pharmacopeial standards as USP, EP, and ChP monograph updates create compliance complexity for multi-territory suppliers.
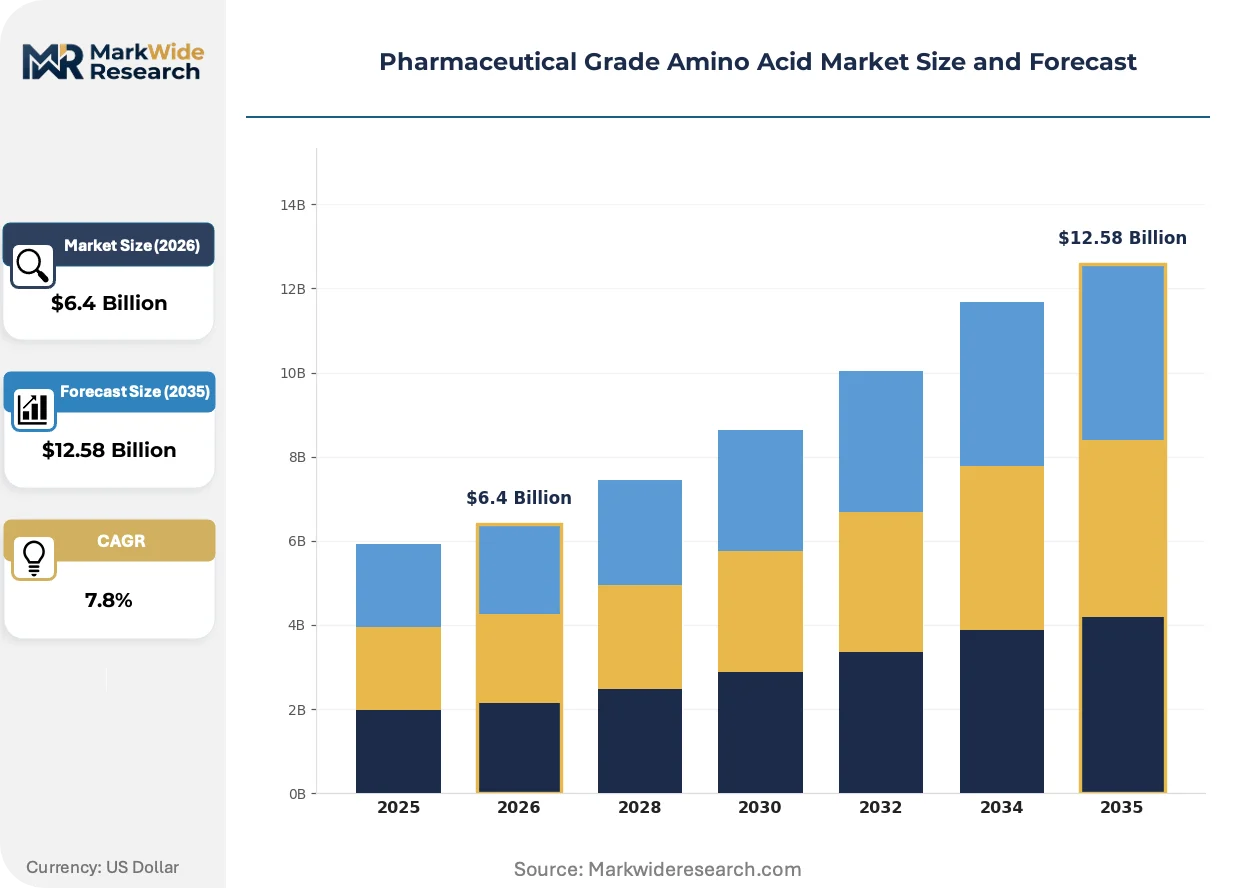
Market Dynamics
Fermentation capacity concentration in East Asia is compressing supply security timelines for European and North American formulators, forcing dual-sourcing mandates and inventory buffer expansion across parenteral nutrition supply chains.
Growth Catalysts
- Injectable nutrition protocols:Hospital systems in Germany and the United States are expanding parenteral nutrition formulary slots for surgical recovery and oncology supportive care, tightening amino acid purity specifications to USP and EP monograph limits.
- EMA quality guideline harmonization:Centralized Active Substance Master File procedures are streamlining multi-country registration for high-purity L-glutamine and L-arginine grades, reducing time-to-market for dedicated fermentation facilities.
- Cell culture media expansion:Bioprocessing demand for chemically defined media is displacing serum-based alternatives, requiring pharmaceutical-grade amino acid inputs with documented endotoxin and heavy metal certificates.
Market Restraints
- Fermentation input volatility:Corn-derived dextrose and nitrogen source pricing swings directly compress margin stability for bulk L-lysine and L-threonine production, particularly affecting spot-market procurement.
- East Asian supply concentration:Over 70 percent of global pharmaceutical-grade fermentation capacity resides in China and South Korea, creating geopolitical exposure and customs delay vulnerability for Atlantic buyers.
- Substitute protein sources:Peptide-based clinical nutrition formulations and hydrolyzed protein hydrolysates are capturing enteral nutrition share, constraining volume growth for crystalline amino acid infusions.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations near Hyderabad and Ahmedabad are building USP-grade fermentation suites, offering alternative sourcing for European generic injectable houses seeking supply diversification.
- Stabilized dipeptide formats:L-alanyl-L-glutamine and glycyl-L-tyrosine derivatives address thermal degradation in L-glutamine solutions, opening premium positioning in bioprocessing media and extended-shelf nutrition products.
- CDSCO fast-track pathways:India's streamlined chemical drug registration for imported APIs is attracting master file submissions for L-histidine and L-isoleucine grades, accelerating market access for qualified suppliers.
Industry Challenges
- Pharmacopeial divergence management:Simultaneous compliance with USP, EP, and ChP monograph updates requires dedicated analytical teams and redundant testing protocols, stretching quality assurance resources at mid-scale suppliers.
- Contamination control infrastructure:Endotoxin limits below 10 EU per gram for injectable grades demand isolated fermentation suites and dedicated downstream processing trains, elevating capital intensity for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Amino Acid Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Valine, L-Taurine, L-Leucine, L-Glutamine Application: Protein Supplementation, Nutraceuticals, Pharmaceutical Formulations, Clinical Nutrition End User: Pharmaceutical Companies, Research Institutions, Hospitals, Dietary Supplement Manufacturers Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | Ajinomoto Co., Inc., Merck KGaA, Fresenius Kabi AG, Archer Daniels Midland Company, CJ CheilJedang Corp., Amino GmbH, Sumitomo Chemical Co., Ltd., Jiangsu Shenhua Pharmaceutical Co., Ltd., Kyowa Hakko Bio Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Amino Acid Market Trends and Innovations
Continuous processing and real-time release testing are displacing batch-oriented fermentation workflows, compressing cycle times and redefining competitive differentiation around analytical throughput rather than scale alone.
Enzymatic synthesis routes for non-proteinogenic amino acids are hybridizing with traditional fermentation, enabling stereospecific production of D-amino acids for peptide API precursors without racemate separation burdens. Contract manufacturers in Switzerland and Japan are adopting these hybrid platforms for orphan drug intermediate supply, securing premium pricing against commodity fermentation volumes.
FDA's enhanced approach to pharmaceutical quality assessment under the Quality Management Maturity program is elevating inspection intensity for amino acid API facilities, particularly those supplying parenteral drug products. Facilities demonstrating proactive quality culture and continuous process verification receive expedited review prioritization, while reactive compliance postures face extended approval timelines and import alert vulnerability.
Hospital procurement consortia in France and the United Kingdom are consolidating amino acid purchasing through centralized tender frameworks, compressing supplier margins and favoring multi-product portfolios with guaranteed volume commitments. Formulators responding with long-term offtake agreements and dedicated inventory positioning are securing formulary access against spot-market competitors.
Pharmaceutical Grade Amino Acid Market Segmentation
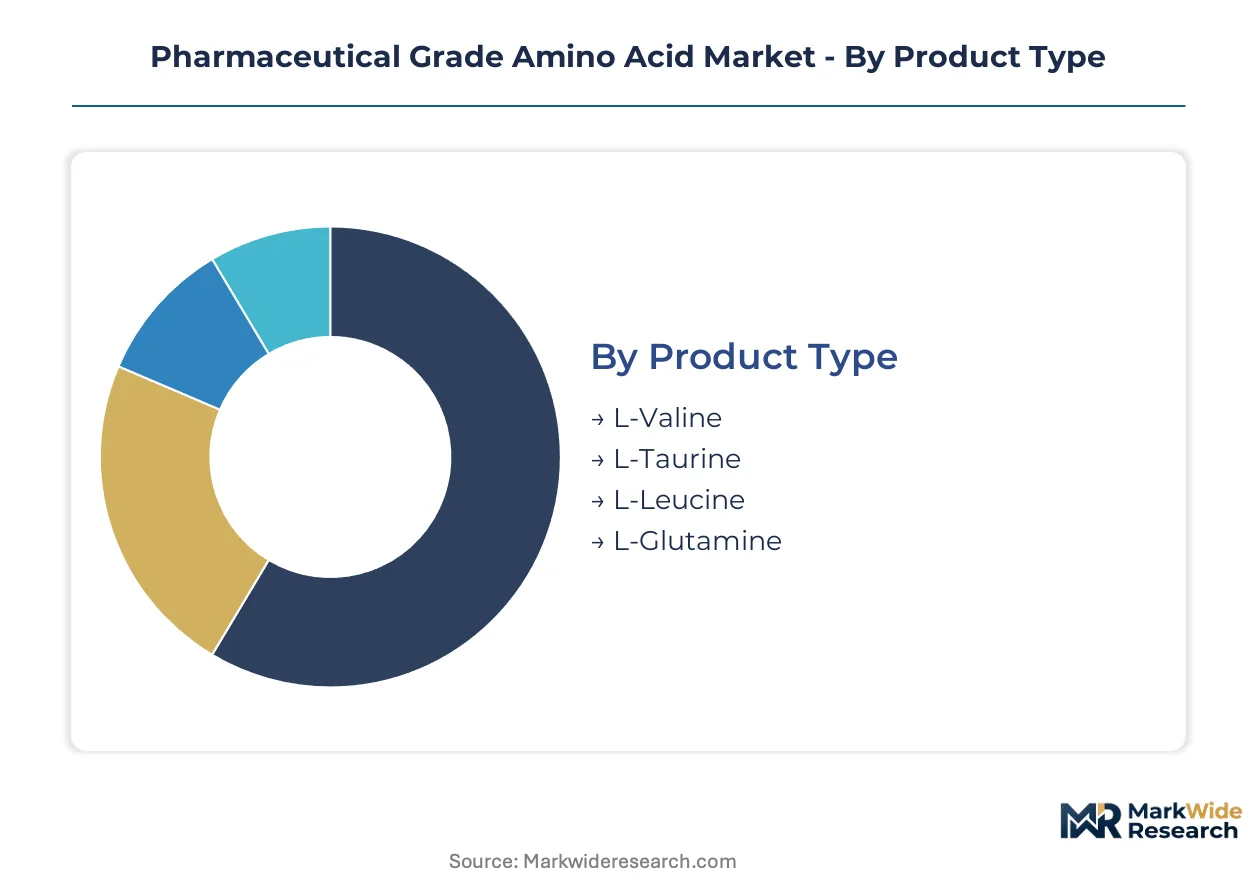
Pharmaceutical grade amino acid procurement patterns diverge sharply across molecular categories, therapeutic applications, and delivery formats. Formulators select grades based on endotoxin thresholds, compendial alignment, and thermal stability requirements rather than commodity pricing alone.
Product Type:
Cost tier differentiation separates fermentation-scale commodities from specialized enzymatic synthesis outputs with premium purity certifications.
- L-Glutamine:This amide-functional amino acid dominates clinical nutrition and bioprocessing volumes. Demand concentrates in parenteral nutrition solutions where thermal instability drives preference for stabilized dipeptide forms. German hospital systems and US oncology wards specify USP-grade certificates with endotoxin documentation.
- L-Leucine:The branched-chain essential amino acid serves protein synthesis modulation in metabolic disorder therapies. Procurement from Ajinomoto's integrated fermentation infrastructure secures supply continuity for European generic injectable houses facing dual-sourcing mandates.
- L-Valine:BCAA-family molecule for muscle protein metabolism applications.
- L-Taurine:Sulfur-containing amino acid for cardiovascular and neurological formulation development.
L-Glutamine commands the established base. The steepest expansion runs through stabilized dipeptide derivatives addressing shelf-life limitations.
Application:
Application maturity determines specification stringency, with injectable grades requiring isolated processing trains that powder supplement applications bypass.
- Clinical Nutrition:Parenteral and enteral feeding solutions demand the highest purity tiers. Hospital procurement consortia in France and the United Kingdom consolidate purchasing through centralized tenders, compressing margins while requiring guaranteed volume commitments from qualified suppliers.
- Pharmaceutical Formulations:Active pharmaceutical ingredient synthesis and excipient functions require documented heavy metal and residual solvent compliance under ICH Q3C. EMA Active Substance Master File procedures govern European market access for these grades.
- Nutraceuticals:Dietary supplement channels sustain broader volume through powdered formats with less stringent microbial limits.
- Protein Supplementation:Sports nutrition and wellness applications with standard-grade specifications.
Clinical Nutrition commands the established base. The steepest expansion runs through Pharmaceutical Formulations as chemically defined media displaces serum-based alternatives.
End User:
Customer type dictates procurement modality, with large formulation houses bypassing distributors for direct API relationships while research institutions rely on catalog suppliers.
- Pharmaceutical Companies:Multinational generic injectable manufacturers and innovator firms drive specification-setting for compendial-grade materials. These buyers enforce dual-sourcing mandates and inventory buffer requirements following East Asian supply concentration exposure.
- Hospitals:Acute care systems and homecare providers administer parenteral nutrition protocols. German surgical recovery programs and US oncology supportive care units are expanding formulary slots, tightening amino acid purity specifications to USP and EP monograph limits.
- Research Institutions:Cell culture media developers and academic laboratories with smaller volume requirements.
- Dietary Supplement Manufacturers:Nutraceutical compounders procuring powdered L-taurine and L-valine through distributor networks.
Pharmaceutical Companies command the established base. The steepest expansion runs through Hospitals as homecare parenteral nutrition protocols extend treatment settings.
Form:
Physical presentation determines stability engineering requirements and supply chain handling protocols across the distribution network.
- Powder:Crystalline formats dominate bulk procurement for compounding pharmacies and supplement manufacturing. This presentation requires controlled humidity packaging and documented particle size distribution for reconstitution performance.
- Liquid:Ready-to-use solutions for clinical nutrition administration. Thermal degradation sensitivity in L-glutamine liquids drives demand for stabilized dipeptide alternatives with extended shelf-life profiles.
- Capsule:Unit-dose oral delivery for nutraceutical applications.
- Tablet:Compressed solid dosage forms for dietary supplement channels.
Powder commands the established base. The steepest expansion runs through Liquid formats as hospital systems prioritize ready-to-administer products reducing compounding labor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation facilities command pricing leverage over Atlantic buyers due to concentrated capacity, while German hospital procurement consortia exploit multi-source tenders to compress supplier margins. This asymmetry shapes procurement behavior across major demand centers.
United States
Oncology supportive care and surgical recovery protocols are expanding parenteral nutrition formulary slots at major hospital systems. FDA enforces Current Good Manufacturing Practice under 21 CFR Parts 210-211 for amino acid API production, with heightened inspection intensity for facilities supplying injectable drug products. Greater Boston hosts cell culture media developers driving chemically defined media demand.
Germany
Hospital procurement consortia consolidate amino acid purchasing through centralized tender frameworks, favoring suppliers with guaranteed volume commitments. EMA Active Substance Master File procedures govern European market access through centralized quality reviews. The Rhine-Ruhr industrial corridor anchors formulation houses enforcing dual-sourcing mandates.
China
Domestic fermentation capacity expansion and NMPA registration pathways are drawing contract manufacturing investment from multinational generic injectable houses. The Chemical Drug Registration Classification system mandates registration testing for imported amino acid raw materials. The Yangtze River Delta concentration of bioreactor operations supplies over half of regional pharmaceutical-grade output.
India
Contract development and manufacturing organizations near Hyderabad and Ahmedabad are building USP-grade fermentation suites for European generic injectable houses seeking supply diversification. CDSCO fast-track pathways for imported APIs are accelerating master file submissions for L-histidine and L-isoleucine grades. The Gujarat pharmaceutical cluster is capturing contract manufacturing migration from East Asian suppliers.
Japan
Hybrid enzymatic-fermentation platforms for non-proteinogenic amino acids are securing premium pricing in orphan drug intermediate supply. PMDA quality assessments elevate inspection intensity for facilities demonstrating proactive quality culture. The Kansai industrial region hosts specialized manufacturers supplying stereospecific D-amino acids for peptide API precursors.
Pharmaceutical Grade Amino Acid Market Competitive Landscape
Integrated fermentation conglomerates and specialized enzymatic synthesis houses split the market between commodity volume and premium purity tiers. Three archetypes dominate: East Asian fermentation majors with captive raw material access, European quality-certified suppliers anchoring EMA-regulated demand, and emerging Indian CDMOs exploiting cost-positioned capacity expansion. Competitive moves concentrate on backward integration into dextrose and nitrogen sourcing, plus geographic diversification of fermentation assets to mitigate supply concentration risk.
Within the integrated fermentation tier, Ajinomoto Co., Inc. and CJ CheilJedang Corp. exemplify scale-driven supply security models, while Merck KGaA occupies a position anchoring European demand through quality-certified portfolios. These three entities represent contrasting strategic postures: Japanese-Korean fermentation depth versus European regulatory alignment.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Merck KGaA |
| Fresenius Kabi AG |
| Archer Daniels Midland Company |
| CJ CheilJedang Corp. |
| Amino GmbH |
| Sumitomo Chemical Co., Ltd. |
| Jiangsu Shenhua Pharmaceutical Co., Ltd. |
| Kyowa Hakko Bio Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals in Chinese fermentation corridors are compressing spot-market premiums for L-glutamine and L-lysine grades while simultaneously pressuring Atlantic suppliers to absorb elevated endotoxin-testing costs. This utilization asymmetry rewards integrated producers with captive dextrose sourcing and punishes toll-manufacturing dependent on spot nitrogen inputs.
Pricing Analysis
Configured-to-order pricing for stabilized dipeptide formats commands substantial premiums over standard crystalline powder grades. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified injectable grades with full endotoxin documentation from EP-aligned technical grades and ChP-registered commodity volumes. Cost compression in standard-grade L-glutamine is intensifying because hospital procurement consortia in Germany and France are consolidating tenders around multi-year volume commitments. Dietary supplement manufacturers exhibit highest price sensitivity, while cell culture media developers prioritize certificate reliability over unit cost.
Supply Chain Analysis
Corn-derived dextrose and nitrogen source procurement rests on agricultural commodity markets with direct margin impact for bulk fermentation operations. Manufacturing gravity centers on China, South Korea, and India, with the Yangtze River Delta and Gujarat pharmaceutical cluster capturing contract manufacturing migration. Single-source vulnerability concentrates in East Asian bioreactor assets supplying over half of injectable-grade L-arginine and L-histidine volumes. Distribution runs through specialty chemical distributors for mid-scale buyers and direct API procurement channels for multinational generic injectable houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consortia consolidation across France, Germany, and the United Kingdom has shifted negotiating leverage toward volume-committed buyers with formulary control. This buyer-power concentration rewards suppliers with dedicated inventory positioning and multi-product portfolios.
For Market Incumbents: Build regulatory-certification moats through simultaneous USP, EP, and ChP monograph compliance to capture multi-territory tender participation. Deepen backward integration into fermentation feedstocks to buffer margin exposure from corn-derived dextrose volatility. Expand capacity in Indian CDMO corridors near Hyderabad to diversify geographic risk from East Asian supply concentration. For New Entrants and Emerging Players: Stabilized dipeptide formats for bioprocessing media represent the most penetrable entry point, as thermal degradation sensitivity in standard L-glutamine creates specification gaps that enzymatic synthesis houses can exploit. CDSCO fast-track pathways for imported APIs offer regulatory acceleration for L-histidine and L-isoleucine grades. Partner with European generic injectable houses seeking dual-sourcing alternatives to established East Asian suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with dedicated fermentation suites and long-term offtake agreements from hospital procurement consortia. Five-to-ten year viability favors assets with integrated quality systems demonstrating proactive FDA Quality Management Maturity posture. Watch for import alert vulnerability at reactive-compliance facilities as an inflection signal for market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Captive dextrose and nitrogen sourcing buffers margin compression from agricultural commodity swings. |
| Stabilized Dipeptide Format Development | L-alanyl-L-glutamine derivatives address thermal degradation gaps in standard parenteral nutrition solutions. |
| Multi-Pharmacopeial Certification Investment | Simultaneous USP, EP, and ChP compliance unlocks consolidated tender access across Atlantic and Asian markets. |
| Indian CDMO Capacity Expansion | Hyderabad and Ahmedabad fermentation suites capture contract manufacturing migration seeking supply diversification. |
| Long-term Offtake Agreement Structuring | Guaranteed volume commitments secure formulary positioning against spot-market competitors in hospital consortia. |
Research Methodology
Cross-validation between primary interviews with fermentation plant managers, hospital procurement directors, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 483 observations, EMA Active Substance Master File submissions, and NMPA registration databases. Bottom-up capacity modeling triangulates against top-down demand estimates from parenteral nutrition formulary expansion and cell culture media displacement trends.
Calibration against historical capacity utilization rates and input cost trajectories shapes the projection framework across the analysis window. Segmentation dimensions include molecular category, application tier, delivery format, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections incorporating fermentation yield improvements and pharmacopeial standard convergence assumptions.
Stress conditions across corn price volatility, East Asian customs disruption scenarios, and EMA quality guideline revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital procurement consolidation velocity and chemically defined media adoption curves. Cross-checking against customs import data for amino acid API volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market