
 Adipamide Market | 2026-2036
Adipamide Market Size, Share, and Industry Trends Forecast 2026-2036
Adipamide Market Analytics
Modular packaging of adipamide in pre-weighed batch containers is broadening procurement flexibility for mid-sized compounders. BASF SE leverages its integrated caprolactam chain to sustain cost-advantaged supply to European fiber producers. DuPont anchors its position through specialized grades engineered for high-temperature automotive underhood applications. Ascend Performance Materials dominates the North American direct-sales channel with vertically controlled hexamethylenediamine feedstock.
Adipamide is a white crystalline diamide compound with the formula C6H12N2O, produced through ammonolysis of adipic acid or nitrile hydrolysis routes, serving primarily as a chemical intermediate and nylon-66 precursor. Powder grades command the widest specification acceptance across textile and coating applications where dissolution kinetics matter. Granule formats lead in automated plastics compounding lines where dust control and flow properties reduce processing variability. Solutions and pellets represent smaller volume pools but carry higher margin structures in electronics-grade and medical-polymer niches respectively.
EPA industrial chemical oversight and REACH substance registration in Europe jointly elevate analytical-certification burdens for adipamide importers and domestic manufacturers. BIS certification requirements in India add a third compliance layer for suppliers targeting that country's expanding fiber-production base. Stakeholders must monitor how diverging purity thresholds across these three regulatory systems reshape qualification costs and supplier eligibility.
Market Dynamics
Automotive lightweighting mandates are compressing qualification timelines for adipamide-derived polymer additives, forcing compounders to reconcile high-purity certification requirements with just-in-sequence delivery pressures from tier-1 suppliers.
Growth Catalysts
- REACH substance registration:European ECHA compliance deadlines are accelerating reformulation cycles among fiber producers, pulling through specification-grade adipamide volumes from qualified suppliers.
- Hexamethylenediamine feedstock security:Captive supply of this critical input by North American producers is insulating regional compounders from cyclical price volatility affecting Asian spot markets.
- Nylon-66 resin demand:Underhood thermal management applications in electric vehicle platforms are expanding consumption of high-heat polymer grades requiring adipamide intermediates.
Market Restraints
- Adipic acid cost volatility:Cyclohexane feedstock price swings and refinery output fluctuations transmit directly to adipamide production economics, compressing margin stability for non-integrated producers.
- European supply concentration:German and Belgian production clusters control disproportionate share of pharmaceutical-grade capacity, creating geographic vulnerability for qualified supply.
- Polyamide 6 substitution:Caprolactam-based alternatives in select textile and packaging applications are displacing adipamide-derived grades where thermal performance thresholds permit.
Strategic Opportunities
- Indian PLI scheme for textiles:Production-linked incentive structures for technical fiber manufacturing are attracting adipamide qualification investments from European and East Asian suppliers.
- Medical-polymer pellet formats:Underpenetrated demand for USP-grade adipamide in biocompatible nylon-66 for surgical instrumentation represents untapped premium positioning.
- Modular pre-weighed packaging:Batch-container delivery systems are opening mid-sized compounder segments previously excluded by minimum order quantity barriers.
Industry Challenges
- Analytical chemistry talent scarcity:REACH-compliant impurity profiling and EPA method validation require specialized spectroscopy expertise that regional laboratories struggle to retain.
- Multi-jurisdiction certification timelines:Simultaneous BIS, EPA, and ECHA dossier preparation extends product launch windows by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adipamide Market |
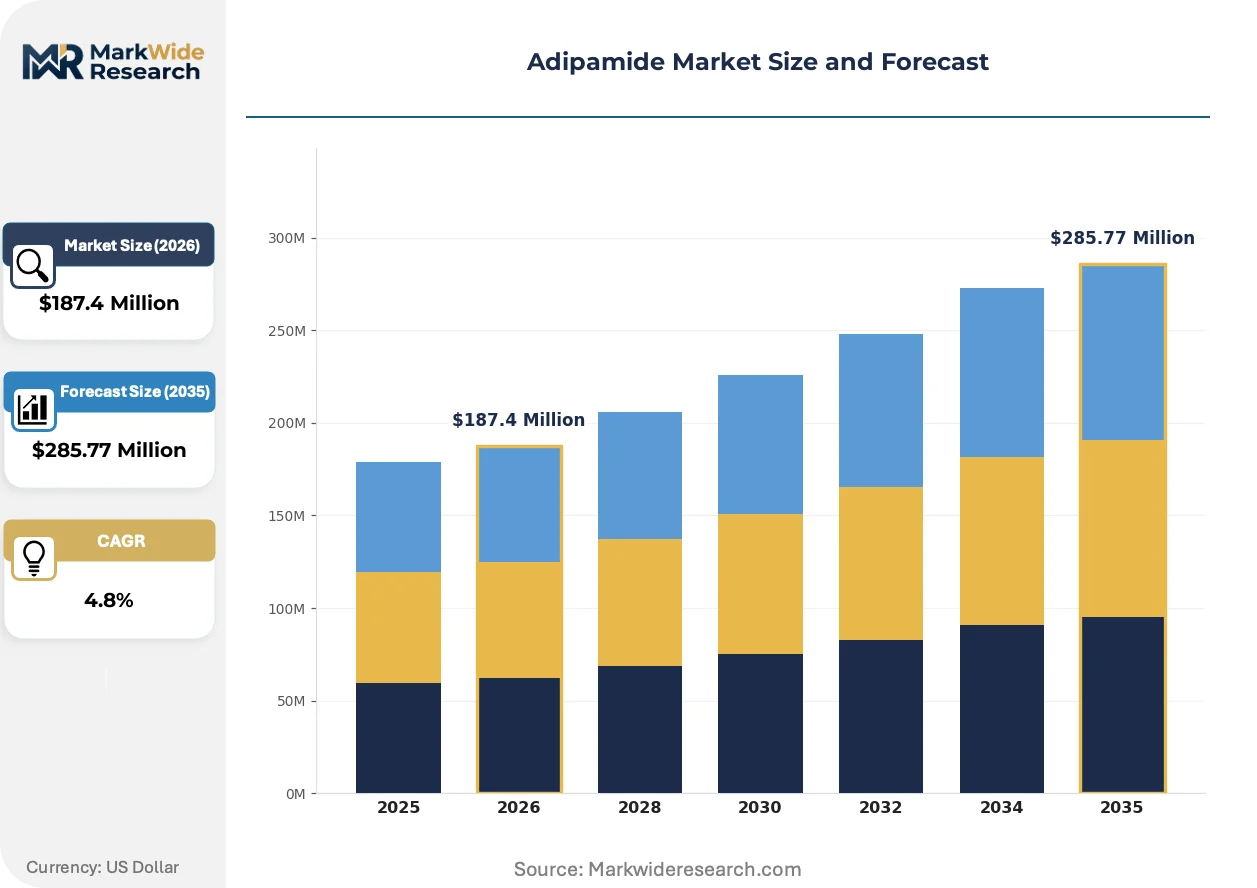
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Solutions, Pellets Application: Textiles, Automotive, Consumer Goods, Industrial Coatings End Use Industry: Fiber Production, Plastics Manufacturing, Electronics, Construction Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | BASF SE, Asahi Kasei Corporation, DuPont, Invista, Toray Industries, Evonik Industries, Ascend Performance Materials, LANXESS, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adipamide Market Evolving Landscape
Process intensification and digital quality assurance are converging to reshape how adipamide producers manage specification variance across automotive, medical, and electronics-grade product lines.
Continuous ammonolysis reactor designs are integrating real-time Raman spectroscopy for inline purity monitoring, replacing offline batch testing that introduced 4-6 hour release delays. German automotive compounders are adopting these systems fastest, driven by OEM zero-defect protocols. The technology is integrating process analytical technology frameworks from pharmaceutical manufacturing, compressing deviation response times from hours to minutes.
EPA industrial chemical oversight is tightening pre-manufacture notification requirements for adipamide derivatives used in lubricant and coating applications. The agency's expanded TSCA Section 5 authority is extending review timelines for novel formulations, particularly those with fluorinated co-monomers. US-based specialty chemical distributors are responding by consolidating supplier qualification dossiers and shifting sourcing toward EPA-registered domestic manufacturers.
Specification-driven procurement is consolidating buyer power among tier-1 automotive suppliers who now mandate certificate-of-analysis data interoperability through blockchain-verified platforms. Direct mill-to-compounder relationships are displacing traditional distributor intermediaries in high-volume nylon-66 precursor transactions. This pattern is most visible in the US Southeast, where polymer compounding clusters around Greenville and Chattanooga are negotiating long-term offtake agreements with adipamide producers.
Adipamide Market Segmentation
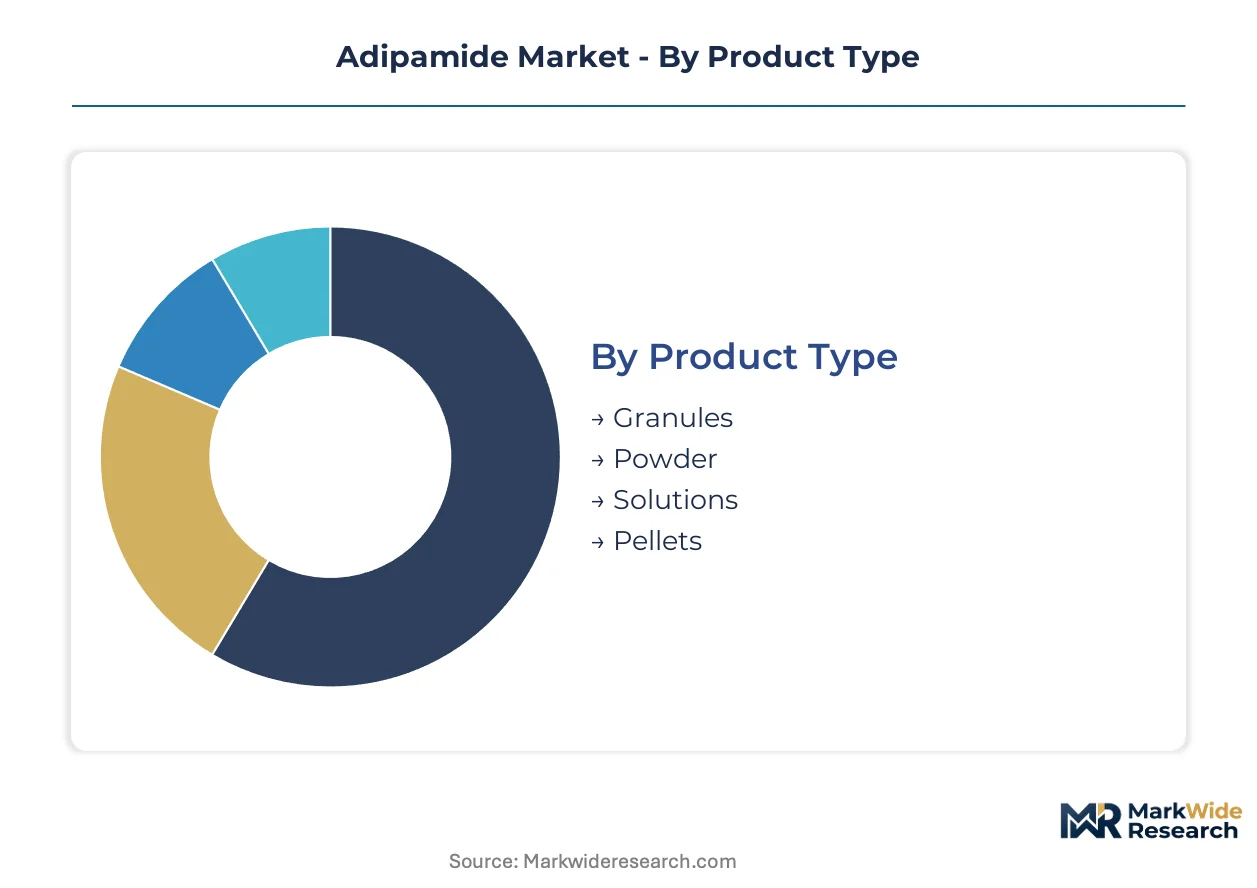
Segmentation discipline separates specification-grade adipamide from commodity volumes, determining which producers capture automotive qualification premiums versus textile contract margins. Procurement teams use these categories to map supplier capabilities against end-use certification requirements.
Product Type:
Format selection drives handling economics and dissolution kinetics, with automated compounding lines forcing upgrades from legacy powder systems to engineered granules.
- Granules:Engineered particle sizes between 0.5-2.0mm optimize flow properties in twin-screw extrusion. Automotive underhood polymer compounders in Germany specify dust-free granule delivery to meet OEM zero-defect protocols.
- Powder:Fine crystalline grades with controlled surface area dominate textile fiber dissolution where rapid ammonolysis kinetics matter. Indian technical fiber producers under PLI scheme incentives are expanding powder-grade offtake agreements.
- Solutions:Pre-dissolved aqueous or solvent-based formats serve electronics-grade coating applications requiring ppm-level impurity control.
- Pellets:Medical-polymer certified grades for biocompatible nylon-66 surgical instrumentation command premium positioning in USP-grade niches.
Granules sit at the top of the volume ranking, with pellets climbing the fastest.
Application:
End-use thermal performance thresholds create tiered pricing structures, with high-heat automotive applications insulating suppliers from polyamide 6 substitution pressures.
- Textiles:Nylon-66 precursor demand for technical fibers and industrial yarns. Chinese and Indian manufacturing clusters are deepening specification-grade procurement as domestic fiber production expands.
- Automotive:Underhood thermal management components in electric vehicle platforms require high-heat polymer grades. ECHA REACH compliance deadlines accelerate reformulation cycles among European tier-1 compounders.
- Consumer Goods:Packaging films and molded components where cost-performance tradeoffs favor adipamide-derived grades.
- Industrial Coatings:Corrosion-resistant finishes and lubricant additives subject to EPA TSCA Section 5 pre-manufacture notification requirements.
Automotive applications generate the steepest expansion trajectory, while textiles retain the largest installed base.
End Use Industry:
Industry verticals impose divergent purity benchmarks, with electronics and medical segments demanding certificate-of-analysis interoperability that commodity fiber producers can bypass.
- Fiber Production:Nylon-66 polymerization for technical textiles and carpet yarns. BIS certification requirements in India add qualification layers for suppliers targeting this expanding production base.
- Plastics Manufacturing:Engineering resin compounding for automotive and industrial components. Greenville and Chattanooga polymer clusters in the US Southeast negotiate direct mill-to-compounder offtake agreements.
- Electronics:High-purity grades for connector housings and circuit board substrates. Inline Raman spectroscopy monitoring is compressing deviation response times from hours to minutes.
- Construction:Geotextiles and structural reinforcement applications with moderate purity requirements.
Fiber production commands the dominant share, with electronics gaining share fastest.
Distribution Channel:
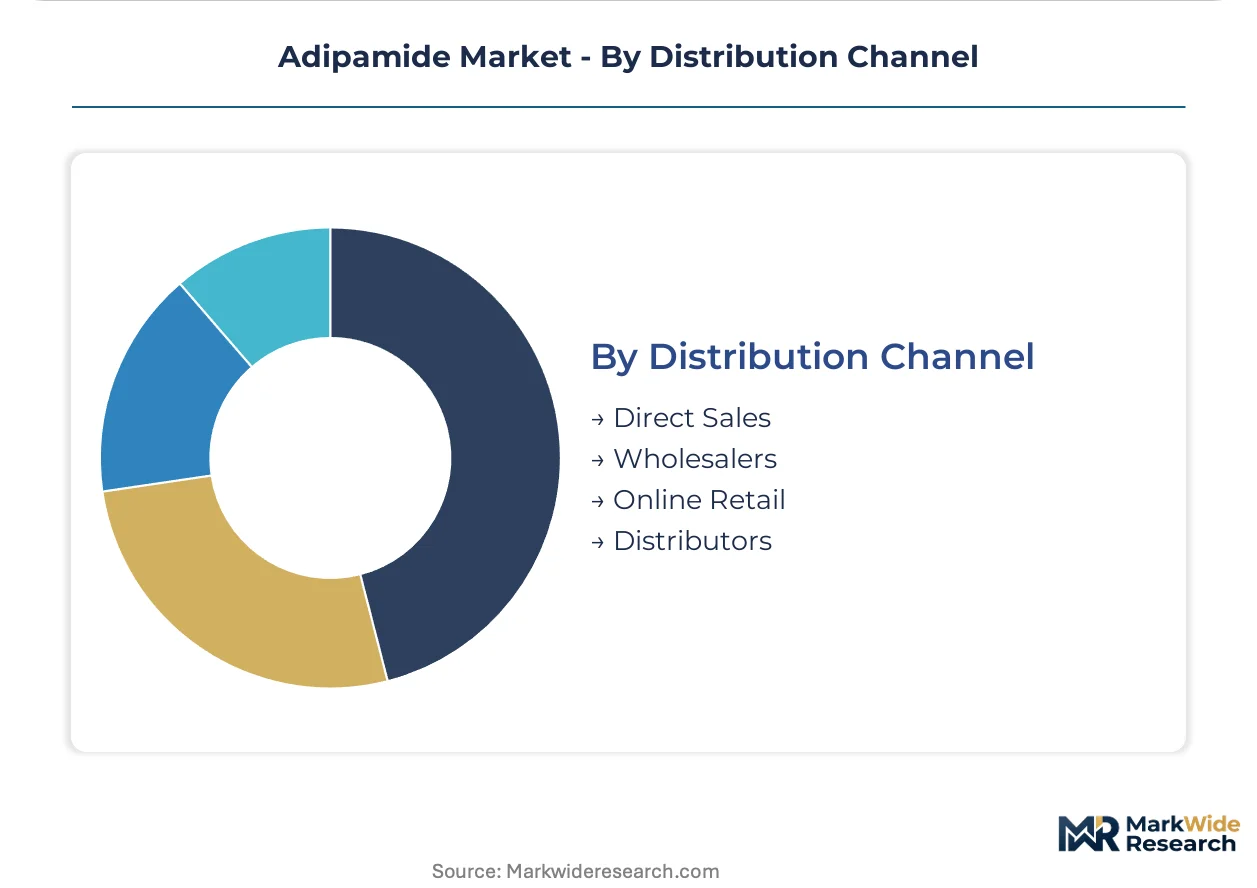
Channel selection reflects order scale and certification burden, with blockchain-verified certificate-of-analysis data interoperability consolidating buyer power among tier-1 automotive suppliers.
- Direct Sales:Long-term offtake agreements between adipamide producers and high-volume compounders. Ascend Performance Materials anchors this channel in North America through vertically controlled hexamethylenediamine feedstock.
- Wholesalers:Inventory-buffered supply for mid-sized textile processors with predictable consumption patterns.
- Online Retail:Modular pre-weighed batch containers opening procurement access for compounders previously excluded by minimum order quantity barriers.
- Distributors:Traditional intermediaries facing displacement as direct relationships expand; surviving distributors consolidate EPA-registered supplier qualification dossiers.
Direct sales dominate value capture, with online retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered industrial adipamide production during the mid-20th century nylon expansion, establishing the technical specifications and purity benchmarks that still govern qualification protocols across automotive and fiber markets today.
Germany
Automotive underhood polymer demand from BMW and Mercedes-Benz EV platforms pulls specification-grade volumes through ECHA REACH-compliant supply chains. The country's national chemical regulator enforces substance registration deadlines that accelerate reformulation cycles among Ludwigshafen-area compounders. Bavarian industrial clusters around Munich and Nuremberg host tier-1 suppliers negotiating direct mill-to-compounder offtake agreements with adipamide producers.
United States
EPA TSCA Section 5 pre-manufacture notification requirements tighten oversight for adipamide derivatives in lubricant applications, extending review timelines for novel formulations. Greenville and Chattanooga polymer compounding clusters in the Southeast negotiate long-term supply agreements bypassing traditional distributor intermediaries. Ascend Performance Materials anchors the direct-sales channel through captive hexamethylenediamine feedstock security.
China
Domestic fiber production expansion in technical textiles drives powder-grade adipamide procurement under MIIT industrial upgrading guidelines. The Ministry of Ecology and Environment enforces dual carbon goals that reshape energy-intensive chemical process economics. Yangtze River Delta manufacturing clusters around Shanghai deepen specification-grade supply relationships with European qualified suppliers.
India
BIS certification requirements add qualification layers for suppliers targeting the country's expanding technical fiber production base under PLI scheme incentives. The Bureau of Indian Standards mandates purity thresholds that extend product launch windows for new market entrants. Maharashtra and Gujarat textile manufacturing clusters attract adipamide qualification investments from East Asian suppliers seeking production-linked incentive benefits.
Japan
Electronics-grade coating applications requiring ppm-level impurity control sustain premium positioning for solution-format adipamide. METI industrial standards govern high-purity chemical specifications for connector housing and circuit board substrate manufacturers. Kanto-region precision chemical clusters around Tokyo deploy inline Raman spectroscopy monitoring systems compressing deviation response times.
Adipamide Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive feedstock positions. European and North American producers dominate specification-grade qualification through vertically controlled supply chains, while Asian manufacturers compete on volume scale in textile precursor segments. Three archetypes define positioning: integrated caprolactam chain operators, specialty high-heat polymer compounders, and regional fiber-grade volume suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake agreements to lock in automotive qualification status.
Among integrated chemical conglomerates, BASF SE and Evonik Industries exemplify the European archetype of REACH-compliant specification-grade supply. DuPont occupies a position on the premium-tier vector for high-temperature automotive underhood applications. Ascend Performance Materials anchors the North American direct-sales channel structure through backward integration into hexamethylenediamine feedstock production.
| Leading Market Players |
|---|
| BASF SE |
| Asahi Kasei Corporation |
| DuPont |
| Invista |
| Toray Industries |
| Evonik Industries |
| Ascend Performance Materials |
| LANXESS |
| Teijin Limited |
| Others |
Value Network & Pricing Analysis
REACH substance registration deadlines in Europe gate both qualified supply access and premium-tier pricing power, forcing non-integrated producers to absorb certification cost burdens while integrated caprolactam chain operators capture specification-grade margins. This regulatory filter compresses margin structures for spot-market suppliers even as automotive compounders absorb higher prices for ECHA-compliant volumes.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume transactions between adipamide producers and tier-1 automotive compounders, with pricing stratifying across pharmaceutical-grade, automotive-specification, and textile-economy tiers. Price differentiation hinges on REACH certification status and captive hexamethylenediamine feedstock security. Cost compression in textile-grade powder formats is intensifying because Indian PLI scheme incentives attract new capacity entrants. Fiber producers in China and India exhibit highest price sensitivity, while German automotive compounders prioritize qualification security over unit cost.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Greenville, and Shanghai anchor hub-and-spoke delivery patterns for specification-grade adipamide, with inventory positioning tied to OEM just-in-sequence requirements. Supply concentrates in Germany, the United States, and China, with production economics drawing from cyclohexane, ammonia, and hexamethylenediamine feedstock streams. Single-source vulnerability around pharmaceutical-grade capacity in German and Belgian clusters exposes qualified supply chains to geographic disruption. Distribution runs through direct mill-to-compounder channels for high-volume automotive contracts, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adipamide market margins are expanding through medical-polymer pellet premiumization and continuous process intensification that compresses per-unit conversion costs. Specification-grade qualification barriers protect pricing power for integrated producers while opening white-space at format and packaging innovation layers.
For Market Incumbents: Cement automotive qualification status through REACH dossier maintenance and inline Raman spectroscopy deployment that compresses deviation response times. Polyamide 6 substitution pressure in textile applications demands capacity reallocation toward underhood thermal management grades. Backward integration into hexamethylenediamine feedstock secures margin stability against cyclohexane price volatility. For New Entrants and Emerging Players: Begin with modular pre-weighed batch container formats that bypass minimum order quantity barriers excluding mid-sized compounders from qualified supply. Medical-polymer pellet segments in USP-grade niches present the most penetrable premium tier. Direct online retail channels open procurement access without distributor qualification overhead. For Investors and Strategic Acquirers: Roll-up economics work for regional fiber-grade volume suppliers because BIS, EPA, and ECHA certification timelines extend product launch windows by 18-24 months, consolidating buyer power among incumbent qualified producers. Targets should demonstrate captive feedstock positions or specialty high-heat polymer compounding relationships. The signal to watch is automotive OEM zero-defect protocol adoption rates that accelerate specification-grade procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive hexamethylenediamine production insulates Ascend Performance Materials from Asian spot market cyclicality. |
| Continuous Process Intensification | Real-time Raman spectroscopy monitoring compresses German automotive compounder deviation response from hours to minutes. |
| Long-term Supply Agreement | Direct mill-to-compounder offtake contracts in Greenville and Chattanooga displace traditional distributor intermediaries. |
| Green Manufacturing Transition | China MIIT dual carbon goals reshape energy-intensive ammonolysis process economics in Yangtze River Delta clusters. |
| Capacity Expansion | Indian PLI scheme incentives attract European and East Asian adipamide qualification investments in Maharashtra textile manufacturing zones. |
Research Methodology
Direct dialogue with adipamide plant managers, procurement leads at nylon-66 fiber producers, distribution channel partners, and technical R&D directors anchored qualitative grounding across the value chain. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up and top-down triangulation reconciled volume estimates from production capacity assessments with demand-side consumption modeling across end-use segments.
Bottom-up modeling tracked grade-tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. Top-down approaches validated aggregate market sizing through macroeconomic elasticity coefficients and polymer precursor demand correlations. CAGRs were derived from segment-level growth rate reconciliation against historical trend baselines. Forecast inputs incorporated automotive lightweighting program timelines and electric vehicle platform thermal management content trajectories.
Several conditions sit outside the modeled scope, including force majeure disruptions to cyclohexane supply chains, abrupt REACH substance restriction amendments, and currency fluctuation effects on cross-border procurement economics. Forecasts reflect documented assumptions around regulatory compliance timeline adherence and OEM qualification protocol stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Paraben Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Citrate Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Trimer Acid Market