
 Global Glutamic Acid Market | 2026-2036
Global Glutamic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glutamic Acid Market Analysis
Pharmaceutical applications are recalibrating demand composition across the glutamic acid value chain. Ajinomoto Co., Inc. leverages its fermentation technology leadership to anchor supply contracts with biotech end users. Evonik Industries AG sustains a differentiated position through pharmaceutical-grade purity capabilities. Kyowa Hakko Bio Co., Ltd specializes in amino acid derivatives for cell culture media, competing with Sichuan Tongsheng Amino Acid Co., Ltd on feed-grade volume in domestic Chinese channels.
Glutamic acid is a non-essential alpha-amino acid with the molecular formula C₅H₉NO₄, produced industrially through Corynebacterium glutamicum fermentation at titers exceeding 150 g/L. It functions primarily as a flavor enhancer precursor, pharmaceutical intermediate, and chelating agent in agricultural formulations. Food Seasoning applications dominate value capture due to MSG downstream demand, though Pharmaceutical-grade segments command premium pricing through USP and EP certification requirements. Powder and Granular forms lead volume throughput, while Liquid formulations are expanding fastest in automated animal feed blending systems across integrated protein operations.
FDA food additive regulations under 21 CFR 182.1045 and EPA effluent guidelines for fermentation facilities shape US manufacturing compliance costs. China's SAMR enforces GB 2760 standards on food-grade glutamic acid, while REACH registration requirements in Europe constrain import volumes from non-registered Asian producers. EMA's ICH Q3D guidelines on elemental impurities further tighten pharmaceutical-grade specifications. Stakeholders must monitor regulatory divergence between feed-grade and food-grade certification pathways to optimize capacity allocation.
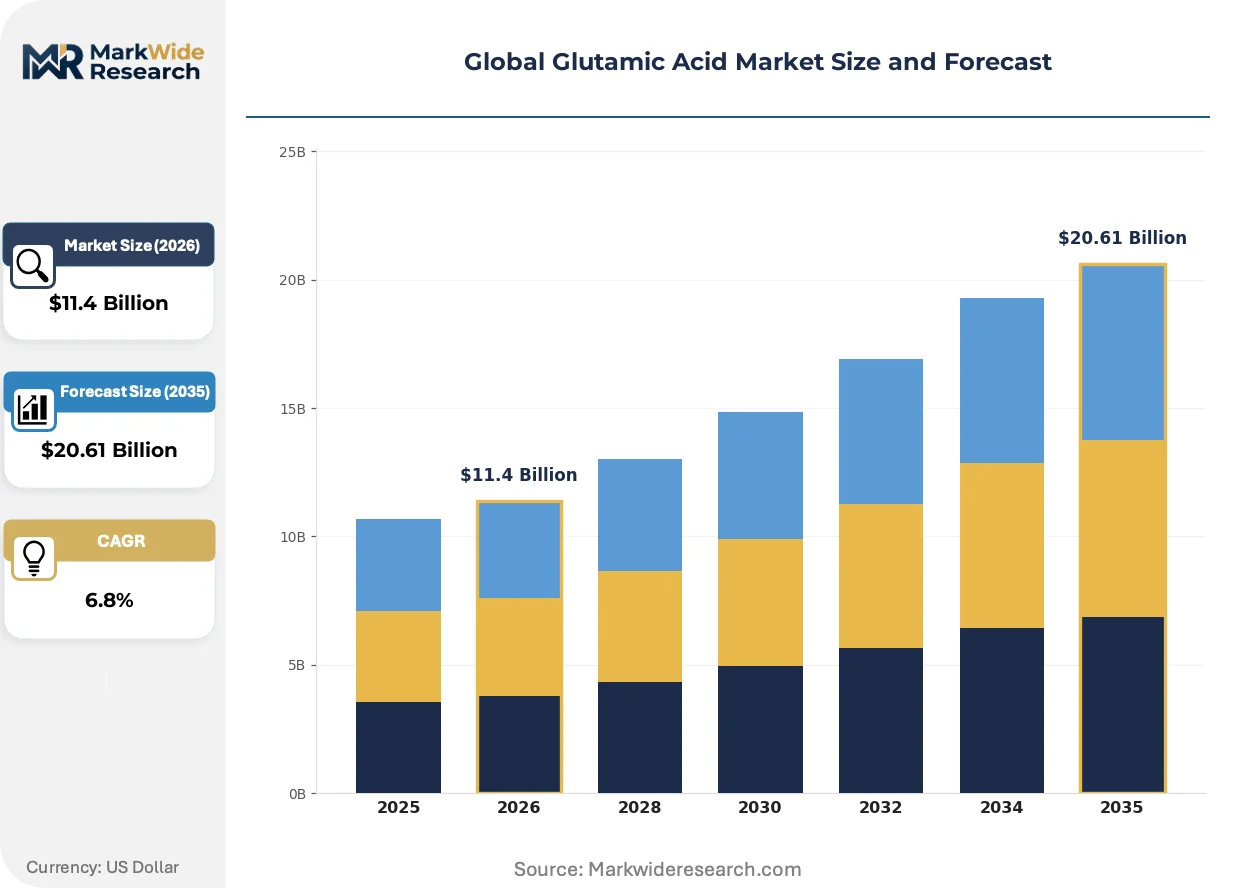
Market Dynamics
Fermentation titers exceeding 150 g/L from Corynebacterium glutamicum strains are compressing unit economics while China's NMPA food additive tightening redirects export flows toward industrial and feed-grade channels. This bifurcation between pharmaceutical certification pathways and commodity volume markets defines current capacity allocation decisions.
Growth Catalysts
- Cell culture media expansion:Biotech formulators are scaling amino acid derivative procurement for monoclonal antibody production, pulling pharmaceutical-grade volumes into long-term supply contracts with fermentation specialists.
- GB 2760 enforcement:China's SAMR food-grade standards are accelerating feed-grade channel development as exporters pivot toward animal nutrition applications with lower certification burdens.
- Automated feed blending:Liquid glutamic acid formulations are penetrating integrated protein operations across Brazil and Vietnam, displacing manual powder handling in large-scale poultry and aquaculture facilities.
Market Restraints
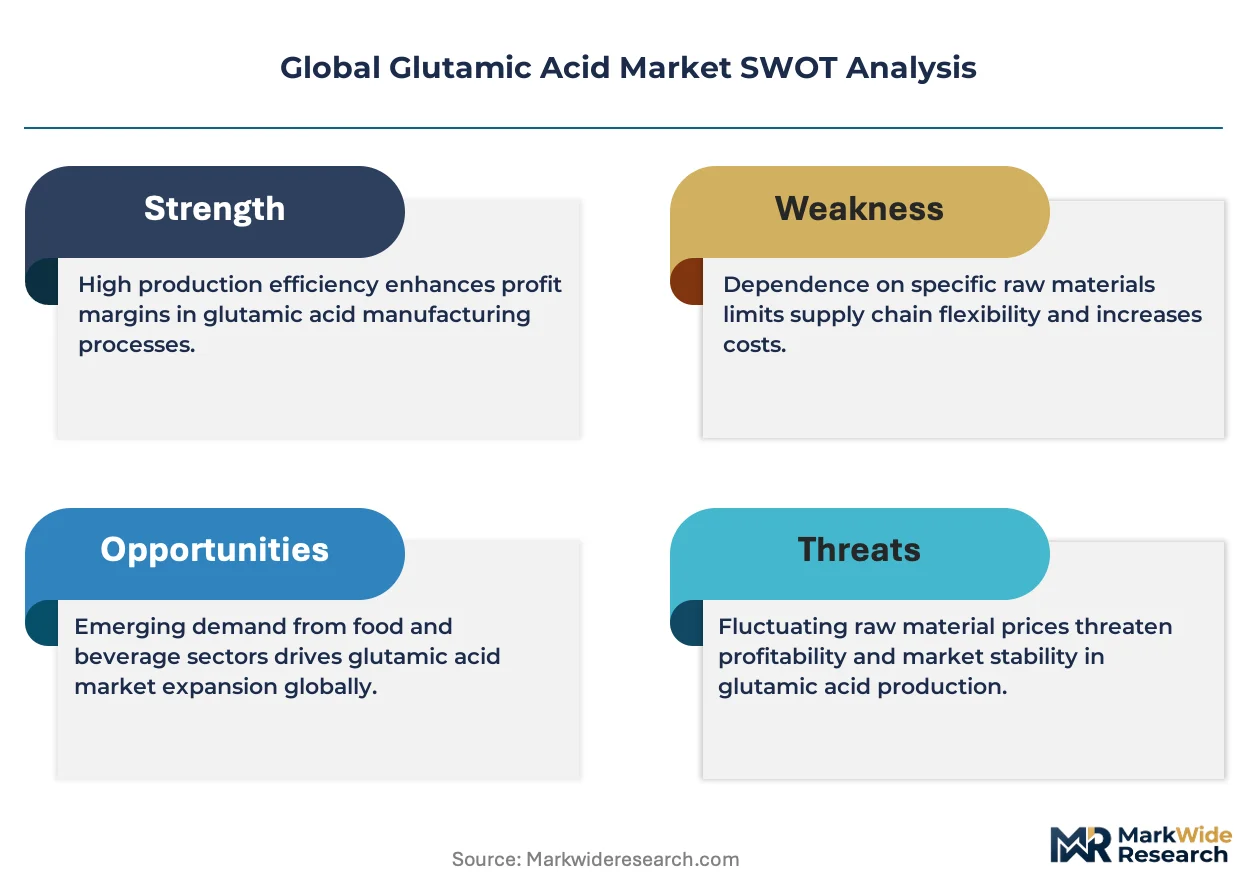
- Raw material volatility:Corn steep liquor and molasses feedstock costs fluctuate with Brazilian and US harvest cycles, squeezing margin stability for non-integrated fermentation operators.
- Supply concentration:Shandong and Jiangsu provinces control disproportionate fermentation capacity, creating geographic risk exposure for buyers dependent on Chinese export volumes.
- ICH Q3D compliance costs:EMA elemental impurity guidelines impose analytical and purification investments that price smaller producers out of pharmaceutical-grade segments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO and PLI scheme incentives for active pharmaceutical ingredient localization create demand for USP-certified glutamic acid among domestic biotech formulators.
- Chelation agriculture:Micronutrient fertilizer formulations in Brazil and Argentina are absorbing technical-grade volumes as farmers adopt amino acid-based metal complexing agents.
- Bioplastics feedstock:Polyglutamic acid production for biodegradable packaging is expanding into Japanese and South Korean materials science supply chains.
Industry Challenges
- Pharmaceutical certification timelines:USP and EP validation cycles extend 18-24 months, locking working capital and delaying revenue recognition for grade-transitioning producers.
- Fermentation specialist scarcity:Corynebacterium strain optimization and downstream purification expertise concentrates among aging technical workforces in East Asian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glutamic Acid Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Granular, Powder, Liquid, Crystal Application: Beverages, Agricultural Fertilizers, Pharmaceuticals, Food Seasoning End User: Food Industry, Agriculture, Animal Feed, Biotechnology Purity Grade: food grade, feed grade, pharmaceutical grade, industrial grade |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Kyowa Hakko Bio Co., Ltd, Sichuan Tongsheng Amino Acid Co., Ltd, Akzo Nobel N.V., Global Bio-chem Technology Group Company, Suzhou Yuanfang Chemical Co., Ltd., Fufeng Group, CJ CheilJedang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glutamic Acid Market Emerging Trajectories
Continuous fermentation systems and single-use bioreactor technologies are displacing batch processing economics while regulatory divergence between food-grade and pharmaceutical-grade pathways fragments certification strategies across producer portfolios.
Cell-free enzymatic synthesis from glucose is expanding into pilot-scale glutamic acid production, offering route flexibility independent of live culture viability. Specialty chemical manufacturers in Germany and the Netherlands are evaluating this platform for pharmaceutical-grade output where sterility assurance demands exceed conventional fermentation capabilities. The technology is expanding into contract manufacturing relationships as brand owners seek supply security outside concentrated Asian fermentation clusters.
REACH registration requirements for imported amino acids are tightening documentary burdens on non-European producers seeking European pharmaceutical and food-grade market access. ECHA substance evaluation workflows now routinely request extended analytical datasets on fermentation-derived impurities. German and French formulators are responding by qualifying registered suppliers earlier in procurement cycles, compressing competitive windows for unregistered Asian volume exporters.
Biotech end-users are consolidating amino acid procurement under direct fermentation partnerships rather than distributor-mediated spot purchasing. Large-scale cell culture media producers in Massachusetts and North Carolina are negotiating captive offtake agreements with specific fermentation facilities. This concentration is most visible in US coastal biotech corridors where supply assurance outweighs price optimization in sourcing decisions.
Global Glutamic Acid Market Segmentation
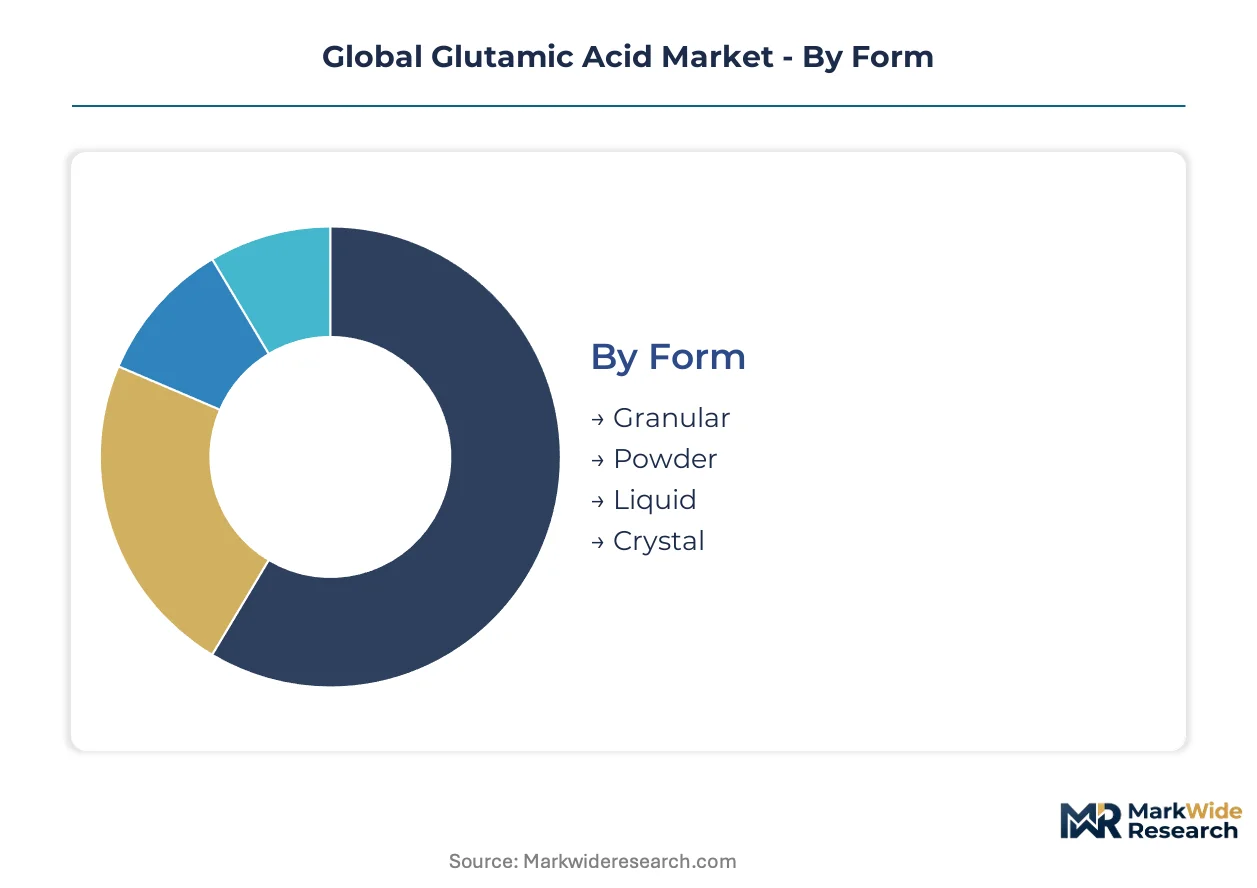
Glutamic acid segmentation reflects divergent certification burdens and handling requirements across downstream channels. Pharmaceutical-grade specifications command extended validation timelines, while feed-grade volumes prioritize logistics efficiency over analytical rigor.
Form:
Customization intensity spans from engineered dissolution profiles to commodity bulk handling, with automation compatibility driving specification divergence.
- Powder:Fine particulate morphology enables rapid dissolution in aqueous media and uniform distribution in dry-blend formulations. Demand concentrates in Chinese food seasoning manufacturing clusters across Shandong province, where MSG precursor integration requires consistent particle size distribution.
- Liquid:Pumpable aqueous solutions eliminate dust exposure and enable automated dosing in continuous processing environments. Brazilian and Vietnamese integrated poultry operations are absorbing volumes fastest as manual powder handling phases out in large-scale protein facilities.
- Granular:Free-flowing agglomerated particles reduce caking during bulk storage and pneumatic conveying. Agricultural fertilizer blenders favor this form for micronutrient chelation applications.
- Crystal:High-purity recrystallized material meets USP and EP visual inspection standards for pharmaceutical intermediate use.
Leading the category by volume: Powder. Growing fastest: Liquid.
Application:
Margin structure stratifies sharply between certification-intensive pharmaceutical pathways and commodity food additive channels.
- Food Seasoning:MSG precursor demand anchors volume throughput, with fermentation-derived material processed into flavor enhancers for Asian and Latin American consumer markets. Downstream integration with Ajinomoto and Fufeng Group manufacturing networks in China and Thailand locks in long-term offtake.
- Pharmaceuticals:USP and EP-certified material serves as chiral building block for synthetic peptide manufacturing and cell culture media supplementation. Massachusetts and North Carolina biotech corridors are pulling pharmaceutical-grade volumes into direct fermentation partnerships rather than distributor-mediated procurement.
- Agricultural Fertilizers:Technical-grade glutamic acid functions as chelating agent for micronutrient delivery in Brazilian and Argentine row crop operations.
- Beverages:Acidulant and flavor modifier applications in sports and functional drinks, primarily in Southeast Asian formulation facilities.
Food Seasoning dominates absolute volume. Pharmaceuticals generate steepest margin expansion.
End User:
Customer sophistication ranges from pharmaceutical GMP compliance to agricultural spot purchasing with minimal specification overhead.
- Food Industry:Processed food manufacturers and seasoning compounders integrate glutamic acid as direct MSG precursor or flavor potentiator. Chinese processors under SAMR GB 2760 enforcement are redirecting volumes toward export markets with less stringent additive documentation.
- Biotechnology:Cell culture media producers and peptide synthesis operations require elemental impurity profiles meeting ICH Q3D guidelines. German and Dutch formulators are qualifying registered suppliers earlier in procurement cycles to satisfy REACH documentary burdens.
- Animal Feed:Integrated protein operations across Brazil and Vietnam utilize liquid formulations for automated amino acid supplementation in poultry and aquaculture diets.
- Agriculture:Micronutrient fertilizer manufacturers incorporate technical-grade material as biodegradable chelating alternative to synthetic EDTA complexes.
Food Industry commands largest volume share. Biotechnology exhibits fastest contract value expansion.
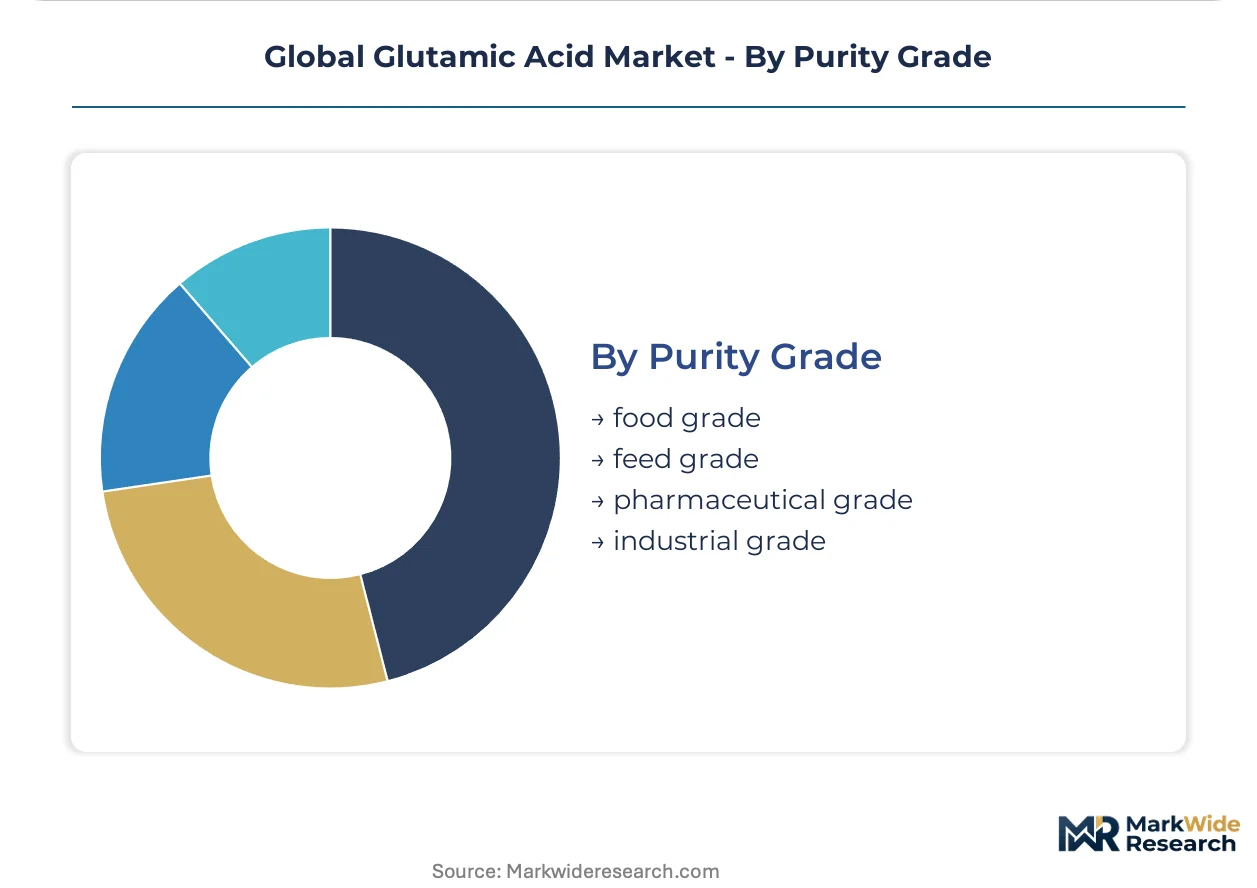
Purity Grade:
Certification tier determines analytical investment, regulatory filing burden, and permissible end-use applications.
- Pharmaceutical Grade:USP and EP monograph compliance with ICH Q3D elemental impurity limits enables API and excipient applications. EMA guidelines impose 18-24 month validation cycles that lock working capital and price smaller producers out of this segment.
- Food Grade:GB 2760 and FDA 21 CFR 182.1045 compliance for direct food additive use. China's NMPA tightening is compressing export volumes as domestic enforcement redirects material toward lower-certification channels.
- Feed Grade:Reduced analytical burden suitable for animal nutrition applications. Exporters are pivoting volumes here to circumvent food-grade documentation requirements.
- Industrial Grade:Technical specifications for chelation, polymer synthesis, and biodegradable packaging feedstocks. Polyglutamic acid production for Japanese and South Korean bioplastics is expanding absorption.
Feed Grade leads volume throughput. Pharmaceutical Grade achieves highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate fermentation capacity through tax incentives and subsidized utilities, anchoring global glutamic acid supply. Shandong and Jiangsu provinces house Corynebacterium strain optimization facilities serving downstream MSG and pharmaceutical derivative channels.
China
Shandong province fermentation clusters process corn steep liquor feedstock into food-grade and pharmaceutical-grade volumes. SAMR's GB 2760 enforcement redirects export flows toward feed-grade channels with lower documentation burdens. Jiangsu province facilities specialize in USP-certified material for biotech formulators in Massachusetts and North Carolina.
United States
FDA 21 CFR 182.1045 compliance shapes domestic food additive manufacturing while EPA effluent guidelines raise fermentation facility compliance costs. Coastal biotech corridors in Massachusetts and North Carolina negotiate direct offtake agreements with Asian fermentation specialists for cell culture media applications.
Germany
REACH registration requirements constrain import volumes from non-registered Asian producers, favoring ECHA-registered suppliers in procurement cycles. Evonik Industries AG maintains pharmaceutical-grade purification capabilities serving synthetic peptide manufacturers across Baden-Württemberg and North Rhine-Westphalia.
Japan
METI industrial policy supports polyglutamic acid production for biodegradable packaging feedstocks in Kansai manufacturing clusters. Ajinomoto Co., Inc. leverages fermentation technology leadership to anchor supply contracts with domestic and international biotech end users. Kanto region facilities specialize in amino acid derivatives for cell culture media.
Brazil
ANVISA regulations on food additives align with Mercosur standards, creating certification overlap with Argentine import requirements. Integrated poultry operations in São Paulo and Paraná absorb liquid glutamic acid formulations for automated feed blending systems. Agricultural fertilizer blenders incorporate technical-grade material as micronutrient chelating agents in row crop operations.
Global Glutamic Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered barriers to entry. Food-grade and feed-grade channels tolerate greater supplier fragmentation due to lower analytical investment requirements. Three archetypes dominate: integrated fermentation specialists with captive strain libraries, purity-focused pharmaceutical-grade processors, and volume-oriented commodity producers serving regional MSG and animal nutrition markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers seek supply security outside concentrated Chinese manufacturing clusters.
Among Japanese fermentation specialists, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd exemplify the integrated archetype through Corynebacterium strain optimization capabilities. German pharmaceutical-grade processor Evonik Industries AG occupies a differentiated position serving synthetic peptide and cell culture media channels. Chinese volume producers including Sichuan Tongsheng Amino Acid Co., Ltd and Fufeng Group represent the commodity-scale tier, competing on feed-grade volume in domestic and export channels.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Kyowa Hakko Bio Co., Ltd |
| Sichuan Tongsheng Amino Acid Co., Ltd |
| Akzo Nobel N.V. |
| Global Bio-chem Technology Group Company |
| Suzhou Yuanfang Chemical Co., Ltd. |
| Fufeng Group |
| CJ CheilJedang |
| Others |
Supply Flow & Price Mechanics
Family-owned fermentation specialists across China's Shandong province anchor supply discipline through captive corn steep liquor sourcing, translating feedstock control into pricing power over spot-dependent competitors. This ownership structure reinforces margin stability when molasses costs swing with Brazilian harvest cycles.
Pricing Analysis
Short lead-time premiums separate pharmaceutical-grade spot buyers from contract-anchored volume purchasers in cell culture media channels. Contract-based long-term offtake dominates the market, with price differentiation resting on USP certification tier and automated feed-blending compatibility. Cost compression in feed-grade volumes is intensifying because exporters pivot from China's tightening GB 2760 enforcement. Biotechnology formulators show least price sensitivity; commodity food seasoning processors absorb maximum pricing pressure.
Supply Chain Analysis
Direct-to-biotech-formulator channels handle Massachusetts and North Carolina cell culture media demand, bypassing distributor markups. Supply concentrates in China, Japan, and Germany, drawing from corn steep liquor, molasses, and purified water feedstocks. Single-source vulnerability runs through Shandong province's Corynebacterium strain optimization facilities. Distribution runs through integrated fermentation partnerships rather than spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation capacity for USP-certified material props pricing across pharmaceutical-grade channels, constraining volume expansion regardless of downstream demand pull.
For Market Incumbents: Hedge against Chinese regulatory divergence by qualifying dual-grade production lines capable of pivoting between food-grade and feed-grade certification. Anchor strain optimization capabilities in Jiangsu province facilities to defend against cell-free enzymatic synthesis substitution. Prioritize captive offtake negotiations with Massachusetts biotech corridors over distributor-mediated spot sales. For New Entrants and Emerging Players: Begin with Indian pharmaceutical manufacturing under CDSCO and PLI scheme incentives, where domestic API localization creates unserved demand for USP-certified glutamic acid. Target chelation agriculture applications in Brazilian micronutrient fertilizer formulations as the most penetrable technical-grade outlet. Pursue contract manufacturing relationships with Japanese materials science firms seeking polyglutamic acid feedstock security. For Investors and Strategic Acquirers: EMA's ICH Q3D enforcement timeline acceleration is the leading indicator that pharmaceutical-grade purification capabilities will command scarcity premiums across the analysis window. Acquisition candidates should display registered REACH status plus Corynebacterium strain libraries. Watch for CDSCO localization mandates as the signal that Indian pharmaceutical-grade demand is structurally shifting from import-dependent to domestic-sourced.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Steep Liquor Sourcing | Captive feedstock supply from US Midwest grain processing insulates margin volatility from Brazilian harvest cycles. |
| Pharmaceutical-Grade Certification Investment | USP and EP validation cycles lock working capital but secure premium positioning against commodity-grade competitors. |
| Long-term Supply Agreement with Biotech Formulators | Direct offtake contracts with Massachusetts cell culture media producers displace distributor-dependent spot purchasing. |
| Joint Venture in Indian API Manufacturing | CDSCO and PLI scheme alignment positions domestic fermentation capacity for localized pharmaceutical-grade demand. |
| Green Manufacturing Transition for Polyglutamic Acid | METI-supported biodegradable packaging feedstocks in Kansai clusters absorb technical-grade volumes from diversifying producers. |
Methodological Framework
SEC 10-K filings, ECHA registration databases, and customs/trade data formed the secondary backbone, cross-referenced against primary interviews with fermentation plant managers, biotech procurement leads, and amino acid distribution channel partners. Bottom-up and top-down triangulation validated volume estimates across grade tiers and regional production hubs.
Bottom-up modeling anchored projections in fermentation titer economics and capacity utilization rates across Shandong and Jiangsu province facilities. Segmentation dimensions span purity grade, form factor, end-use industry, and regional regulatory cluster. CAGRs were derived from weighted capacity expansion timelines and substitution elasticity estimates for cell-free enzymatic synthesis platforms.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than feed-grade spot market estimates due to longer validation visibility. Forecasts reflect assumptions around NMPA enforcement trajectory and EMA ICH Q3D implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Paraben Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Citrate Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Lauric Acid Market