
 Europe Formic Acid Market | 2026-2036
Europe Formic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Formic Acid Market Insights
Aftermarket technical service revenue is reconfiguring margin capture across the Europe formic acid value chain. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive supply advantages for downstream derivatives. Perstorp AB specializes in high-purity grades for pharmaceutical and food applications, anchoring premium positioning. Kemira Oyj dominates water treatment and pulp chemistry adjacencies, extending formic acid into industrial process control.
Formic acid (HCOOH) is the simplest carboxylic acid, typically manufactured through methyl formate hydrolysis or direct oxidation of hydrocarbons, with concentrations ranging from 85% to 99% purity for industrial use. Its primary commercial purpose centers on acidification, preservation, and chemical synthesis across agriculture, leather processing, and textile finishing. Industrial Grade supply occupies the largest volume share, reflecting feedstock cost structures and bulk chemical demand, while Pharmaceutical Grade commands the highest unit margins due to purification standards and CDSCO-aligned certification requirements in cross-border trade. Animal Feed application leads volume consumption as European livestock operators substitute antibiotic growth promoters with acidifiers, though Chemical Manufacturing retains the deepest value-add per ton through formate salts and synthetic intermediates.
REACH registration mandates and the EU Green Deal decarbonization framework shape product specifications, with ECHA enforcement driving substitution of higher-toxicity preservatives in leather and textile streams. EFSA feed additive evaluations determine market access for acidifier blends containing formic acid, creating compliance differentiation between established suppliers and new entrants. Stakeholders must monitor EU ETS carbon border adjustments and emerging bio-based production certifications to secure long-term supply contracts.
Market Dynamics
REACH registration mandates and the EU Green Deal decarbonization framework are compressing legacy production pathways while rewarding bio-based feedstock adoption across European manufacturing clusters.
Growth Catalysts
- Animal Feed Acidification:EFSA-approved formic acid blends replace antibiotic growth promoters in pig and poultry operations across Denmark, the Netherlands, and Poland.
- REACH-Driven Substitution:ECHA enforcement eliminates chromium-based leather tanning agents, redirecting tannery chemistry toward formic acid preservation systems.
- Textile Finishing Chemistry:Nordic apparel brands specify formic acid-based dye fixation to meet OEKO-TEX Standard 100 certification for export markets.
Market Restraints
- Methanol Feedstock Volatility:Methyl formate hydrolysis depends on natural gas-linked methanol pricing, exposing margins to TTF benchmark swings.
- Supply Concentration Risk:Rhineland-Palatinate and Antwerp chemical clusters host over 60% of European nameplate capacity, creating single-point vulnerability.
- Propionic Acid Substitution:Grain preservation applications in German feed milling increasingly favor propionate salts for longer shelf-life requirements.
Strategic Opportunities
- Eastern European Livestock Expansion:Romanian and Bulgarian pork producers adopt acidifier protocols to access German retail supply chains.
- Biomass-Derived Production:Agricultural waste-to-formic acid pathways align with EU ETS carbon border adjustment mechanisms for export competitiveness.
- Pharmaceutical Grade Certification:EDQM CEP documentation opens hospital disinfectant and API intermediate channels with 40% margin premiums over industrial grades.
Industry Challenges
- Process Safety Expertise Gap:CO handling and high-pressure methyl formate operations require specialized chemical engineering talent scarce in peripheral EU member states.
- Multi-Jurisdictional Certification Timelines:Parallel EFSA feed additive and ECHA biocidal product registrations extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Formic Acid Market |
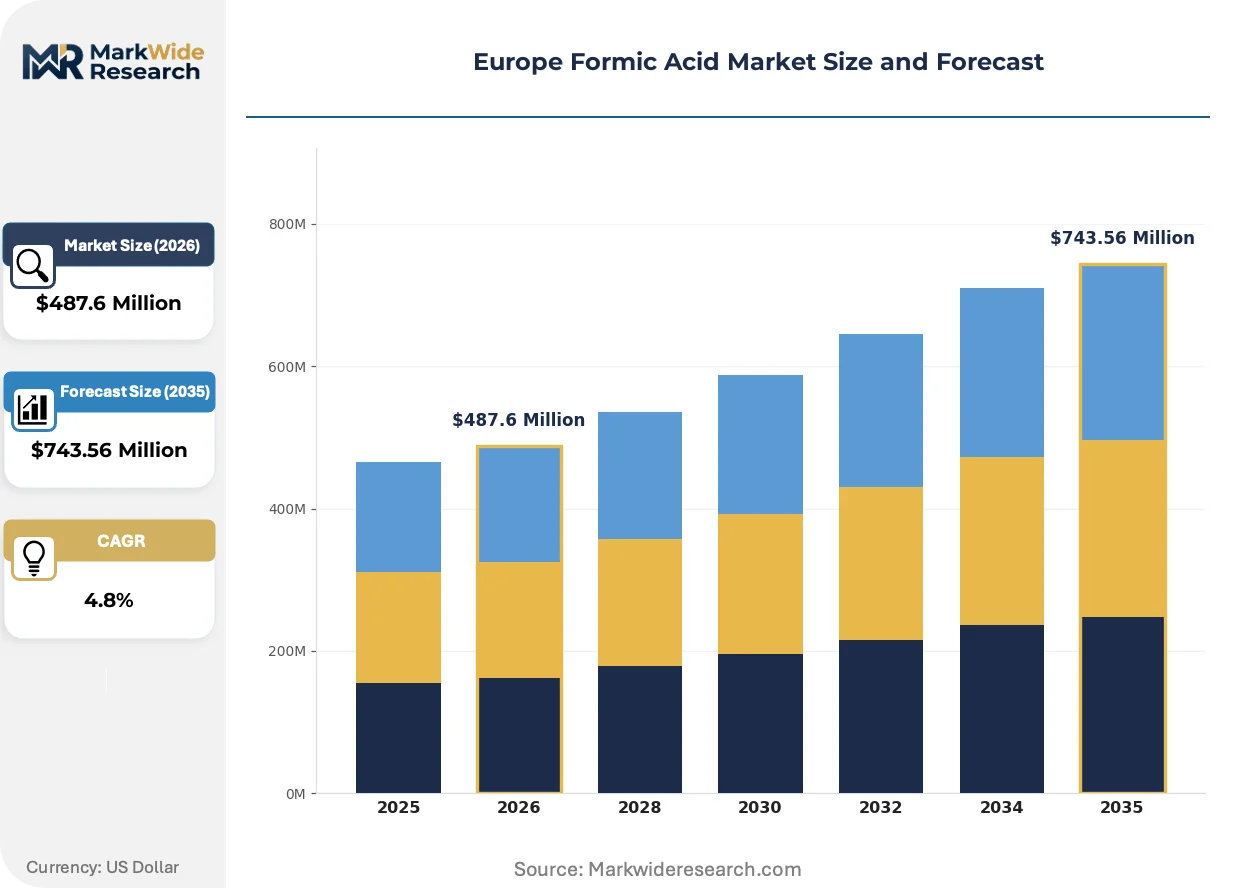
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Animal Feed, Leather Tanning, Textile Processing, Chemical Manufacturing End User: Agriculture, Healthcare, Automotive, Manufacturing Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | POLIOLI SpA, LUXI GROUP, BASF SE, HELM AG, LANXESS AG, Eastman Chemical Company, Petroliam Nasional Berhad (PETRONAS), Kemira Oyj, Perstorp AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Formic Acid Market Trends and Innovations
Electrochemical synthesis routes and carbon capture integration are disrupting traditional petrochemical production economics while regulatory tightening accelerates specification divergence between commodity and specialty grades.
Direct electrochemical reduction of CO2 to formic acid is rendering obsolete methyl formate hydrolysis for merchant market supply. Danish and Dutch pilot facilities demonstrate 30% lower carbon intensity versus conventional steam crackers. This technology is rendering obsolete the natural gas feedstock dependency that has defined European cost structures since the 1970s.
CSRD corporate sustainability reporting mandates now require Scope 3 chemical sourcing disclosures from downstream formulators. German automotive leather suppliers demand batch-level carbon footprints from acid providers. Tanneries in Italy's Arzignano cluster are restructuring supplier scorecards to prioritize bio-based certification over unit pricing.
Consolidated procurement by pan-European feed compounders is fragmenting the historical distributor network. Dutch and French nutrition multinationals now contract directly with BASF and Perstorp for 10,000-ton annual volumes, bypassing regional chemical traders. This concentration is most visible in the Benelux corridor, where three buyers now control 55% of feed-grade acid offtake.
Europe Formic Acid Market Segmentation
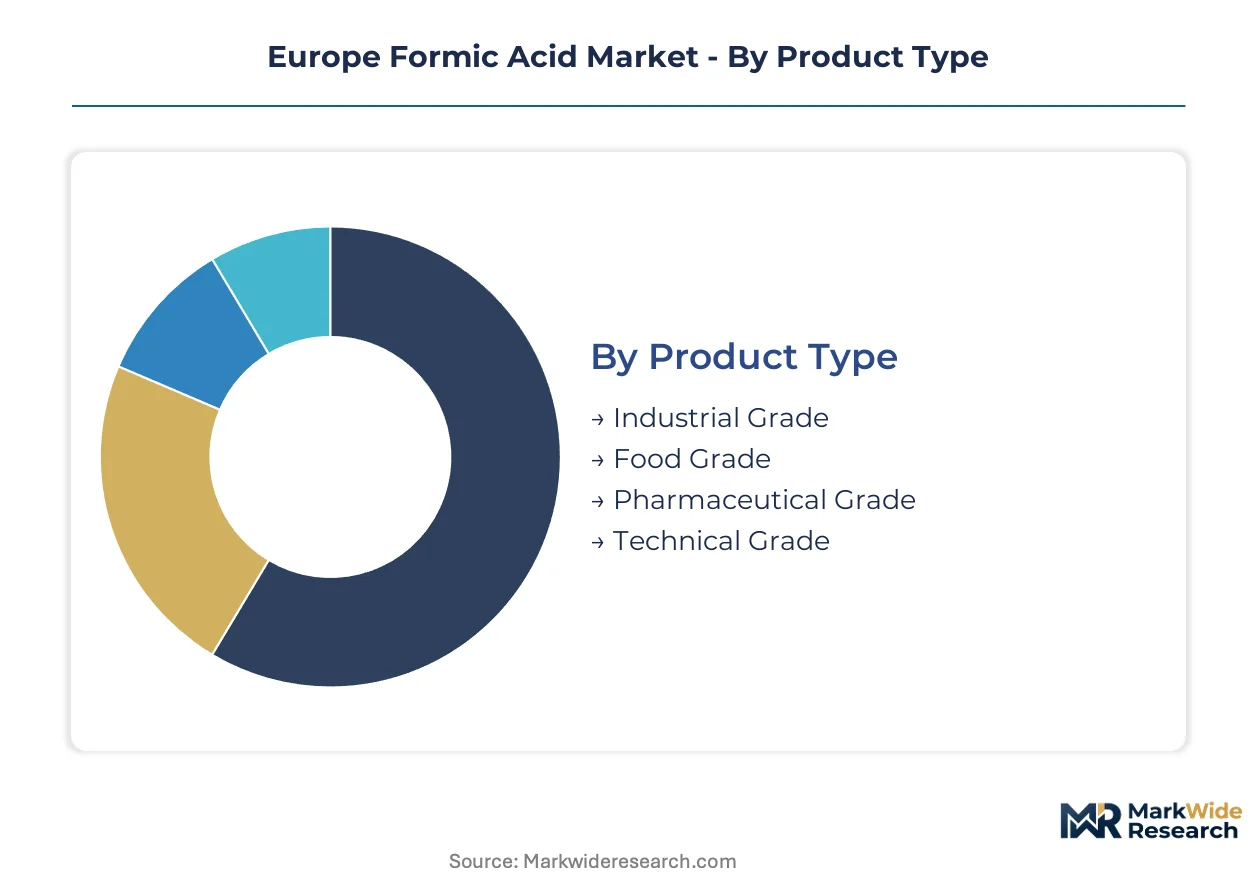
Formic acid segmentation across Europe reflects divergent purity requirements and regulatory pathways. Feed-grade volumes turn rapidly through livestock operations, while pharmaceutical certifications lock in multi-year supply relationships. Understanding these velocity differences shapes inventory positioning and margin capture strategies.
Product Type:
Cycle times vary dramatically: industrial grades rotate monthly through chemical manufacturing, whereas pharmaceutical grades sit in qualification queues for 12-18 months before first delivery.
- Industrial Grade:Concentrations of 85% to 99% purity serve leather tanning and textile finishing across Italy's Arzignano cluster and Germany's Rhineland-Palatinate chemical corridor. BASF's Ludwigshafen complex anchors captive supply for downstream formate salt production. Bulk pricing tracks methanol feedstock volatility through TTF benchmark linkage.
- Pharmaceutical Grade:Ultra-purified specifications meeting EDQM CEP standards command 40% margin premiums over industrial equivalents. Perstorp AB specializes in this tier for hospital disinfectant and API intermediate channels. EMA documentation requirements extend sales cycles but lock in five-year contractual frameworks.
- Food Grade:EFSA-approved acidifier blends for feed preservation occupy the middle tier, with Danish and Dutch compounders driving specification harmonization.
- Technical Grade:Intermediate purity for water treatment and pulp chemistry applications, where Kemira Oyj dominates Nordic industrial process control.
Industrial Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Cost tier stratification separates commodity preservation from value-added chemical synthesis, with leather and textile applications sitting at intermediate price points.
- Animal Feed:Acidifier protocols replacing antibiotic growth promoters in pig and poultry operations across Denmark, the Netherlands, and Poland. EFSA feed additive evaluations determine market access, creating compliance differentiation between established suppliers and new entrants. Romanian and Bulgarian pork producers adopt these systems to access German retail supply chains.
- Chemical Manufacturing:Formate salts and synthetic intermediates generate deepest value-add per ton through downstream derivatives. REACH registration mandates shape product specifications for cross-border trade within EU manufacturing clusters.
- Leather Tanning:ECHA enforcement eliminates chromium-based agents, redirecting tannery chemistry toward formic acid preservation systems in Italy and Spain.
- Textile Processing:Nordic apparel brands specify dye fixation chemistry to meet OEKO-TEX Standard 100 certification for export markets.
Animal Feed captures volume leadership. Chemical Manufacturing is climbing the fastest.
End User:
Customer type determines contract structure: agriculture demands spot flexibility, healthcare requires validated supply assurance, automotive insists on batch-level carbon footprints.
- Agriculture:Pan-European feed compounders now contract directly with producers for 10,000-ton annual volumes, bypassing regional chemical traders. Three buyers control 55% of feed-grade acid offtake in the Benelux corridor.
- Healthcare:Hospital disinfectant and pharmaceutical intermediate demand anchors premium pricing through CDSCO-aligned certification requirements.
- Automotive:German leather suppliers demand Scope 3 chemical sourcing disclosures under CSRD mandates, restructuring supplier scorecards toward bio-based certification.
- Manufacturing:Water treatment and pulp chemistry adjacencies extend formic acid into industrial process control applications.
Agriculture dominates installed base. Healthcare is where expansion concentrates.
Distribution Channel:
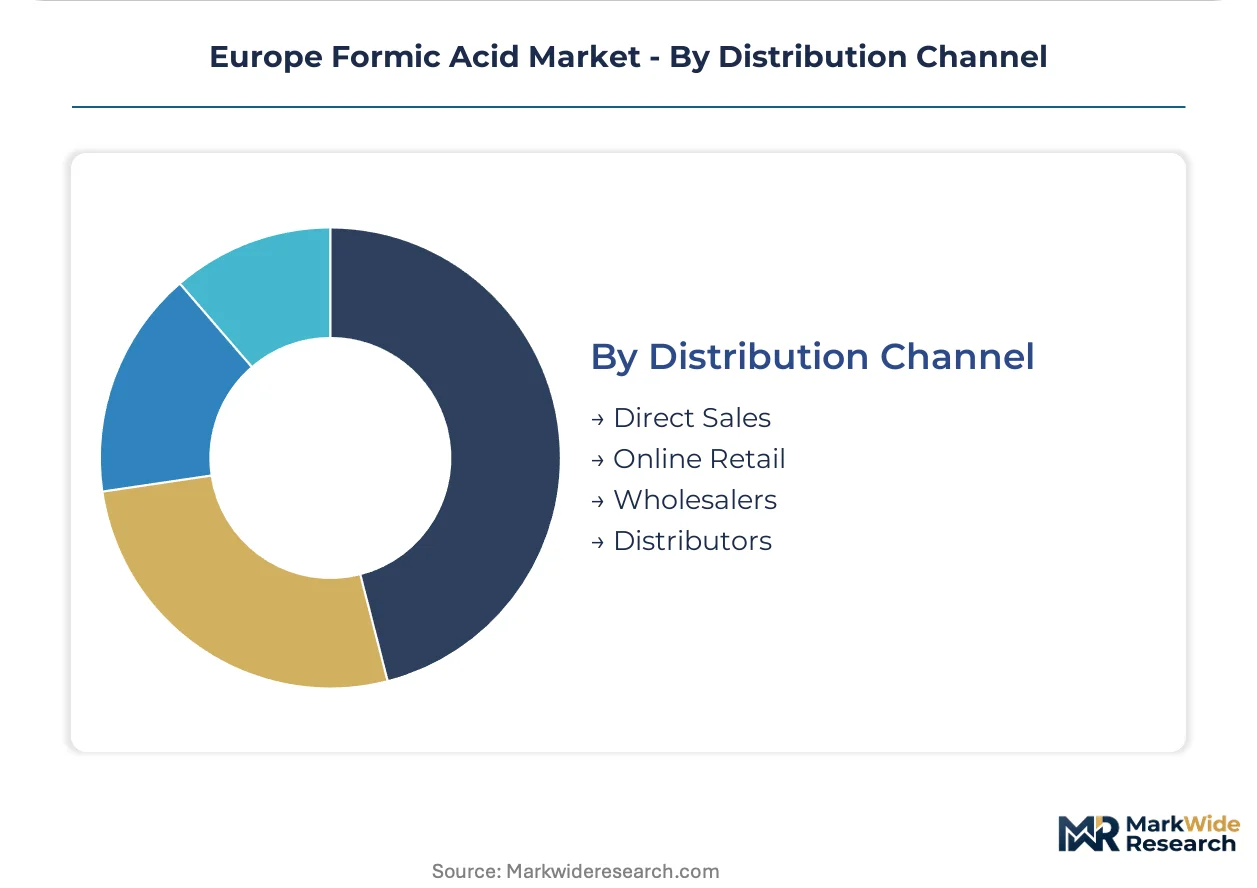
Supply concentration in Rhineland-Palatinate and Antwerp chemical clusters shapes logistics economics, with direct sales favored for bulk chemical flows and distributor networks fragmenting under procurement consolidation.
- Direct Sales:Consolidated procurement by Dutch and French nutrition multinationals concentrates volume through producer relationships, eliminating historical distributor margins.
- Distributors:Regional chemical traders retain relevance in peripheral EU member states where process safety expertise gaps limit direct producer engagement.
- Wholesalers:Intermediate stocking points for industrial grade volumes serving fragmented leather and textile processor bases.
- Online Retail:Emerging channel for technical grade and specialty quantities, though bulk chemical logistics limit penetration.
Direct Sales dominates installed base. Distributor relationships are gaining share fastest in Eastern European expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian feed compounders exhibit the sharpest price elasticity, while German automotive leather buyers absorb premiums for carbon-certified supply. This demand stratification reshapes regional sales strategies across the continent.
Germany
Automotive leather suppliers in Baden-Württemberg and Rhineland-Palatinate drive pharmaceutical-grade demand for Scope 3 disclosure compliance. CSRD mandates force batch-level carbon footprint documentation from acid providers. BASF's Ludwigshafen complex anchors captive supply chains for downstream formate derivatives serving industrial manufacturing clusters.
Netherlands
Denmark-bound feed acidifier volumes concentrate through Rotterdam chemical terminals serving pan-European nutrition multinationals. EFSA feed additive evaluations determine market access for acidifier blends entering Dutch formulation facilities. Three buyers now control fifty-five percent of feed-grade acid offtake through direct producer contracts bypassing traditional distributors.
Italy
Arzignano leather tanneries redirect chemistry toward formic acid preservation systems as ECHA enforcement eliminates chromium-based tanning agents. REACH registration mandates shape product specifications for export-oriented finished leather. Northern Italian textile processors specify acid-based dye fixation to meet OEKO-TEX Standard 100 certification requirements for Nordic apparel brand supply chains.
Poland
Pig and poultry operations across Greater Poland and Lower Silesia adopt EFSA-approved acidifier protocols replacing antibiotic growth promoters. Polish feed compounders exhibit acute price sensitivity to methanol feedstock volatility through TTF benchmark exposure. Distribution networks fragment as regional chemical traders retain relevance amid process safety expertise gaps limiting direct producer engagement.
Romania
Bulgarian-border pork producers implement acidifier systems to access German retail supply chain certification requirements. Romanian livestock expansion lags Western European compliance infrastructure, creating distributor-dependent procurement patterns. Bucharest-based chemical traders mediate between Black Sea import terminals and fragmented agricultural processor bases lacking direct producer relationships.
Europe Formic Acid Market Competitive Landscape
Capability concentration sits with specialty-grade specialists; scale advantage sits with integrated petrochemical complexes. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with captive methanol feedstock, purity-focused specialists serving pharmaceutical and food channels, and regional distributors bridging process safety expertise gaps in peripheral markets. Dominant competitive moves include backward integration into methanol supply and direct contracting relationships with consolidated feed compounders eliminating historical distributor margins.
Within the integrated chemical conglomerate tier, BASF SE exemplifies scale-driven positioning through its Ludwigshafen complex. Among Nordic specialists, Perstorp AB and Kemira Oyj occupy differentiated positions—Perstorp representing the high-purity pharmaceutical-grade archetype, Kemira anchoring industrial process control adjacencies in water treatment and pulp chemistry. These three names illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| POLIOLI SpA |
| LUXI GROUP |
| BASF SE |
| HELM AG |
| LANXESS AG |
| Eastman Chemical Company |
| Petroliam Nasional Berhad (PETRONAS) |
| Kemira Oyj |
| Perstorp AB |
| Others |
Pricing and Supply Chain Analysis
Rhineland-Palatinate and Antwerp chemical clusters anchor over sixty percent of European nameplate capacity, concentrating margin capture with integrated producers who command premium pricing for pharmaceutical-grade certification against methanol-volatile industrial tiers.
Pricing Analysis
Aftermarket technical service revenue from multi-year pharmaceutical supply contracts drives lifetime value far above spot industrial sales. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects EDQM CEP documentation costs and TTF-linked methanol feedstock exposure. Cost compression in industrial-grade volumes is intensifying because propionic acid substitutes erode grain preservation market share. Polish feed compounders exhibit acute price sensitivity, while German automotive leather buyers absorb premiums for batch-level carbon footprint certification.
Supply Chain Analysis
Contract manufacturing concentration rests with BASF's Ludwigshafen complex, Perstorp's specialty purification facilities, and Kemira's Nordic process control operations. Supply concentrates in Germany, Belgium, and the Netherlands, with raw material dependencies on natural gas-linked methanol, agricultural waste feedstocks for bio-based pathways, and high-purity water for pharmaceutical grades. Single-source vulnerability runs through Rhineland-Palatinate's integrated chemical corridor. Distribution runs through direct sales to consolidated feed compounders, with regional distributors retaining Eastern European fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chemical engineering talent for CO handling and high-pressure methyl formate operations is scarce across peripheral EU member states, creating capability bottlenecks that favor incumbents with established safety protocols and regulatory qualification track records.
For Market Incumbents: Pre-empt propionic acid substitution in German feed milling by securing backward integration into bio-based methanol supply and accelerating EDQM CEP certification for pharmaceutical-grade expansion. Lock in ten-thousand-ton direct contracts with pan-European compounders before distributor networks reconstitute in Eastern Europe. Process safety expertise gaps limit new entrant replication of high-pressure operations. For New Entrants and Emerging Players: Build out Romanian and Bulgarian distributor-dependent procurement channels where fragmented agricultural processor bases lack direct producer relationships. Target pharmaceutical-grade certification for hospital disinfectant applications with forty percent margin premiums over industrial equivalents. Lead with EFSA feed additive evaluation support as a go-to-market differentiator against established suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical platforms holding pharmaceutical-grade purification capabilities and established EMA documentation relationships. Long-term viability hinges on carbon border adjustment alignment and bio-based production certification securing export competitiveness into EU manufacturing clusters. Watch EU ETS price trajectory and biomass-derived production pilot scale-up as inflection signals for feedstock cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Methanol | Aligns production with EU Green Deal carbon intensity benchmarks for export competitiveness. |
| Pharmaceutical Grade Certification Investment | EDQM CEP documentation opens hospital disinfectant channels with premium margin capture. |
| Direct Contracting with Feed Compounders | Bypasses distributor margins and locks volume with Dutch and French nutrition multinationals. |
| Eastern European Distribution Network Buildout | Captures Romanian and Bulgarian livestock expansion through trader-mediated procurement. |
| Electrochemical Synthesis Pilot Scale-up | Danish and Dutch facilities demonstrate lower carbon intensity versus methyl formate hydrolysis. |
Research Methodology
The analysis maps industrial-grade, pharmaceutical-grade, food-grade, and technical-grade production tiers, each validated through plant managers at Rhineland-Palatinate and Antwerp chemical clusters, procurement leads at Danish and Dutch feed compounders, distribution channel partners in Eastern Europe, and technical R&D directors specializing in electrochemical synthesis. Primary interview insights triangulate against customs and trade data, Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and EFSA feed additive evaluation databases. Bottom-up capacity and consumption estimates reconcile with top-down value chain margin analysis.
Assumptions around methanol feedstock pricing volatility, REACH enforcement timelines, and EFSA evaluation throughput were held fixed across baseline scenarios while bio-based production cost curves and EU ETS carbon border adjustment mechanisms were stress-tested. Segmentation dimensions modeled include grade tier purity specifications, end-use industry application splits, regional production hub concentration, and distribution channel structure. CAGRs derive from installed base rotation rates and premium-grade penetration trajectories, with animal feed acidification protocols and pharmaceutical intermediate demand as key forecast inputs.
Stress conditions across TTF natural gas benchmarks, ECHA enforcement intensity, and electrochemical synthesis technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that propionic acid substitution acceleration or biomass feedstock supply constraints could materially revise trajectory. Quarterly review of EU ETS price movements, EFSA feed additive approval cadence, and electrochemical pilot facility announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Imidazole Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Citrate Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Trimer Acid Market