
 US Acids Market | 2026-2036
US Acids Market Size, Share, and Industry Trends Forecast 2026-2036
US Acids Market Intelligence
Software-defined inventory management and predictive maintenance subscriptions is realigning how acid producers monetize customer relationships beyond commodity tonnage. BASF SE leverages its integrated North American production network to sustain supply security for pharmaceutical-grade acid buyers. PVS Chemicals, Inc. anchors its position through dedicated sulfuric acid distribution infrastructure across the Midwest and Southeast. DuPont competes on specialty acid derivatives for semiconductor and electronics applications, differentiating through materials science depth rather than volume scale.
Acids comprise proton-donating inorganic and organic compounds typically characterized by pH below seven, manufactured through fermentation, petrochemical oxidation, or mining and refining of mineral sources, serving as fundamental inputs for pH adjustment, catalysis, preservation, and chemical synthesis. Citric acid and lactic acid lead growth trajectories within the product type dimension, propelled by food and beverage formulators replacing synthetic preservatives with fermentation-derived alternatives. Industrial grade acids still occupy the largest value pool by tonnage, though margin concentration sits with pharmaceutical grade specifications where FDA validation requirements create qualification barriers.
EPA enforcement of TSCA Section 5 premanufacture notification rules and OSHA Process Safety Management standards govern acid handling, storage, and worker exposure limits across US production facilities. FDA food additive regulations and USP monograph compliance for pharmaceutical grades further segment market access by purity tier. State-level environmental permitting in Texas and Louisiana adds another compliance layer for Gulf Coast producers. Stakeholders must monitor how evolving PFAS restrictions and green chemistry procurement mandates reshape acceptable feedstock pathways and process chemistry investments.
Market Dynamics
Clean-label preservation mandates from FDA and USDA are forcing food and beverage formulators to replace synthetic acidulants with fermentation-derived alternatives, compressing qualification timelines and reshaping supplier-buyer relationships across the value chain.
Growth Catalysts
- Fermentation technology maturation:Bioprocess engineering advances have cut citric acid and lactic acid production costs by half, enabling price parity with petrochemical-derived acidulants for the first time.
- EPA TSCA reform enforcement:Stricter premanufacture notification rules under Section 5 are accelerating market exit of non-compliant acid processors, consolidating volume with validated producers.
- Gulf Coast petrochemical clustering:Integrated production corridors in Texas and Louisiana generate captive sulfuric acid and hydrochloric acid supply for downstream specialty chemical operations.
Market Restraints
- Sulfur feedstock volatility:Acid producers remain exposed to sulfur price swings tied to oil refining throughput and phosphate fertilizer demand cycles.
- Midwest distribution infrastructure concentration:Dedicated sulfuric acid storage and rail terminal networks limit new entrant access to industrial buyers in the manufacturing belt.
- Pharmaceutical grade qualification barriers:USP monograph compliance and FDA validation requirements create multi-year approval timelines that freeze out uncertified suppliers.
Strategic Opportunities
- Southeast food processing expansion:North Carolina and Georgia meat and dairy processors are accelerating demand for natural acidulants in clean-label preservation applications.
- Software-defined inventory management:Predictive maintenance subscriptions and real-time tank monitoring are creating recurring revenue streams beyond commodity tonnage sales.
- IRA green chemistry procurement incentives:Federal procurement mandates for bio-based feedstocks are opening qualification pathways for fermentation-derived acid producers in government supply chains.
Industry Challenges
- Process Safety Management compliance:OSHA's 14-element PSM standard for highly hazardous chemicals requires specialized safety engineering talent that remains scarce in secondary markets.
- Legacy ERP integration with IoT platforms:Tank-level sensor deployment demands capital reconfiguration of enterprise resource planning systems at mid-scale acid terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Acids Market |
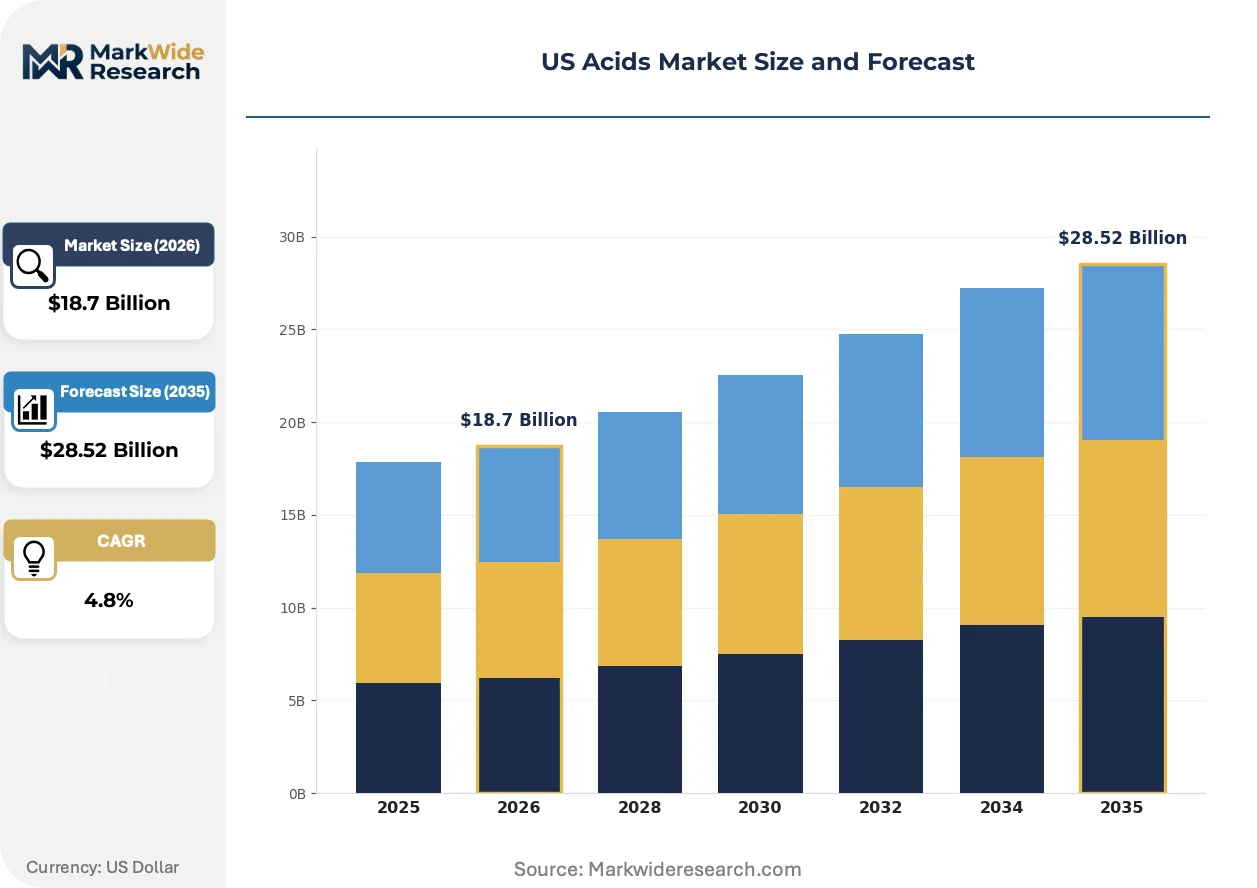
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Citric Acid, Lactic Acid, Formic Acid Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Application: Food Preservation, Pharmaceuticals, Cleaning Agents, Agriculture End User: Food & Beverage, Healthcare, Cosmetics, Chemical Manufacturing |
| Companies Covered | Cargill, Incorporated, BASF SE, Archer Daniels Midland Company, Tate & Lyle PLC, DuPont, PVS Chemicals, Inc., Akzo Nobel NV, Polynt Group, The Dow Chemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Acids Market Strategic Shifts & Innovations
Digital instrumentation and bio-based process chemistry are converging to transform how acid producers manage asset utilization, compliance documentation, and customer relationships across fragmented end-use segments.
Continuous fermentation monitoring with dissolved oxygen and pH probe arrays is decentralizing quality control from central laboratories to production vessels. Food and beverage manufacturers are adopting these real-time assurance systems to compress batch release cycles. The shift is compressing supplier qualification timelines and enabling just-in-time acidulant delivery models.
EPA's revised chemical handling standards under TSCA reform are tightening storage and worker exposure thresholds for industrial acid processors. Facilities must now deploy secondary containment and automated leak detection systems to maintain operating permits. Gulf Coast producers in Texas and Louisiana face the steepest retrofit requirements due to concentrated tank farm density.
Buyer consolidation among national food and beverage formulators is concentrating procurement leverage and compressing supplier rosters. Large meat and dairy processors are consolidating acidulant contracts with single-source fermentation-derived suppliers. The pattern is most visible in the Midwest and Southeast, where regional processing hubs are standardizing on validated clean-label acid portfolios.
US Acids Market Segmentation
Acid producers in the United States configure production assets and certification pathways around discrete purity tiers and end-use specifications. Segmentation discipline determines which Gulf Coast sulfur-burning facilities, Midwest fermentation plants, and pharmaceutical-grade refineries capture margin concentration across divergent buyer requirements.
Product Type:
Fermentation-derived alternatives are displacing petrochemical acidulants as food and beverage formulators execute clean-label preservation upgrades.
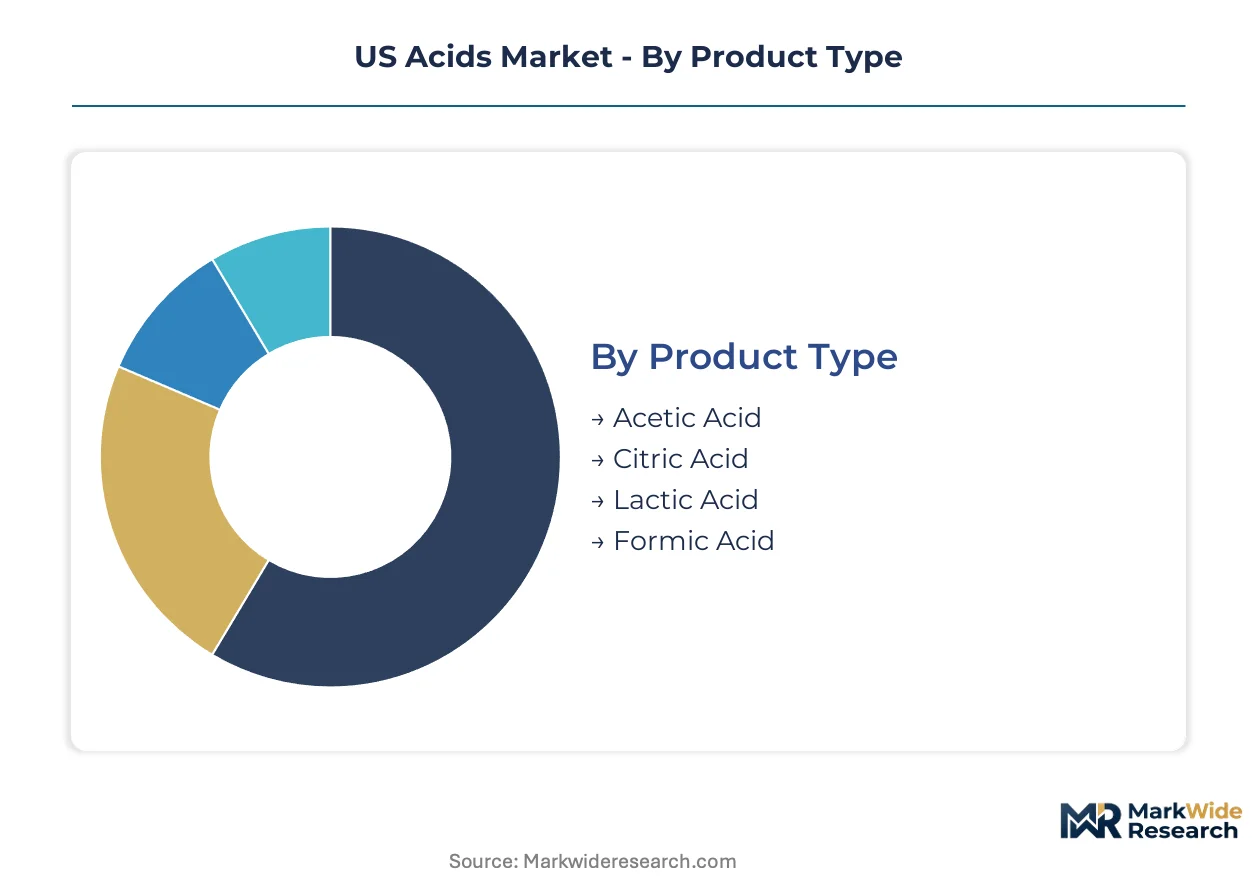
- Citric Acid:Produced through submerged fermentation of Aspergillus niger on molasses or dextrose substrates, this tricarboxylic acid delivers pH reduction and chelation functionality. Southeast meat and dairy processors in North Carolina and Georgia are consolidating procurement with single-source fermentation suppliers to meet USDA preservation mandates.
- Lactic Acid:Bacterial fermentation of carbohydrate feedstocks yields this alpha-hydroxy acid in stereochemically pure L- or D- forms. Food and beverage manufacturers across the Midwest are accelerating uptake for clean-label shelf-life extension, compressing qualification timelines with validated bioprocess producers.
- Acetic Acid:Petrochemical oxidation of ethylene or methanol carbonylation produces this monocarboxylic acid for industrial solvent and vinyl acetate monomer applications.
- Formic Acid:Methyl formate hydrolysis or carbon dioxide hydrogenation generates this simplest carboxylic acid for leather tanning and silage preservation uses.
Acetic acid sits at the top of the volume ranking, with lactic acid climbing the fastest.
Grade:
Regulatory validation tiers fragment market access and margin capture across acid processors serving divergent compliance environments.
- Industrial Grade:Sulfuric acid and hydrochloric acid specifications for petrochemical catalysis, metal pickling, and wastewater treatment dominate tonnage throughput. Gulf Coast integrated production corridors in Texas and Louisiana generate captive supply for downstream specialty chemical operations, though sulfur feedstock volatility compresses margin stability.
- Pharmaceutical Grade:USP monograph compliance and FDA validation requirements for parenteral and oral drug formulations create multi-year qualification barriers. FDA food additive regulations and current Good Manufacturing Practice standards govern impurity profiles and documentation rigor, freezing out uncertified suppliers from high-margin contracts.
- Food Grade:Fermentation-derived citric and lactic acid specifications meet FDA food additive regulations for pH adjustment and preservation in processed foods.
- Technical Grade:Intermediate purity specifications serve laboratory reagent and industrial synthesis applications with reduced documentation burden.
Industrial grade commands the largest tonnage position, while pharmaceutical grade captures the steepest margin expansion trajectory.
Application:
End-use concentration patterns align with regional processing infrastructure and regulatory enforcement intensity across US manufacturing belts.
- Food Preservation:Natural acidulants replace synthetic preservatives in clean-label meat, dairy, and beverage formulations. FDA and USDA mandates are forcing rapid supplier consolidation among national formulators, with Midwest and Southeast regional processing hubs standardizing on validated fermentation-derived portfolios.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis, pH adjustment in parenteral solutions, and tablet excipient functions demand USP-validated acid supplies. Multi-year FDA approval timelines for new suppliers protect incumbent positions in this high-barrier segment.
- Cleaning Agents:Descaling, disinfectant formulation, and industrial sanitation applications consume technical and industrial grade acid volumes.
- Agriculture:Silage preservation, feed acidification, and pesticide formulation represent fragmented demand across rural processing infrastructure.
Food preservation anchors volume demand, with pharmaceutical applications generating the highest value per kilogram.
End User:
Buyer consolidation and procurement centralization are reshaping supplier relationship economics across acid-consuming industries.
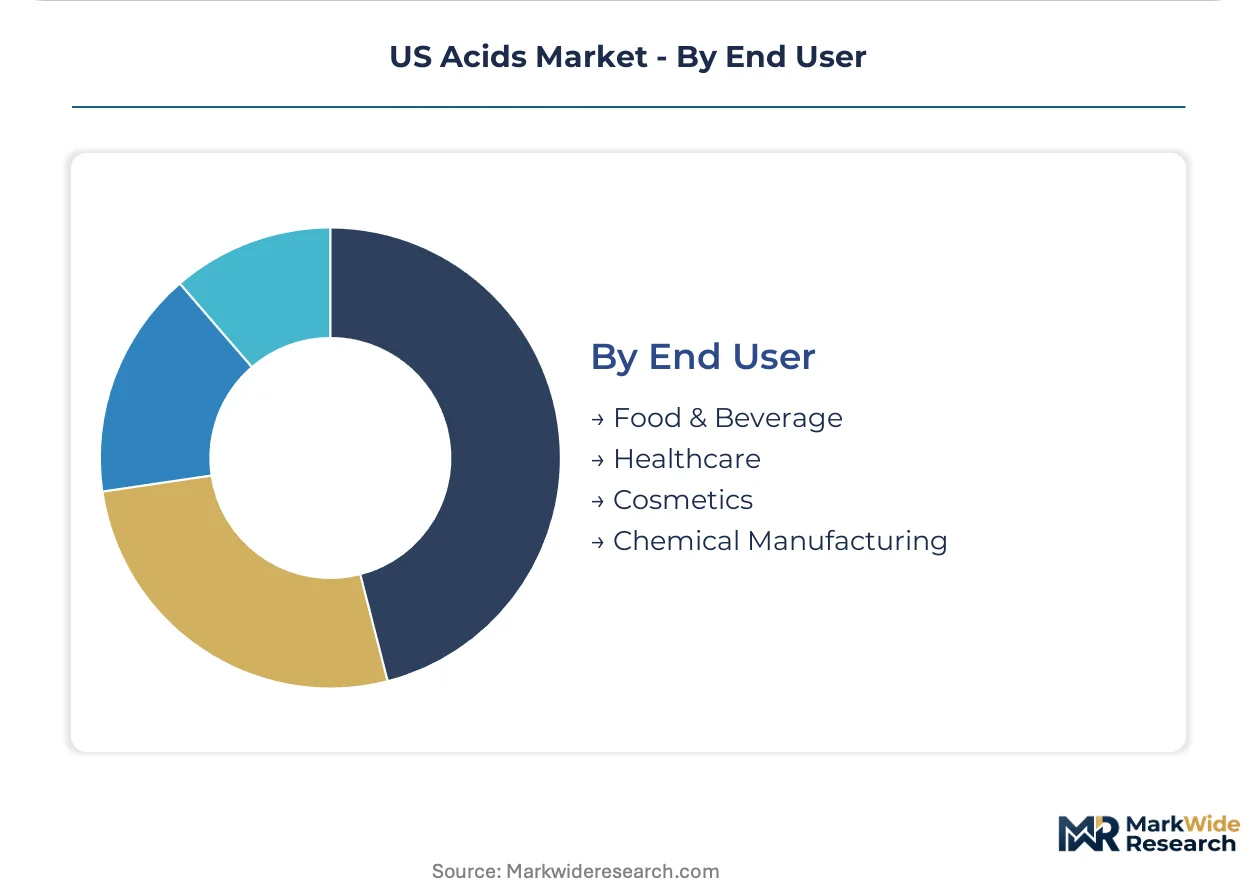
- Food & Beverage:National meat and dairy processors wield concentrated procurement leverage, compressing supplier rosters to single-source fermentation acid providers. Clean-label preservation mandates from FDA and USDA are accelerating contract consolidation with validated clean-label acid portfolios.
- Chemical Manufacturing:Gulf Coast petrochemical complexes consume captive sulfuric acid and hydrochloric acid for downstream specialty chemical synthesis. Integrated production clustering generates supply security advantages for vertically positioned processors.
- Healthcare:Hospital systems and pharmaceutical manufacturers source USP-grade acids for compounding and manufacturing with stringent documentation requirements.
- Cosmetics:Personal care formulators utilize pH-adjusting acids in skincare and haircare products with moderate regulatory burden relative to pharmaceutical tiers.
Food and beverage represents the most active buyer segment, with chemical manufacturing commanding the largest contract volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Louisiana concentrate sulfuric acid production capacity while North Carolina and Georgia food processors drive fermentation-derived acidulant procurement, revealing a bifurcated geography between industrial feedstock corridors and clean-label demand centers.
Gulf Coast Corridor
Integrated petrochemical complexes in Texas and Louisiana generate captive sulfuric acid and hydrochloric acid supply for downstream specialty chemical operations. EPA TSCA Section 5 premanufacture notification enforcement tightens compliance thresholds for acid storage and worker exposure limits. Houston and Lake Charles anchor the densest tank farm concentrations, where producers face steep retrofit requirements for secondary containment systems.
Southeast Food Belt
North Carolina and Georgia meat and dairy processors accelerate demand for citric acid and lactic acid in clean-label preservation applications. USDA preservation mandates force rapid supplier consolidation with single-source fermentation providers. Charlotte and Atlanta regional processing hubs standardize on validated bio-based acid portfolios, compressing qualification timelines with bioprocess producers.
Midwest Manufacturing Belt
Illinois, Ohio, and Michigan industrial consumers rely on dedicated sulfuric acid distribution infrastructure for metal pickling and wastewater treatment. OSHA Process Safety Management standards govern handling protocols across aging storage terminals. Chicago and Detroit rail terminals limit new entrant access through concentrated tank car networks and legacy terminal ownership.
California Pharmaceutical Corridor
San Francisco Bay Area and Los Angeles biopharma manufacturers source USP-grade acids for active pharmaceutical ingredient synthesis and parenteral formulation. FDA validation requirements and current Good Manufacturing Practice standards create multi-year qualification barriers for uncertified suppliers. South San Francisco and San Diego clusters protect incumbent positions through established FDA master file relationships.
Northeast Chemical Processing
New Jersey and Pennsylvania specialty chemical manufacturers consume technical and pharmaceutical grade acids for fine chemical synthesis. State-level environmental permitting adds compliance layers beyond federal TSCA requirements. Philadelphia and northern New Jersey industrial zones maintain legacy acid handling infrastructure with elevated PSM compliance costs.
US Acids Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived acidulant producers capturing premium positioning in food preservation while commodity sulfuric acid suppliers compete on terminal access and rail logistics. The vendor base organizes around three strategic archetypes: integrated petrochemical conglomerates with captive acid production, dedicated fermentation specialists with USP and food-grade certifications, and regional distributors with tank terminal infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as producers seek to secure sulfur feedstock contracts and lock in long-term offtake agreements with national food formulators.
Within the integrated petrochemical tier, BASF SE and The Dow Chemical Company exemplify multinational conglomerates with North American production networks that sustain supply security for pharmaceutical-grade and industrial acid buyers. Among fermentation specialists, Cargill, Incorporated and Archer Daniels Midland Company occupy positions as agricultural processors with integrated bioprocess capabilities for citric acid and lactic acid production. PVS Chemicals, Inc. represents the regional distributor archetype, anchoring market presence through dedicated sulfuric acid storage and rail terminal networks across the Midwest and Southeast.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| DuPont |
| PVS Chemicals, Inc. |
| Akzo Nobel NV |
| Polynt Group |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Clean-label procurement consolidation among national food and beverage formulators is forcing acid producers to reconfigure supply networks toward fermentation-derived capacity, compressing margins on petrochemical acidulants while elevating price premiums for USP-validated grades.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for industrial sulfuric acid as Gulf Coast integrated producers leverage captive sulfur supply. Three-tier pricing structure across pharmaceutical, food, and industrial grade levels stratifies margin capture, with FDA-validated specifications commanding substantial premiums over technical grades. Cost compression in industrial acid runs through sulfur feedstock volatility tied to refinery throughput cycles. National meat processors exhibit the least price sensitivity due to single-source contract structures, while regional chemical manufacturers face acute pressure from spot market exposure.
Supply Chain Analysis
Dedicated tank car and rail terminal networks handle bulk industrial acid distribution across the Midwest manufacturing belt. Supply concentrates in Texas, Louisiana, and Illinois production corridors, with sulfuric acid capacity anchored in Gulf Coast petrochemical clusters and fermentation-derived acidulants sourced from Midwest agricultural processing hubs. Raw material dependencies rest on molasses and dextrose feedstocks for citric acid, sulfur recovery from oil refining for sulfuric acid, and ethylene oxidation for acetic acid. Single-source vulnerability pervades pharmaceutical-grade supply chains where USP monograph compliance creates multi-year qualification barriers. Distribution runs through integrated producer-direct channels for large-volume industrial buyers and specialized distributors for food-grade acidulants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Acids Market functions as a regulatory compounder where EPA TSCA reform enforcement and FDA clean-label mandates are accelerating demand bifurcation between fermentation-derived and petrochemical acid supplies.
For Market Incumbents: Deepen backward integration into sulfur recovery infrastructure to buffer margin erosion from feedstock volatility, while accelerating USP certification investments to defend pharmaceutical-grade positions against emerging bioprocess specialists. Consolidate tank terminal ownership in Chicago and Detroit rail corridors to limit new entrant access. Prioritize software-defined inventory management subscriptions to lock in long-term offtake relationships beyond commodity tonnage transactions. For New Entrants and Emerging Players: IRA green chemistry procurement incentives in the United States open a window for fermentation-derived acid producers to penetrate federal supply chains previously dominated by petrochemical incumbents. Target Southeast food processing expansion in North Carolina and Georgia where USDA preservation mandates force rapid supplier consolidation with clean-label portfolios. Enter through toll manufacturing partnerships with established Midwest bioprocess facilities to bypass capital-intensive fermentation asset builds. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation specialists holding dual USP and food-grade certifications capable of serving both pharmaceutical and clean-label food preservation demand pools. Five-to-ten-year viability favors producers with integrated agricultural feedstock sourcing and validated bioprocess engineering capabilities. Monitor EPA enforcement intensity around TSCA Section 5 premanufacture notifications as an inflection indicator for market consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Gulf Coast producers secure captive feedstock supply insulating margins from refinery cycle volatility. |
| USP Certification Investment | FDA validation creates multi-year barriers protecting high-margin pharmaceutical acid contracts from commoditization. |
| Software-Defined Inventory Subscriptions | Predictive tank monitoring transforms transactional tonnage sales into recurring revenue relationships with food processors. |
| Southeast Fermentation Capacity Expansion | Proximity to North Carolina and Georgia meat processing hubs reduces logistics costs for clean-label acidulant delivery. |
| Long-term Supply Agreement with National Formulators | Single-source contracts with consolidated meat and dairy processors lock in volume commitments across multi-year horizons. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with plant managers at Gulf Coast sulfur-burning facilities, procurement leads at Midwest food processing operations, distribution channel partners across rail terminal networks, and technical R&D directors at fermentation specialists. Secondary validation drew from EPA enforcement databases, FDA food additive petitions, USP monograph revisions, and American Chemistry Council trade flow data. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across grade tiers and end-use applications.
Historical reference periods anchored the projection horizon to establish baseline growth trajectories and volatility patterns. Segmentation dimensions modeled include grade tier (pharmaceutical, food, industrial, technical), end-use industry (food preservation, pharmaceuticals, chemical manufacturing, cleaning agents), and regional production hub (Gulf Coast, Midwest, Southeast, California, Northeast). CAGRs were derived through exponential smoothing of annual growth rates adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated sulfur price cycle modeling and fermentation technology cost curves.
Revisions become necessary when EPA enforcement intensity shifts materially, sulfur feedstock availability disrupts Gulf Coast production economics, or FDA clean-label mandates accelerate beyond modeled timelines. Forecasts reflect documented assumptions around regulatory continuity and technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market