
 Threonine Acids Market | 2026-2036
Threonine Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Threonine Acids Market Analytics
EU F-Gas Regulation phase-down targets for hydrofluorocarbons are shifting amino acid fermentation cooling requirements across European production assets. Evonik Industries AG leverages its backward integration into precursor chemicals to sustain margin capture in pharmaceutical-grade threonine. Ajinomoto Co., Inc. anchors its position through biotechnology leadership in strain optimization. CJ CheilJedang Corporation competes on manufacturing scale across Southeast Asian feed markets.
Threonine is an essential alpha-amino acid with the chemical formula HO₂CCH(NH₂)CH(OH)CH₃, produced industrially through microbial fermentation of carbohydrate substrates using Corynebacterium glutamicum or Escherichia coli strains engineered for high titers. The compound serves primarily as a limiting amino acid in livestock nutrition, where it optimizes protein synthesis efficiency and reduces nitrogen excretion in monogastric animals. L-Threonine dominates volume flows in the product type dimension, while pharmaceutical-grade specifications command premium positioning against standard feed-grade material. Powder form leads industrial procurement due to handling efficiency and shelf stability, though liquid formulations are gaining traction in integrated feed mill operations.
FDA feed additive regulations and China's SAMR national food safety standards shape purity thresholds and import documentation requirements for cross-border threonine trade. REACH registration obligations in Europe and BIS certification mandates in India create divergent compliance cost structures that filter market participation by production geography. Stakeholders must monitor fermentation yield improvements and carbon intensity metrics as buyer procurement criteria harden around lifecycle assessments.
Market Dynamics
Fermentation yield improvements and carbon intensity metrics are hardening into primary procurement criteria as feed manufacturers and pharmaceutical buyers integrate lifecycle assessments into supplier qualification protocols.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbons are retrofitting cooling systems across European fermentation assets, accelerating capital deployment into energy-efficient biomanufacturing infrastructure.
- Swine nutrition optimization:Threonine fortification protocols are reducing nitrogen excretion rates in monogastric operations, aligning livestock operations with tightening environmental discharge permits.
- Henan-Shandong cluster expansion:Concentrated fermentation capacity in these provinces is capturing economies of scale in feed-grade amino acid production.
Market Restraints
- Carbohydrate substrate volatility:Corn and molasses price swings transmit directly into threonine production economics, compressing margin buffers for non-integrated producers.
- Strain IP concentration:High-performance Corynebacterium glutamicum and Escherichia coli engineering capabilities remain concentrated among a limited set of biotechnology licensors.
- REACH registration burdens:European chemical registration obligations create fixed compliance costs that filter participation by production geography.
Strategic Opportunities
- India feed market penetration:BIS certification pathways and DGFT import frameworks are opening formal channels for pharmaceutical-grade threonine in aquaculture nutrition.
- Precision fermentation convergence:Synthetic biology toolsets are merging with traditional microbial platforms to enable novel strain development timelines.
- Liquid formulation channels:Integrated feed mill operations are adopting liquid threonine delivery systems, bypassing powder handling infrastructure.
Industry Challenges
- Metabolic engineering talent scarcity:Strain optimization and pathway design capabilities outpace available specialist labor pools in key production geographies.
- Multi-jurisdiction certification timelines:FDA feed additive approvals, SAMR national food safety standards, and BIS mandates create asynchronous market entry schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Threonine Acids Market |
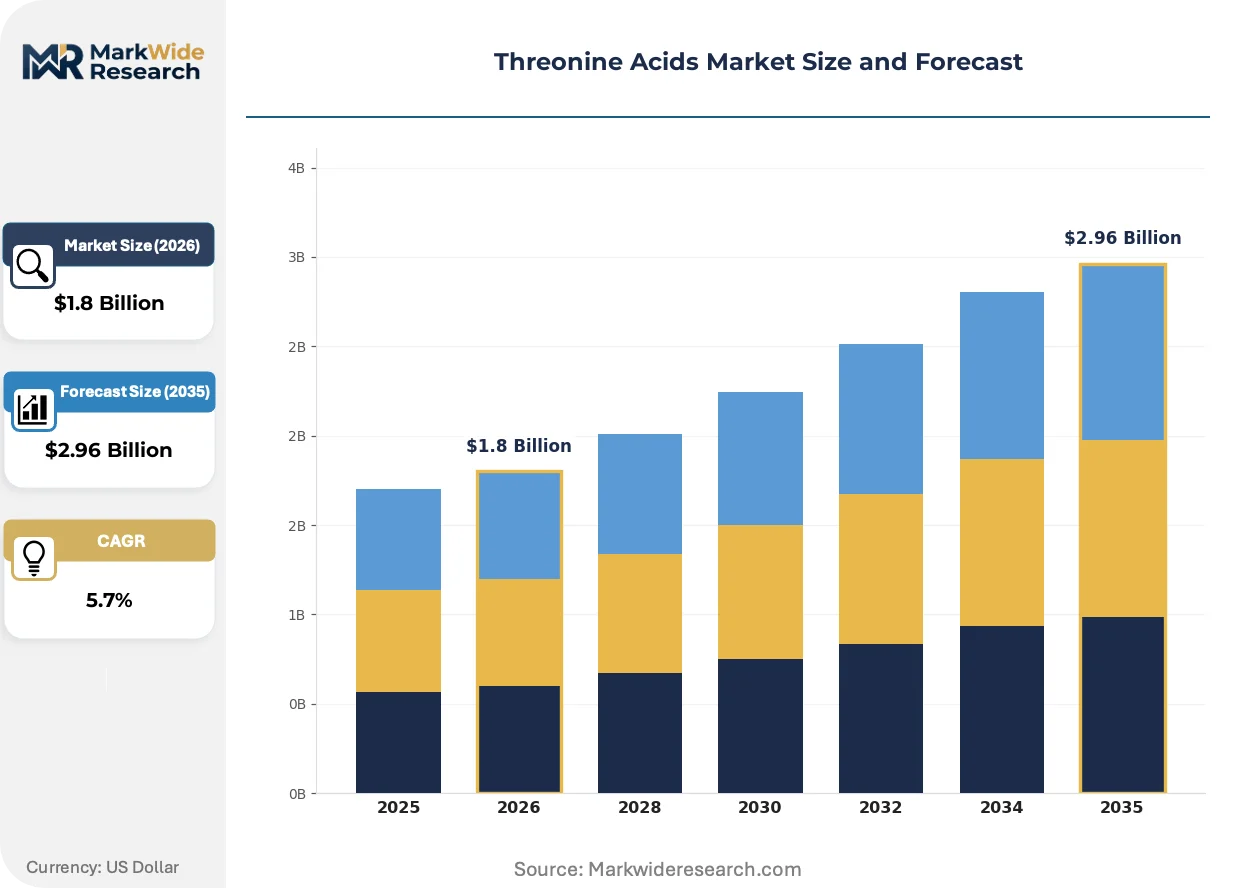
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Threonine, L-Threonine, D-Threonine, Threonine Nitrate End Use Industry: Animal Feed, Pharmaceuticals, Food & Beverages, Nutraceuticals Form: Powder, Liquid, Granules, Tablets Purity: 98%, 99%, 95%, Others |
| Companies Covered | Evonik Industries AG, Ajinomoto Co., Inc., CJ CheilJedang Corporation, Archer Daniels Midland Company, Meihua Holdings Group Co., Ltd., Fufeng Group Limited, Kyowa Hakko Bio Co., Ltd., Daesang Corporation, Novus International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Threonine Acids Market Evolving Landscape
Bioprocess intensification and digital fermentation control systems are compressing batch cycle times while regulatory frameworks harden around carbon accounting and supply chain traceability.
Continuous fermentation technology is absorbing capital deployment across large-scale amino acid facilities. European and North American producers are retrofitting batch infrastructure to reduce energy intensity per kilogram of L-threonine output. The technology is absorbing margin pressure from rising utility costs while enabling real-time quality monitoring that reduces off-specification losses.
China's MIIT biomanufacturing standards are tightening purity specifications for feed-grade amino acids. These rules are forcing fermentation asset upgrades and documentation protocols that raise operational compliance costs. Export-oriented producers in Shandong province are responding by segregating production lines between domestic and international specification tiers.
Integrated feed mills are consolidating procurement around long-term offtake agreements with fermentation specialists. Direct supplier relationships are displacing spot-market purchasing and distributor intermediation in North American and European livestock operations. This pattern is most visible in vertically coordinated poultry supply chains where threonine dosing integrates with automated ration formulation systems.
Threonine Acids Market Segmentation
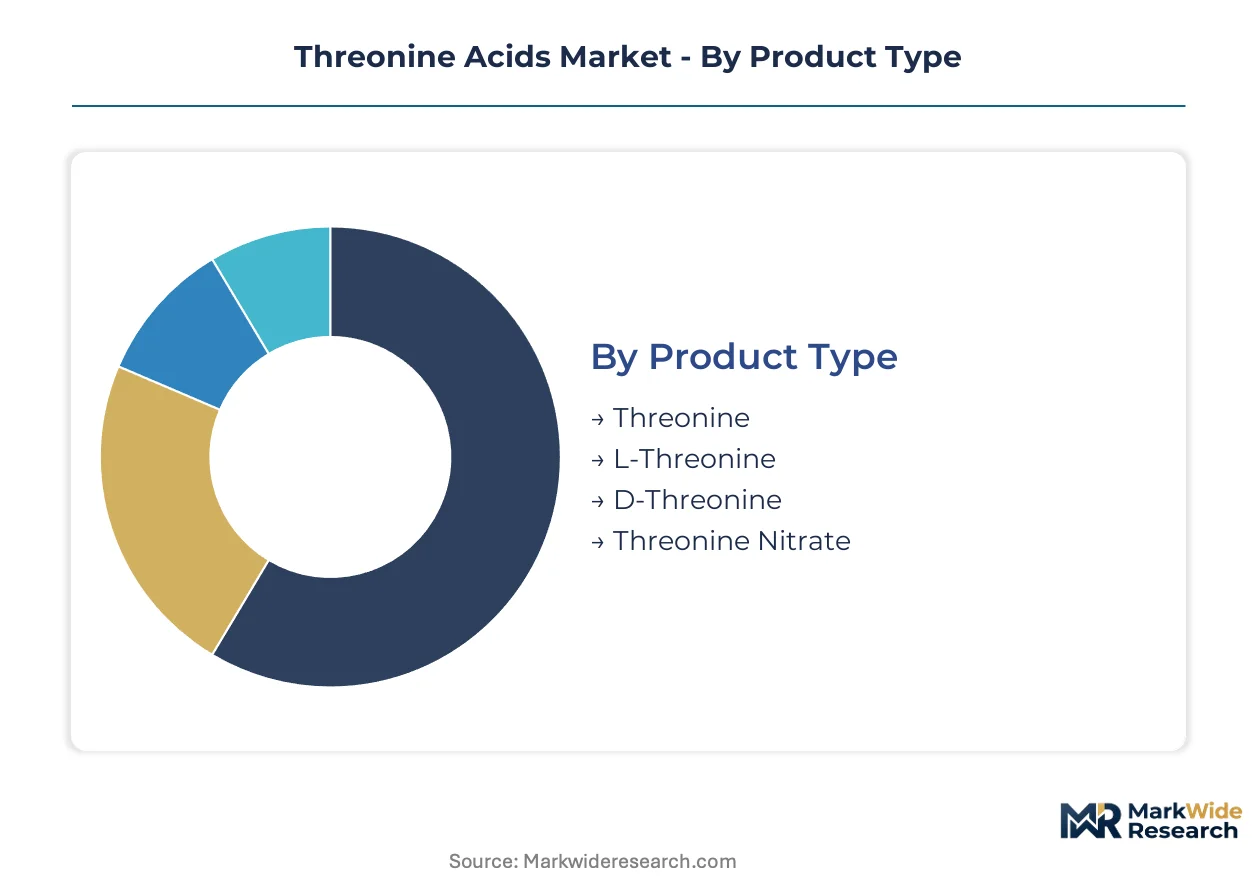
Threonine acid segmentation reveals how certification burdens, formulation requirements, and end-use specifications fragment procurement patterns across pharmaceutical, feed, and food-grade channels. Each dimension carries distinct regulatory overlays that reshape supplier qualification protocols and margin structures.
Product Type:
FDA feed additive approvals apply to standard threonine and L-threonine for livestock applications, while pharmaceutical-grade L-threonine demands USP-NF compliance and DMF filing with regulators.
- Threonine:Generic-grade material serves bulk feed fortification with minimal purity certification. Demand concentrates in China's Shandong province where fermentation clusters supply Southeast Asian swine operations facing EU F-Gas Regulation compliance costs.
- L-Threonine:The biologically active enantiomer dominates pharmaceutical and premium feed applications. Specifications require chiral purity verification and SAMR national food safety documentation for Chinese export channels.
- D-Threonine:Non-proteinogenic stereoisomer with limited commercial traction. Research-grade volumes flow to specialty chemical intermediates and asymmetric synthesis feedstock.
- Threonine Nitrate:Salt derivative serving niche pharmaceutical formulations. BIS certification pathways in India and ANVISA registration in Brazil constrain market access for non-specialized producers.
L-Threonine sits at the top of the volume ranking, with threonine nitrate climbing the fastest as pharmaceutical salt formulations expand.
End Use Industry:
Cost tier stratification separates commodity feed applications from pharmaceutical-grade margins, with nutraceuticals occupying an intermediate specification band.
- Animal Feed:Volume anchor segment where threonine fortification optimizes lysine utilization in monogastric diets. Integrated poultry operations in the United States and Brazil are consolidating procurement around direct fermentation supplier relationships.
- Pharmaceuticals:Parenteral nutrition formulations and active pharmaceutical ingredient synthesis drive specification intensity. EMA GMP certification and FDA Type II drug master files create fixed compliance thresholds that filter supplier participation.
- Food & Beverages:Fortification applications in sports nutrition and clinical foods require FSSAI clearance in India and GB standard compliance in China. Volume flows remain constrained by cost-positioning against alternative amino acid fortificants.
- Nutraceuticals:Dietary supplement positioning demands USP verification and clean-label supply chain documentation. Direct-to-consumer brands are sourcing through segregated fermentation batches with identity-preserved carbohydrate substrates.
Animal feed commands the dominant cost tier position, with pharmaceuticals capturing the steepest margin expansion trajectory.
Form:
Handling infrastructure investments and shelf stability requirements divide procurement between established powder systems and emerging liquid delivery channels.
- Powder:Crystalline L-threonine with standardized mesh distribution dominates industrial procurement. Flowability specifications and anti-caking treatments vary by geography, with caking-resistant grades commanding premiums in humid Southeast Asian markets.
- Liquid:Aqueous solutions enable direct injection into automated feed mill systems, bypassing dissolution stages. Adoption concentrates in vertically integrated North American poultry operations where ration formulation software integrates liquid dosing protocols.
- Granules:Agglomerated forms improve dust control during bulk handling. Dust-free grades are penetrating European compound feed facilities facing OSHA-equivalent workplace exposure regulations.
- Tablets:Compressed dosage forms serve pharmaceutical and nutraceutical channels. Direct compression excipient compatibility and disintegration profiles determine supplier selection for tablet manufacturers.
Powder maintains volume leadership, with liquid formulations gaining share fastest as feed mill automation deepens.
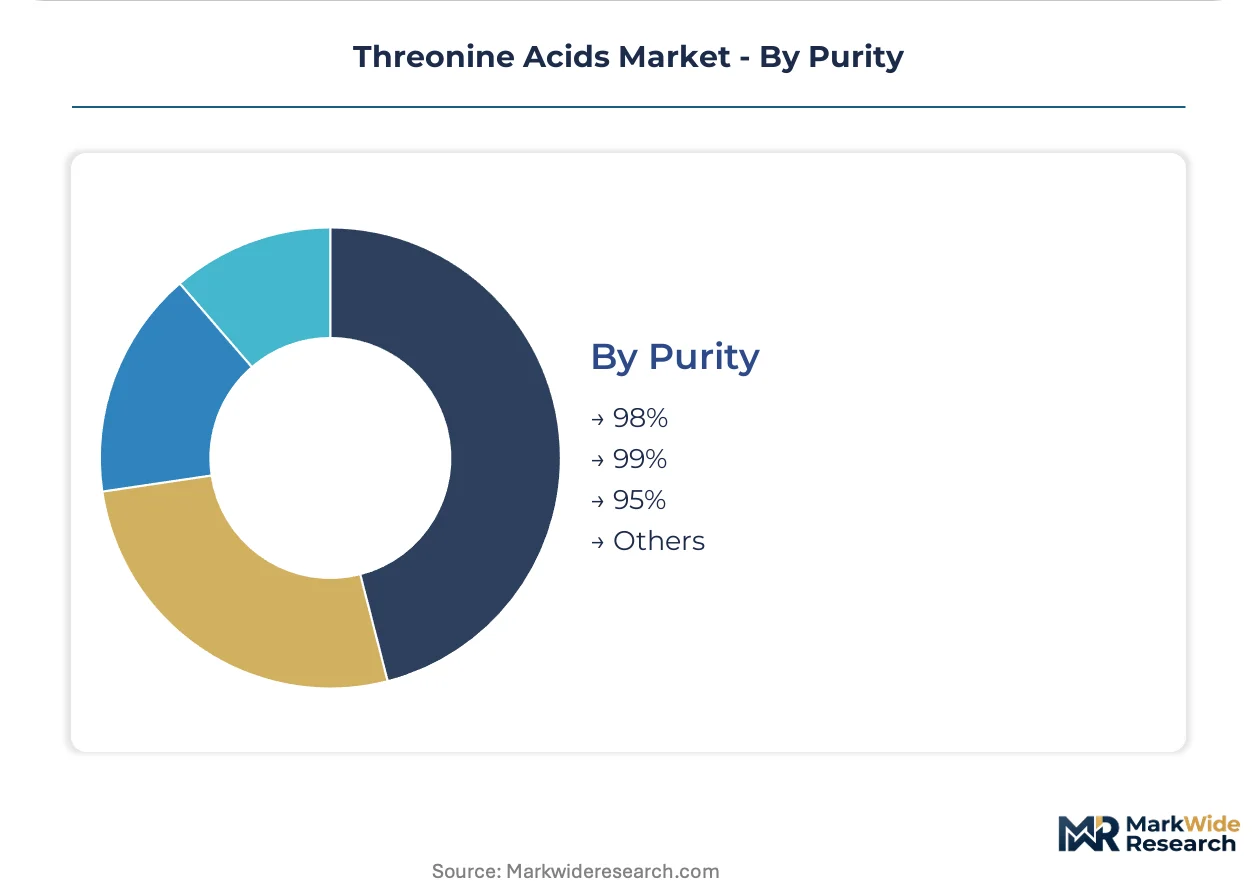
Purity:
Specification tiering aligns with end-use criticality, where percentage-point purity differences trigger order-of-magnitude price spreads.
- 98%:Standard feed-grade threshold satisfying minimum amino acid content for livestock nutrition. MIIT biomanufacturing standards in China are tightening allowable impurity profiles, forcing fermentation yield optimization investments.
- 99%:Pharmaceutical and premium food-grade specification requiring chromatographic purification or crystallization refinement. REACH registration obligations in Europe and residual solvent testing protocols elevate documentation burdens.
- 95%:Technical-grade material for industrial applications and intermediate synthesis. Price-sensitive buyers in emerging markets accept lower purity for non-critical applications.
- Others:Custom specifications including low-endotoxin grades for parenteral nutrition and low-heavy-metal variants for infant formula applications. Lot-to-lot consistency requirements exceed standard analytical thresholds.
98% purity occupies the top volume position, with 99% grades expanding most quickly as pharmaceutical sourcing hardens around USP-NF compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based amino acid production traces its industrial lineage to Japanese biotechnology advances in the 1950s, with Corynebacterium glutamicum strain development establishing the foundational platform for modern threonine manufacturing. The current geographic distribution reflects successive waves of capacity migration toward feed-demand centers and cost-optimized fermentation clusters.
China
Swine and poultry feed fortification drives threonine consumption across integrated livestock operations. MIIT biomanufacturing standards and SAMR national food safety rules enforce tightening purity documentation for export-bound material. Shandong and Henan provinces concentrate fermentation capacity, with Shandong-based producers segregating production lines between domestic and international specification tiers.
United States
Vertically coordinated poultry supply chains automate threonine dosing through integrated feed mill systems. FDA feed additive regulations and EPA environmental discharge permits shape procurement protocols for nitrogen-excretion-reducing formulations. The Midwest corn belt anchors carbohydrate substrate supply, with Illinois and Iowa processing infrastructure feeding regional fermentation economics.
Germany
EU F-Gas Regulation phase-down mandates accelerate cooling system retrofits across biomanufacturing assets. REACH registration obligations and EMA GMP certification requirements filter supplier participation for pharmaceutical-grade material. Bavarian chemical clusters leverage existing infrastructure for high-specification amino acid purification.
Brazil
Poultry export competitiveness hinges on feed cost optimization through amino acid fortification. ANVISA registration frameworks and agricultural ministry feed additive protocols govern import documentation. São Paulo state compound feed facilities consolidate procurement around direct supplier relationships bypassing distributor intermediation.
India
Aquaculture nutrition expansion creates formal channels for pharmaceutical-grade threonine penetration. BIS certification mandates and DGFT import frameworks structure market access for fermentation-derived material. Gujarat and Maharashtra pharmaceutical manufacturing zones absorb premium-grade amino acids for parenteral nutrition formulations.
Threonine Acids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and end-use specification dimensions. The vendor base stratifies between pharmaceutical-grade specialists commanding USP-NF compliance premiums and feed-grade volume producers competing on fermentation yield economics. Three archetypes dominate: backward-integrated chemical conglomerates, dedicated biotechnology platforms, and diversified agribusiness processors. Capacity expansion and strain optimization licensing represent the dominant competitive vectors as producers defend position against carbohydrate substrate volatility.
Within the biotechnology leadership tier, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. represent the Japanese fermentation heritage that established industrial amino acid production platforms. CJ CheilJedang Corporation anchors Korean manufacturing scale across Southeast Asian feed markets. Evonik Industries AG exemplifies European chemical conglomerate positioning through captive precursor supply integration.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Ajinomoto Co., Inc. |
| CJ CheilJedang Corporation |
| Archer Daniels Midland Company |
| Meihua Holdings Group Co., Ltd. |
| Fufeng Group Limited |
| Kyowa Hakko Bio Co., Ltd. |
| Daesang Corporation |
| Novus International, Inc. |
| Others |
Value Network & Pricing Analysis
Integrated feed mill operators in North America and Brazil are consolidating procurement around long-term offtake agreements, forcing a contract-based pricing structure that displaces spot-market purchasing and compresses margin buffers for non-integrated fermentation specialists.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, premium feed, and standard feed-grade levels dominates threonine transactions, with USP-NF certification and chiral purity verification driving 99% grade premiums against 98% feed-grade material. Price differentiation rests on fermentation yield economics and REACH registration compliance burdens rather than brand positioning. Cost compression in standard feed-grade tiers is intensifying because Shandong-based producers are segregating production lines to capture domestic Chinese volume at lower specification thresholds. Pharmaceutical buyers show the least price sensitivity due to DMF filing requirements and EMA GMP certification barriers, while Southeast Asian compound feed facilities face acute margin pressure from carbohydrate substrate volatility.
Supply Chain Analysis
Metabolic engineering talent scarcity in Henan and Shandong provinces is constraining strain optimization capacity expansion just as EU F-Gas Regulation cooling retrofits absorb technical labor pools in Bavarian chemical clusters. Supply concentrates in China, Germany, and the United States, with Corynebacterium glutamicum engineering capabilities and precursor chemical integration determining competitive positioning. Raw material dependencies draw from corn belt carbohydrate substrates in Illinois and Iowa, molasses feedstock in Brazil, and purified fermentation media components from Japanese biotechnology licensors. Single-source vulnerability sits with high-performance strain IP concentration among limited biotechnology licensors. Distribution runs through direct supplier relationships displacing distributor intermediation in vertically coordinated poultry supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in European fermentation assets create cost-positioning advantages for Shandong-based producers serving export channels under SAMR documentation protocols.
For Market Incumbents: Deploy backward integration into precursor chemicals to sustain margin capture against carbohydrate substrate volatility threatening non-integrated producers. Anchor position through captive supply of fermentation media components and strain optimization licensing agreements that filter emerging entrant participation. Fortify pharmaceutical-grade positioning by accelerating EMA GMP certification timelines ahead of asynchronous FDA feed additive approval schedules. For New Entrants and Emerging Players: The 99%-to-98% purity price-point gap in Indian aquaculture nutrition creates white-space penetration opportunity through BIS certification pathways and DGFT import frameworks. Target liquid formulation channels in North American integrated feed mill operations where automated dosing protocols bypass established powder handling infrastructure. Pursue precision fermentation convergence with synthetic biology toolsets to compress novel strain development timelines against incumbent metabolic engineering talent pools. For Investors and Strategic Acquirers: Chemical conglomerates with existing fermentation infrastructure are the most active acquirer in this space, seeking biotechnology platforms to complete backward integration into amino acid manufacturing. Long-term viability over the coming decade hinges on carbon intensity metrics hardening into primary procurement criteria across lifecycle assessment-integrated buyer protocols. Monitor fermentation yield improvement trajectories and SAMR export documentation standardization as inflection indicators for margin compression or expansion in premium-grade tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Shandong-Henan Cluster | Captures economies of scale in feed-grade amino acid production serving Southeast Asian swine operations. |
| Backward Integration into Precursor Chemicals | Evonik Industries AG leverages captive supply to defend margin position against carbohydrate substrate volatility. |
| Long-term Supply Agreement with Integrated Feed Mills | Displaces spot-market purchasing in North American poultry supply chains automating threonine dosing protocols. |
| Green Manufacturing Transition | EU F-Gas Regulation phase-down mandates accelerate energy-efficient biomanufacturing infrastructure deployment. |
| Joint Venture for Strain Optimization Licensing | Ajinomoto Co., Inc. anchors biotechnology leadership through Corynebacterium glutamicum engineering capabilities. |
Research Methodology
Multiple input streams — fermentation plant managers, procurement leads at integrated poultry operations, distribution channel partners, and technical R&D directors — were reconciled against customs and trade data, MIIT biomanufacturing standard filings, SEC 10-K disclosures, and feed industry association reports. Bottom-up capacity assessments across Shandong and Henan fermentation clusters were triangulated with top-down demand modeling from livestock nutrition optimization protocols.
Historical production volume trajectories were cross-referenced against expert panel inputs from strain optimization specialists and regulatory affairs leads to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry criticality, formulation handling requirements, and regional regulatory cluster stringency. CAGRs were derived from fermentation yield improvement curves and carbon intensity metric integration timelines into supplier qualification protocols.
Caveats apply where carbohydrate substrate price volatility, asynchronous multi-jurisdiction certification timelines, or metabolic engineering talent scarcity could materially shift the outlook. Material deviation in EU F-Gas Regulation implementation pace or SAMR export documentation standardization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Imidazole Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Global Potassium Citrate Market